
 Asia-Pacific Cereal Bar Market | 2026-2036
Asia-Pacific Cereal Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cereal Bar Market Outlook
Convenience store distribution is fragmenting across Southeast Asian corridors as local chains and multinational operators compete for shelf space. PepsiCo leverages its beverage-retail integration to secure prime placement in Indonesian and Thai outlets. Kellogg Company anchors its portfolio through manufacturing scale in the region. Naturell India Pvt. Ltd. specializes in ayurveda-infused formulations that differentiate against Western imports.
Asia-Pacific cereal bars comprise baked or cold-pressed grain matrices bound with syrups, proteins, or fruit concentrates, typically delivering between 150 and 300 calories per serving with shelf lives extending 12 to 18 months under moisture-barrier packaging. Protein Bars command premium positioning among gym-centric consumers while Granola Bars sustain volume leadership through breakfast substitution. Single-Serve Packs capture impulse occasions in transit retail formats. Gluten-Free ingredient formulations attract coeliac-diagnosed populations and wellness-adjacent buyers across Australian and Japanese markets.
FSSAI in India enforces label disclosure rules that force reformulation of imported products. China's SAMR and GB standards govern additive thresholds and nutritional claims. Australia's FSANZ coordinates with New Zealand on cross-Tasman food standards that streamline market access. Stakeholders must track evolving protein-content verification protocols and packaging waste directives before committing to capacity expansion or brand localization strategies.
Market Dynamics
India's FSSAI clean-label mandates and China's GB food safety standards are forcing multinational brands to reformulate ingredient matrices and relocate production assets to maintain market access across the region's largest consumer bases.
Growth Catalysts
- Urban Professional Demand:Fitness enthusiasts in Shanghai, Mumbai, and Sydney transit corridors drive single-serve pack consumption during compressed morning routines.
- GB Standards Compliance:China's SAMR enforcement of additive thresholds accelerates domestic manufacturing investment by brands seeking to avoid import label rejections.
- Ayurveda Infusion:Traditional medicine ingredient integration attracts wellness-adjacent buyers seeking differentiation from Western formulations.
Market Restraints
- Palm Oil Price Volatility:Binding syrup and coating fat input costs fluctuate with Southeast Asian commodity harvest cycles, compressing margin predictability.
- Moisture-Barrier Packaging Concentration:Three Japanese and Korean film suppliers control regional high-barrier substrate capacity, creating procurement bottlenecks during demand spikes.
- Fresh Food Substitution:Traditional breakfast cultures in Vietnam and Philippines favor hot rice and noodle dishes, limiting habitual adoption among older demographics.
Strategic Opportunities
- Vietnam Convenience Retail:Underdeveloped modern trade infrastructure in secondary cities creates first-mover shelf space for brands establishing local distribution partnerships.
- PLI Scheme Alignment:India's production-linked incentive framework for food processing subsidizes capital equipment for domestic manufacturing scale-up.
- E-Commerce Subscription Models:Direct-to-consumer replenishment platforms bypass fragmented traditional retail in Indonesian archipelago logistics.
Industry Challenges
- Protein Content Verification:Laboratory testing capacity scarcity across regional third-party facilities delays product launch timelines for premium-positioned bars.
- Cross-Border Formulation Harmonization:Divergent maximum residue limits between Australia's FSANZ and New Zealand's equivalent standards force SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cereal Bar Market |
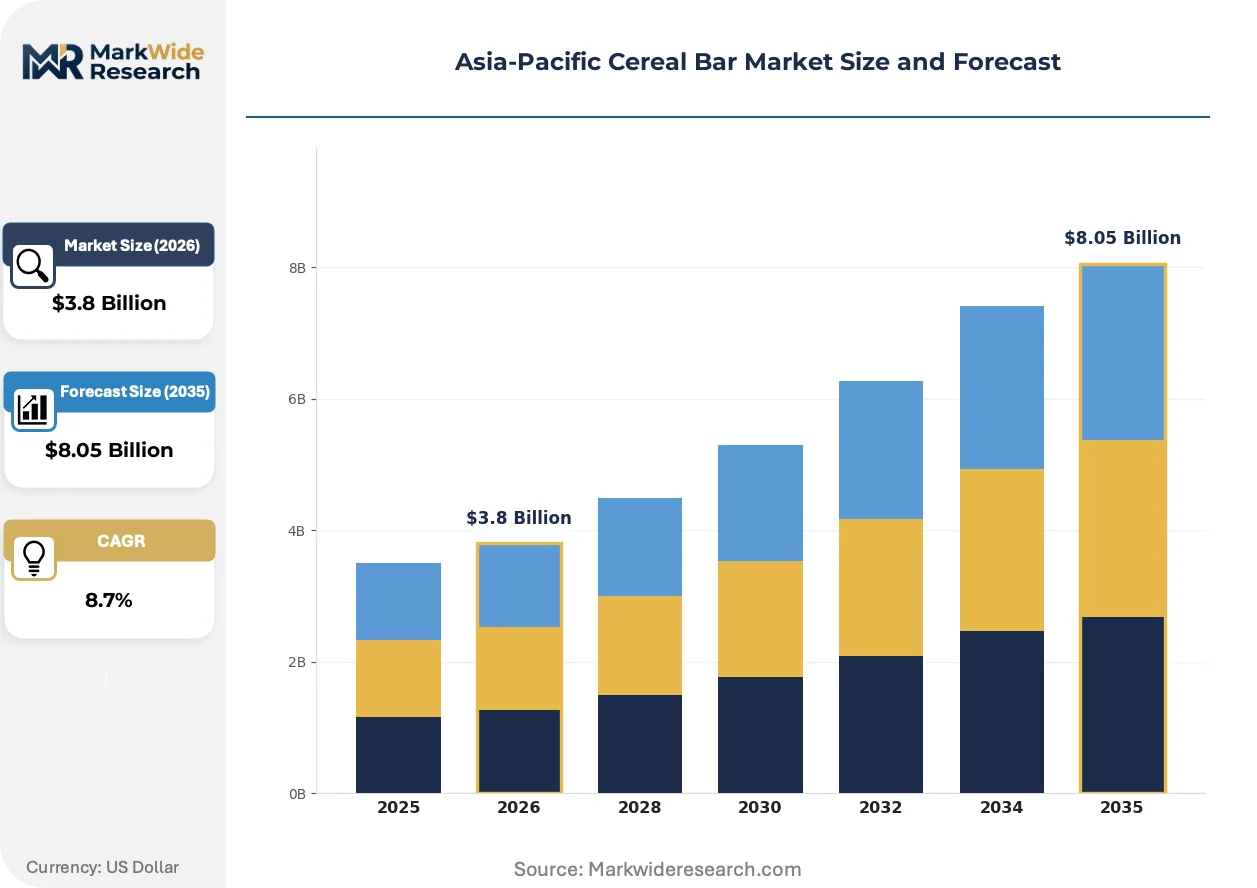
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Bars, Granola Bars, Protein Bars, Organic Bars Ingredient Type: Gluten-Free, High-Protein, Low-Sugar, Whole Grain Packaging Type: Boxes, Pouches, Single-Serve Packs, Bulk Packs Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Shops |
| Companies Covered | PepsiCo Inc, Abbott Laboratories, Kellogg Company, NuGo Nutrition, Clif Bar & Company, Yogabars, Naturell India Pvt. Ltd., General Mills Inc., Nestle, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cereal Bar Market Strategic Shifts
Cold-pressed processing and ayurveda ingredient integration are reshaping competitive positioning in the Asia-Pacific cereal bar landscape, while regulatory disclosure requirements accelerate transparency investments.
Extrusion technology is hybridizing with traditional baking methods to preserve heat-sensitive bioactive compounds in functional ingredient formulations. Gym-centric consumers in Seoul and Melbourne premium channels adopt these hybrid-processed bars at triple the rate of conventional baked alternatives. The technology is compressing shelf-life differentials between natural-positioned and preservative-stabilized products.
China's GB 28050 nutritional labeling standards now mandate front-of-pack disclosure for sugar and sodium content thresholds. Reformulation costs for imported brands have risen substantially as SAMR inspection protocols tighten at port-of-entry facilities. Protein bar SKUs targeting China's tier-one cities face the steepest compliance timelines due to complex amino acid declaration requirements.
Transit retail procurement patterns are fragmenting as convenience store operators unbundle category management from beverage-supplier捆绑 agreements. Indonesian and Thai chains now negotiate cereal bar placement independently, displacing legacy integrated distribution structures. This channel restructuring is most visible in Jakarta's commuter corridor outlets where local operators command direct supplier relationships.
Asia-Pacific Cereal Bar Market Segmentation
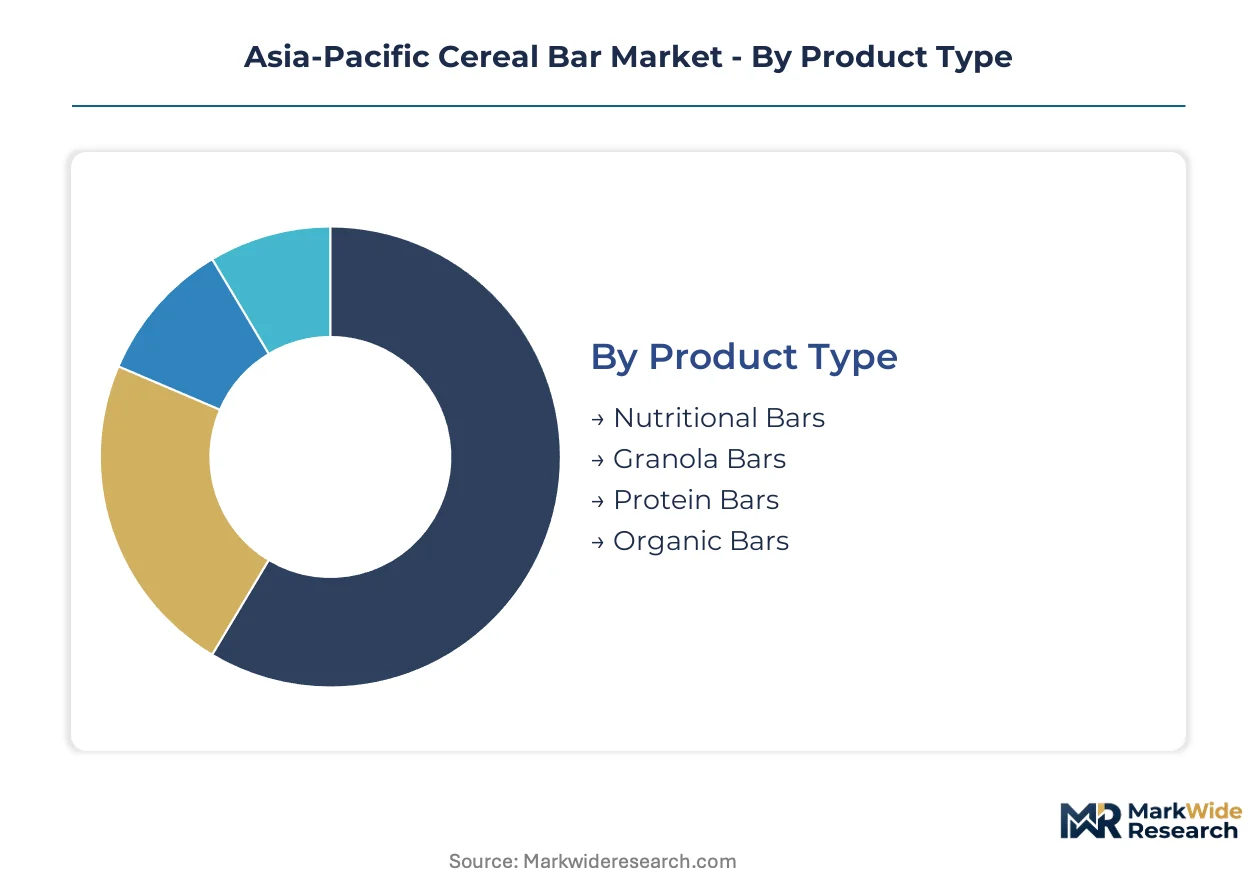
Product architecture in the Asia-Pacific cereal bar market fragments across functional positioning, dietary compliance, and retail occasion. Each segmentation layer demands distinct formulation expertise and channel-specific merchandising strategies.
Product Type:
After-sales engagement intensity varies sharply across product categories, with protein-focused lines requiring nutritional consultation support while breakfast substitutes rely on shelf-life guarantees.
- Protein Bars:Amino acid-fortified matrices delivering 15-25g protein per serving through whey, casein, or plant isolates. Demand clusters in Seoul and Melbourne gym corridors where consumers verify protein claims against GB standards and FSSAI disclosure mandates.
- Granola Bars:Baked oat and honey clusters bound with vegetable oils, positioned for breakfast substitution. Volume concentrates in China's tier-one cities and India's metropolitan corridors where compressed morning routines displace traditional hot meals.
- Nutritional Bars:Vitamin and mineral-enriched formulations targeting micronutrient supplementation.
- Organic Bars:Certified ingredient sourcing with restricted synthetic additive profiles.
Granola Bars hold the largest share; momentum sits with Protein Bars.
Ingredient Type:
Cost tier stratification separates premium-positioned functional ingredients from commodity grain bases, with certification premiums widening price spreads across Australian and Japanese retail shelves.
- High-Protein:Concentrated protein isolates integrated at 20%+ by weight, requiring moisture management to prevent texture degradation. Adoption accelerates in Shanghai and Sydney fitness channels where consumers cross-reference amino acid profiles against laboratory verification protocols.
- Gluten-Free:Oat, rice, or pseudocereal matrices excluding wheat, barley, and rye proteins. Demand concentrates among diagnosed coeliac populations in Australia and wellness-adjacent buyers across Japanese premium retail.
- Low-Sugar:Polyol and stevia-sweetened formulations reducing glycemic load.
- Whole Grain:Intact bran and germ preservation through minimal processing.
High-Protein commands premium shelf positioning; Gluten-Free is climbing the fastest.
Packaging Type:
Volume throughput determines format economics, with single-serve units optimizing impulse velocity while bulk configurations reduce per-unit logistics burden for e-commerce subscription models.
- Single-Serve Packs:Individual flow-wrapped units with moisture-barrier substrates extending shelf life to 18 months. Penetration peaks in Jakarta and Bangkok transit retail where commuter traffic drives unplanned purchase frequency.
- Pouches:Flexible film constructions enabling vertical display and reduced shipping cube. Adoption concentrates in Indonesian archipelago logistics where e-commerce platforms bypass fragmented traditional distribution.
- Boxes:Rigid paperboard multipacks for pantry stock-up occasions.
- Bulk Packs:Large-format configurations for institutional and food-service procurement.
Single-Serve Packs dominate velocity metrics; Pouches are expanding most quickly.
Distribution Channel:
Customer type fragmentation splits procurement between planned pantry replenishment and impulse transit consumption, with channel-specific ranging dictulating pack size and flavor architecture.
- Convenience Stores:High-frequency, small-format outlets in urban transit corridors. Shelf space competition intensifies in Indonesian and Thai markets as local chains displace legacy beverage-supplier捆绑 agreements.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators. Penetration accelerates across Vietnamese secondary cities where modern trade infrastructure remains underdeveloped.
- Supermarkets:Planned purchase environments with extended variety and promotional depth.
- Health Food Shops:Curated specialty retail with certified organic and functional positioning.
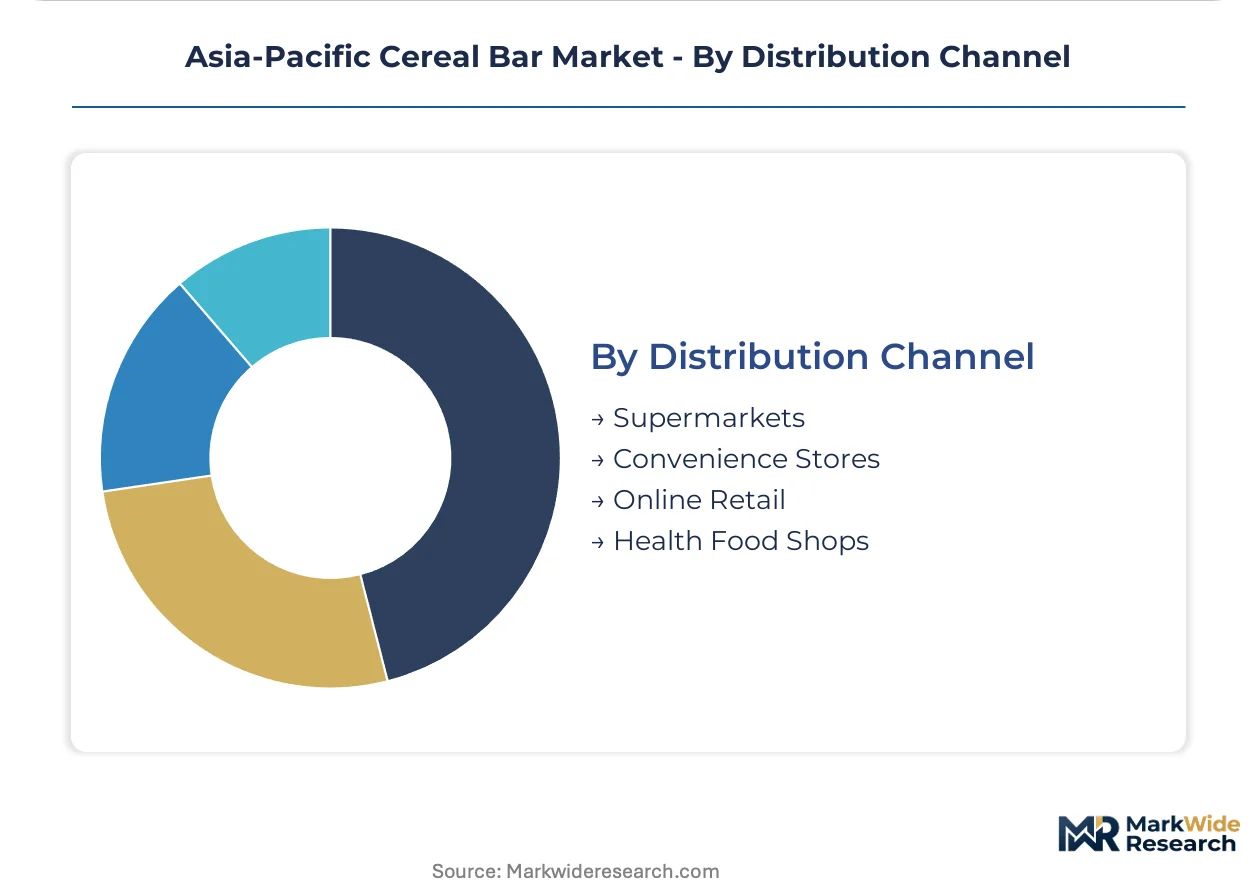
Supermarkets retain volume leadership; Convenience Stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing premiums in tier-one cities that outpace Southeast Asian secondary markets by substantial margins. India's metropolitan corridors sustain volume throughput through domestic manufacturing scale. Australia's certification-driven retail channels extract value through compliance premiums that Indonesian transit retail cannot replicate.
China
Fitness enthusiasts in Shanghai and Beijing drive protein bar adoption through gym-centric verification of amino acid profiles. SAMR enforcement of GB 28050 nutritional labeling standards forces reformulation of imported SKUs at port-of-entry facilities. Manufacturing investment clusters in the Yangtze River Delta as brands relocate production to bypass import rejection timelines.
India
Urban professionals in Mumbai and Delhi-NCR substitute traditional breakfasts with single-serve granola packs during compressed morning commutes. FSSAI clean-label mandates compel disclosure of additive matrices and protein sourcing origins. The Maharashtra-Gujarat industrial corridor anchors domestic capacity expansion under PLI scheme subsidies for food processing equipment.
Australia
Coeliac-diagnosed populations and wellness-adjacent buyers in Sydney and Melbourne sustain gluten-free premium positioning. FSANZ coordination with New Zealand on cross-Tasman standards streamlines formulation compliance across both markets. Specialty retail channels in New South Wales and Victoria curate certified organic lines that command shelf-space premiums unavailable in mass grocery.
Japan
Moisture-barrier packaging procurement concentrates among three domestic film suppliers serving Tokyo-Osaka retail corridors. METI guidelines on food contact materials govern substrate specifications for extended shelf-life claims. Convenience store operators in the Kanto region unbundle category management from beverage-supplier捆绑 agreements to negotiate direct cereal bar placement.
Vietnam
Underdeveloped modern trade infrastructure in Ho Chi Minh City and Hanoi secondary districts creates first-mover shelf space for distribution partnerships. Local breakfast cultures favoring hot rice and noodle dishes limit habitual adoption among older demographics. E-commerce subscription platforms bypass fragmented traditional retail to reach archipelago logistics constraints.
Asia-Pacific Cereal Bar Market Competitive Environment
Multinational packaged food conglomerates and domestic ayurveda specialists split the market across premium functional and traditional wellness positioning. The structure consolidates around manufacturing scale advantages in protein bar matrices and formulation differentiation in granola alternatives. Three archetypes dominate: beverage-retail integrated giants, cereal manufacturing scale players, and ayurveda-infused domestic specialists. Competitive moves concentrate on production relocation to satisfy FSSAI and GB standards compliance, plus direct distribution partnerships with unbundled convenience store operators.
Within the multinational tier, PepsiCo Inc and Kellogg Company exemplify divergent integration strategies. PepsiCo leverages beverage-retail channel integration to secure prime placement in Indonesian and Thai transit outlets. Kellogg Company anchors regional presence through manufacturing scale economies in core cereal bar matrices. Among domestic specialists, Naturell India Pvt. Ltd. occupies a position representing ayurveda-infused formulation differentiation against Western import positioning.
| Leading Market Players |
|---|
| PepsiCo Inc |
| Abbott Laboratories |
| Kellogg Company |
| NuGo Nutrition |
| Clif Bar & Company |
| Yogabars |
| Naturell India Pvt. Ltd. |
| General Mills Inc. |
| Nestle |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor's containerized logistics costs compress margin buffers for brands importing protein isolates into Shanghai, concentrating pricing power among domestic manufacturers that bypass port-of-entry inspection delays while forcing multinational importers to absorb premium positioning costs or localize production assets.
Pricing Analysis
Customization-premium spreads separate ayurveda-infused formulations from commodity granola matrices, with three-tier pricing structure across premium, standard, and economy levels anchored by protein-content verification tiers, FSSAI disclosure compliance grades, and moisture-barrier packaging substrate quality. Price differentiation rests on certification investment and gym-channel brand equity, with cost compression in economy tiers intensifying because palm oil syrup input volatility feeds through binding ingredient costs. Urban professionals in transit retail show lowest price sensitivity; budget-conscious pantry stock-up buyers in Vietnamese secondary markets exhibit highest elasticity.
Supply Chain Analysis
Upstream feedstock procurement for high-protein isolates draws from New Zealand whey processing, Australian oat milling, and Indian chickpea concentrate extraction, with binding syrup formulations sourcing from Thai tapioca and Indonesian palm oil refineries. Raw material dependencies center on moisture-barrier film substrates from Japanese and Korean suppliers, ayurveda botanical extracts from Maharashtra-Gujarat cultivation belts, and amino acid premixes from Chinese fermentation facilities. Supply chain risk concentrates in single-source vulnerability for high-barrier packaging films. Distribution runs through unbundled convenience store direct partnerships and e-commerce subscription platforms bypassing fragmented traditional wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FSSAI, GB standards, and FSANZ regimes fragments competitive space, with clean-label mandates and protein verification protocols creating specialist niches that reward formulation expertise over manufacturing scale alone.
For Market Incumbents: Insulate market position by deepening backward integration into domestic Indian and Chinese manufacturing to preempt import rejection timelines under tightening SAMR and FSSAI protocols, while securing captive supply of high-barrier packaging substrates through long-term offtake agreements with Japanese film suppliers to mitigate procurement bottlenecks during demand spikes. For New Entrants and Emerging Players: Vietnamese secondary cities and Indonesian archipelago e-commerce channels represent the most penetrable white-space targets, with underdeveloped modern trade infrastructure creating first-mover shelf access and direct-to-consumer subscription models bypassing fragmented logistics constraints; prioritize ayurveda-infused differentiation to capture wellness-adjacent buyers seeking alternatives to Western formulations. For Investors and Strategic Acquirers: Domestic specialists with certified organic sourcing networks and established FSSAI compliance track records represent the priority acquisition archetype for long-term viability within a 5-10 year regulatory tightening horizon; monitor protein-content laboratory verification capacity expansion as the inflection signal indicating premium tier supply constraints easing.| Strategic Initiative | Industry Significance |
|---|---|
| Production Relocation to India and China | Local manufacturing under PLI subsidies and GB standards compliance accelerates market access timelines. |
| Ayurveda Ingredient Integration | Traditional medicine differentiation captures wellness-adjacent buyers in Mumbai and Delhi-NCR corridors. |
| Direct Convenience Store Partnerships | Unbundled category management in Jakarta and Bangkok secures prime transit retail shelf positioning. |
| E-Commerce Subscription Launch | Direct-to-consumer replenishment bypasses fragmented Indonesian archipelago distribution infrastructure. |
| Moisture-Barrier Packaging Investment | Captive supply agreements with Japanese film suppliers mitigate procurement bottlenecks during demand spikes. |
Study Parameters
A spread of perspectives from brand managers at multinational and domestic cereal bar manufacturers, category buyers at Indonesian and Thai convenience store chains, FSSAI regulatory affairs consultants, and supply planners at moisture-barrier packaging suppliers converged on the working assumptions underlying demand projections. Primary interview insights combined with secondary validation from customs records, Nielsen retail audit data, SAMR GB standards filings, and FSSAI disclosure mandate documentation. Bottom-up volume builds across product type, ingredient certification tier, packaging format, and distribution channel segments triangulated against top-down macroeconomic consumption indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning protein bar versus granola bar matrices, high-protein versus gluten-free versus low-sugar ingredient positioning, single-serve versus pouch versus box packaging configurations, and convenience store versus online retail versus supermarket channel splits. CAGRs derived from historical trajectory analysis adjusted for regulatory compliance cost pass-through and urban professional consumption pattern shifts. Forecast inputs incorporated PLI scheme subsidy impact on domestic manufacturing economics and e-commerce penetration acceleration across Vietnamese and Indonesian logistics constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated beverage-retail conglomerates or ayurveda-specialist domestic challengers would shift outcomes beyond modeled ranges. Quarterly review of protein-content laboratory verification capacity utilization, FSSAI enforcement intensity on additive disclosure, and convenience store unbundling progression in Southeast Asian transit corridors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
South East Asia Snack Bar Market
Snacks
Middle East Snack Bar Market
Snacks
Global Snack Food Market
Snacks
Low Fat Protein Snacks Market
Snacks
Snacks Market
Snacks
Potato Chips Market
Snacks
Brazil Snack Bar Market
Snacks
Europe Energy Bar Market
Snacks
Qatar Potato Chips Market
Snacks
Vegan Protein Balls Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Healthy Snacks Market
Snacks
Indonesia Snack Bar Market
Snacks
Global Vegetable Chips Market
Snacks
Germany Energy Bar Market