
 Gluten-Free Desserts and Ice Creams Market | 2026-2036
Gluten-Free Desserts and Ice Creams Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Desserts and Ice Creams Market Foresight
EU Regulation 1169/2011 on food information to consumers is consolidating manufacturer investment in certified gluten-free production lines. General Mills Inc. leverages its supply chain scale to secure dedicated oat milling facilities for gluten-free baked goods. Nestlé SA anchors its frozen dessert portfolio with reformulated ice cream bases that eliminate cross-contamination risks. The Hain Celestial Group Inc. specializes in organic-certified gluten-free confectionery, targeting health-conscious shoppers through premium channel positioning.
Gluten-free desserts and ice creams comprise sweet food products formulated without wheat, barley, rye, or their crossbred varieties, typically substituting rice flour, almond meal, or tapioca starch to achieve comparable texture and mouthfeel while maintaining gluten levels below regulatory thresholds. Frozen desserts command the largest current volume share, driven by Unilever's extensive dairy-free and gluten-free ice cream distribution, while gelato segments attract artisanal producers seeking margin differentiation through premium ingredient sourcing. Online retail channels represent the fastest-growing distribution pathway, as direct-to-consumer subscription models reduce shelf-space competition with conventional products.
FDA gluten-free labeling standards and EU Commission Regulation 828/2014 define maximum 20 ppm gluten thresholds, compelling manufacturers to implement segregated production protocols and third-party certification audits. Health Canada and FSANZ maintain parallel strictures, creating a complex compliance landscape for exporters serving multiple jurisdictions. Stakeholders must monitor evolving allergen labeling mandates and traceability requirements to sustain market access across divergent national regulatory frameworks.
Market Dynamics
FDA gluten-free labeling enforcement and EU Commission Regulation 828/2014 are compressing manufacturer margins while simultaneously consolidating supply chains toward certified production facilities. The regulatory ratchet is forcing capital reallocation from marketing to traceability infrastructure.
Growth Catalysts
- EU Regulation 1169/2011:Mandatory allergen disclosure requirements accelerate retailer demand for certified gluten-free SKUs. Major supermarket chains now mandate third-party certification for shelf placement.
- Celiac disease diagnosis protocols:Expanded serological screening in pediatric populations creates durable patient cohorts requiring lifetime dietary management. Gastroenterology clinics increasingly prescribe strict gluten elimination.
- Dedicated oat milling infrastructure:Supply chain investments in segregated grain handling eliminate cross-contamination risks that previously limited category expansion. Foodservice operators now specify certified oat bases for dessert formulations.
Market Restraints
- Almond meal price volatility:California drought cycles and water allocation disputes create input cost instability for premium gluten-free formulations. Manufacturers face margin compression during supply shocks.
- Segregated production line capex:Dedicated gluten-free facilities require 40-60% higher capital intensity than shared lines. Mid-tier producers lack balance sheet capacity for full certification.
- Tapioca starch supply concentration:Thai and Vietnamese cassava processors control 70% of global food-grade starch exports. Geopolitical disruptions in Southeast Asia propagate through dessert ingredient supply chains.
Strategic Opportunities
- Direct-to-consumer subscription channels:Monthly dessert box models bypass retail slotting fees and capture full margin. Digital-native brands leverage Instagram-native creative to build affinity.
- Clean-label convergence with organic certification:Dual-certified products command shelf price premiums in Whole Foods and specialty retail. Consumer willingness-to-pay escalates for multi-attribute claims.
- Frozen dessert cross-merchandising:Gluten-free ice cream placement adjacent to conventional dairy alternatives expands basket penetration. Retailers recognize category halo effects.
Industry Challenges
- ELISA testing technician scarcity:Accredited laboratory capacity for gluten ppm verification lags demand growth. Certification timelines extend from weeks to months.
- Legacy ERP traceability gaps:Batch-level ingredient tracking requires software upgrades incompatible with decades-old manufacturing execution systems. Integration costs deter smaller facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Desserts and Ice Creams Market |
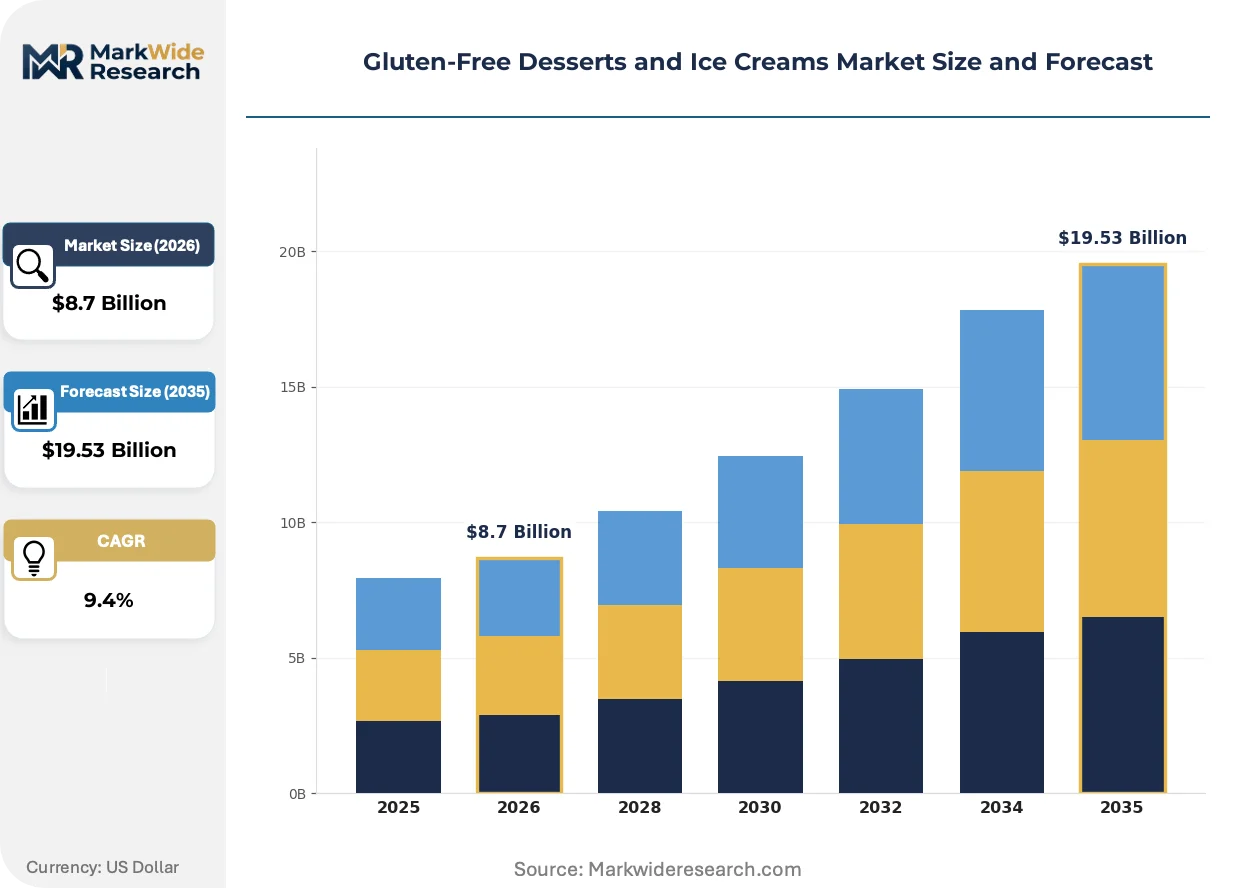
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baked Goods, Frozen Desserts, Confectionery, Gelato Flavor Profile: Chocolate, Vanilla, Strawberry, Matcha Packaging Type: Cartons, Pouches, Cups, Jars Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | General Mills Inc., Kellogg's Company, Unilever, Hero Group AG, The Kraft Heinz Company, Nestlé SA, Conagra Brands Inc., Boulder Brands, The Hain Celestial Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Desserts and Ice Creams Market Shifts & Advancements
Novel protein stabilization technologies are reformulating frozen dessert mouthfeel without gluten-derived structure. These advances compress the sensory gap between conventional and gluten-free products.
Hydrocolloid blends incorporating tara gum and locust bean gum are expanding into premium gelato formulations. Artisanal producers in Brooklyn and Copenhagen adopt these systems to replicate traditional texture without wheat-based stabilizers. The technology is expanding into mass-market private label programs as cost curves decline.
EU F-Gas Regulation phase-down mandates are accelerating refrigeration infrastructure replacement across frozen dessert distribution. Cold chain operators face stranded asset risk in hydrofluorocarbon-dependent facilities. German and Italian manufacturers lead retrofit adoption to maintain supermarket compliance deadlines.
Subscription-based replenishment models are displacing impulse freezer-aisle purchases among diagnosed celiac households. Direct channels offer flavor customization unavailable in conventional retail. This behavioral shift concentrates most visibly in coastal US metropolitan markets with high health-conscious consumer density.
Gluten-Free Desserts and Ice Creams Market Segmentation
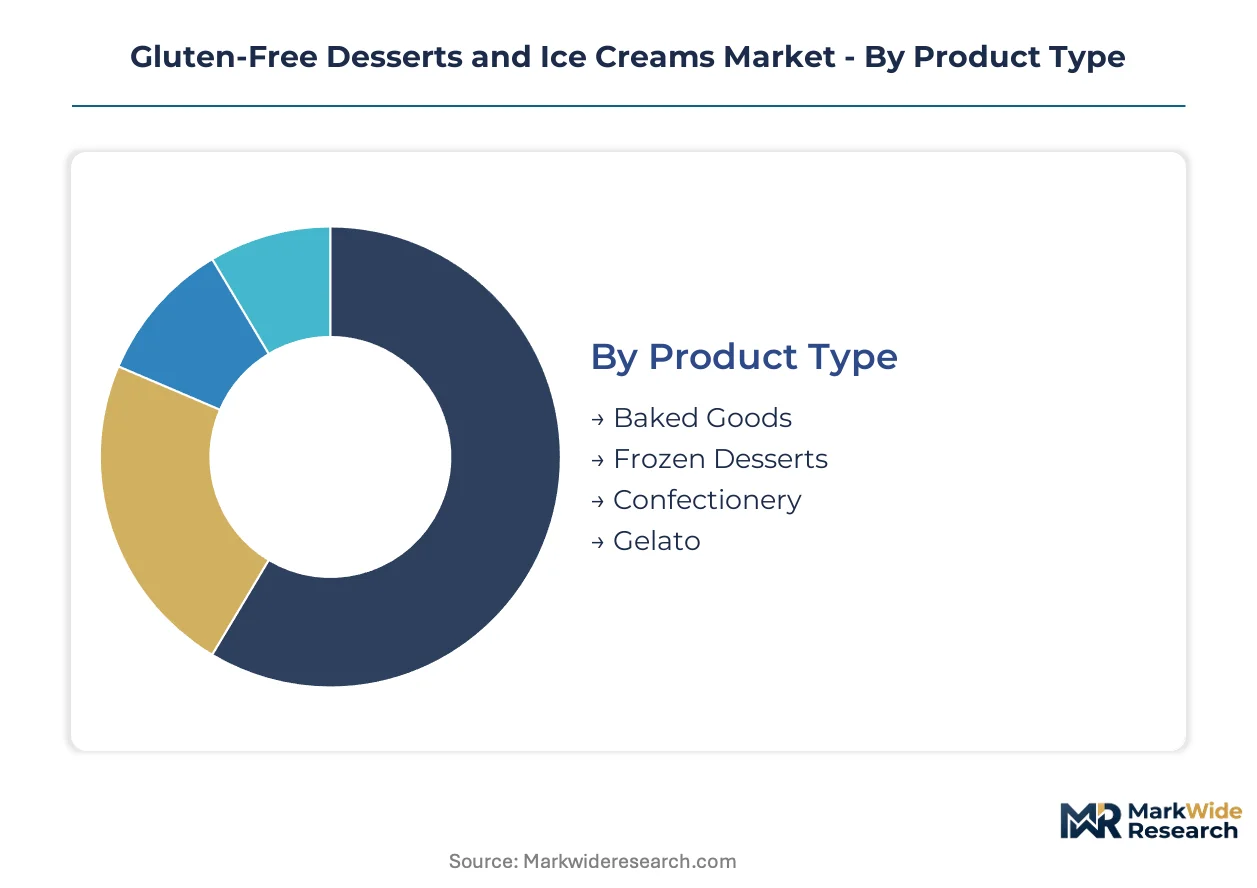
Segmentation in gluten-free desserts and ice creams determines which manufacturing protocols apply, which certifications command shelf placement, and which distribution economics govern profitability. Each dimension carries distinct regulatory burdens and margin structures that reshape competitive positioning across the value chain.
Product Type:
FDA and EU gluten-free labeling thresholds apply variably across production formats, with frozen lines requiring additional cold-chain verification and baked formats demanding stricter cross-contamination controls.
- Baked Goods:Formulations rely on rice flour, almond meal, and tapioca starch to replicate wheat-based structure. US celiac households drive concentrated demand through specialty retail channels where third-party certification is mandatory for shelf placement.
- Frozen Desserts:Ice cream bases eliminate gluten-derived stabilizers through hydrocolloid systems incorporating tara gum and locust bean gum. Unilever's distribution scale anchors volume concentration in conventional retail freezer sections.
- Confectionery:The Hain Celestial Group targets organic-certified gluten-free confectionery through premium channel positioning. Health-conscious shoppers in coastal US metropolitan markets sustain pricing power.
- Gelato:Artisanal producers in Brooklyn and Copenhagen adopt advanced hydrocolloid blends to replicate traditional texture without wheat-based stabilizers. Premium ingredient sourcing supports margin differentiation.
Leading the category by volume: Frozen Desserts. Growing fastest: Gelato.
Flavor Profile:
Flavor selection determines ingredient sourcing geography and associated supply chain risk, with cocoa and matcha procurement facing distinct climate and trade policy exposures.
- Chocolate:Cocoa butter and cacao powder formulations require rigorous gluten-free certification due to shared processing equipment with malt-containing confectionery. West African supply concentration creates price volatility exposure.
- Vanilla:Madagascar and Tahitian vanilla extracts command premium positioning in clean-label portfolios. Dual-certified organic-gluten-free SKUs capture shelf price premiums at Whole Foods.
- Strawberry:Fruit-based formulations leverage established allergen-free supply chains with lower certification complexity. California strawberry processors dominate North American ingredient sourcing.
- Matcha:Japanese-origin matcha powder carries premium positioning in health-conscious segments. Tokyo and Kyoto supplier relationships require dedicated import compliance protocols.
Highest margin concentration: Chocolate and Matcha. Steepest expansion trajectory: Matcha.
Packaging Type:
Packaging format dictates shelf-life extension capabilities, cold-chain requirements, and retail slotting economics across frozen and ambient distribution channels.
- Cartons:Frozen dessert cartons dominate supermarket freezer sections with established case-ready logistics. EU F-Gas Regulation phase-down mandates accelerate refrigeration infrastructure replacement for carton-dependent distribution.
- Pouches:Flexible packaging reduces shipping cube and supports direct-to-consumer subscription models. Digital-native brands leverage Instagram-native creative to build affinity through pouch-format novelty.
- Cups:Single-serve portions command foodservice placement in cafeterias and healthcare facilities. Portion control aligns with pediatric celiac disease management protocols.
- Jars:Premium dessert sauces and layered confections utilize glass packaging for shelf differentiation. Specialty shops favor jar formats for artisanal visual merchandising.
Fastest-growing format: Pouches. Dominant by volume: Cartons.
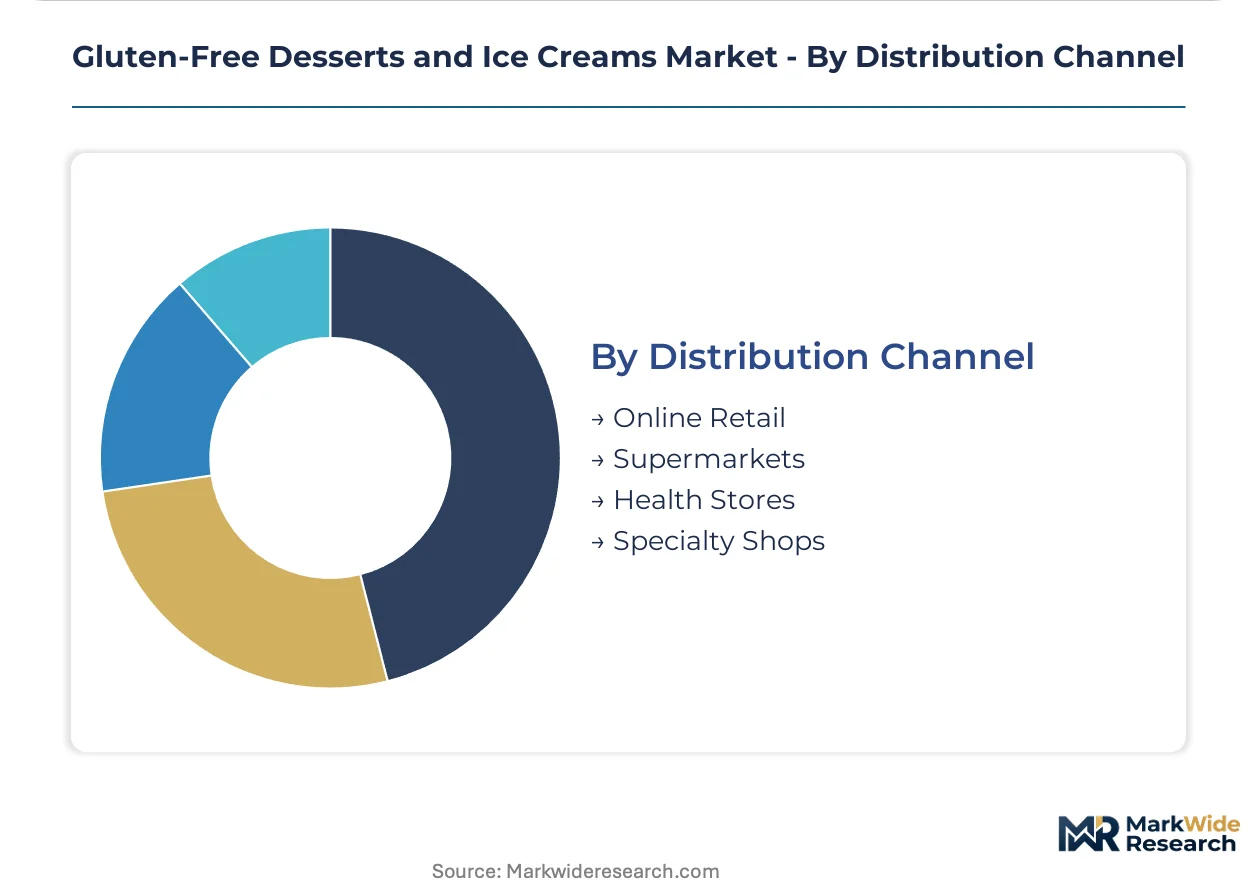
Distribution Channel:
Channel selection determines margin capture, certification requirements, and customer data access, with direct models bypassing retail slotting fees entirely.
- Online Retail:Monthly dessert box subscription models capture full margin while reducing shelf-space competition with conventional products. Direct channels offer flavor customization unavailable in conventional retail.
- Supermarkets:Major chains mandate third-party gluten-free certification for shelf placement under EU Regulation 1169/2011 allergen disclosure requirements. Cross-merchandising adjacent to dairy alternatives expands basket penetration.
- Health Stores:Whole Foods and specialty retail reward dual-certified organic-gluten-free products with premium positioning. Consumer willingness-to-pay escalates for multi-attribute claims in this channel.
- Specialty Shops:Artisanal gelato producers and boutique confectioners target diagnosed celiac households through personalized service. Brooklyn and Copenhagen cluster density supports premium pricing.
Highest volume throughput: Supermarkets. Climbing the fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in North American and European processing hubs while consumption concentrates in urban centers with elevated celiac diagnosis rates and clean-label purchasing power. The divergence between manufacturing geography and demand density shapes cold-chain logistics investment and regulatory compliance strategy across exporter networks.
United States
FDA gluten-free labeling enforcement and expanded pediatric serological screening create durable patient cohorts requiring lifetime dietary management. The FDA's 20 ppm threshold mandates segregated production protocols that consolidate supply chains toward certified facilities. Brooklyn and Los Angeles anchor artisanal gelato and premium confectionery clusters where direct-to-consumer subscription models bypass conventional retail slotting economics.
Germany
EU F-Gas Regulation phase-down mandates accelerate refrigeration infrastructure replacement across frozen dessert distribution networks. EFSA gluten threshold standards and mandatory allergen disclosure under EU Regulation 1169/2011 compress manufacturer margins while consolidating retailer certification requirements. Berlin and Munich host specialized health food retail chains that mandate third-party gluten-free certification for shelf placement.
United Kingdom
NHS celiac disease screening protocols and free-from aisle expansion in Tesco and Sainsbury's drive category penetration. The Food Standards Agency enforces parallel gluten labeling strictures to EU Commission Regulation 828/2014, creating compliance continuity post-Brexit. London's premium food hall clusters support artisanal producers seeking margin differentiation through organic-gluten-free dual certification.
Italy
Deep gelato heritage and rising gluten sensitivity awareness converge to expand certified gluten-free frozen dessert production. Ministry of Health allergen regulations align with EU-wide 20 ppm thresholds while preserving artisanal production exemptions for small-batch producers. Bologna and Florence concentrate traditional gelato reformulation expertise adapted to hydrocolloid stabilization systems.
Canada
Health Canada gluten-free labeling standards and elevated celiac disease prevalence in prairie provinces sustain import demand from US manufacturers. CFIA enforcement of traceability requirements parallels FDA protocols, simplifying cross-border supply chain compliance. Toronto and Vancouver anchor specialty retail networks where dual-certified organic-gluten-free products command shelf price premiums.
Gluten-Free Desserts and Ice Creams Market Competitive Landscape
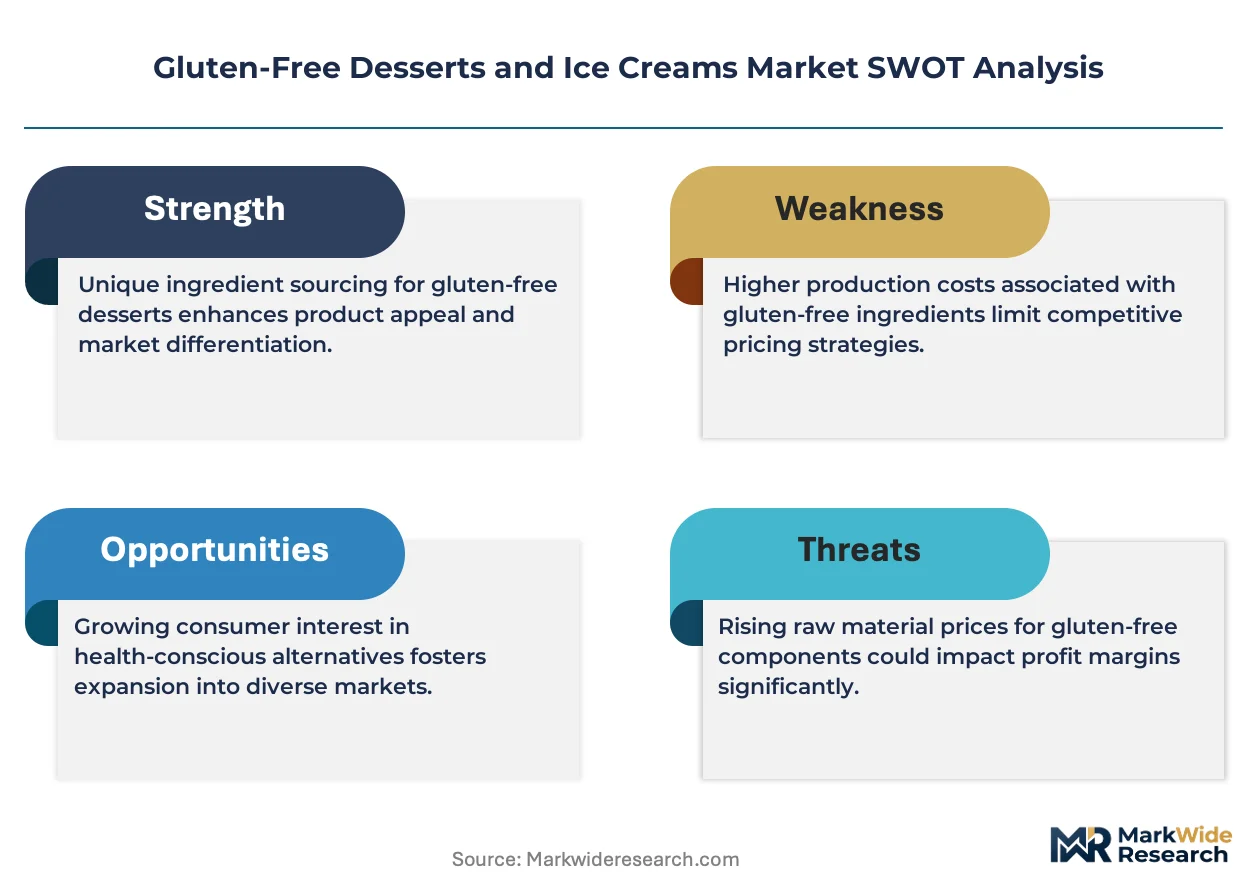
The competitive structure tilts toward diversified consumer goods conglomerates with dedicated allergen-free production infrastructure. Scale-advantaged players leverage supply chain integration to secure certified oat milling and segregated grain handling capabilities. Strategic archetypes include: (1) multinational CPG conglomerates with frozen dessert scale and reformulation expertise; (2) organic-specialist mid-caps with premium channel positioning; and (3) digital-native direct-to-consumer brands bypassing retail intermediation. Dominant competitive moves center on dedicated facility certification and direct channel expansion.
Among diversified food conglomerates, General Mills Inc. and Nestlé SA exemplify scale-driven archetypes with supply chain integration into certified gluten-free production infrastructure. Unilever anchors conventional retail freezer section penetration through extensive dairy-free and gluten-free distribution networks. The Hain Celestial Group Inc. occupies a specialist position targeting health-conscious shoppers through organic-certified confectionery and premium channel placement.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellogg's Company |
| Unilever |
| Hero Group AG |
| The Kraft Heinz Company |
| Nestlé SA |
| Conagra Brands Inc. |
| Boulder Brands |
| The Hain Celestial Group Inc. |
| Others |
Supply & Pricing Matrix
ELISA-certified laboratory technicians in the Minneapolis-St. Paul corridor command wage premiums that propagate through certification costs into tiered pricing spreads separating artisanal gelato from mass-market frozen desserts.
Pricing Analysis
Margin tightening in mid-tier baked goods reflects almond meal price volatility from California water allocation disputes. Three-tier pricing structure across premium, standard, and economy levels separates dual-certified organic-gluten-free SKUs from single-attribute claims and private-label alternatives. Price differentiation hinges on third-party certification tier and dedicated facility verification. Foodservice operators show highest price sensitivity due to volume procurement protocols, while diagnosed celiac households in coastal metropolitan markets exhibit lowest sensitivity for subscription-based replenishment.
Supply Chain Analysis
Certification gating through FDA and EU third-party audits concentrates supply relationships among Thai and Vietnamese cassava processors controlling food-grade tapioca starch exports. Raw material dependencies center on Madagascar vanilla extracts, West African cocoa butter, and Japanese matcha powder. Single-source vulnerability in Southeast Asian starch supply creates propagation risk through dessert ingredient networks. Distribution runs through refrigerated logistics networks with EU F-Gas Regulation compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrocolloid stabilization systems are displacing wheat-derived structure in frozen dessert formulations, creating technology-transition dynamics that reshape competitive positioning across formulation tiers.
For Market Incumbents: Lock in dedicated oat milling capacity through supply agreements with certified grain handlers to defend against cross-contamination liability exposure. Prioritize ERP traceability upgrades to capture batch-level ingredient tracking before certification timelines extend further. ELISA testing technician scarcity threatens certification velocity.
For New Entrants and Emerging Players: EU Regulation 1169/2011 in European markets opens a window for digital-native brands to bypass retail slotting fees through direct-to-consumer subscription channels. Target underpenetrated gelato segments in German and Italian metropolitan clusters where artisanal reformulation expertise concentrates. Leverage Instagram-native creative for pouch-format novelty positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with dual-certified organic-gluten-free specialists given clean-label convergence tailwinds in Whole Foods and specialty retail. Long-term viability favors facilities with segregated production lines and captive supply arrangements. Watch for pediatric celiac screening protocol expansions as inflection indicators for durable patient cohort formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Facility Certification | FDA and EU third-party audits secure shelf placement in major supermarket chains. |
| Direct-to-Consumer Channel Launch | Subscription models bypass retail slotting fees and capture full margin in coastal markets. |
| Backward Integration into Oat Supply | Certified grain handling eliminates cross-contamination risks in baked goods production. |
| Hydrocolloid Formulation Partnership | Tara gum and locust bean gum systems replicate traditional texture without wheat stabilizers. |
| Dual Certification Program | Organic-gluten-free claims command shelf price premiums in specialty retail channels. |
Research Methodology
Trade databases, regulatory filings, and retail audit data formed the secondary backbone, supplemented by primary interviews with dessert category buyers at supermarket chains, certification laboratory directors, supply chain managers at oat milling facilities, and formulation scientists at frozen dessert manufacturers. Bottom-up volume estimates triangulated against top-down spending analysis across consumer segments.
Historical trendline analysis anchored growth rate derivation across product type, flavor profile, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segment-level trajectory modeling incorporating celiac diagnosis rate projections, clean-label purchasing power indices, and cold-chain infrastructure expansion schedules.
The model assumes a particular technology adoption path for hydrocolloid stabilization systems; alternative pathways for protein-based structure replacement would alter the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and certification capacity expansion. A model refresh is warranted upon material change in FDA or EU gluten threshold standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Space Food Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Halal Products Market
Specialty Foods
Asia-Pacific Hummus Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Organic Skin Care Market