
 Protein Ice Cream Market | 2026-2036
Protein Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Ice Cream Market Analytics
The price-performance boundary between premium protein ice cream and commodity frozen desserts is hardening as ingredient costs diverge. Halo Top leverages its ultra-low-calorie formulation heritage to sustain shelf-space dominance in mainstream grocers. Perfect Day anchors its position through precision-fermented dairy proteins that differentiate the brand from conventional whey-based rivals. Wheyhey competes on clean-label credentials and occupies the British market with high-protein density formats.
Protein ice cream denotes a frozen dessert category engineered with elevated protein content, typically derived from whey, casein, or plant isolates, achieving nutritional profiles that deliver 10–20 grams of protein per serving while maintaining scoopable texture through modified overrun control. The category serves consumers seeking macro-nutrient optimization without sacrificing indulgence occasions. High-Protein formats lead absolute volume but Plant-Based variants register the fastest trajectory as lactose-intolerant and vegan dietary restriction consumers expand the addressable base. Specialty Stores capture outsized margin pools through curated assortments, while Online channels erode traditional supermarket dominance among fitness enthusiasts reordering subscription formats.
The FDA governs protein content claims and nutrition fact panel disclosures, compelling reformulation investments from manufacturers targeting the United States. EFSA and FSSAI establish parallel thresholds in Europe and India, fragmenting compliance architecture for brands with multi-country distribution. Stakeholders must monitor evolving precision-fermentation regulatory classifications, as novel dairy protein pathways risk reclassification under novel food frameworks that could accelerate or constrain market access depending on jurisdiction.
Market Dynamics
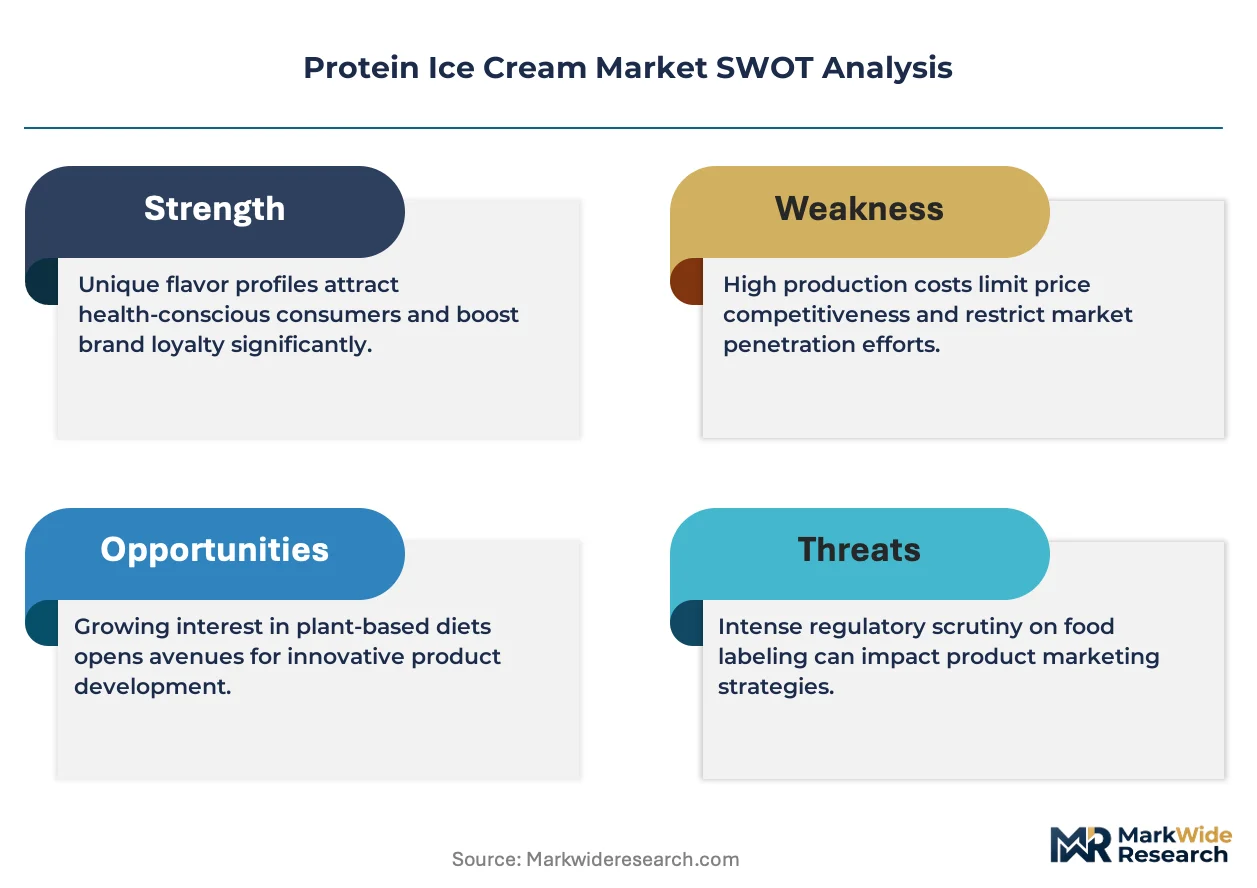
FDA's updated nutrition labeling requirements for protein content claims are forcing manufacturers to reformulate across whey, casein, and plant isolate bases, compressing margins while elevating technical barriers to entry.
Growth Catalysts
- FDA Protein Claim Rules:The United States regulator's stricter substantiation standards for "high protein" and "excellent source" claims are accelerating clean-label investments and pushing formulators toward precision-fermented dairy proteins with verified amino acid profiles.
- Fitness Enthusiast Subscription Models:Direct-to-consumer reordering formats among gym-goers and competitive athletes are displacing traditional supermarket impulse purchases, concentrating lifetime value in curated online channels.
- Precision Fermentation Scale-Up:Bioreactor capacity expansion for animal-free dairy proteins is absorbing venture capital inflows and enabling texture-matched formulations that bypass conventional whey supply constraints.
Market Restraints
- Whey Protein Concentrate Volatility:Global dairy commodity swings transmit directly to input costs, squeezing gross margins for brands locked into conventional whey sourcing without long-term offtake agreements with co-manufacturers.
- EFSA Novel Food Pathways:European precision-fermented proteins face 18-24 month safety evaluation timelines under centralized novel food regulations, delaying market access for fermentation-derived entrants relative to plant-based alternatives.
- Texture-Function Tradeoffs:High-protein density formulations above 15 grams per serving encounter scoopability degradation and ice crystal formation, limiting product architecture without expensive hydrocolloid stabilization systems.
Strategic Opportunities
- India FSSAI Protein Fortification:India's food safety regulator is evaluating protein claim frameworks for functional foods, opening a 1.4 billion-person market where dairy consumption traditions align with ice cream formats.
- Specialty Store Curated Assortments:Premium fitness retailers and boutique grocers are capturing outsized margin pools through exclusive flavor rotations and influencer co-development programs unavailable in mass retail.
- Plant-Isolate Taste Convergence:Pea and fava protein isolate suppliers are achieving flavor-neutral profiles through enzymatic debittering, enabling vegan formats to compete on sensory parity with dairy-based protein ice creams.
Industry Challenges
- Co-Manufacturer Capacity Bottlenecks:Qualified frozen dessert facilities with high-shear mixing and controlled overrun capabilities are concentrated among a handful of North American and European contract manufacturers, constraining rapid scale-up.
- Dual Jurisdiction Compliance:Brands distributing across FDA and EFSA regimes must maintain parallel substantiation dossiers for protein claims, fragmenting regulatory affairs resources and extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Ice Cream Market |
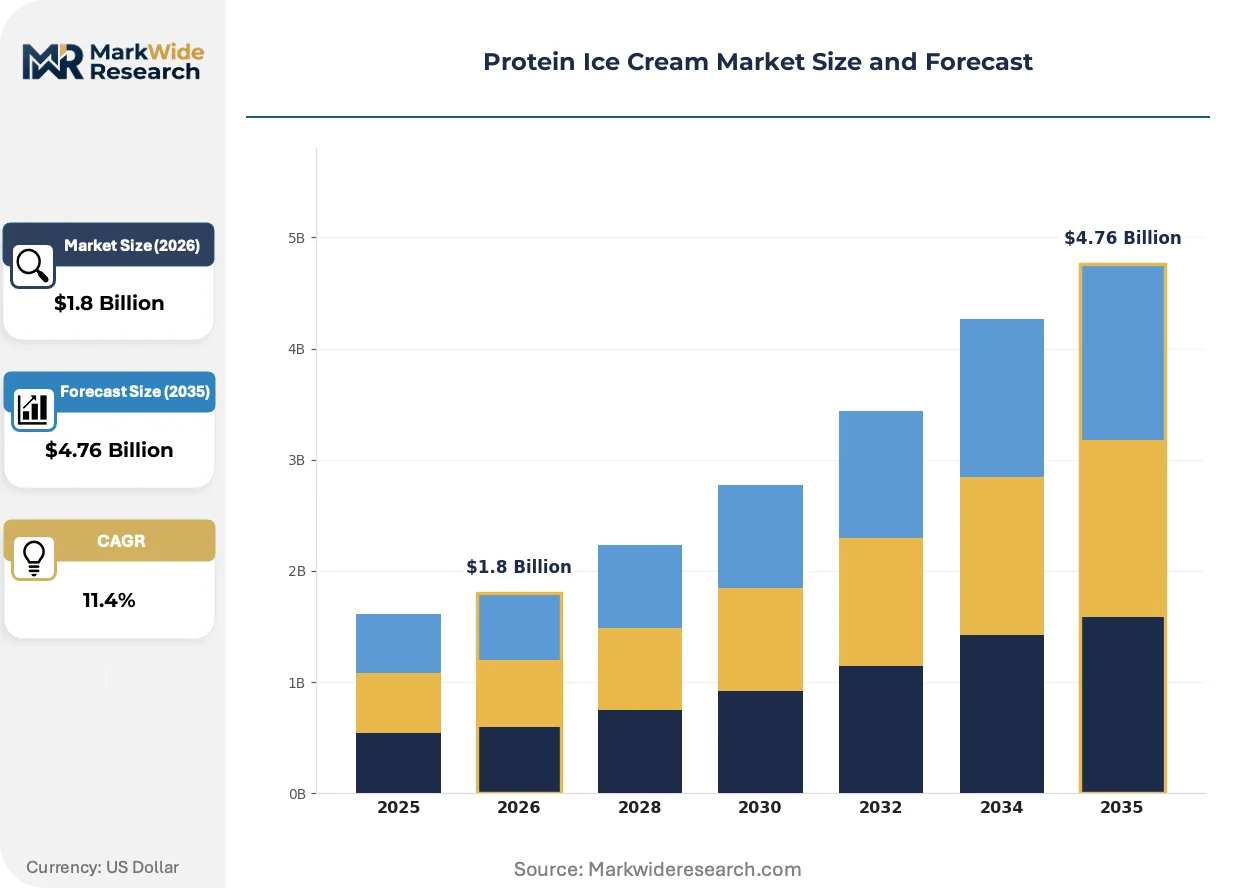
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Protein, Low-Sugar, Non-Dairy, Plant-Based Distribution Channel: Online, Supermarkets, Specialty Stores, Health Food Shops Customer Type: Health Conscious, Fitness Enthusiasts, Dietary Restriction Consumers, Families Packaging Type: Cups, Pints, Single Serve, Bulk |
| Companies Covered | Yasso, Peak Protein, Halo Top, Perfect Day, The Brooklyn Creamery, Wheyhey, Arctic Zero, Protein Pints, So Delicious, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Ice Cream Market Evolving Landscape
Formulation science and regulatory classification debates are reshaping competitive positioning in protein ice cream, with texture engineering and novel protein sourcing pathways commanding R&D investment priority.
Precision-fermented dairy proteins are absorbing technical validation resources from both startups and established dairy alternatives. Biotech platforms using microbial hosts to express casein and whey proteins are achieving gelling and emulsification properties identical to conventional dairy. Fitness enthusiasts and clean-label seekers are adopting these formats at accelerating velocity as sensory equivalence improves.
EFSA's evolving stance on precision-fermented dairy under novel food frameworks is compressing European launch timelines for fermentation-derived entrants. The regulator's 2023-2024 consultation period on "cellular agriculture" classification has introduced uncertainty over whether animal-free dairy proteins qualify as dairy or novel food. Brands targeting Germany, France, and Netherlands distribution are responding with parallel dossier preparation for both pathways.
Gym-based vending and micro-market installations are displacing traditional retail freezer placement among core protein ice cream consumers. Boutique fitness chains and CrossFit affiliates are installing dedicated frozen dessert units with subscription-linked QR code purchasing. This channel rotation is most visible in United States coastal metros and United Kingdom urban centers where fitness penetration exceeds national averages.
Protein Ice Cream Market Segmentation
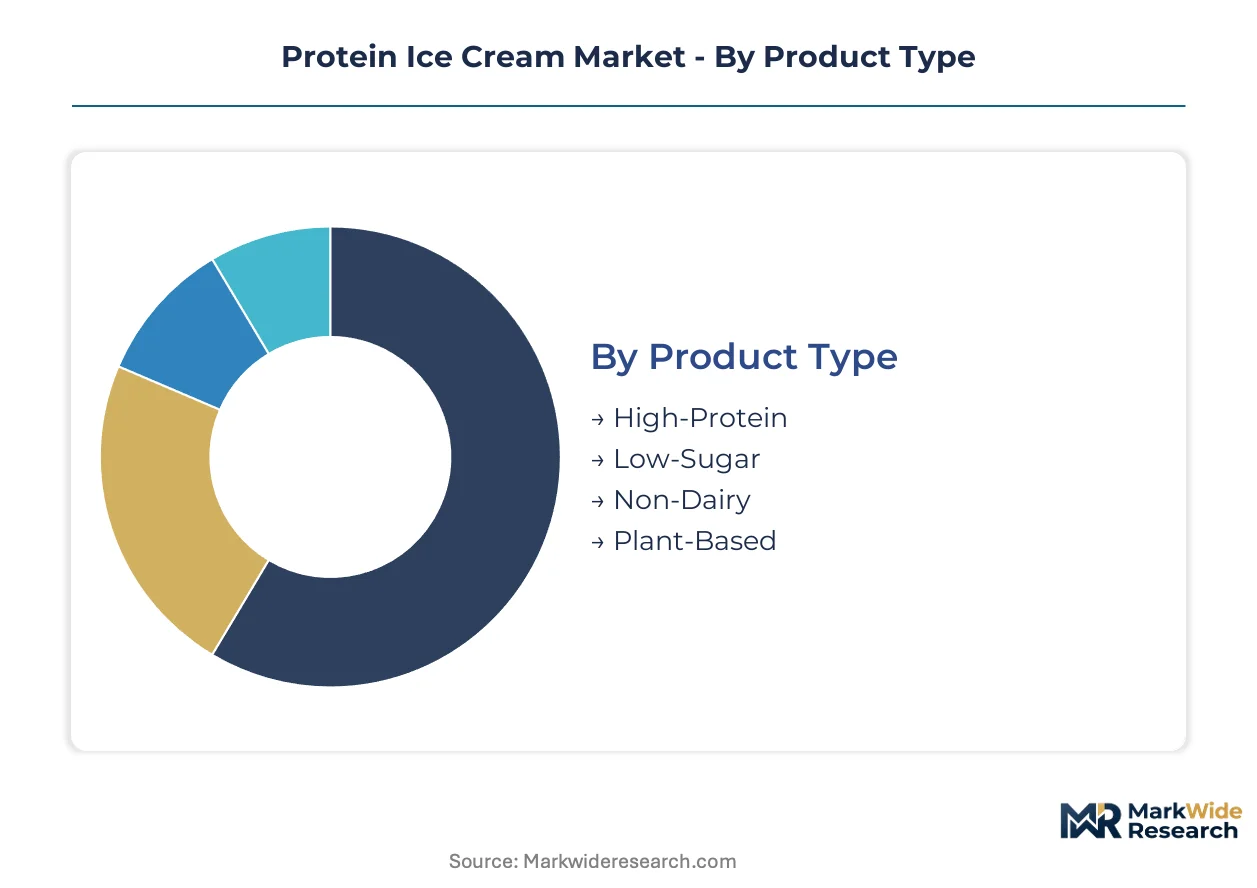
Protein ice cream segmentation reveals divergent technical requirements across consumption contexts. Standalone premium formats demand precision-fermented proteins and controlled overrun engineering, while embedded retail SKUs compete on shelf stability and impulse pricing. Manufacturers must align formulation investments with channel-specific performance thresholds rather than pursuing universal recipes.
Product Type:
Integration depth varies sharply across this category, with standalone functional formats commanding premium R&D investment while hybrid dessert-positioned variants embed protein claims within conventional indulgence frameworks.
- High-Protein:Formulations delivering 15-20 grams protein per serving through whey or casein isolates, requiring hydrocolloid stabilization to maintain scoopability at elevated protein density. Demand concentrates among competitive athletes and bodybuilders in United States metro markets where gym-adjacent retail placement drives reorder frequency. Texture-function tradeoffs above 15 grams per serving elevate manufacturing complexity and ingredient costs.
- Plant-Based:Pea, fava, and rice protein isolates formulated for vegan and lactose-intolerant consumers, with enzymatic debittering investments narrowing sensory gaps with dairy-based alternatives. European markets show fastest adoption velocity as EFSA novel food pathways for precision-fermented dairy create temporary access advantages for plant isolates. Clean-label positioning attracts sustainability-motivated purchasers willing to absorb 15-25% price premiums.
- Low-Sugar:Sugar alcohol and high-intensity sweetener systems replacing sucrose to maintain frozen dessert texture while reducing glycemic load.
- Non-Dairy:Coconut, oat, or almond milk bases with added protein isolates, targeting dairy allergy consumers rather than ethical vegan positioning.
High-Protein leads volumes today; Plant-Based is gaining share fastest.
Distribution Channel:
Cost tier stratification separates premium curated channels from high-volume retail, with margin structures dictating which product architectures each channel can absorb.
- Specialty Stores:Boutique fitness retailers and premium grocers capturing outsized margins through exclusive flavor rotations and influencer co-development programs. United States coastal metros and United Kingdom urban centers concentrate this channel's footprint where fitness penetration exceeds national baselines. Curated assortments justify 30-40% price premiums over mass retail equivalents.
- Online:Direct-to-consumer subscription formats displacing supermarket impulse purchases among core protein ice cream buyers, with QR-code-linked reorder systems embedded in gym micro-markets. Lifetime value concentration in this channel rewards brands investing in retention analytics and personalized flavor profiling. Cold-chain logistics requirements constrain geographic expansion for smaller entrants.
- Supermarkets:Mainstream grocers prioritizing shelf-stable formulations and recognizable brand names over functional innovation.
- Health Food Shops:Independent retailers emphasizing clean-label credentials and local or regional brand discovery.
Supermarkets dominate absolute volume; Online climbs the fastest as subscription models mature.
Customer Type:
Application intensity separates performance-optimized purchasers from occasion-driven buyers, with protein target thresholds varying tenfold across these segments.
- Fitness Enthusiasts:Competitive athletes and dedicated gym-goers treating protein ice cream as post-workout recovery nutrition rather than indulgence. This segment demands verified amino acid profiles and rejects formulations below 15 grams protein per serving. United States demand concentrates in CrossFit affiliates and boutique studio ecosystems where peer influence accelerates brand adoption.
- Dietary Restriction Consumers:Lactose-intolerant, dairy-allergic, and vegan purchasers prioritizing allergen safety and ethical sourcing over protein density thresholds. European markets show higher prevalence of this segment due to stricter allergen labeling requirements and plant-forward dietary traditions. Clean-label verification demands exceed those of performance-focused buyers.
- Health Conscious:General wellness seekers treating protein fortification as a permissibility signal for dessert consumption.
- Families:Household purchasers balancing adult functional demands with children's taste preferences in multi-serve formats.
Fitness Enthusiasts anchor premium pricing power; Dietary Restriction Consumers expand the addressable base most quickly.
Packaging Type:
Volume scale and consumption occasion determine packaging economics, with single-serve formats absorbing disproportionate per-unit cost structures.
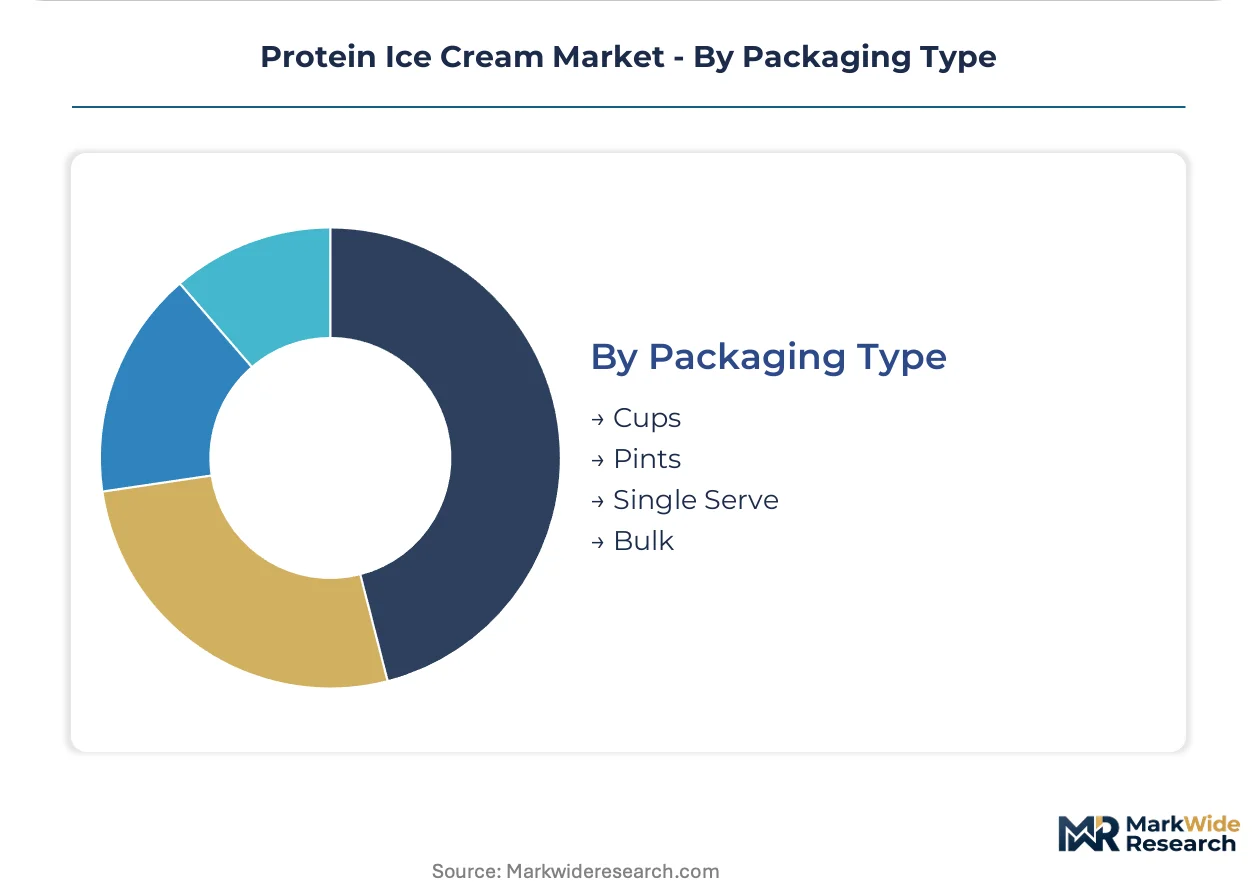
- Pints:Standard 473ml containers dominating at-home consumption and subscription box economics, with HDPE or paperboard options responding to sustainability pressures. United States retail placement favors this format for brand discovery and flavor variety trials. Manufacturing scale advantages concentrate among co-manufacturers with dedicated high-shear mixing lines.
- Single Serve:Individually portioned cups and bars targeting gym vending, office micro-markets, and on-the-go consumption. Premium pricing per gram of protein reflects convenience positioning and cold-chain last-mile costs. United Kingdom urban fitness centers show highest installation density of dedicated freezer units for this format.
- Cups:Multi-pack single-serve configurations balancing portion control with household purchase economics.
- Bulk:Foodservice and institutional formats for gyms, universities, and corporate cafeterias with dedicated frozen dessert programs.
Pints command the revenue base today; Single Serve posts the steepest expansion trajectory as gym-channel penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing power through fitness-channel density, while India offers volume expansion through dairy-forward consumption traditions and regulatory opening. National regulators are recalibrating protein claim frameworks, reshaping where formulation investments flow.
United States
Fitness enthusiasts and CrossFit affiliates drive demand for 15-20 gram protein formats in coastal metros. The FDA's updated substantiation standards for "high protein" claims are forcing reformulation toward precision-fermented dairy proteins with verified amino acid profiles. Los Angeles and New York City concentrate gym-based vending installations with subscription-linked QR purchasing.
United Kingdom
Boutique fitness chains and urban health clubs absorb single-serve formats through dedicated freezer units. EFSA's 18-24 month novel food evaluation timelines for precision-fermented proteins delay fermentation-derived launches relative to plant isolates. London anchors the highest installation density of gym-channel protein ice cream vending.
Germany
Clean-label seekers and sustainability-motivated purchasers absorb 15-25% price premiums for plant-based variants. EFSA's evolving "cellular agriculture" classification consultation introduces uncertainty over animal-free dairy protein pathways. Berlin and Munich fitness ecosystems show accelerating adoption of curated specialty store assortments.
India
Dairy consumption traditions align with ice cream formats across 1.4 billion consumers. FSSAI's evaluation of protein claim frameworks for functional foods is opening regulatory pathways for fortified frozen desserts. Maharashtra and Gujarat industrial clusters concentrate co-manufacturing capacity for emerging domestic brands.
Canada
Health-conscious households balance adult functional demands with family-friendly multi-serve formats. Health Canada's nutrition labeling requirements parallel FDA substantiation standards, easing cross-border formulation alignment. Toronto and Vancouver anchor specialty retail distribution for premium imported and domestic protein ice cream lines.
Protein Ice Cream Market Competitive Landscape
Top-tier vendors anchor shelf-space dominance in mainstream grocers, while emerging precision-fermentation specialists and regional clean-label players occupy differentiated niches. The vendor base stratifies across three tiers: legacy low-calorie brands with distribution scale, biotech-enabled dairy protein platforms, and plant-based specialists targeting allergen-sensitive segments. Dominant competitive moves include precision-fermentation capacity expansion and exclusive flavor co-development with fitness influencers.
Within the biotech-protein tier, Perfect Day represents precision-fermentation scale-up ambitions, while Halo Top exemplifies ultra-low-calorie formulation heritage translated into sustained retail presence. Wheyhey occupies a position among clean-label specialists with British market concentration. These three anchors illustrate how technical differentiation pathways—fermentation-derived proteins, calorie minimization, and allergen-focused positioning—map to distinct competitive territories.
| Leading Market Players |
|---|
| Yasso |
| Peak Protein |
| Halo Top |
| Perfect Day |
| The Brooklyn Creamery |
| Wheyhey |
| Arctic Zero |
| Protein Pints |
| So Delicious |
| Others |
Value Network & Pricing Analysis
Whey protein concentrate futures on the Chicago Mercantile Exchange transmit volatility directly through protein ice cream cost structures, compressing margins for brands without long-term offtake agreements while elevating precision-fermented alternatives into premium pricing tiers. This commodity cascade bifurcates the market between conventional whey-dependent producers absorbing input swings and biotech-enabled formulators commanding stability premiums.
Pricing Analysis
Capacity additions in precision-fermentation bioreactors across California and Singapore are reshaping price floors for animal-free dairy proteins, enabling texture-matched formulations to undercut conventional whey isolates on cost stability. Three-tier pricing structure across premium precision-fermented, standard whey-based, and economy plant-isolate levels separates brands by protein verification rigor and sensory fidelity. Pricing pressure stems from gym-channel subscription models demanding volume discounts, squeezing per-unit economics for entrants lacking scale. Fitness enthusiasts show lowest price sensitivity, accepting 30-40% premiums for verified amino acid profiles, while health-conscious generalists migrate toward mid-tier plant-based alternatives.
Supply Chain Analysis
Single-source vulnerability sits with North American co-manufacturers controlling high-shear mixing and controlled overrun capabilities, concentrating qualified frozen dessert production among a handful of contract facilities. Raw material flows draw from Wisconsin and New Zealand for whey isolates, California and Netherlands for precision-fermentation proteins, and Canada and France for pea and fava protein isolates. Tariff exposure on dairy derivatives threatens margin stability for brands without diversified sourcing. Distribution runs through cold-chain logistics networks anchored in regional frozen distribution centers, with last-mile costs constraining direct-to-consumer geographic expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protein ice cream functions as a stable compounder anchored by fitness-culture normalization that institutionalizes recovery nutrition as daily ritual rather than occasional indulgence.
For Market Incumbents: Extend formulation pipelines into precision-fermented dairy proteins before EFSA and FDA regulatory pathways harden, securing first-mover positioning in clean-label segments. Deepen exclusive co-development agreements with CrossFit affiliates and boutique studio chains to lock in subscription-based lifetime value. Vertical integration into bioreactor capacity or captive offtake agreements with fermentation specialists defends margin position against whey commodity swings. For New Entrants and Emerging Players: FSSAI protein claim framework evaluation in India opens a window for domestic brands to establish footholds before multinational entrants achieve regulatory compliance. Target Maharashtra and Gujarat industrial clusters where co-manufacturing capacity concentrates and dairy consumption traditions align with frozen dessert formats. Plant-isolate taste convergence through enzymatic debittering offers the most penetrable entry angle for vegan positioning without precision-fermentation capital requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-fermentation platforms achieving regulatory clarity across multiple jurisdictions simultaneously. Five-to-ten-year viability favors biotech-enabled dairy protein specialists with validated texture-function profiles and diversified geographic dossier preparation. Watch EFSA's final "cellular agriculture" classification determination as the inflection signal that either accelerates European market access or fragments compliance architecture for fermentation-derived entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Scale-Up | Bioreactor capacity expansion in California and Singapore enables cost-competitive animal-free dairy proteins with verified amino acid profiles. |
| Gym-Channel Micro-Market Installation | QR-code-linked subscription systems in CrossFit affiliates and boutique studios concentrate lifetime value away from supermarket impulse purchases. |
| Regulatory Dossier Diversification | Parallel FDA and EFSA substantiation preparation hedges against novel food reclassification risk for fermentation-derived proteins. |
| Plant-Isolate Taste Convergence | Enzymatic debittering investments by pea and fava suppliers narrow sensory gaps with dairy-based alternatives for vegan positioning. |
| Co-Manufacturer Capacity Lock-Up | Long-term agreements with qualified frozen dessert facilities secure high-shear mixing and controlled overrun capabilities for rapid scale-up. |
Research Methodology
Direct dialogue with protein ice cream brand managers, frozen dessert co-manufacturing executives, regulatory affairs specialists at precision-fermentation platforms, and category buyers at specialty fitness retailers grounded qualitative insights. Secondary validation drew from FDA nutrition labeling guidance documents, EFSA novel food consultation records, FSSAI functional food framework evaluations, and trade data on whey protein concentrate imports. Bottom-up demand modeling across gym-channel subscription flows and top-down market sizing from retail audit databases achieved triangulation.
Segment-level projections across high-protein, plant-based, low-sugar, and non-dairy product types combined with distribution channel dynamics and customer archetype penetration rates produced volume and value estimates across the analysis window. CAGRs derived from fitted growth curves incorporating protein claim regulatory adoption timelines, precision-fermentation capacity expansion schedules, and fitness-channel vending installation densities. Forecast inputs included bioreactor deployment pipelines, co-manufacturer capacity utilization rates, and cross-border cold-chain logistics cost indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA reclassification of precision-fermented proteins as novel foods rather than dairy equivalents, or sustained whey commodity volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Germany Non-Dairy Milk Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Cheese Analogue Market