
 Digital Cutting Machine Market | 2026-2036
Digital Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Cutting Machine Market Insights
The capability gap between high-R&D specialists and assembly-only vendors is collapsing as software-defined control becomes table stakes. ZUND leverages its integrated CAD-to-cut workflow to sustain premium positioning across European packaging hubs. Lectra SA anchors its franchise through deep textile automation expertise, while Kongsberg PCS competes aggressively in signage and display substrates.
A digital cutting machine is a computer-numerically-controlled fabrication system that drives blades, lasers, or knives across flat or semi-rigid materials with positioning tolerances typically below 0.1 millimeters, executing vector paths derived from CAD files to produce finished parts without hard tooling. Its primary purpose is to eliminate die-making lead times and enable lot-size-one production across industrial and commercial workflows. Flatbed cutter configurations dominate installed base and aftermarket service revenue, while laser cutter variants capture disproportionate margin pools in aerospace fabricator and composite material processing applications where thermal precision replaces mechanical contact. Optical sensor technology is gaining fastest traction as real-time material distortion correction becomes standard in high-volume textile designing and automotive trim operations.
EPA emissions guidelines for composite material processing and OSHA machine guarding standards shape US equipment specifications, while REACH substance restrictions in Europe drive material compatibility testing for cutting surfaces and extraction systems. The EU Machinery Directive and ISO safety standards further constrain market access for non-certified suppliers. Stakeholders must monitor how servo motor efficiency regulations and emerging digital product passport requirements reshape total cost of ownership calculations and supplier qualification timelines.
Market Dynamics
Software-defined control architectures are collapsing the historical capability gap between high-R&D specialists and assembly-only vendors, compressing premium positioning power across European packaging hubs and German automotive clusters.
Growth Catalysts
- REACH substance restrictions:European material compatibility mandates are forcing equipment upgrades across composite processing lines, accelerating replacement cycles for extraction systems and cutting surfaces.
- Automotive trim precision:OEMs in Germany and adjacent supply basins are specifying sub-0.1 millimeter tolerances for interior material processing, pulling advanced flatbed configurations into production lines.
- Optical sensor integration:Real-time distortion correction technology is becoming standard in high-volume textile operations, expanding addressable application scope beyond traditional mechanical cutting.
Market Restraints
- Servo motor supply concentration:Precision motion control component sourcing clusters in East Asian manufacturing basins, exposing lead time vulnerability for European and North American fabricators.
- EPA composite emissions compliance:US equipment specifications now require costly extraction system redesigns, elevating total cost of ownership for mid-scale operators.
- Laser thermal precision limitations:Aerospace-grade composite processing remains locked to high-capital laser variants, mechanically excluding price-sensitive entry segments.
Strategic Opportunities
- EU digital product passport mandates:Emerging traceability requirements will favor integrated CAD-to-cut workflow vendors capable of automated documentation generation.
- Signage substrate convergence:Display and exhibition industries are consolidating equipment procurement around multi-material platforms, opening cross-selling pathways for flatbed specialists.
- India packaging automation:Underpenetrated converting operations present white space for servo-driven knife systems as labor cost arbitrage erodes.
Industry Challenges
- ISO safety certification timelines:Machinery Directive compliance testing extends supplier qualification periods, delaying market entry for non-certified vendors.
- CAD-to-floor integration complexity:Legacy ERP systems in established textile houses resist seamless workflow handoff, demanding costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Cutting Machine Market |
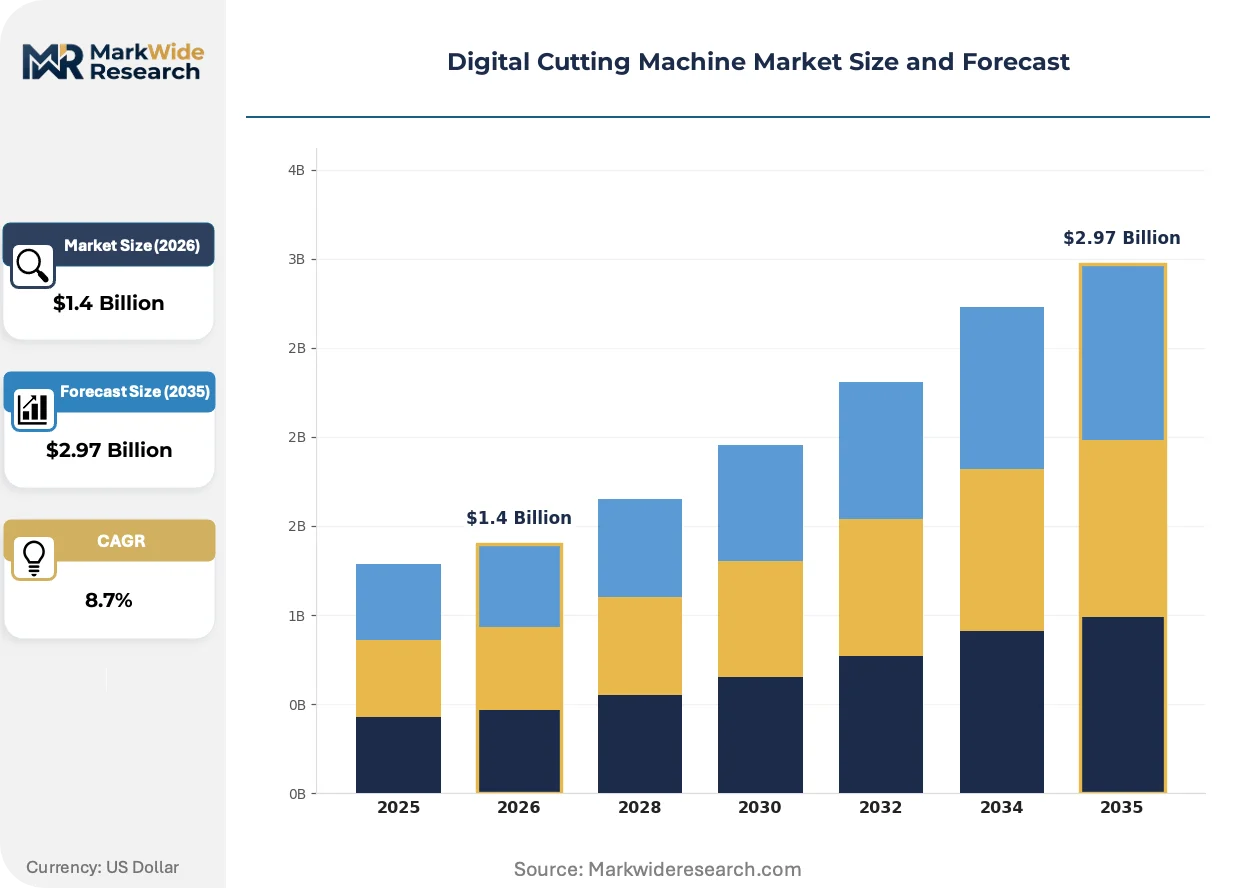
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Cutter, Rotary Cutter, Laser Cutter, V-Cut Machine, Knife Cutter Technology: CAD Software Integration, Automated Control System, Digital Servo Motor, Optical Sensor, Touchscreen Interface Application: Packaging Manufacturing, Textile Designing, Signage Production, Automotive Trim, Composite Material Processing End User: Print Shops, Apparel Manufacturers, Vehicle Assembly Plants, Advertising Agencies, Aerospace Fabricators |
| Companies Covered | ZUND, Kongsberg PCS, Bullmer, Ningbo Jingwei, Richpeace, Elitron, Lectra SA, ESKO, Gerber Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Cutting Machine Market Trends and Innovations
Control software, sensor hardware, and regulatory traceability requirements are converging to redefine equipment specification criteria and vendor selection frameworks across industrial and commercial buyer segments.
Vision-guided knife positioning is displacing mechanical registration systems in textile and automotive trim applications. Tier-one seat manufacturers in Germany now specify camera-array feedback loops as baseline requirements. This displacement is compressing margins for vendors lacking in-house optical engineering capabilities.
REACH substance restrictions are tightening material surface compatibility testing protocols for cutting beds and extraction filtration media. Equipment suppliers must now document chemical composition across consumable touchpoints. Composite fabricators in France and Benelux markets are front-loading compliance verification into procurement evaluations.
Service contract unbundling is fragmenting traditional bundled maintenance relationships. Large-format print shops and packaging converters now separate hardware acquisition from software subscription and field service agreements. This pattern is most pronounced in UK and Dutch markets where independent service providers have built certified technician networks.
Digital Cutting Machine Market Segmentation
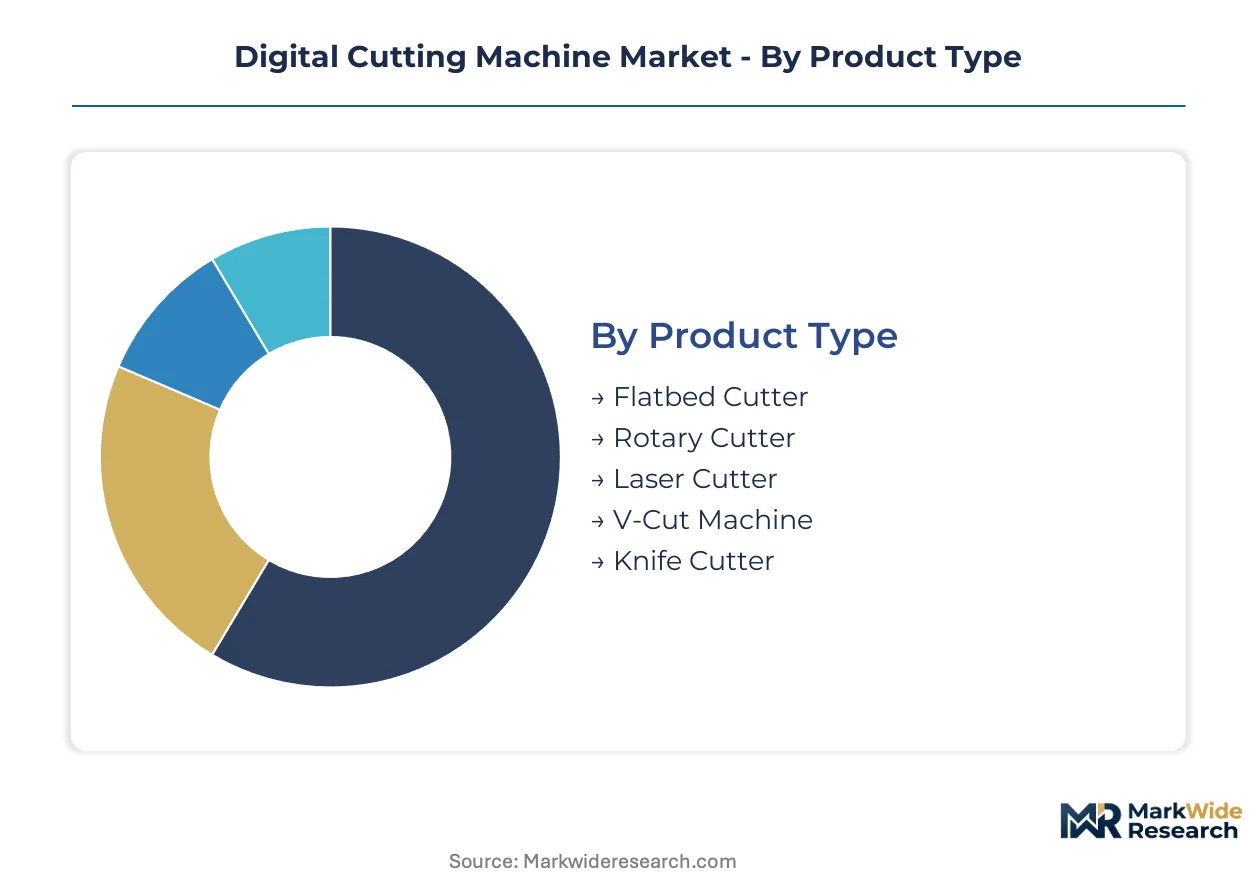
Equipment specification in digital cutting machines fragments across product architectures, control technologies, and end-use workflows. Substitution pressures from adjacent fabrication methods reshape competitive boundaries within each category.
Product Type:
Flatbed configurations face the strongest substitution threat from hybrid additive-subtractive systems in prototyping environments, while laser variants defend position through thermal precision that mechanical alternatives cannot replicate.
- Flatbed Cutter:Computer-numerically-controlled gantry systems position blades or knives across stationary material beds with sub-0.1 millimeter repeatability. German automotive trim suppliers and Dutch packaging converters anchor procurement volume as REACH-compliant material handling becomes mandatory.
- Laser Cutter:Thermal ablation systems using CO2 or fiber sources vaporize material along vector paths without mechanical contact. Aerospace fabricators in France and composite processors in Belgium specify these for carbon fiber and aramid processing where blade wear would contaminate substrates.
- Rotary Cutter:Cylindrical blade drums enable continuous feed cutting of rolled textiles and flexible films.
- V-Cut Machine:Angled blade scoring systems create fold lines in corrugated and folding carton substrates.
- Knife Cutter:Oscillating or drag-knife configurations handle thick foam, rubber, and gasket materials.
Flatbed Cutter retains volume leadership; Laser Cutter holds the steepest expansion curve.
Technology:
Control layer differentiation determines margin capture, with software-defined architectures eroding historical hardware specialization advantages.
- CAD Software Integration:Native vector file interpretation and nesting algorithms eliminate pre-processing bottlenecks. UK large-format print shops and German packaging design houses prioritize seamless Illustrator-to-cut workflow handoff.
- Optical Sensor:Camera-array feedback loops detect material distortion and edge position in real time. Tier-one seat manufacturers in Germany now specify this as baseline for textile and leather cutting operations.
- Automated Control System:PLC-based machine sequencing coordinates multi-axis motion and tool changes.
- Digital Servo Motor:Closed-loop positioning drives achieve acceleration rates exceeding mechanical alternatives.
- Touchscreen Interface:Operator panels reduce training burden and error rates in high-turnover production environments.
CAD Software Integration commands the widest installed base; Optical Sensor is climbing the fastest.
Application:
End-use concentration varies sharply by precision requirement and material handling complexity, with automotive and aerospace specifications pulling technology upward.
- Packaging Manufacturing:Folding carton, corrugated, and flexible film converting dominate unit shipments. Benelux and UK converters drive specification of quick-change tooling systems as SKU proliferation accelerates.
- Automotive Trim:Interior leather, synthetic suede, and acoustic textile processing demands sub-0.1 millimeter tolerances. OEM supply bases in Germany and tier-one clusters in Austria anchor premium equipment procurement.
- Textile Designing:Pattern cutting and sample production in apparel and upholstery workflows.
- Signage Production:Acrylic, foam board, and vinyl cutting for display and exhibition industries.
- Composite Material Processing:Carbon fiber and glass fiber prepreg cutting for aerospace and wind energy components.
Packaging Manufacturing retains volume leadership; Automotive Trim holds the steepest expansion curve.
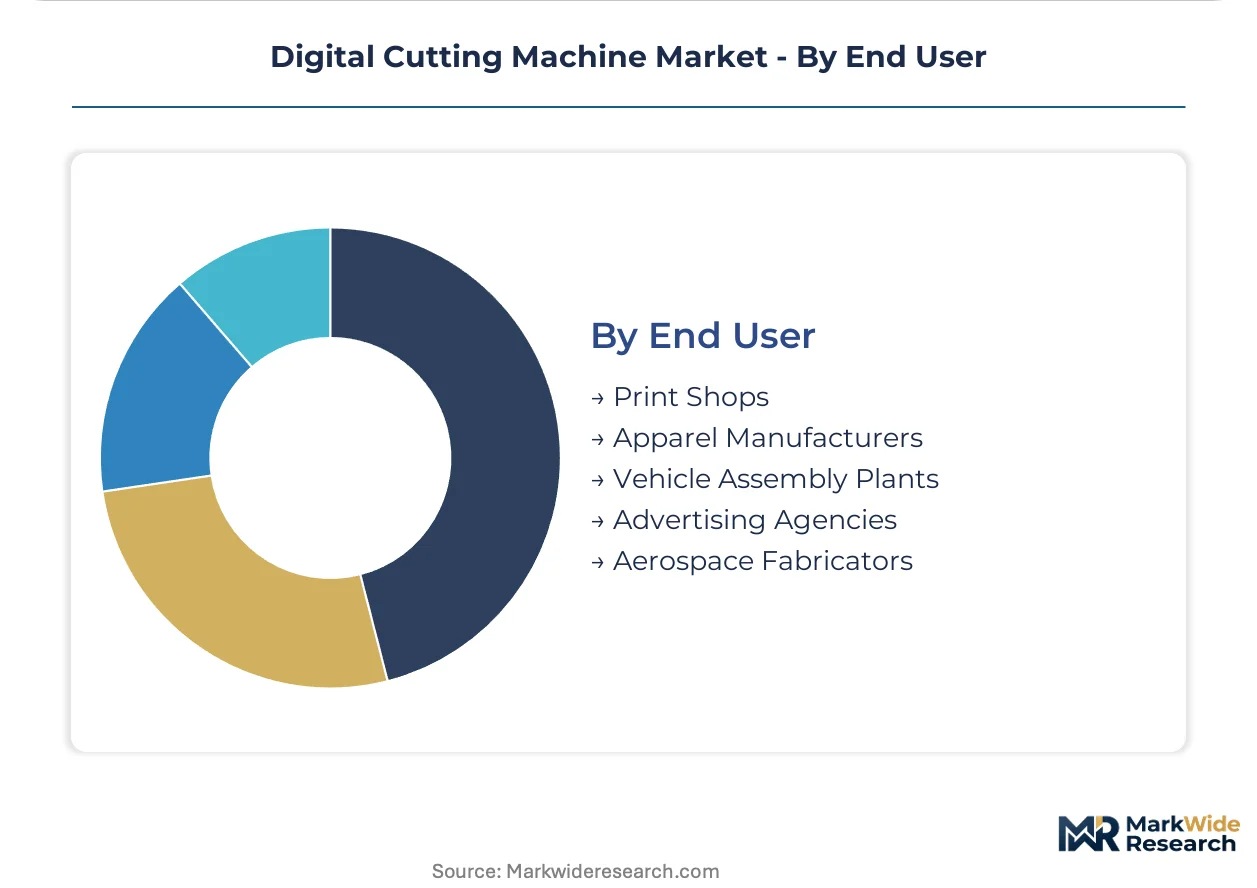
End User:
Customer scale and technical sophistication create distinct procurement patterns, with capital intensity and compliance requirements segmenting the buyer base.
- Vehicle Assembly Plants:Tier-one and OEM in-house operations specify fully integrated cells with automated material handling. German and French automotive clusters drive demand for ISO-certified safety architectures and REACH-compliant extraction systems.
- Aerospace Fabricators:Composite part manufacturers require thermal cutting for advanced materials and full process traceability. French and Italian aerostructures suppliers prioritize equipment with automated documentation generation for EU digital product passport readiness.
- Print Shops:Wide-format and sign production operations value throughput and substrate flexibility.
- Apparel Manufacturers:Pattern making and sample production operations balance precision against labor cost arbitrage.
- Advertising Agencies:In-house production studios and experiential marketing fabricators.
Print Shops retain volume leadership; Aerospace Fabricators hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium equipment procurement in Germany commands pricing power that assembly-only vendors in India cannot replicate, creating a structural asymmetry across procurement basins.
Germany
Automotive trim suppliers in Stuttgart and Munich specify sub-0.1 millimeter tolerance systems for interior leather processing. REACH substance restrictions under ECHA mandate extraction system upgrades across Baden-Württemberg composite fabricators. The Bavarian packaging cluster around Nuremberg drives quick-change tooling adoption as SKU proliferation accelerates.
United States
Aerospace fabricators in Seattle and Wichita require thermal precision for carbon fiber prepreg cutting without mechanical contact. EPA emissions guidelines for composite processing elevate extraction system costs for mid-scale operators. The Pacific Northwest signage production corridor consolidates procurement around multi-material flatbed platforms.
France
Aerostructures suppliers in Toulouse prioritize automated documentation generation for EU digital product passport readiness. ECHA REACH compliance testing protocols tighten material surface compatibility requirements for cutting beds. The Lyon textile design cluster integrates camera-array feedback loops as baseline specifications.
China
Packaging converters in the Yangtze River Delta adopt servo-driven knife systems as labor cost arbitrage erodes. GB standards and MIIT industrial automation directives shape equipment specification criteria. The Pearl River Delta apparel manufacturing belt demands pattern cutting precision for export-oriented production.
India
Underpenetrated converting operations in Maharashtra and Gujarat present white space for automation vendors. BIS certification requirements and DGFT import regulations constrain non-certified supplier market entry. The Tamil Nadu textile processing corridor balances precision requirements against capital intensity constraints.
Digital Cutting Machine Market Competitive Landscape
Concentration sits with integrated CAD-to-cut workflow specialists who have collapsed the historical capability gap against assembly-only vendors. The vendor base stratifies across three tiers: premium software-defined platforms, mid-market servo-driven systems, and price-competitive mechanical configurations. Strategic archetypes include European precision automation houses, East Asian scale fabricators, and North American aerospace specialists. Competitive moves center on strategic partnerships for sensor technology licensing and geographic expansion into underpenetrated Asian packaging markets.
Among European precision automation houses, ZUND and Lectra SA exemplify the integrated workflow archetype, while Kongsberg PCS anchors the signage and display substrate specialization tier. These three occupy positions that reflect divergent R&D intensity and geographic procurement focus rather than convergent product strategies.
| Leading Market Players |
|---|
| ZUND |
| Kongsberg PCS |
| Bullmer |
| Ningbo Jingwei |
| Richpeace |
| Elitron |
| Lectra SA |
| ESKO |
| Gerber Technology |
| Others |
Pricing and Supply Chain Analysis
REACH substance restrictions under ECHA simultaneously gate supplier qualification and stratify price tiers across European procurement basins, forcing mid-scale operators to absorb compliance premiums while premium vendors capture margin expansion through certified extraction systems.
Pricing Analysis
Configured-to-order pricing commands spreads exceeding standard flatbed configurations by factors tied to optical sensor integration and CAD-to-cut workflow depth. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling intensity. Cost compression in entry mechanical tiers is intensifying because assembly-only vendors from East Asian manufacturing basins erode base pricing. Print shops and packaging converters exhibit highest price sensitivity; aerospace fabricators and automotive OEM supply chains demonstrate lowest.
Supply Chain Analysis
Just-in-time component sourcing dominates servo motor and optical sensor procurement, though strategic stockpiling of cutting surfaces and extraction filtration media persists among REACH-compliant European fabricators. Precision motion control component sourcing clusters in China, Japan, and South Korea, exposing lead time vulnerability for European and North American equipment assemblers. The supply chain rests on high-grade aluminum framing systems, linear motion rails, and laser resonator assemblies. Single-source vulnerability concentrates in camera-array feedback loop suppliers. Distribution runs through OEM-direct channels for large automotive and aerospace accounts, with regional distributor networks serving mid-scale packaging and signage operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house optical engineering capabilities and ECHA REACH certification infrastructure constitute scarce assets that concentrate margin capture among integrated workflow specialists, leaving assembly-dependent vendors exposed to substitution.
For Market Incumbents: Secure optical sensor technology licensing partnerships to defend against vision-guided knife positioning commoditization. Anchor certification investment in EU digital product passport readiness to preempt regulatory displacement. Capacity addition in underpenetrated Indian packaging corridors counters East Asian labor cost arbitrage erosion. For New Entrants and Emerging Players: Anchor in Maharashtra and Gujarat converting operations where BIS certification gaps delay incumbent market entry. Target signage substrate convergence as the most penetrable application segment, exploiting multi-material platform demand consolidation. Pursue independent service provider certification to capture unbundled maintenance relationships fragmenting in UK and Dutch markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive digital cutting divisions lacking standalone scale. Long-term viability favors vendors with software-defined control architectures and automated documentation generation capabilities. Watch EU digital product passport mandate implementation timelines as inflection indicator for integrated workflow premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sensor Technology Licensing | Camera-array feedback loops are becoming baseline specifications for German automotive trim suppliers. |
| EU Digital Product Passport Integration | Automated documentation generation capabilities will separate compliant vendors from qualification-delayed competitors. |
| Backward Integration into Servo Motor Sourcing | In-house precision motion control production reduces East Asian supply concentration exposure for European fabricators. |
| Geographic Expansion into Indian Packaging Markets | Maharashtra and Gujarat converting operations present white space as labor cost arbitrage erodes manual cutting. |
| Service Contract Unbundling | Independent certified technician networks capture fragmented maintenance relationships in UK and Dutch large-format print shops. |
Research Methodology
A standing panel of plant engineers at automotive trim suppliers, packaging converter operations managers, aftermarket service heads, and OEM procurement teams provided ongoing calibration against secondary validation from customs trade data, SEC equipment manufacturer filings, ECHA REACH substance restriction updates, and ISO machinery safety certification registries. Primary fieldwork combined structured interviews with bottom-up and top-down triangulation across installed base estimates and regional production cluster surveys.
Consistency checks validated volume and value outputs against aerospace fabricator capex disclosures and automotive interior supplier equipment procurement patterns across the analysis window. Segmentation modeling incorporated product architecture, control technology tier, end-use application precision requirements, and customer scale sophistication. CAGRs were derived from regression analysis of historical replacement cycles and regulatory-forced upgrade trajectories, with servo motor efficiency regulations and digital product passport mandates as specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement intensity and continued automotive trim precision specification tightening; material deviation would warrant model refresh. Revision becomes warranted when EPA composite emissions guidelines or EU Machinery Directive compliance timelines cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Construction Camera Market
Tools
Crimping Tool Market
Tools
L Allen Wrench Market
Tools
Flooring Tools Market
Tools
Automatic Heat Press Machines Market
Tools
Automotive Torque Tools Market
Tools
Cordless Power Drill Market
Tools
Fastening Power Tools Market
Tools
Garden Digging Tools Market
Tools
Woodworking Tools Market
Tools
Edging Tool Market
Tools
Concrete Saw Market
Tools
Portable Grinders Market
Tools
Cutting Equipment Market
Tools
China Power Tools Market
Tools
Tool Hammer Market