
 MIG Guns Market | 2026-2036
MIG Guns Market Size, Share, and Industry Trends Forecast 2026-2036
MIG Guns Market Analytics
Multi-source procurement for consumable torch components is rebalancing toward vertically integrated supply arrangements. Lincoln Electric leverages captive manufacturing of contact tips and nozzles to control lead times. TBi Industries GmbH anchors its position through precision-engineered gas diffuser systems. Panasonic Welding Systems dominates robotic MIG gun integration for automotive OEM lines.
MIG guns are manually or robotically operated welding torches that deliver shielding gas and consumable electrode wire to the weld pool, typically rated between 150 and 600 amperes depending on duty cycle and cooling method. They serve as the primary interface between the welding power source and the workpiece across repetitive production environments. Heavy-duty MIG guns command the largest installed base due to continuous-duty demands in shipbuilding and structural steel. Inverter technology is displacing transformer-based systems as fabricators prioritize energy efficiency and portable deployment. Compact MIG guns represent the fastest-growing product configuration as cobot welding cells proliferate in small-batch metal fabrication.
OSHA enforces permissible exposure limits for manganese in welding fumes, compelling manufacturers to engineer lower-emission gun designs and extraction-integrated torches. The EU Machinery Directive and CE marking requirements govern arc stability and operator safety interlocks for equipment sold across Europe. Stakeholders must monitor evolving fume extraction mandates and power-source interoperability standards as automation retrofits reshape replacement cycles.
Market Dynamics
Robotic welding deployment in automotive OEM lines is compressing replacement cycles and forcing suppliers to redesign MIG guns for seamless cobot integration. This structural shift favors compact, lightweight torch configurations over traditional heavy-duty models.
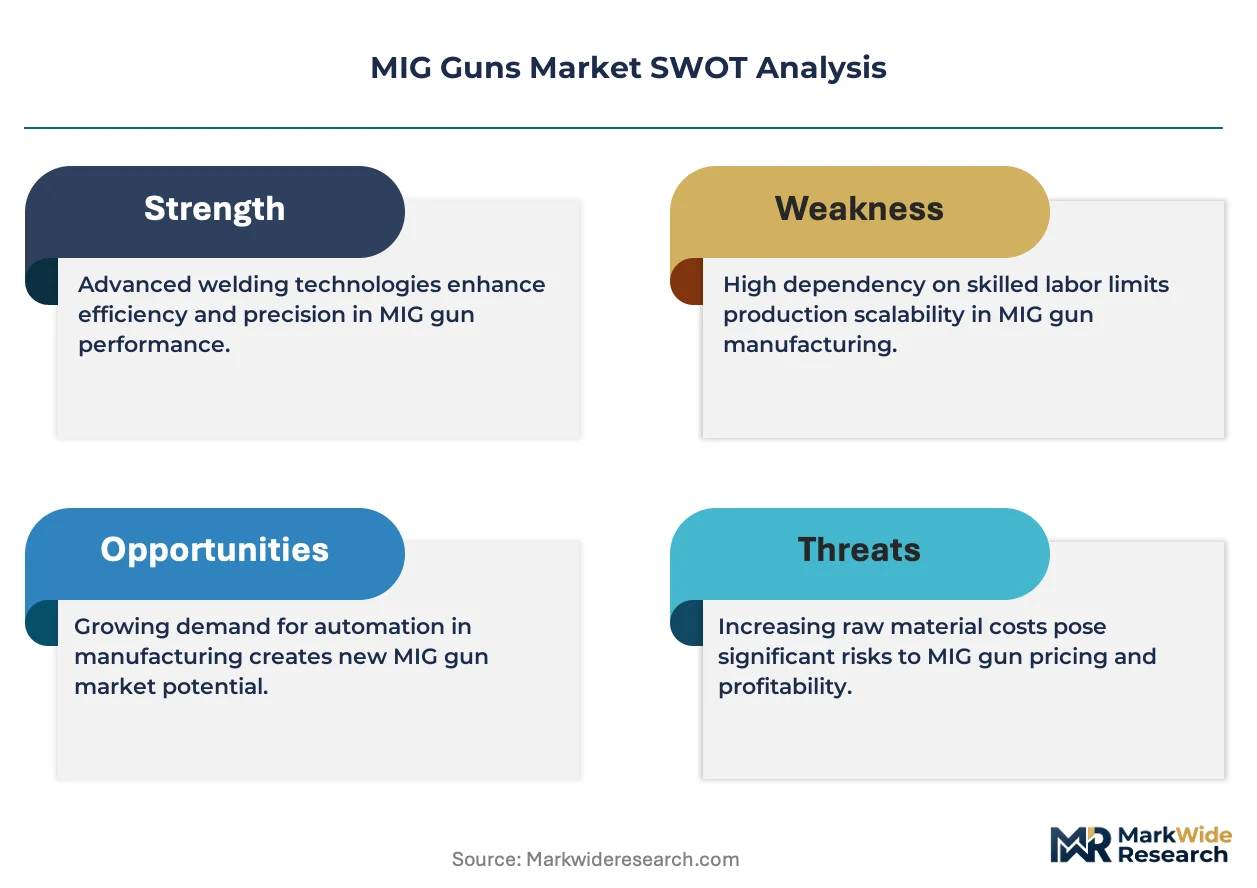
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for arc stability and operator safety interlocks are compelling fabricators to upgrade legacy equipment across European metalworking facilities.
- Automotive lightweighting programs:Aluminum-intensive vehicle architectures are expanding demand for specialized MIG gun configurations optimized for non-ferrous wire feed and thermal management.
- OSHA manganese exposure limits:Permissible exposure limits for welding fumes are accelerating adoption of extraction-integrated torches and lower-emission gun designs in US fabrication shops.
Market Restraints
- Copper and brass input volatility:Contact tips, nozzles, and gas diffusers depend on non-ferrous metal prices that fluctuate with commodity cycles, squeezing margins for consumable-dependent revenue models.
- German precision component concentration:Critical gas diffuser and torch neck manufacturing clusters in Baden-Württemberg create geographic supply risk for non-European fabricators.
- Laser welding substitution:High-speed laser joining systems are capturing thin-gauge automotive applications previously served by MIG processes, particularly in battery tray assembly.
Strategic Opportunities
- India industrial automation acceleration:PLI scheme incentives for capital goods manufacturing are expanding addressable demand for robotic MIG gun integration in emerging automotive supplier parks near Chennai and Pune.
- Wind tower fabrication boom:Offshore wind installation targets in the North Sea and Taiwan Strait are creating demand for heavy-duty water-cooled guns rated for 600-ampere continuous duty on thick plate.
- Digital twin convergence:Integration of MIG gun telemetry with welding data analytics platforms enables predictive maintenance contracts and consumable replenishment automation.
Industry Challenges
- Robotic welding technician scarcity:Programming and maintaining cobot welding cells requires cross-functional skills spanning metallurgy, motion control, and quality systems that outpace vocational training pipeline output.
- CE-UL dual certification timelines:Manufacturers targeting both European and North American markets face extended approval cycles for arc stability validation and electrical safety testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MIG Guns Market |
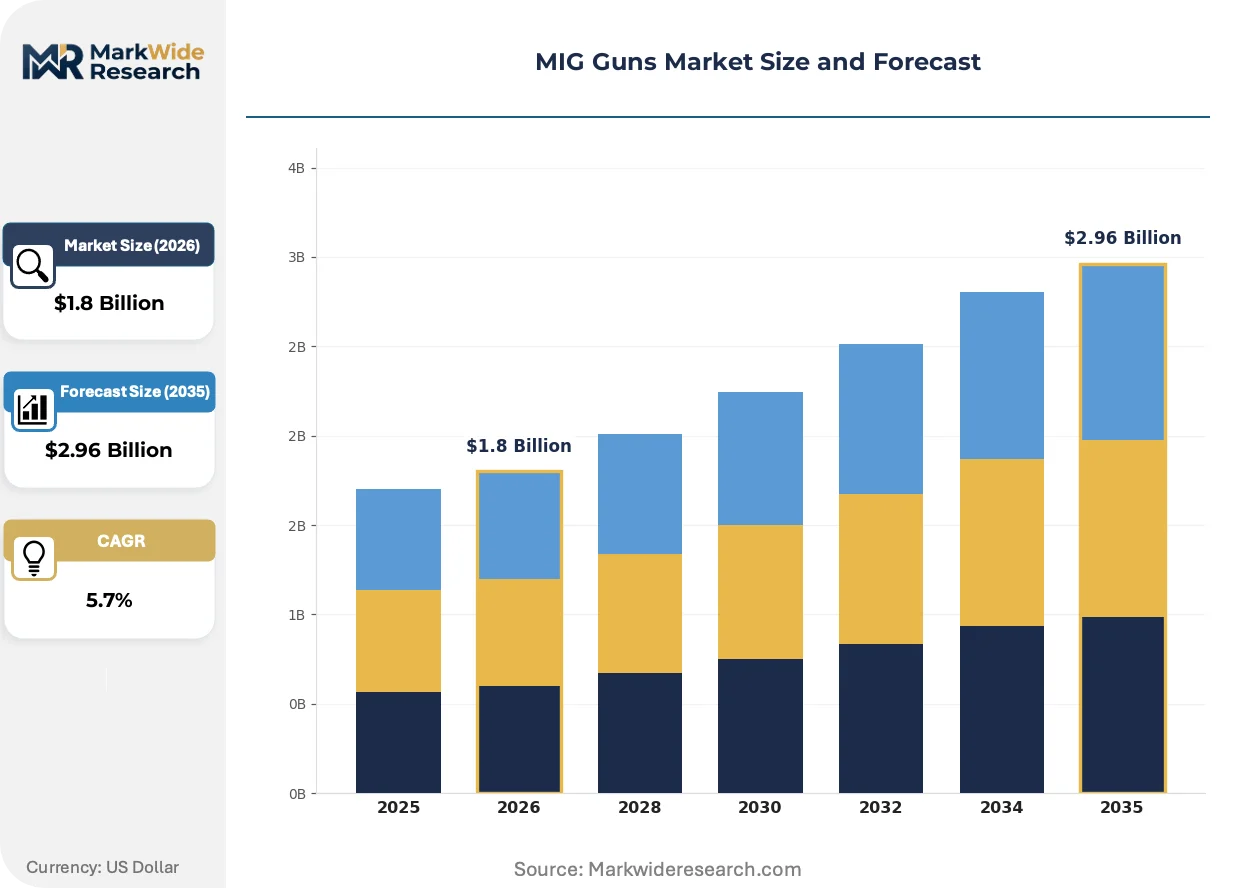
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MIG Guns, Auto Feed MIG Guns, Heavy-duty MIG Guns, Compact MIG Guns Technology: Inverter Technology, Transformer Technology, Mixed Technology, Portable Technology End User: Automotive Manufacturers, Shipbuilders, Metal Fabricators, Construction Companies Application: Repair, Maintenance, Assembly, Fabrication |
| Companies Covered | Lincoln Electric, TBi Industries GmbH, DINSE Inc., Tokin Corporation, SUMIG USA Corporation, ESAB, Miller Electric, Panasonic Welding Systems, Fronius International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MIG Guns Market Evolving Landscape
Inverter power source technology is fundamentally altering how welding current is delivered to the torch, enabling precise waveform control that transformer architectures cannot replicate. This transition is reshaping gun design priorities across fabrication sectors.
Advanced inverter power sources with pulse and double-pulse waveform capabilities are electrifying MIG gun performance benchmarks. Automotive OEMs in Germany and the United States are specifying these systems for aluminum body-in-white applications. The technology is electrifying competitive differentiation as fabricators prioritize energy efficiency and portable deployment over transformer-based reliability.
OSHA's enforcement of permissible exposure limits for manganese in welding fumes is tightening fume extraction integration requirements. Fabricators must now specify torches with onboard extraction nozzles or external capture arms to maintain compliance. Heavy-duty applications in shipyards and structural steel are most affected, with equipment buyers prioritizing extraction-integrated gun designs over conventional configurations.
Buyer concentration among automotive OEMs and tier-one suppliers is compressing procurement cycles and unbundling after-sales service contracts. Large fabricators are negotiating direct supply arrangements with gun manufacturers, bypassing traditional welding distributor networks. This pattern is most visible in Michigan, South Carolina, and Lower Saxony where automotive welding cell deployment is densest.
MIG Guns Market Segmentation
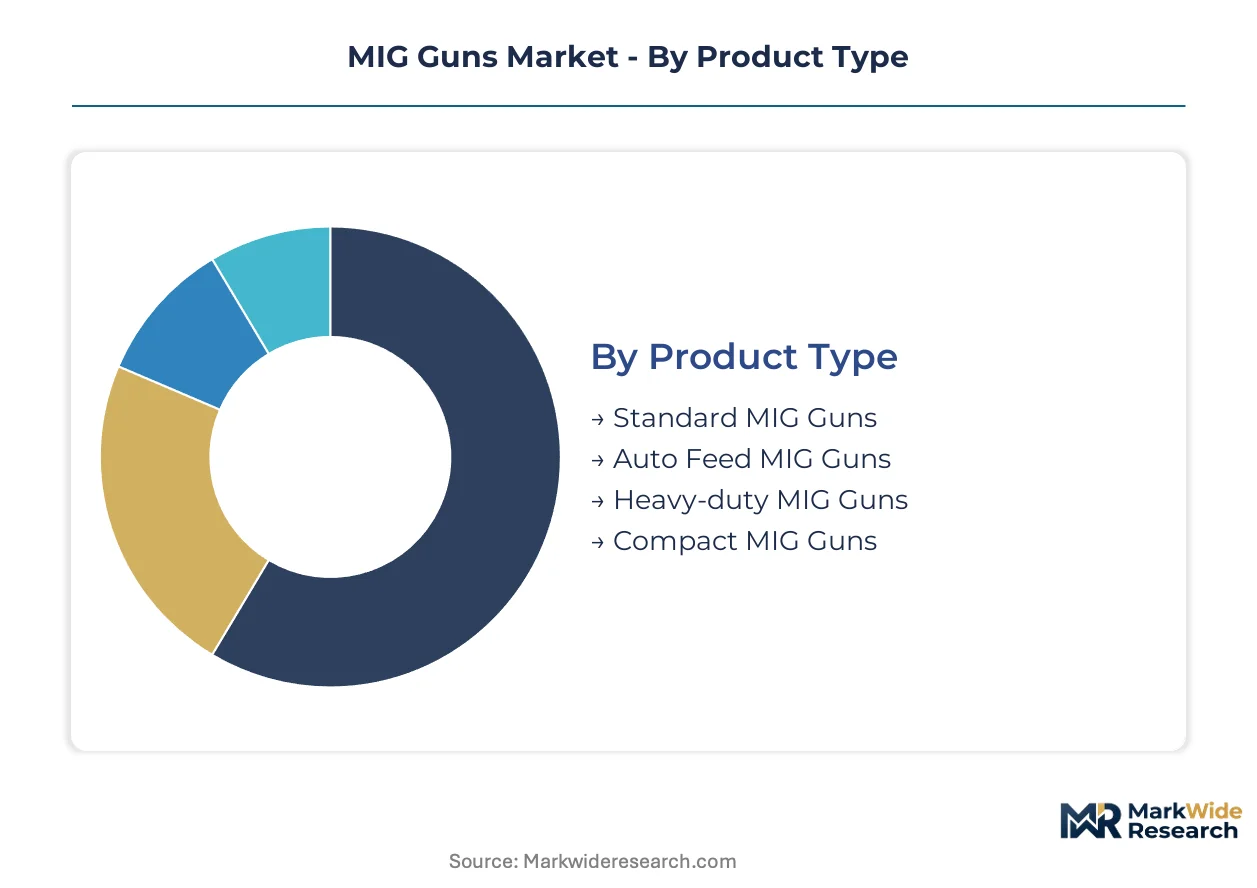
Segmentation in the MIG guns market reflects divergent buyer priorities across welding duty cycles, power source architectures, and end-use environments. Procurement decisions hinge on thermal management requirements, automation compatibility, and regulatory compliance rather than price alone.
Product Type:
Buyers select torch configurations based on continuous-duty demands and robotic integration requirements, with cooling method and amperage rating driving total cost of ownership calculations.
- Heavy-duty MIG Guns:Water-cooled designs rated for 400-600 amperes continuous duty dominate shipbuilding yards and structural steel fabrication in Germany and the United States. These systems command the largest installed base due to penetration in thick-plate environments where thermal load management determines equipment lifespan.
- Compact MIG Guns:Lightweight air-cooled configurations optimized for cobot welding cells are expanding most quickly in small-batch metal fabrication shops across Michigan and Lower Saxony. Their reduced mass enables faster torch articulation and lower robot payload requirements.
- Standard MIG Guns:General-purpose air-cooled torches serve maintenance and repair operations in mid-volume fabrication environments.
- Auto Feed MIG Guns:Integrated wire feed mechanisms reduce operator fatigue in high-deposition production lines.
Heavy-duty MIG guns lead on scale; compact MIG guns lead on momentum.
Technology:
Power source architecture determines waveform precision, energy efficiency, and portability trade-offs that reshape competitive positioning across fabrication sectors.
- Inverter Technology:IGBT-based systems deliver pulse and double-pulse waveform control essential for aluminum body-in-white welding at automotive OEMs in Germany and the United States. These units are displacing transformer architectures as fabricators prioritize energy efficiency and precise heat input management.
- Portable Technology:Compact inverter designs with generator compatibility serve remote construction sites and field repair operations where mains power is unavailable.
- Transformer Technology:Conventional copper-wound systems retain presence in cost-sensitive maintenance shops valuing durability over waveform sophistication.
- Mixed Technology:Hybrid architectures combine transformer robustness with inverter control elements for transitional upgrade paths.
Inverter technology leads on scale; portable technology leads on momentum.
End User:
End-use concentration determines specification intensity, with automotive procurement driving the most demanding performance benchmarks and compliance requirements.
- Automotive Manufacturers:OEM welding cells in Michigan, South Carolina, and Lower Saxony specify robotic MIG guns with integrated fume extraction and CE-UL dual certification. Aluminum-intensive vehicle architectures are expanding demand for specialized torch configurations optimized for non-ferrous thermal management.
- Shipbuilders:Korean and Chinese yards deploy heavy-duty water-cooled guns for thick-plate hull assembly requiring 600-ampere continuous duty ratings.
- Metal Fabricators:Job shops across Baden-Württemberg and Pune balance versatility against capital constraints in equipment selection.
- Construction Companies:Infrastructure contractors prioritize portability and generator compatibility for on-site structural welding.
Automotive manufacturers lead on scale; shipbuilders lead on momentum.
Application:
Application type dictates duty cycle intensity and consumable throughput, with assembly operations commanding the most sophisticated torch specifications.
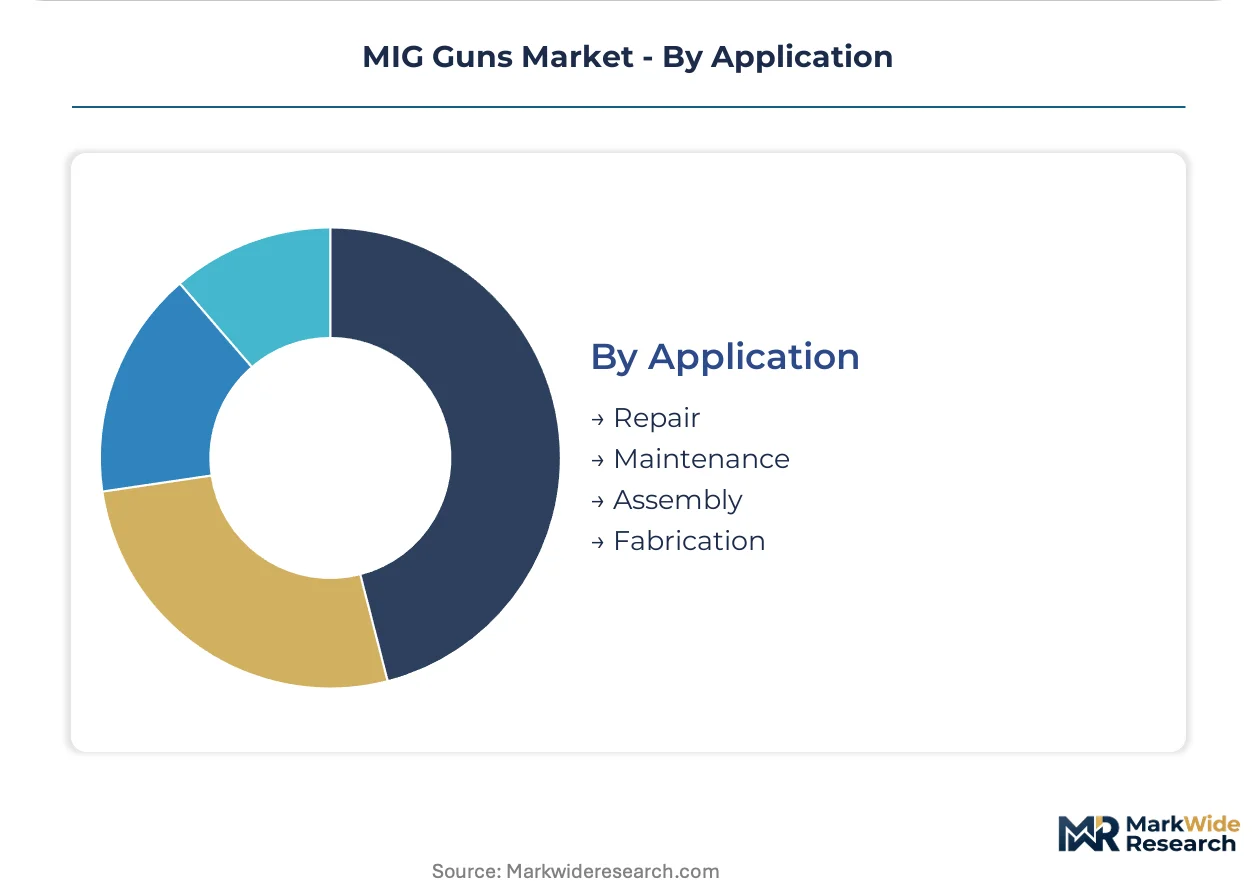
- Assembly:High-volume production lines at automotive OEMs and tier-one suppliers require robotic MIG guns with predictive maintenance telemetry and automated consumable replenishment. These environments compress replacement cycles and demand seamless cobot integration.
- Fabrication:Custom metalwork operations in industrial clusters near Chennai and Pune specify versatile torch configurations accommodating frequent changeovers between material thicknesses.
- Repair:Field service operations prioritize portability and quick-change consumable systems for downtime minimization.
- Maintenance:Facility upkeep teams favor standard-duty guns with broad spare parts availability for equipment longevity.
Assembly leads on scale; fabrication leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering clusters anchor MIG gun demand through automotive supplier networks and specialized machinery builders. Regional concentration reflects proximity to Stuttgart's OEM welding cell deployment and the EU Machinery Directive compliance mandates reshaping equipment procurement across European fabrication facilities.
United States
Automotive OEMs in Michigan and South Carolina compress replacement cycles through dense cobot welding cell deployment. OSHA manganese exposure limits for welding fumes accelerate extraction-integrated torch adoption across fabrication shops. The Southeast automotive corridor concentrates procurement volume among tier-one suppliers seeking CE-UL dual certification.
Germany
Lower Saxony's automotive body-in-white lines specify pulse-capable inverter systems for aluminum-intensive vehicle architectures. The EU Machinery Directive governs arc stability and operator safety interlocks for equipment sold across European metalworking facilities. Stuttgart and Wolfsburg industrial zones drive specification intensity for robotic MIG gun integration.
China
Shipbuilding yards in Dalian and Shanghai deploy heavy-duty water-cooled guns for thick-plate hull assembly requiring continuous duty ratings. MIIT industrial automation targets expand robotic welding penetration in automotive supplier parks. Yangtze River Delta fabrication clusters prioritize cost-competitive torch configurations for high-volume production lines.
India
PLI scheme incentives for capital goods manufacturing expand addressable demand for robotic MIG gun integration near Chennai and Pune. BIS certification requirements shape equipment selection criteria for domestic fabricators. Maharashtra and Tamil Nadu automotive supplier parks concentrate emerging procurement volume for cobot-compatible torch configurations.
South Korea
Hyundai and Kia welding cells in Ulsan specify high-amperage systems for steel-intensive vehicle platforms. KBA-equivalent automotive safety standards influence torch specification benchmarks for export-oriented production. Busan shipbuilding complexes sustain demand for heavy-duty water-cooled configurations in thick-plate environments.
MIG Guns Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cobot integration specialization and digital twin convergence. The vendor base stratifies across three maturity tiers: legacy welding equipment conglomerates with captive consumable manufacturing, mid-scale specialists in precision torch components, and regional fabricators serving cost-sensitive maintenance markets. Dominant competitive moves include backward integration into contact tip and nozzle production to control lead times, plus strategic partnerships with power source manufacturers for waveform-optimized system bundling.
Among Germany-based precision specialists, TBi Industries GmbH exemplifies the component-engineering archetype through its positioning in gas diffuser systems. Lincoln Electric anchors the integrated-systems tier with its captive manufacturing footprint across consumable torch elements. Panasonic Welding Systems occupies the robotic integration vector, representing the automation-centric configuration that automotive OEMs specify for body-in-white production lines.
| Leading Market Players |
|---|
| Lincoln Electric |
| TBi Industries GmbH |
| DINSE Inc. |
| Tokin Corporation |
| SUMIG USA Corporation |
| ESAB |
| Miller Electric |
| Panasonic Welding Systems |
| Fronius International |
| Others |
Value Network & Pricing Analysis
OSHA manganese exposure limits and EU Machinery Directive compliance mandates gate qualified supply and premium-tier pricing access for MIG gun manufacturers serving automotive and heavy fabrication segments. Buyers seeking CE-UL dual certification or extraction-integrated torch configurations face extended supplier qualification timelines that compress pricing elasticity for compliant product tiers.
Pricing Analysis
Copper and brass input volatility passes through to contact tip and nozzle pricing, squeezing margins for consumable-dependent revenue models. Three-tier pricing structure across premium, standard, and economy levels separates robotic integration-ready systems from maintenance-grade torches. Cost compression in standard air-cooled configurations is intensifying because of commodity metal price swings. Tier-one automotive OEMs exhibit lowest price sensitivity; small-batch metal fabricators in emerging supplier parks show highest sensitivity.
Supply Chain Analysis
CE marking and UL certification requirements gate supplier access to North American and European automotive welding cell procurement. Manufacturing clusters in Germany, China, and the United States anchor precision gas diffuser and torch neck production. Contact tips, nozzles, and brass gas diffusers draw from non-ferrous metal supply chains exposed to commodity cycles. Single-source vulnerability concentrates in Baden-Württemberg precision component manufacturing. Distribution runs through welding equipment distributors, though direct OEM supply arrangements are displacing traditional channels in Michigan and Lower Saxony.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the MIG guns market rests on inverter power source bundling and captive consumable manufacturing that captures replacement cycle value. Cobot welding cell proliferation creates premium-tier pricing power for compact torch configurations.
For Market Incumbents: Lock in robotic integration partnerships with automotive OEMs in Lower Saxony and Michigan to defend against laser welding substitution in battery tray assembly. Deepen captive supply of contact tips and nozzles to control lead times against commodity price volatility. Prioritize CE-UL dual certification investment to maintain access to transatlantic procurement volumes. For New Entrants and Emerging Players: Capture PLI scheme-driven demand in Tamil Nadu and Maharashtra automotive supplier parks where cobot-compatible torch specifications outpace established supplier capacity. Target small-batch fabrication shops migrating from transformer to inverter systems with portable technology configurations. Pursue power source manufacturer partnerships for waveform-optimized system bundling as primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for precision gas diffuser specialists because automotive OEM consolidation is compressing qualified supplier counts and extending contract durations. Five-to-ten year viability favors targets with inverter waveform optimization capabilities and established automotive tier-one relationships. Watch fume extraction mandate enforcement intensity across US fabrication shops as inflection indicator for extraction-integrated torch demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumables | Lincoln Electric's captive contact tip manufacturing controls lead times against copper price volatility. |
| Robotic Integration Partnership | Panasonic Welding Systems dominates automotive OEM body-in-white lines through cobot-native torch designs. |
| CE-UL Dual Certification Investment | Extended approval cycles for arc stability validation gate access to transatlantic automotive procurement. |
| Digital Twin Telemetry Integration | Welding data analytics platforms enable predictive maintenance contracts and consumable replenishment automation. |
| Regional Manufacturing Footprint Expansion | PLI scheme incentives in Tamil Nadu and Maharashtra expand addressable demand for robotic MIG gun suppliers. |
Research Methodology
Multiple input streams — executive interviews with welding equipment procurement leads, technical discussions with plant engineers at automotive tier-one suppliers, and validation sessions with aftermarket service heads — were reconciled against customs trade data, SEC filings from publicly traded welding equipment manufacturers, and OSHA enforcement records. Secondary sources included EU Machinery Directive implementation guidance, MIIT industrial automation policy documents, and BIS certification requirement updates. Bottom-up equipment shipment analysis and top-down fabrication sector spend estimates were triangulated to anchor volume and value outputs.
Data-stream reconciliation across product type, cooling method, power source technology, and end-use application dimensions shaped the analytical framework across the analysis window. CAGRs were derived from segment-level growth trajectory blending and cross-referenced against automotive production forecasts and shipbuilding orderbook data. Inverter displacement rates, cobot welding cell deployment curves, and fume extraction mandate compliance timelines served as industry-specific forecast inputs.
Copper price volatility, regulatory enforcement intensity shifts, and laser welding substitution acceleration in thin-gauge automotive applications are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding technology transition rates and procurement cycle compression. A model refresh is warranted upon material change in OSHA manganese exposure limit enforcement or EU Machinery Directive scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gear Honing Machines Market
Tools
Industrial Hand Tools Market
Tools
Belt File Sander Market
Tools
Entrenching Tool Market
Tools
Tool Setting Gauges Market
Tools
Press Machine Market
Tools
Crimping Tool Market
Tools
Orbital Sanders Market
Tools
Pneumatic Bolting Tools Market
Tools
Thread Milling Machine Market
Tools
Rebar Cutter Market
Tools
Global Protractor Market
Tools
Fastening Power Tools Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Floor Pads Market
Tools
Friction Washer Market