
 Global Protractor Market | 2026-2036
Global Protractor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protractor Market Outlook
Precision-grade calibration standards is unwinding legacy tolerance benchmarks across the measuring instrument sector. Starrett leverages its century-long metrology heritage to sustain premium positioning in North American industrial channels. Mitutoyo dominates Asian precision manufacturing markets with dense distributor networks and localized calibration services. Tesa differentiates through Swiss-engineered digital readout systems that target high-frequency quality assurance environments.
A protractor is an angular measurement instrument, typically graduated from 0 to 180 or 0 to 360 degrees, constructed from stainless steel, aluminum, or engineered polymers to achieve ±0.1 degree accuracy in professional grades; its primary commercial purpose spans mechanical engineering layout, architectural drafting, and educational geometry instruction. Digital protractors command widening margin pools as battery-powered electronic displays displace vernier-scale units in professional workflows. Stainless steel construction anchors the premium tier where machinists and metrology labs demand thermal stability and wear resistance. Plastic variants occupy high-volume educational channels where unit cost sensitivity overrides precision requirements.
FDA oversight of medical device manufacturing indirectly shapes protractor demand through ISO 13485 quality system requirements that mandate traceable angular measurement in surgical instrument fabrication. EPA guidelines on metal finishing chemicals affect stainless steel protractor production costs and supply chain configuration in the United States. REACH compliance in Europe restricts certain polymer additives used in low-cost plastic student models, elevating material specification thresholds for export-oriented manufacturers. Stakeholders must monitor how dual carbon goals in China and evolving extended producer responsibility frameworks in the European Union recalibrate material sourcing decisions and certification investments across the value chain.
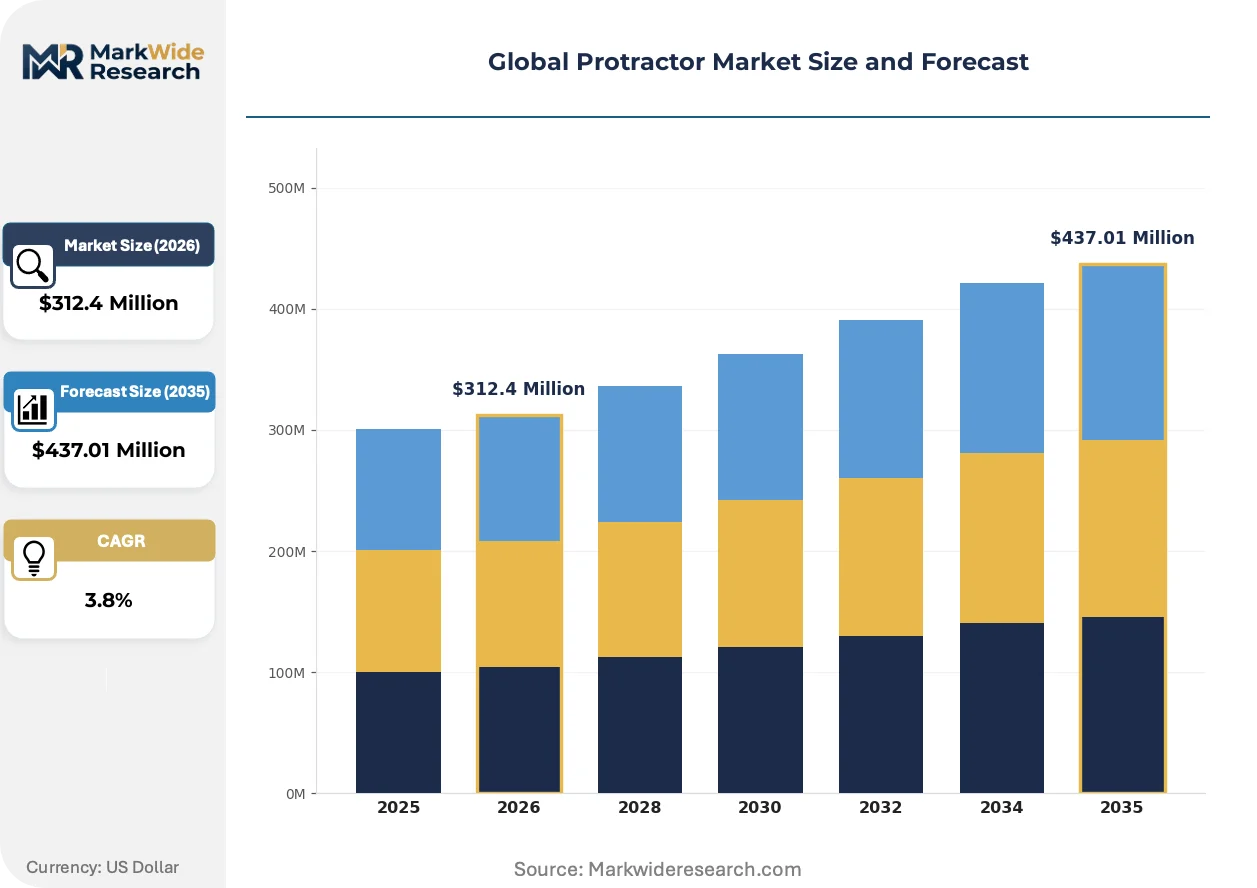
Market Dynamics
The transition from analog vernier scales to battery-powered digital displays is restructuring protractor procurement across precision manufacturing and educational channels, compressing replacement cycles and elevating calibration service attach rates.
Growth Catalysts
- Vocational Training Expansion:China's Ministry of Education has mandated upgraded technical drawing curricula in secondary schools, institutionalizing digital protractor procurement at provincial tender scales.
- REACH Polymer Compliance:ECHA restrictions on phthalate additives in student-grade plastics are forcing material upgrades that incidentally improve durability and reduce warranty claims.
- ISO 13485 Traceability Mandates:Surgical instrument manufacturers in FDA-regulated supply chains now require calibrated angular measurement, embedding protractors into medical device quality systems.
Market Restraints
- Aluminum Price Volatility:Recycled aluminum feedstock costs fluctuate with EU Green Deal sourcing requirements, squeezing margin on mid-grade industrial protractors.
- Calibration Infrastructure Concentration:Accredited metrology labs cluster in Germany, Japan, and the United States, creating logistics friction for Southeast Asian and Latin American end-users.
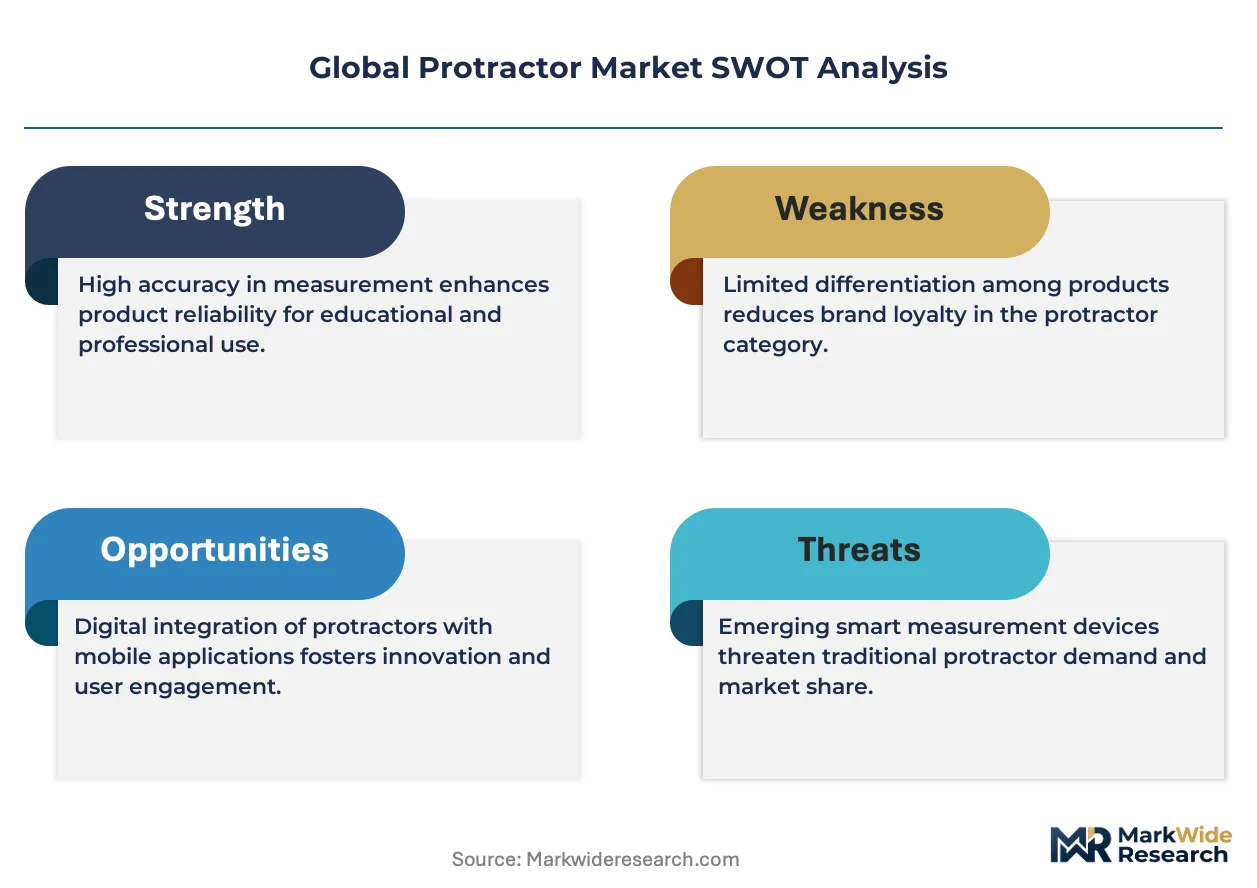
- Smartphone App Substitution:Free gyroscope-based angle measurement applications satisfy casual users, capping addressable market expansion in consumer segments.
Strategic Opportunities
- Vietnam Manufacturing Uptake:Electronics assembly migration from China is generating fresh demand for precision layout tools in Ho Chi Minh City and Bac Ninh industrial zones.
- EU AI Act Quality Documentation:Automated manufacturing systems require auditable angular measurement records, positioning connected digital protractors as compliance infrastructure.
- Direct-to-Technical-School Distribution:Bypassing traditional industrial distributors to sell calibrated kits directly to vocational programs captures recurring calibration revenue streams.
Industry Challenges
- Metrology Technician Scarcity:Calibration certification programs in India and Brazil graduate insufficient technicians to service expanding industrial installed bases.
- Dual Carbon Compliance Timelines:Chinese manufacturers face compressed deadlines to transition energy-intensive aluminum smelting to renewable sources without disrupting cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protractor Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Protractors, Digital Protractors, Adjustable Protractors, Circular Protractors Material: Plastic, Stainless Steel, Aluminum, Wood End User: Students, Architects, Engineers, Hobbyists Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Starrett, Mitutoyo, Tesa, Bocchi, Moore & Wright, Stabila, SOLA, Winton Machine Company, Mahr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protractor Market Strategic Shifts
Electronic angle measurement is fragmenting traditional product categories while regulatory documentation requirements and procurement centralization reshape how buyers source and validate angular instruments.
Bluetooth-enabled digital protractors with data-logging capability are displacing standalone units in quality-assurance environments where ISO 9001 audit trails require timestamped measurement records. Automotive tier-one suppliers in Stuttgart and Detroit have adopted these devices at scale since 2023. The technology is displacing manual transcription workflows and reducing gage R&R variation in statistical process control.
REACH Annex XVII restrictions on short-chain chlorinated paraffins in metalworking fluids are altering stainless steel protractor finishing processes, forcing suppliers to adopt aqueous cleaning systems or ceramic blasting. German and Polish manufacturers report 8-12 month qualification periods for alternative surface treatments. Medical device subcontractors in Ireland and Switzerland face the steepest compliance cost escalation given their low-volume, high-mix production profiles.
Consolidated procurement through industrial distributors is giving way to manufacturer-direct relationships for calibrated instrument bundles. German automotive OEMs now specify accredited calibration certificates at point of purchase rather than accepting post-delivery third-party service. This pattern is most pronounced in Bavaria and Baden-Württemberg, where supplier quality agreements embed metrology traceability into component approval workflows.
Global Protractor Market Segmentation
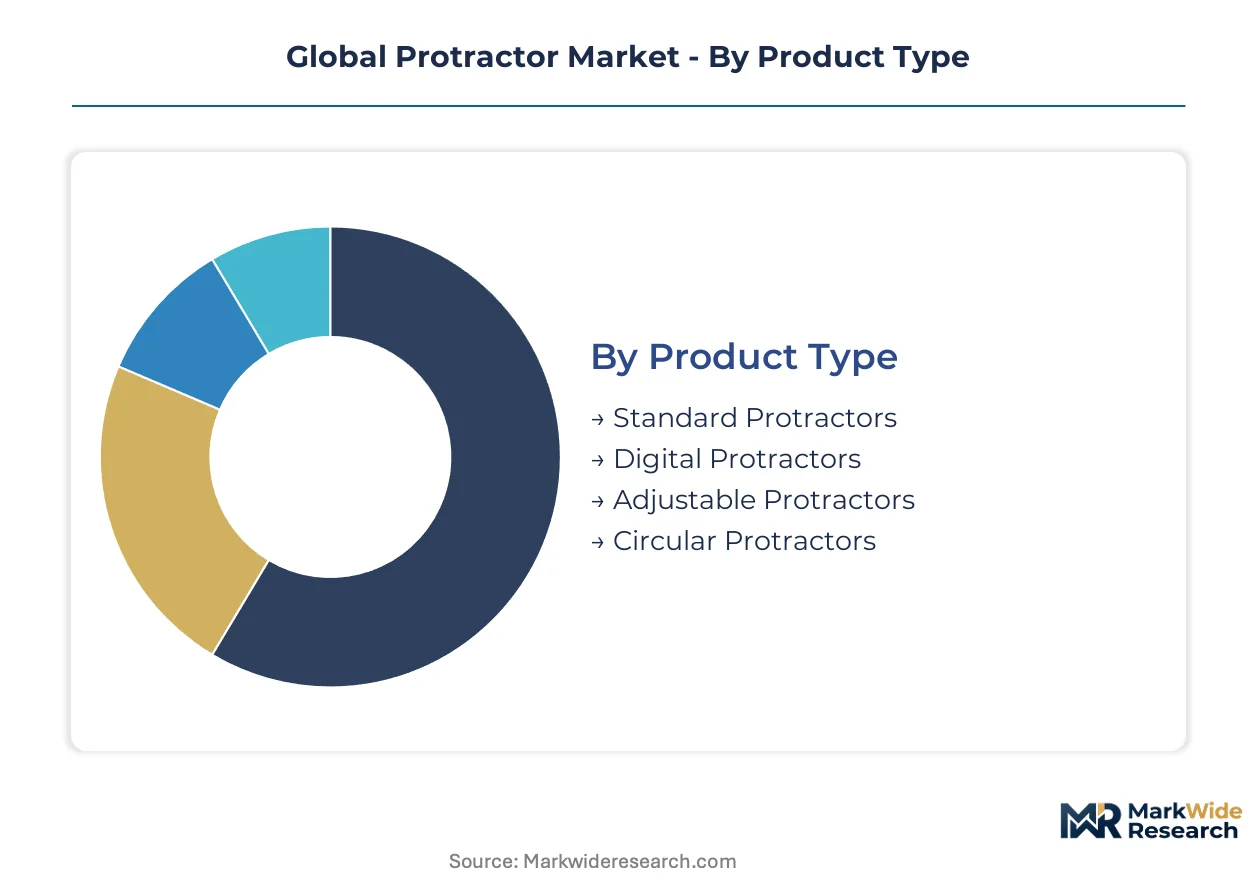
Protractor procurement patterns diverge sharply across material grades, digital capability, and end-use certification requirements. Understanding these segment boundaries clarifies where margin pools concentrate and which specifications command premium positioning.
Product Type:
REACH Annex XVII restrictions on phthalate additives and FDA traceability mandates for surgical instrument fabrication create divergent compliance burdens across analog and electronic formats.
- Standard Protractors:Vernier-scale instruments constructed from stamped metal or molded polymers dominate educational procurement in China and Southeast Asia. China's Ministry of Education provincial tenders institutionalize volume purchases for secondary technical drawing curricula, though REACH polymer upgrades are elevating material costs for export-bound manufacturers.
- Digital Protractors:Battery-powered electronic displays with ±0.05 degree resolution anchor quality assurance workflows in automotive and medical device manufacturing. Stuttgart and Detroit automotive tier-one suppliers have adopted Bluetooth-enabled data-logging variants since 2023 to satisfy ISO 9001 audit trail requirements.
- Adjustable Protractors:Articulating arm designs with locking mechanisms serve machinists and layout technicians in metal fabrication shops.
- Circular Protractors:Full 360-degree graduated discs target specialized surveying and astronomical instrument calibration applications.
Established volume favors Standard Protractors; emerging adoption favors Digital Protractors.
Material:
Cost tier stratification aligns with thermal stability demands and regulatory exposure across industrial versus educational channels.
- Stainless Steel:Austenitic grades deliver thermal expansion coefficients below 17 μm/m·K for metrology lab environments. FDA-regulated surgical instrument manufacturers in Ireland and Switzerland specify these for ISO 13485 traceable angular measurement, though REACH restrictions on chlorinated paraffin finishing fluids have extended qualification timelines.
- Aluminum:Recycled 6061-T6 alloy balances weight and machinability for mid-grade industrial protractors. EU Green Deal sourcing requirements for recycled content are squeezing margin as feedstock costs fluctuate with energy-intensive smelting transitions.
- Plastic:ABS and polycarbonate variants occupy high-volume student channels where unit cost sensitivity overrides precision requirements; ECHA phthalate restrictions are forcing bio-based polymer migrations.
- Wood:Traditional beech and maple constructions persist in artisanal woodworking and heritage craft instruction settings.
Margin concentration sits with Stainless Steel; volume scale concentrates in Plastic.
End User:
Application maturity separates specification-intensive professional workflows from price-sensitive institutional procurement.
- Engineers:Mechanical and civil engineering practices demand calibrated instruments with NIST-traceable or DAkkS-accredited certificates, particularly in Bavarian automotive supplier quality agreements.
- Architects:Technical drafting and building information modeling workflows favor digital protractors with direct CAD input capability.
- Students:Secondary and vocational programs in China, Vietnam, and Indonesia drive bulk procurement of plastic and basic metal vernier models.
- Hobbyists:Maker and DIY segments exhibit price elasticity and susceptibility to smartphone gyroscope app substitution.
Specification rigor peaks with Engineers; shipment volume concentrates with Students.
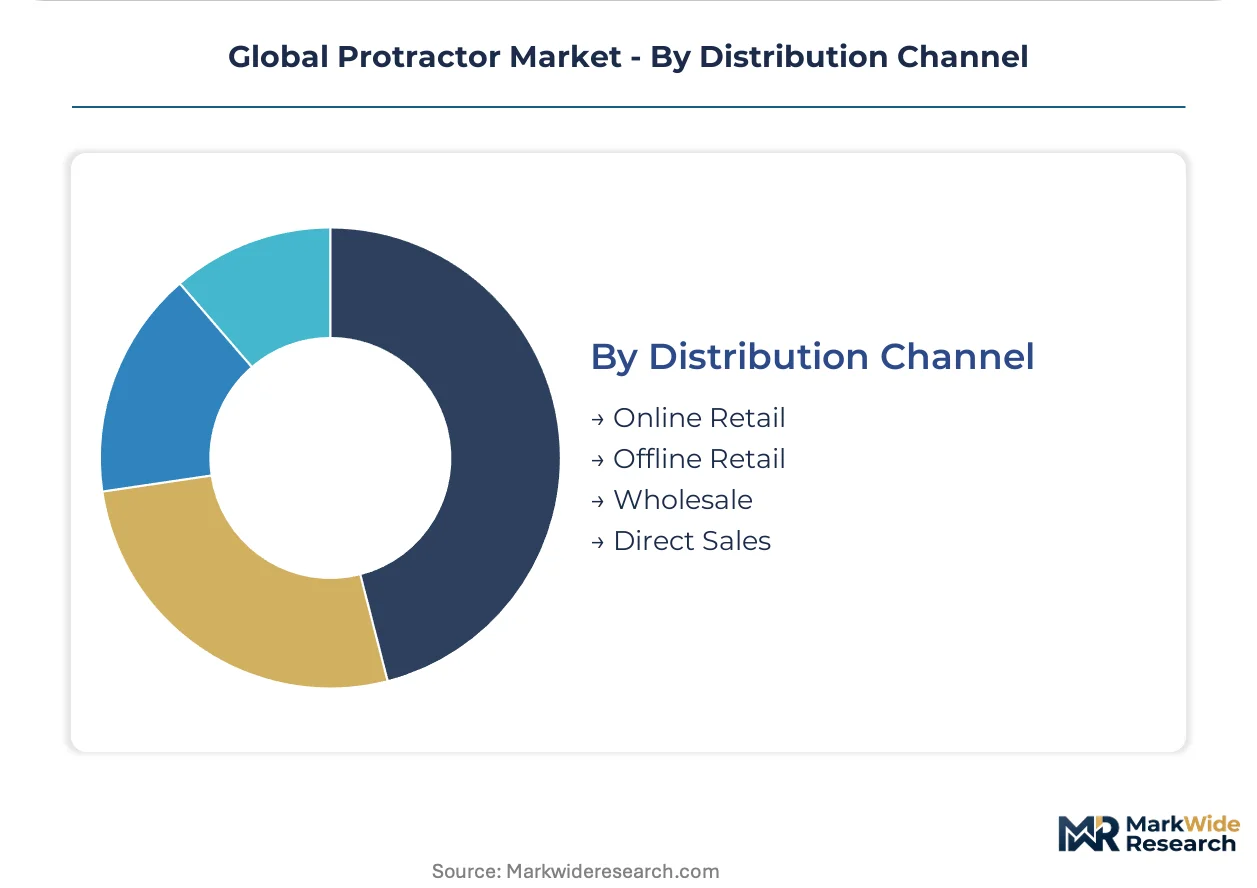
Distribution Channel:
Customer type and calibration requirements are restructuring traditional industrial distributor relationships toward direct manufacturer engagement.
- Direct Sales:German automotive OEMs now specify accredited calibration certificates at point of purchase, bypassing post-delivery third-party service and embedding metrology traceability into component approval workflows.
- Wholesale:Industrial distributors remain relevant for uncalibrated instrument bundles in metalworking and general manufacturing.
- Online Retail:E-commerce platforms capture hobbyist and student segments with price-transparent comparison shopping.
- Offline Retail:Stationery and specialty tool stores serve immediate-need procurement in urban centers.
Service attach rates favor Direct Sales; price competition concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protractor manufacturing clusters concentrate in Germany, Japan, and the United States where metrology infrastructure and precision engineering ecosystems sustain premium production. Demand dispersion follows vocational training expansion in Asia-Pacific and automotive supplier quality mandates in Europe.
China
Vocational enrollment growth and infrastructure drafting activity drive procurement volume. The Ministry of Education mandates upgraded technical drawing curricula in secondary schools, institutionalizing digital protractor procurement at provincial tender scales. Yangtze River Delta manufacturers face compressed dual carbon compliance timelines for aluminum smelting transitions.
Germany
Automotive tier-one suppliers in Stuttgart and Bavaria specify accredited calibration certificates at point of purchase. REACH Annex XVII restrictions on chlorinated paraffin finishing fluids extend qualification periods for stainless steel surface treatments. Baden-Württemberg supplier quality agreements embed metrology traceability into component approval workflows.
United States
FDA-regulated surgical instrument manufacturers require ISO 13485 traceable angular measurement for quality systems. EPA guidelines on metal finishing chemicals affect stainless steel production costs and supply chain configuration. Detroit automotive suppliers adopted Bluetooth-enabled data-logging protractors since 2023 to satisfy ISO 9001 audit requirements.
Japan
Precision manufacturing markets sustain dense distributor networks with localized calibration services. METI industrial standards support metrology lab accreditation infrastructure concentrated in Tokyo and Osaka clusters. Automotive and electronics assembly quality assurance drives digital protractor adoption with ±0.05 degree resolution specifications.
Vietnam
Electronics assembly migration from China generates fresh demand for precision layout tools in Ho Chi Minh City and Bac Ninh industrial zones. Technical training institutions expand geometry instruction curricula. Local procurement concentrates through industrial distributors serving foreign-invested manufacturing facilities.
Global Protractor Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the protractor market structure. Premium-grade digital instruments with calibration traceability concentrate among established metrology specialists, while high-volume educational procurement flows to scaled polymer fabricators. Two strategic archetypes dominate: heritage precision instrument makers leveraging century-long calibration reputations, and diversified measurement tool portfolios serving automotive quality assurance channels. Competitive moves center on backward integration into aluminum smelting for EU Green Deal compliance and direct-to-technical-school distribution bypassing traditional industrial channels.
Among heritage metrology specialists, Starrett exemplifies premium positioning sustained through North American industrial channel relationships. Mitutoyo occupies a position as a representative of Asian precision manufacturing market density with localized service infrastructure. Tesa anchors the Swiss-engineered digital readout segment targeting high-frequency quality assurance environments. These three entities collectively represent the technology-tier archetype where calibration heritage and electronic measurement capability determine competitive position.
| Leading Market Players |
|---|
| Starrett |
| Mitutoyo |
| Tesa |
| Bocchi |
| Moore & Wright |
| Stabila |
| SOLA |
| Winton Machine Company |
| Mahr |
| Others |
Value Chain & Pricing Dynamics
Long-term calibration service contracts lock in supply access for accredited digital protractors while anchoring price visibility for German automotive OEMs and FDA-regulated surgical instrument manufacturers. These arrangements compress margin volatility for metrology specialists who bundle ISO 17025 certificates at point of purchase.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the European procurement landscape, forcing material upgrades that separate stainless steel metrology-grade instruments from plastic educational variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal stability specifications. Cost compression in mid-grade aluminum segments intensifies because EU Green Deal recycled content mandates elevate feedstock expenses. Students exhibit highest price sensitivity, while engineers purchasing for ISO 13485 traceability demonstrate minimal elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as aluminum smelters and polymer compounders buffer against EU carbon border adjustment timelines. Manufacturing concentrates in Germany, Japan, and China where metrology lab density supports calibration infrastructure. Production draws from austenitic stainless steel feedstock, recycled 6061-T6 aluminum, and bio-based ABS polymers. Single-source vulnerability concentrates in Swiss-engineered digital readout components. Distribution runs through industrial distributors for uncalibrated bundles and direct manufacturer relationships for certified instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protractor market sits in early-cycle recovery driven by vocational training procurement waves across Southeast Asia and China's Ministry of Education tender programs.
For Market Incumbents: Fortify calibration service attach rates by embedding ISO 17025 certificates into provincial educational tenders before competitors replicate direct-to-school distribution. Secure captive supply of recycled aluminum feedstock through backward integration into EU-sourced smelting partnerships to defend margin against Green Deal cost volatility. Threat substitution from smartphone gyroscope applications demands specification escalation toward Bluetooth-enabled data-logging variants. For New Entrants and Emerging Players: Differentiate on calibration infrastructure proximity by establishing accredited service partnerships in Vietnam and Indonesia where metrology technician scarcity creates service gaps. White-space targets include Ho Chi Minh City electronics assembly zones and Indonesian vocational technical institutes. Go-to-market angle emphasizes rapid certificate turnaround versus German and Japanese incumbent lead times. For Investors and Strategic Acquirers: The market sits at an infrastructure-build phase that favors calibration-capable specialists with established distributor relationships. Long-term viability hinges on regulatory documentation requirements deepening across automotive and medical device quality systems. Acquisition archetype targets mid-tier digital protractor manufacturers with latent calibration accreditation. Signal to watch is EU AI Act quality documentation mandates accelerating connected instrument adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Accredited service partnerships in Vietnam and Indonesia address metrology technician scarcity. |
| Backward Integration into Recycled Aluminum | Captive EU Green Deal-compliant feedstock secures margin stability for mid-grade industrial protractors. |
| Direct-to-Technical-School Distribution | Bypassing industrial distributors captures recurring calibration revenue from China's provincial tenders. |
| Bluetooth-Enabled Data-Logging Development | ISO 9001 audit trail compliance positions devices in Stuttgart and Detroit automotive supplier workflows. |
| Bio-Based Polymer Migration | ECHA phthalate restriction compliance opens REACH-certified export channels for educational variants. |
Study Parameters
Initial hypotheses were tested against primary input from metrology lab directors, vocational training procurement officers, automotive supplier quality engineers, and industrial distributor category managers and refined through secondary validation against METI industrial standards documentation, ECHA restriction entry databases, FDA 510(k) submission records, and Chinese provincial tender archives. Bottom-up shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, material grade, end-user certification requirement, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by procurement volume concentration. Industry-specific forecast inputs incorporated dual carbon compliance timeline acceleration and REACH Annex XVII restriction phase-in schedules.
Forecasts assume regulatory continuity in EU REACH, FDA ISO 13485 enforcement, and Chinese vocational curriculum mandates; material policy shifts would require re-modeling. Specific risks include aluminum price volatility from renewable smelting transitions and smartphone app substitution acceleration in consumer segments. Revision becomes warranted when Bluetooth-enabled protractor adoption in automotive quality assurance crosses threshold penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Forging Press Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Foam Cutting Machine Market
Tools
3D Milling Machines Market
Tools
Drill Bit Market
Tools
Rivet Busters Market
Tools
Deburring Tool Market
Tools
Global Diamond Tools Market
Tools
Land Survey Equipment Market
Tools
Level Floats Market
Tools
Tool Hammer Market
Tools
Global Table Saws Market
Tools
Laser Engraving Machine Market
Tools
GCC Machine Tools Market
Tools
Automatic Heat Press Machines Market
Tools
Surface Planer Market