
 Spindle Shaper Market | 2026-2036
Spindle Shaper Market Size, Share, and Industry Trends Forecast 2026-2036
Spindle Shaper Market Analytics
Chinese CNC machinery clusters in Shandong and Jiangsu provinces are recalibrating export capacity toward precision woodworking equipment. SCM Group leverages its Italian engineering heritage to sustain premium positioning in European furniture manufacturing lines. Felder Group anchors its competitive stance through integrated dust-collection systems and training academy networks. WEINIG Group differentiates via high-frequency spindle technology and automated profile grinding compatibility.
A spindle shaper is a stationary woodworking machine employing a vertically oriented rotating spindle (typically 25–50 mm diameter, 3,000–10,000 RPM) to shape edges, cut profiles, and form joints on solid wood and panel stock. The machine feeds workpieces against profiled cutter heads for molding, rabbeting, and tenoning operations in cabinet and furniture production. Table-mounted configurations dominate commercial installations where fixed-shop precision outweighs mobility requirements, while portable units occupy the renovation-contractor segment with reduced setup time. Electric drive technology leads volume shipments, though pneumatic variants retain share in high-humidity Southeast Asian mills where motor sealing costs escalate.
CE marking under the EU Machinery Directive and OSHA lockout/tagout standards in the United States enforce spindle guard interlocks and emergency braking thresholds, elevating compliance costs for entry-tier suppliers. China's GB standards for woodworking machinery safety, administered by SAMR, mandate noise limits and residual run-down times that reshape product development priorities for domestic manufacturers. Buyers must weigh total cost of ownership across retrofit compatibility, energy efficiency certifications, and regional service network density when selecting equipment platforms.
Market Dynamics
Precision demands from German and Italian furniture manufacturers are compressing tolerances for spindle speed stability and cutter alignment, forcing equipment suppliers to recalibrate engineering priorities around automated feedback systems rather than manual adjustment protocols.
Growth Catalysts
- EU Machinery Directive CE marking:Mandatory spindle guard interlocks and emergency braking thresholds are creating replacement cycles for non-compliant legacy equipment across woodworking facilities.
- CNC woodworking clusters in Shandong:Concentrated supplier ecosystems in China's Jiangsu province are achieving scale economies that lower unit costs for precision spindle systems exported to Southeast Asian mills.
- High-frequency spindle technology:Adoption of automated profile grinding compatibility is reducing setup times for custom molding operations in European cabinet production lines.
Market Restraints
- Copper and rare-earth magnet costs:Electric drive motor components face input price volatility that compresses margin structures for mid-tier spindle shaper manufacturers.
- Single-source dependence on German spindle bearing suppliers:Concentrated precision component sourcing creates vulnerability to supply interruptions for high-RPM machine configurations.
- Pneumatic variant sealing limitations:Motor protection costs in high-humidity Southeast Asian environments restrict electric drive substitution in tropical mill operations.
Strategic Opportunities
- Underpenetrated Vietnamese furniture export sector:Rising FDI in wood processing creates demand for precision edge-shaping equipment that meets EU import standards.
- Integrated dust-collection system bundling:Training academy networks combined with extraction technology packages differentiate full-service suppliers from component vendors.
- China's dual carbon goals:Energy efficiency certifications for woodworking machinery are creating procurement preferences that favor variable-frequency drive spindle systems.
Industry Challenges
- CNC programming and maintenance technician scarcity:Furniture manufacturers face recruitment gaps for operators capable of integrating automated spindle shapers with shop-floor management software.
- GB standard certification timelines:China's SAMR noise limit and residual run-down testing protocols extend product launch schedules for domestic equipment releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spindle Shaper Market |
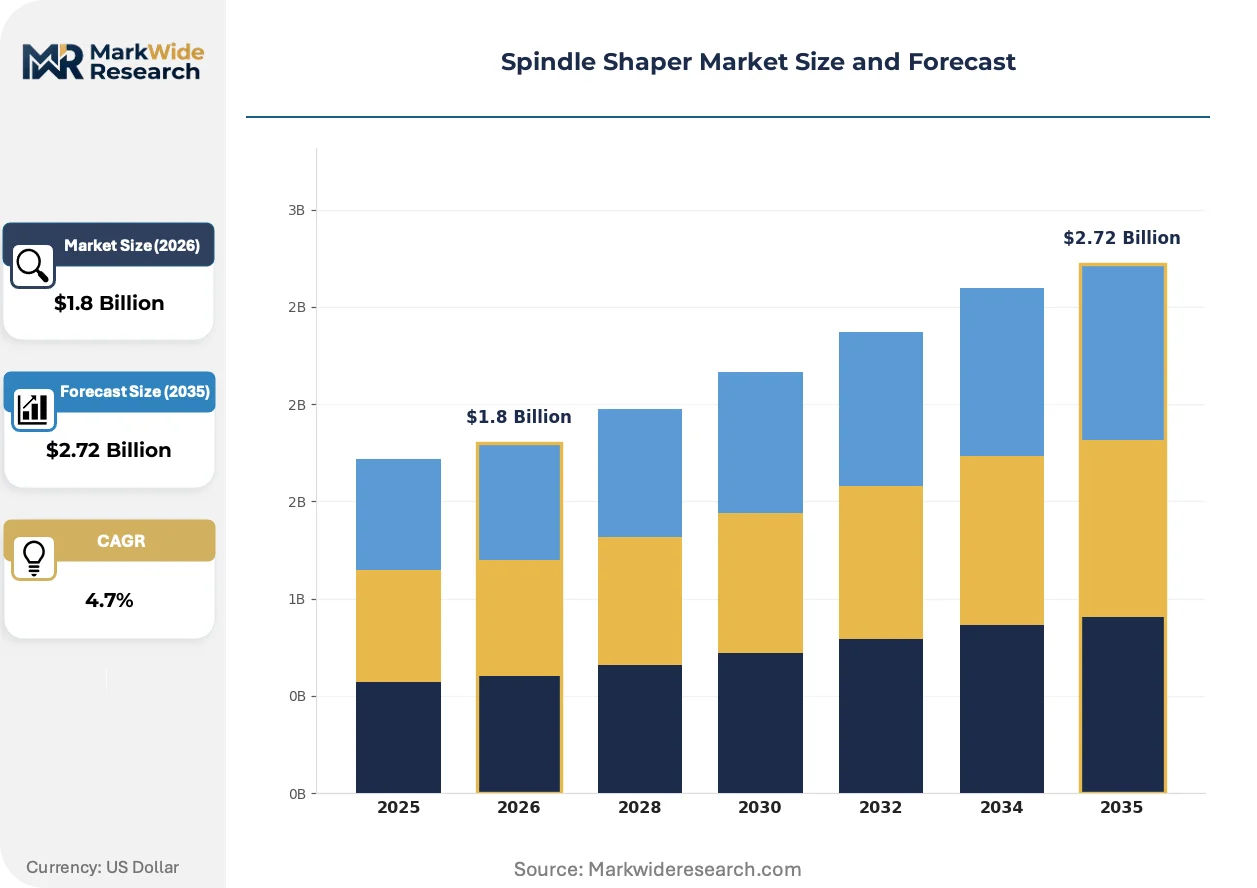
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table-mounted, Portable, Vertical, Horizontal End User: Woodworking Shops, Furniture Manufacturers, Cabinet Makers, DIY Enthusiasts Technology: Electric, Pneumatic, Hydraulic, Manual Management Type: Standalone, Integrated, Customizable, Automated |
| Companies Covered | Qingdao Zhongding Machinery, Jaya International, Shandong Guandiao CNC, Shanghai Win Star, SCM Group, Felder Group, Martin, Format-4, WEINIG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spindle Shaper Market Evolving Landscape
Woodworking machinery is undergoing a hardware-software convergence where spindle systems become nodes in connected factory architectures rather than isolated cutting stations. This shift is compressing the competitive window for suppliers lacking digital integration capabilities.
High-frequency spindle technology is electrifying precision woodworking operations through direct-drive configurations that eliminate belt transmission losses and vibration. German furniture manufacturers are adopting these systems at accelerated rates for complex profile replication. The technology is electrifying competitive positioning by enabling tolerances that manual-adjustment spindles cannot match, forcing tier-two suppliers toward obsolescence or partnership.
OSHA lockout/tagout enforcement in the United States is tightening compliance verification for spindle guard interlock functionality during maintenance operations. Industrial consequence includes mandatory documented testing protocols that extend service intervals and increase total cost of ownership calculations. Metalworking and woodworking job shops in the Midwest are responding by consolidating supplier relationships toward vendors with certified field service networks.
Buyer concentration among large-format furniture exporters is compressing procurement cycles and demanding outcome-based performance guarantees rather than equipment specifications alone. Distributor networks in China's Pearl River Delta are being displaced by direct manufacturer engagement with provincial purchasing consortia. This pattern is most visible in Jiangsu province, where state-backed woodworking machinery cooperatives negotiate volume contracts that bypass traditional equipment dealers.
Spindle Shaper Market Segmentation
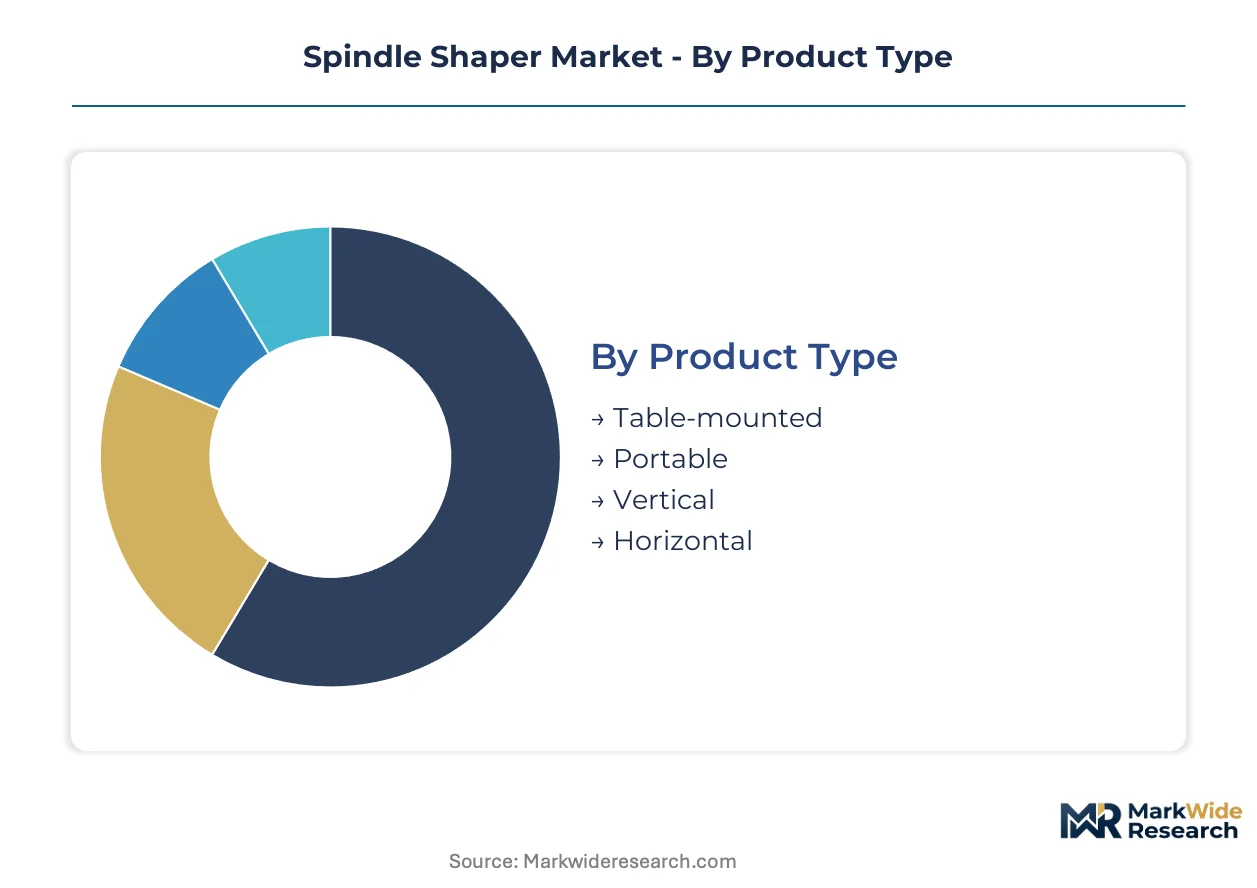
Spindle shaper procurement patterns diverge sharply between high-volume furniture manufacturing lines and precision-focused artisan workshops. Equipment specification, automation level, and powertrain technology selection all track to end-use scale and regulatory environment rather than price sensitivity alone.
Product Type:
Table-mounted configurations command premium positioning through fixed-shop precision, while portable units compete on setup velocity for renovation contractors.
- Table-mounted:Stationary installations with cast-iron tables and precision fence systems dominate German and Italian furniture manufacturing lines. CE marking compliance for spindle guard interlocks and emergency braking thresholds concentrates demand among large-format exporters seeking automated feedback integration.
- Portable:Compact units with reduced mass and quick-release fences serve Southeast Asian mill renovation cycles and on-site custom installation work. Motor sealing limitations in high-humidity environments restrict electric drive penetration, preserving pneumatic variant share.
- Vertical:Spindle orientation perpendicular to the work surface enables complex joinery and raised-panel operations in cabinet production.
- Horizontal:Side-mounted spindle configurations accommodate specialized molding and edge-shaping workflows in architectural millwork shops.
Mature deployment sits with table-mounted systems in European furniture manufacturing corridors. Newer deployment is concentrated in portable units serving Vietnam's expanding wood processing FDI.
End User:
Scale of operation determines automation tier and service network requirements, with large manufacturers consolidating procurement through direct manufacturer engagement.
- Woodworking Shops:Independent craft operations prioritize retrofit compatibility and training academy access over maximum spindle speed. Procurement runs through regional distributor networks with certified field service capabilities.
- Furniture Manufacturers:High-volume exporters in China's Jiangsu province negotiate volume contracts through state-backed machinery cooperatives. GB standard certification timelines from SAMR reshape product launch schedules for domestic equipment releases.
- Cabinet Makers:Mid-scale production lines demand integrated dust-collection bundling and CNC programming support.
- DIY Enthusiasts:Hobbyist segments drive entry-tier electric drive shipments with reduced safety interlock specifications.
Procurement consolidation is accelerating among furniture manufacturers. Woodworking shops retain fragmented purchasing patterns with higher distributor dependence.
Technology:
Powertrain selection tracks regional humidity conditions and energy efficiency certification requirements rather than performance specifications alone.
- Electric:Variable-frequency drive configurations dominate volume shipments, with China's dual carbon goals creating procurement preferences for certified efficient systems. Copper and rare-earth magnet input costs compress margin structures for mid-tier suppliers.
- Pneumatic:Compressed-air powertrains retain defensive positioning in tropical Southeast Asian mills where motor sealing costs escalate. OSHA lockout/tagout enforcement in the United States tightens compliance verification for maintenance operations.
- Hydraulic:Fluid-power systems serve specialized high-torque applications in heavy timber processing.
- Manual:Hand-cranked configurations persist in heritage restoration and educational training environments.
Electric systems are gaining share fastest in European and Chinese markets with tightening efficiency mandates. Pneumatic deployment defends its position in high-humidity zones.
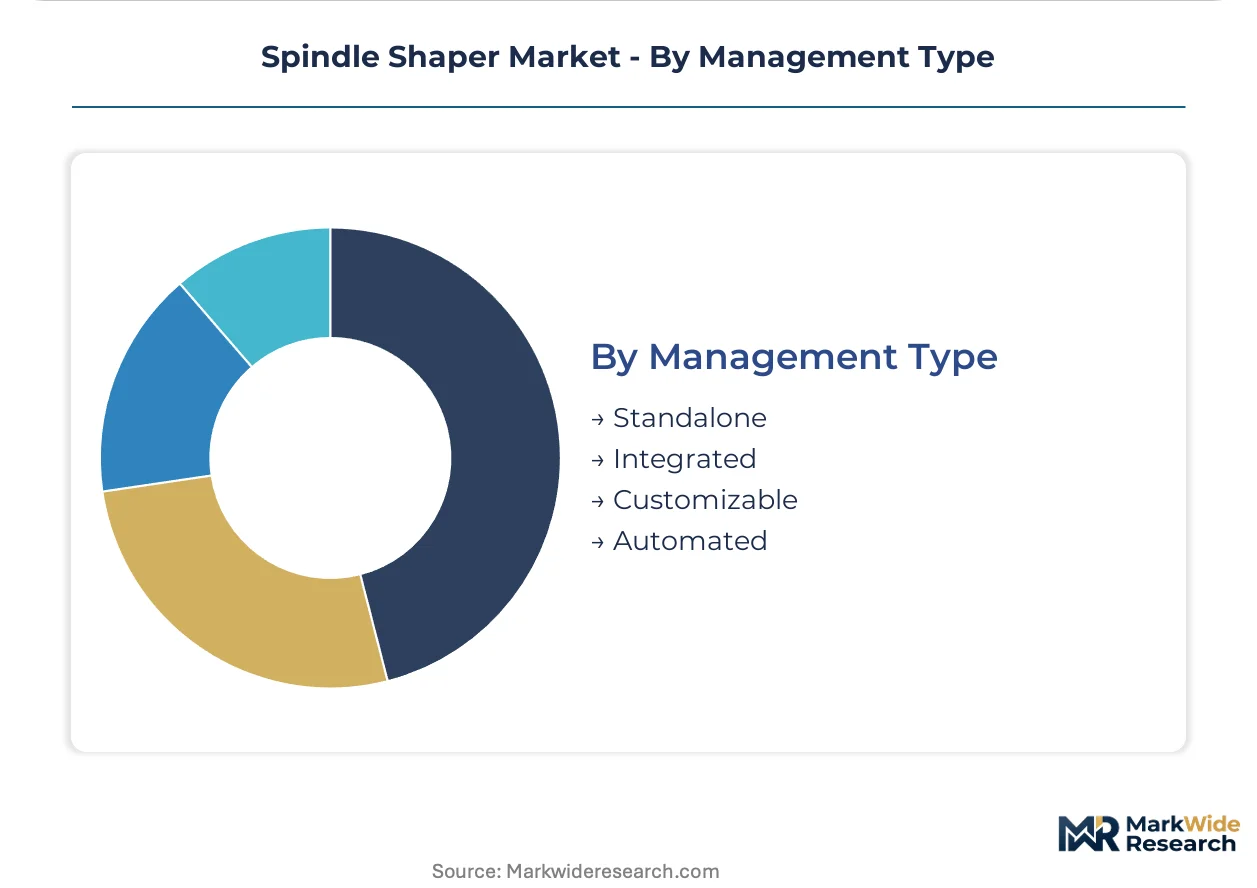
Management Type:
Control architecture determines integration depth with shop-floor management software and connected factory architectures.
- Standalone:Operator-dependent systems without external connectivity serve cost-sensitive entry tiers and legacy facility retrofits.
- Integrated:Networked spindle systems functioning as nodes in factory architectures are compressing competitive windows for suppliers lacking digital capabilities. German manufacturers are adopting these configurations at accelerated rates.
- Customizable:Modular programming interfaces accommodate small-batch custom molding operations.
- Automated:Feedback-loop systems with automated profile grinding compatibility reduce setup times in complex replication workflows.
Standalone management persists in artisan woodworking shops. Automated deployment is climbing the fastest in large-format furniture export lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision bearing clusters and Italian furniture manufacturing corridors anchor European spindle shaper engineering standards. Chinese CNC machinery ecosystems in Shandong and Jiangsu provinces reshape cost structures for precision woodworking equipment.
Germany
Baden-Württemberg and North Rhine-Westphalia host precision spindle bearing suppliers that constrain global high-RPM machine configurations. CE marking under the EU Machinery Directive enforces emergency braking thresholds and spindle guard interlocks that elevate compliance costs for non-compliant legacy equipment. Stuttgart's industrial belt concentrates automated feedback system development for furniture manufacturing lines.
China
Jiangsu province's state-backed woodworking machinery cooperatives negotiate volume contracts that bypass traditional equipment dealers. GB standards administered by SAMR mandate noise limits and residual run-down times that reshape domestic product development priorities. Shandong's CNC woodworking clusters supply precision spindle systems to Southeast Asian export markets at compressed unit costs.
Italy
Emilia-Romagna and Lombardy furniture manufacturers compress tolerances for spindle speed stability and cutter alignment through automated adoption. CE marking compliance creates replacement cycles for legacy equipment across woodworking facilities. SCM Group leverages Italian engineering heritage from its Rimini base to sustain premium positioning in European production lines.
United States
Midwest metalworking and woodworking job shops consolidate supplier relationships toward vendors with certified field service networks. OSHA lockout/tagout enforcement tightens compliance verification for spindle guard interlock functionality during maintenance operations. Michigan and Ohio industrial corridors demand documented testing protocols that extend service intervals and increase total cost of ownership calculations.
Vietnam
Rising FDI in wood processing from export-oriented furniture manufacturers creates demand for precision edge-shaping equipment meeting EU import standards. The country's national industrial regulator enforces machinery safety protocols aligned with export market requirements. Ho Chi Minh City and Binh Duong province clusters absorb Chinese-origin CNC spindle systems for integration into regional supply chains.
Spindle Shaper Market Competitive Landscape
Global majors compete with regional champions across technology tiers and service network density. The vendor base stratifies between precision engineering specialists with automated feedback integration and cost-optimized fabricators serving price-sensitive renovation segments. Three archetypes dominate: heritage European engineering houses, Chinese scale manufacturers with provincial cooperative ties, and integrated solution providers bundling extraction technology with training infrastructure. Competitive moves concentrate on strategic partnerships for digital integration capabilities and geographic expansion through direct manufacturer engagement with purchasing consortia.
Among Italian heritage engineering houses, SCM Group and Felder Group occupy positions exemplifying premium-tier differentiation through integrated dust-collection systems and training academy networks. WEINIG Group anchors the high-frequency spindle technology vector with automated profile grinding compatibility. Chinese scale manufacturers including Shandong Guandiao CNC and Qingdao Zhongding Machinery represent the provincial cooperative model achieving cost compression through concentrated supplier ecosystems in Shandong and Jiangsu.
| Leading Market Players |
|---|
| Qingdao Zhongding Machinery |
| Jaya International |
| Shandong Guandiao CNC |
| Shanghai Win Star |
| SCM Group |
| Felder Group |
| Martin |
| Format-4 |
| WEINIG Group |
| Others |
Value Network & Pricing Analysis
Copper and rare-earth magnet price indices cascade through spindle shaper manufacturing cost structures, compressing margin structures for mid-tier electric drive suppliers while amplifying pricing power for bearing-integrated premium vendors. This input-cost asymmetry stratifies procurement across warranty-bundled service tiers, with CE-marked automated systems commanding premium positioning against pneumatic variants serving humidity-constrained Southeast Asian mills.
Pricing Analysis
Warranty and field service bundling separates premium-tier positioning from unbundled economy offerings, with CE-marked automated feedback systems carrying extended coverage terms that inflate upfront capital outlay. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and spindle speed stability specifications, with German and Italian furniture manufacturers least price-sensitive due to outcome-based performance guarantees. Cost compression in mid-tier electric drive configurations is intensifying because copper and rare-earth magnet input volatility erodes supplier margins without commensurate pricing power. DIY enthusiasts and small woodworking shops exhibit highest price sensitivity, prioritizing retrofit compatibility over maximum spindle speed or automated profile grinding capabilities.
Supply Chain Analysis
CE marking and GB standard certification gating concentrates component sourcing among qualified precision bearing suppliers in Germany, electric motor manufacturers in China, and cast-iron foundry operations in Italy. Spindle shaper production draws from German spindle bearing clusters, Chinese rare-earth magnet processing, and Italian precision machining heritage, creating geographic interdependence across high-RPM machine configurations. Single-source vulnerability on precision bearings from Baden-Württemberg suppliers exposes high-frequency spindle manufacturers to supply interruption risks. Distribution runs through state-backed woodworking machinery cooperatives in Jiangsu province and certified field service networks in the Midwest United States, displacing traditional equipment dealers in volume procurement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spindle shaper market sits in a technology-transition phase where high-frequency direct-drive configurations are displacing belt-transmission legacy systems. Automated feedback integration and CNC compatibility are becoming baseline requirements rather than premium differentiators, compressing competitive windows for manual-adjustment suppliers.
For Market Incumbents: To counter obsolescence pressure from high-frequency spindle technology, SCM Group and Felder Group should deepen backward integration into precision bearing supply chains through captive partnerships with Baden-Württemberg suppliers. Certification investment in China's SAMR GB standards compliance creates defensive moats against domestic scale manufacturers, while training academy network expansion locks in woodworking shop loyalty through operator certification dependency.
For New Entrants and Emerging Players: Launch via direct manufacturer engagement with Vietnamese provincial purchasing consortia in Ho Chi Minh City and Binh Duong province, bypassing distributor margin extraction. The underpenetrated furniture export sector offers white-space expansion for CE-marked precision edge-shaping equipment meeting EU import standards. Portable pneumatic variants for high-humidity Southeast Asian renovation contractors represent the most penetrable segment, with quick-release fence configurations reducing setup velocity gaps against established electric drive portfolios.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electric drive specialists with SAMR certification pipelines and Jiangsu province cooperative relationships, where margin compression from copper input costs creates acquisition windows. Long-term viability over a five-to-ten-year horizon hinges on digital integration capabilities and automated feedback system development. The signal to watch is CNC programming technician scarcity resolution rates, as recruitment gaps for operators capable of integrating spindle shapers with shop-floor management software determine adoption velocity for integrated management configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Frequency Spindle Technology Adoption | Direct-drive configurations eliminate belt losses and enable tolerances manual systems cannot match. |
| CE Marking and GB Standard Certification Investment | Compliance gating creates replacement cycles for non-compliant legacy equipment across European and Chinese facilities. |
| Training Academy Network Expansion | Felder Group's certification dependency locks in woodworking shop loyalty and differentiates from component vendors. |
| Direct Manufacturer Engagement with Purchasing Consortia | Jiangsu state-backed cooperatives negotiate volume contracts that bypass traditional equipment dealers. |
| Integrated Dust-Collection System Bundling | Extraction technology packages combined with field service networks elevate total cost of ownership calculations. |
Research Methodology
Document review covered customs and trade data from Shandong and Jiangsu province export registries, SAMR GB standard certification filings, and EU Machinery Directive compliance databases, complemented by interviews with plant engineers at German furniture manufacturers, maintenance directors at Southeast Asian mills, procurement leads at Chinese state-backed machinery cooperatives, and aftermarket service heads at Italian heritage engineering houses. Secondary validation drew from SEC filings of publicly traded woodworking machinery suppliers, OSHA enforcement action records, and CNC woodworking cluster production statistics. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Historical shipment patterns cross-referenced against expert panel input from SCM Group and WEINIG Group product development executives established baseline growth trajectories. Segmentation modeling tracked product type, end-user scale, powertrain technology, and management architecture dimensions, with CAGRs derived from regression analysis of correlated industrial machinery demand indicators. Spindle speed stability specifications, cutter alignment tolerances, and automated feedback adoption rates served as industry-specific forecast inputs.
Copper and rare-earth magnet price volatility, single-source bearing supply interruptions, and CNC technician recruitment gaps are the dominant revision risks that could compress or accelerate projected expansion. Forecasts reflect assumptions documented in stakeholder interview transcripts and secondary source triangulation. A model refresh is warranted upon material change in China's dual carbon goals procurement enforcement or EU Machinery Directive emergency braking threshold amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Metal Cutting Machine Market
Tools
Tape Measure Market
Tools
Industrial Ladder Market
Tools
Indexable Inserts Market
Tools
Tile Saw Market
Tools
Forging Press Market
Tools
Hand Tools Market
Tools
Telescopic Tool Boxes Market
Tools
Power Nibbler Market
Tools
Cordless Wood Planer Market
Tools
Turning Centers Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Digital Cutting Machine Market
Tools
Collated Screws Market
Tools
Power Tool Accessories Market
Tools
Coil Fed Punching and Cutting Machines Market