
 Global Open API Market | 2026-2036
Global Open API Market Size, Share, and Industry Trends Forecast 2026-2036
Global Open API Market Foresight
Platform licensing revenue is tilting from perpetual on-premises contracts toward recurring cloud-native subscriptions. MuleSoft leverages its Salesforce integration ecosystem to anchor enterprise-grade API management deployments. RapidAPI competes through marketplace network effects that aggregate thousands of third-party endpoints. Tyk Technologies specializes in lightweight, developer-first gateway solutions that extend API control to edge computing environments.
An open API is a publicly available application programming interface that exposes standardized HTTP endpoints with defined request-response schemas, authentication protocols, and rate-limiting parameters, enabling external software systems to interact with a platform's data or functionality without accessing underlying source code. REST APIs dominate current deployment volumes due to their stateless architecture and JSON payload efficiency, while GraphQL is displacing traditional query patterns in mobile and frontend applications where bandwidth optimization drives performance. Cloud-native deployment now captures the fastest-growing margin pool as Kubernetes-native service meshes eliminate infrastructure provisioning overhead for API publishers.
The EU AI Act, GDPR, and ISO/IEC 27001 standards collectively mandate audit trails, consent management, and data minimization across API transaction flows, elevating compliance tooling from optional to procurement-critical. The US FCC and SEC frameworks impose sector-specific transparency requirements on telecommunications and financial APIs, respectively. Stakeholders must monitor how fragmented national data-localization rules reshape multi-cloud routing architectures and gateway placement decisions.
Market Dynamics
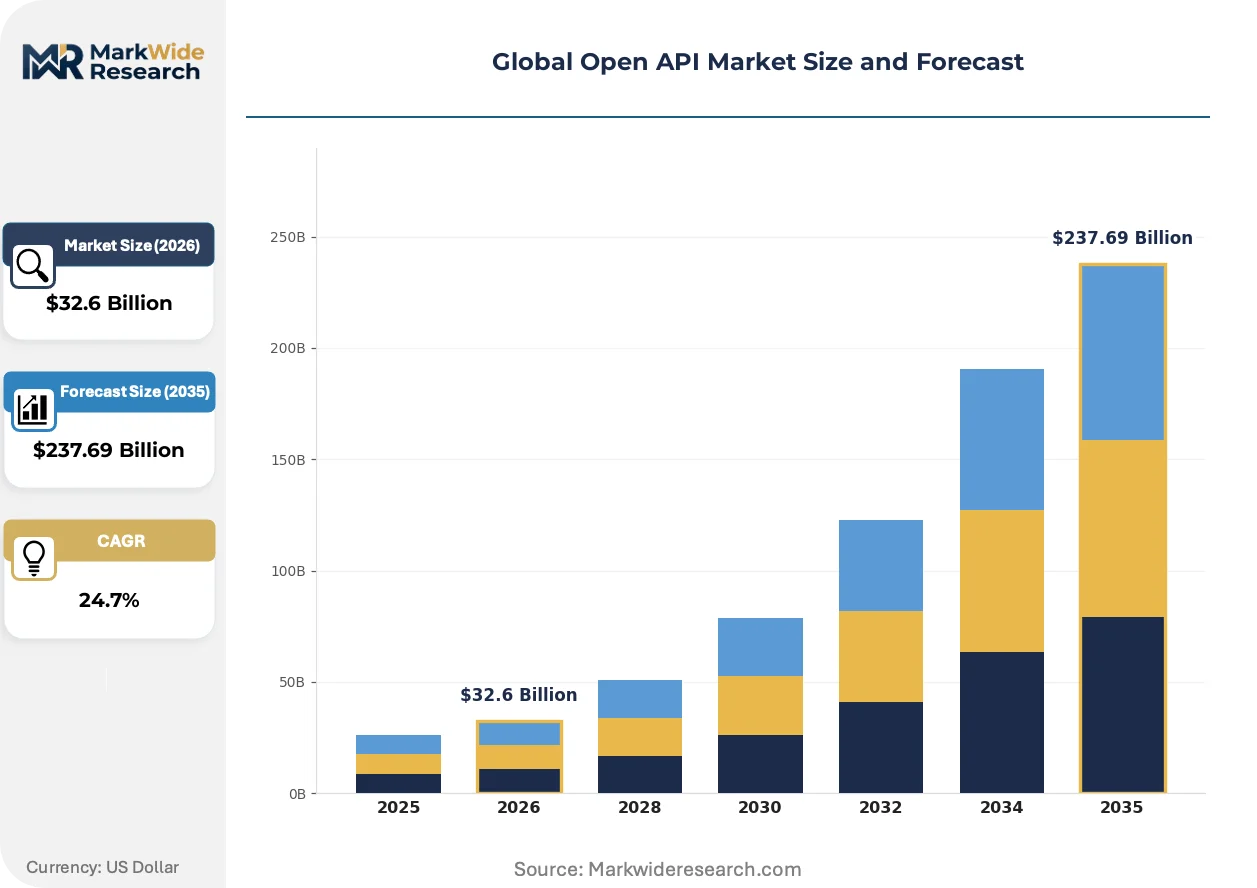
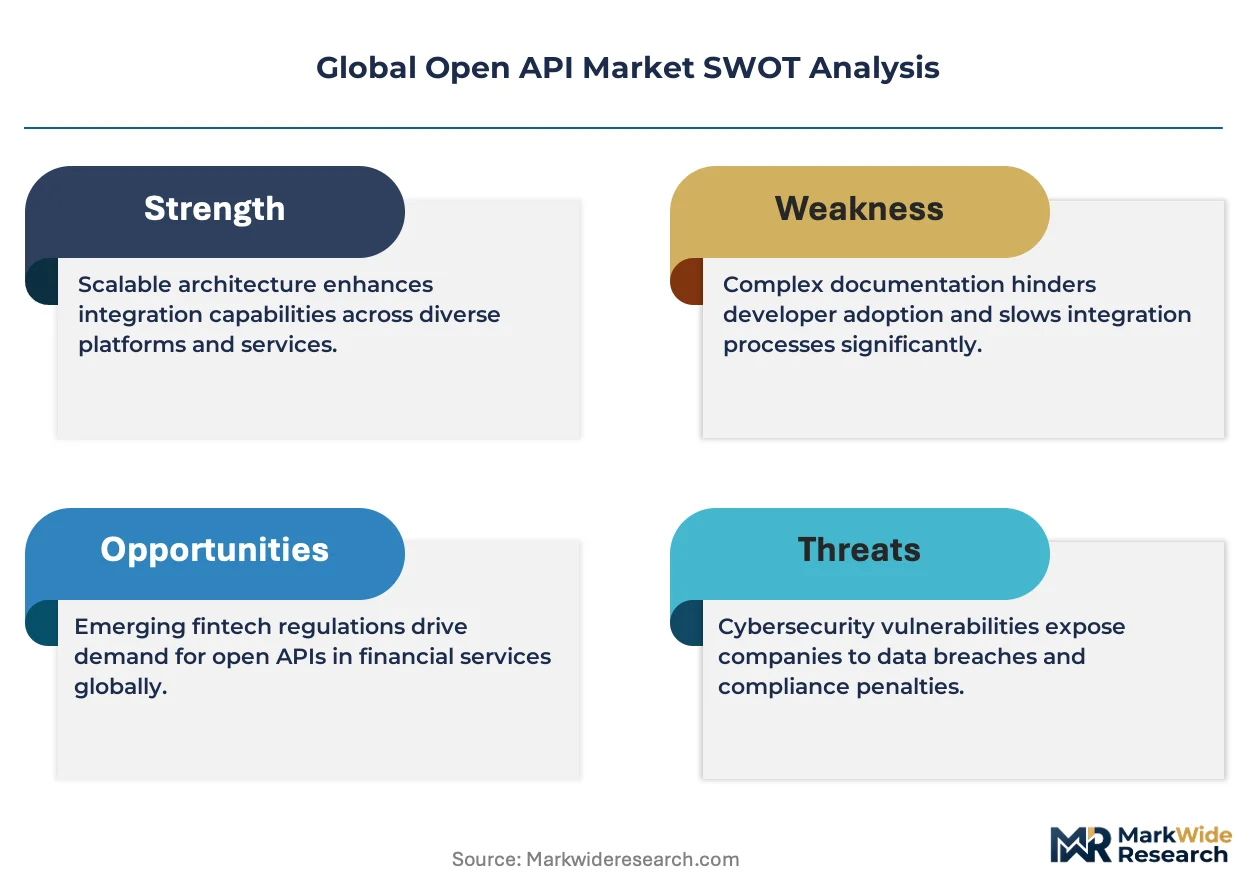
Cloud-native API deployment is compressing infrastructure provisioning cycles while regulatory mandates from the EU AI Act and GDPR impose audit-trail requirements that reshape procurement priorities for enterprise buyers.
Growth Catalysts
- FinTech Embedded Payments:Real-time data sharing protocols between banking platforms and merchant systems are accelerating API consumption across transaction processing workflows.
- GDPR Compliance Mandates:European enterprises must implement standardized consent management and data minimization across API transaction flows, elevating governance tooling to procurement-critical status.
- Kubernetes-Native Service Meshes:Container orchestration eliminates manual gateway provisioning for API publishers, reducing deployment friction in Silicon Valley and New York financial corridors.
Market Restraints
- Multi-Cloud Routing Complexity:Fragmented national data-localization rules force API publishers to maintain redundant gateway infrastructure across jurisdictions.
- Specialized Talent Scarcity:Shortage of engineers proficient in both API security architecture and cloud-native deployment patterns constrains rollout velocity.
- Legacy System Entrenchment:SOAP-based integrations in established financial institutions resist migration to REST and GraphQL protocols despite efficiency advantages.
Strategic Opportunities
- Edge Computing Expansion:Lightweight gateway solutions extend API control to distributed IoT environments where bandwidth constraints dominate.
- India Digital Public Infrastructure:The country's open network protocols for digital commerce create demand for standardized API interoperability frameworks.
- ISO/IEC 27001 Certification:Information security management standards create procurement preference for vendors with auditable compliance tooling.
Industry Challenges
- API Versioning Complexity:Maintaining backward compatibility across multiple schema iterations strains DevOps resources and extends release cycles.
- Cross-Border Data Governance:Reconciling GDPR requirements with US FCC transparency mandates and sector-specific SEC frameworks fragments compliance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Open API Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $237.69 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
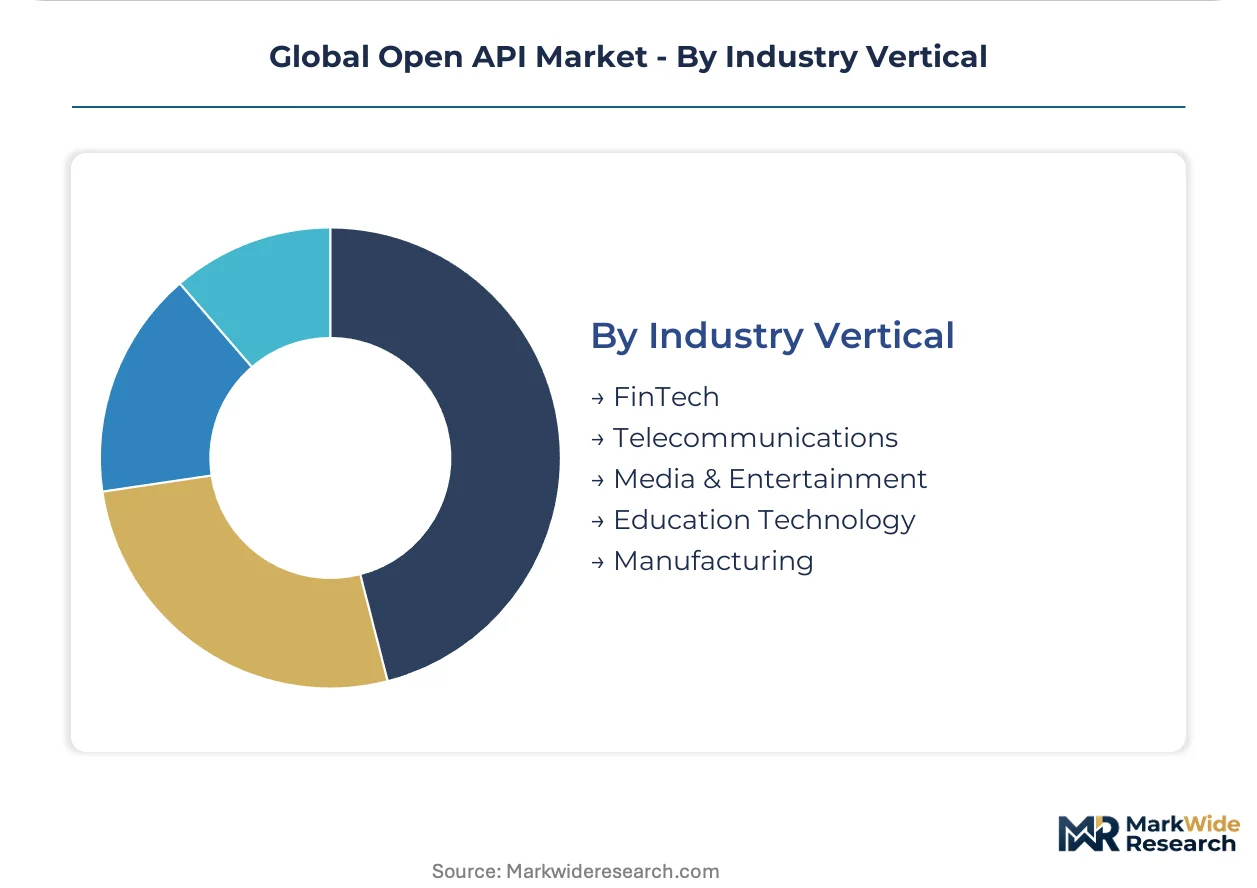
| Segmentation | API Type: REST, SOAP, GraphQL, RPC, Webhooks Deployment: On-Premises, Cloud-Native, Hybrid, Multi-Cloud, Edge End User: Startups, Independent Developers, Digital Agencies, E-Commerce Platforms, System Integrators Industry Vertical: FinTech, Telecommunications, Media & Entertainment, Education Technology, Manufacturing |
| Companies Covered | MuleSoft, Apideck, RapidAPI, Unified.to, Merge, Algolia, Workato, Platformatic, Tyk Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Open API Market Shifts & Advancements
API architecture is undergoing protocol diversification as bandwidth constraints and developer experience priorities reshape endpoint design standards across mobile, edge, and enterprise environments.
GraphQL query languages are migrating from niche mobile applications toward mainstream enterprise deployments. Frontend development teams at bandwidth-sensitive operations are adopting the protocol to reduce payload overhead. The technology is migrating from experimental implementations to production-critical infrastructure, compressing REST's dominance in consumer-facing applications.
The EU AI Act mandates algorithmic transparency and risk-classification documentation for automated decision-making systems exposed through APIs. Publishers must implement technical documentation standards and human-oversight mechanisms for high-risk use cases. Financial services APIs across Frankfurt and Paris face the steepest compliance ramp as national regulators issue implementation guidance.
Enterprise buyers are consolidating vendor relationships around integrated platform ecosystems rather than point-solution procurement. API management purchasing now flows through cloud-provider marketplaces and Salesforce-anchored suites, displacing standalone gateway negotiations. This concentration is most visible among cloud-native enterprises in US technology corridors where procurement authority has shifted to central IT architecture teams.
Global Open API Market Segmentation

Open API architectures fragment across protocol standards, infrastructure models, and buyer sophistication levels. Procurement patterns diverge sharply between cloud-native enterprises seeking Kubernetes-native service meshes and legacy institutions maintaining SOAP-based integrations.
API Type:
The use-case spectrum spans lightweight mobile transactions to complex enterprise orchestration, with protocol selection driven by payload efficiency versus schema rigidity tradeoffs.
- REST:Stateless HTTP architecture with JSON payload standard dominates current deployment volumes. Silicon Valley cloud-native enterprises and New York financial corridors anchor demand as bandwidth optimization drives mobile and web application performance.
- GraphQL:Query language enabling clients to request precise data subsets reduces over-fetching overhead. Frontend development teams at bandwidth-sensitive operations across Germany and France are migrating this protocol from experimental implementations to production-critical infrastructure.
- SOAP:XML-based messaging protocol with rigid schema enforcement persists in established financial institutions. Legacy system entrenchment constrains migration velocity despite REST efficiency advantages.
- RPC:Remote procedure call frameworks optimize internal microservice communication. High-frequency trading platforms and real-time gaming infrastructure represent concentrated adoption pockets.
- Webhooks:Event-driven HTTP callbacks enable asynchronous data推送 without polling overhead. E-commerce payment notification systems and CI/CD pipeline automation drive implementation.
The dominant share belongs to REST, while GraphQL is closing the gap fastest.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from operational expenditure cloud models, with hybrid architectures capturing regulatory-constrained buyers.
- Cloud-Native:Kubernetes-native service meshes eliminate manual gateway provisioning for API publishers. Container orchestration reduces deployment friction among technology corridors in the United States where procurement authority has shifted to central IT architecture teams.
- On-Premises:Dedicated hardware deployments within enterprise data centers satisfy data residency mandates. Frankfurt and Paris financial services institutions facing EU AI Act compliance requirements maintain this infrastructure for high-risk automated decision-making systems.
- Hybrid:Split architectures balance sensitive workload isolation with scalable public cloud burst capacity. GDPR data minimization requirements across European enterprises drive segmentation between consent-managed on-premises cores and analytics cloud extensions.
- Multi-Cloud:Redundant gateway infrastructure spans AWS, Azure, and GCP environments simultaneously. Fragmented national data-localization rules force publishers to maintain jurisdictional presence across United States, Germany, and Singapore regulatory zones.
- Edge:Lightweight gateway solutions extend API control to distributed IoT environments. Manufacturing facilities and autonomous vehicle networks leverage this deployment where bandwidth constraints dominate latency-sensitive operations.
Cloud-Native deployment captures the largest revenue pool, though Edge infrastructure is expanding most quickly.
End User:
Customer type segmentation reflects procurement sophistication, from individual developers consuming marketplace endpoints to enterprise architecture teams negotiating platform licensing.
- System Integrators:Professional services firms aggregate multiple client API ecosystems into unified integration layers. Salesforce-anchored suites and cloud-provider marketplaces concentrate purchasing authority among these intermediaries.
- E-Commerce Platforms:Merchant systems demanding real-time payment processing and inventory synchronization generate embedded API consumption. Transaction volume scaling drives gateway performance requirements.
- Digital Agencies:Creative technology shops implement client-facing API integrations for marketing automation and content personalization. Project-based procurement favors consumption-based pricing over perpetual licensing.
- Startups:Venture-backed technology companies prioritize developer experience and rapid prototyping capabilities. Marketplace network effects aggregating thousands of third-party endpoints reduce integration overhead.
- Independent Developers:Individual practitioners leverage freemium tiers and documentation quality for side-project implementations. Community-driven support channels influence platform selection.
System Integrators command the dominant procurement volume, while E-Commerce Platforms are gaining share fastest.
Industry Vertical:
Application-specific requirements reshape security postures, with FinTech demanding real-time latency and Manufacturing prioritizing edge reliability.
- FinTech:Banking platforms and merchant systems accelerate API consumption across transaction processing workflows. SEC transparency mandates and real-time data sharing protocols between United States financial corridors anchor specialized governance tooling procurement.
- Telecommunications:Carrier-grade infrastructure exposes network provisioning and billing systems through standardized interfaces. FCC sector-specific requirements impose transparency obligations on United States telecommunications APIs.
- Media & Entertainment:Content delivery networks and streaming platforms optimize for bandwidth-efficient payload structures. GraphQL adoption concentrates here for mobile application performance.
- Education Technology:Learning management systems and assessment platforms integrate third-party content libraries. Student data privacy regulations constrain cross-border API routing architectures.
- Manufacturing:Industrial IoT sensor networks and predictive maintenance systems require edge-deployed gateway reliability. ISO/IEC 27001 certification creates procurement preference for vendors with auditable compliance tooling.
FinTech holds the dominant vertical position, though Manufacturing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States buyers prioritize cloud-native deployment velocity, while European enterprises weight compliance tooling more heavily in procurement decisions.
United States
Silicon Valley cloud-native enterprises and New York financial corridors anchor API management demand. SEC transparency mandates impose sector-specific requirements on financial APIs. Kubernetes-native service meshes eliminate manual gateway provisioning among technology corridor buyers where procurement authority has shifted to central IT architecture teams.
Germany
Frankfurt financial services institutions drive embedded payments API consumption across banking platforms. EU AI Act compliance requirements mandate algorithmic transparency documentation for automated decision-making systems. Manufacturing facilities in Bavaria leverage edge-deployed gateway reliability for industrial IoT sensor networks.
United Kingdom
London-based fintech platforms accelerate real-time data sharing protocols between merchant systems. GDPR consent management requirements elevate governance tooling to procurement-critical status for British enterprises. Digital agencies across the Southeast implement client-facing API integrations for marketing automation workflows.
India
The country's open network protocols for digital commerce create demand for standardized API interoperability frameworks. RBI oversight shapes financial API governance requirements for banking sector deployments. Bengaluru and Hyderabad technology clusters concentrate venture-backed startup activity prioritizing developer experience and rapid prototyping capabilities.
Singapore
Multi-cloud routing architectures concentrate in this jurisdiction due to fragmented national data-localization rules across Asia-Pacific. The central bank's technology risk management guidelines influence API security procurement standards. Financial institutions maintain redundant gateway infrastructure to satisfy cross-border data governance requirements.
Global Open API Market Competitive Landscape
Capability concentration sits with specialized gateway vendors; scale advantage sits with platform ecosystem anchors. The vendor base stratifies across three tiers: enterprise-suite incumbents, marketplace aggregators, and lightweight developer-first specialists. Strategic archetypes include Salesforce-anchored integration suites, network-effect marketplaces, and Kubernetes-native service mesh providers. Competitive moves center on cloud-provider marketplace listings and vertical API template libraries.
Within the enterprise-suite tier, MuleSoft leverages its Salesforce integration ecosystem to anchor deployments. RapidAPI competes through marketplace network effects that aggregate third-party endpoints. Tyk Technologies occupies a position among lightweight gateway specialists extending API control to edge computing environments.
| Leading Market Players |
|---|
| MuleSoft |
| Apideck |
| RapidAPI |
| Unified.to |
| Merge |
| Algolia |
| Workato |
| Platformatic |
| Tyk Technologies |
| Others |
Supply & Pricing Matrix
Bengaluru and Hyderabad technology clusters concentrate API gateway engineering talent, compressing labor costs for cloud-native deployment while amplifying pricing power for vendors serving US financial corridors. This geographic asymmetry shapes tiered subscription models that extract premium rates from Frankfurt compliance-heavy buyers while competing on developer-experience metrics in Silicon Valley.
Pricing Analysis
Long-term enterprise offtake contracts with annual recurring revenue clauses dominate procurement between system integrators and platform vendors. Three-tier pricing structure across premium, standard, and economy levels segments by ISO/IEC 27001 certification tier and dedicated support SLAs. Pricing pressure stems from RapidAPI marketplace aggregation commoditizing standalone gateway features. Independent developers exhibit highest price sensitivity, while Frankfurt financial institutions accept premium tiers for EU AI Act audit-trail compliance.
Supply Chain Analysis
Export-control regimes restricting cryptographic module transfers limit gateway firmware distribution from United States to certain jurisdictions. Engineering talent concentrates in India, United States, and Germany, with cloud infrastructure provisioning drawing from AWS, Azure, and GCP hyperscaler networks. Single-source vulnerability sits with Kubernetes control plane dependencies. Distribution runs through cloud-provider marketplaces and Salesforce-anchored procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now reward API ecosystem orchestration over point-solution dominance, with Salesforce-anchored integration suites capturing procurement authority shifts among central IT architecture teams.
For Market Incumbents: Build switching-cost moats through deep Salesforce ecosystem integration and proprietary vertical API template libraries. Consolidate vendor relationships by embedding governance tooling directly into Kubernetes-native service meshes. Counter RapidAPI marketplace network effects with exclusive FinTech partnership lock-ins. Prioritize ISO/IEC 27001 certification investment to defend Frankfurt and Paris financial corridor accounts against lightweight challengers. For New Entrants and Emerging Players: Pursue edge computing gateway deployments where Tyk Technologies has established lightweight positioning but manufacturing IoT penetration remains shallow. Target India digital public infrastructure protocols for standardized interoperability frameworks underserved by incumbent compliance-heavy pricing. Penetrate through developer-experience differentiation and consumption-based pricing that undercuts enterprise-suite annual commitments. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-technology play because EU AI Act and GDPR audit-trail mandates elevate governance tooling from optional to procurement-critical across European enterprises. Acquisition candidates with Kubernetes-native service mesh architecture and existing ISO/IEC 27001 certification command structural scarcity premiums. Watch for inflection when national data-localization rule fragmentation forces multi-cloud gateway redundancy spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Salesforce-anchored suites capture procurement authority shifts among central IT architecture teams in US technology corridors. |
| Acquisition of Specialist Firm | Edge computing gateway vendors extend API control to manufacturing IoT environments with bandwidth-constrained operations. |
| Strategic Partnership | FinTech embedded payments partnerships lock in transaction volume scaling across New York financial corridor banking platforms. |
| Geographic Expansion | India digital public infrastructure protocols create standardized API interoperability demand in Bengaluru and Hyderabad clusters. |
| Product Launch | EU AI Act-compliant governance tooling launches capture Frankfurt and Paris financial services procurement mandates. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and integration specialists anchored the qualitative base for this analysis. Primary fieldwork across Silicon Valley, New York, Frankfurt, and Bengaluru technology corridors combined with secondary validation from SEC filings, hyperscaler capex disclosures, cloud-provider marketplace data, and EU regulatory implementation guidance. Bottom-up deployment volume estimates and top-down platform revenue analysis underwent triangulation to converge on segment-level projections.
Scenario-bracketing around regulatory implementation timelines and cloud adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include API protocol type, deployment architecture, end-user sophistication tier, and industry vertical compliance intensity. CAGRs derived from deployment volume trajectories and pricing tier migration patterns, with Kubernetes-native service mesh penetration and EU AI Act compliance spending serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in enterprise software budget cycles or hyperscaler infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions regarding GDPR enforcement consistency and FinTech embedded payments adoption curves. Material shifts in national data-localization rule fragmentation or EU AI Act implementation guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Communication Software Market
Software & Services
Productivity Management Software Market
Software & Services
Global Webinar Software Market
Software & Services
Oracle Services Market
Software & Services
Global CMDB Software Market
Software & Services
Global Video Streaming Software Market
Software & Services
Interior Design Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Global Open Source Services Market
Software & Services
Lead Scoring Software Market
Software & Services
Shift Planning Software Market
Software & Services
North America IT Services Market