
 Server Virtualization Software Market | 2026-2036
Server Virtualization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Server Virtualization Software Market Outlook
Container-to-virtual-machine convergence is tilting enterprise infrastructure strategies toward unified orchestration platforms. VMware Inc. leverages its hypervisor heritage to anchor hybrid cloud deployments across Fortune 500 data centers. Microsoft Corporation extends Azure Stack integration to compete for on-premises-to-cloud workloads. Huawei Technologies Co. Ltd. navigates Western market restrictions by dominating domestic and emerging-market government contracts.
Server virtualization software abstracts physical server hardware into multiple isolated virtual instances through a hypervisor layer, enabling resource pooling, dynamic allocation, and workload isolation with sub-millisecond context switching. Its primary commercial purpose is to maximize hardware utilization while reducing capital expenditure and operational overhead in enterprise computing environments. Cloud-based deployment is capturing the fastest expansion as enterprises exit owned data centers, while proprietary solutions still command the deepest margin pools due to integrated support ecosystems. Data center optimization remains the dominant application segment, though disaster recovery is gaining traction as climate-related business continuity risks intensify.
US federal procurement now requires FedRAMP and NIST SP 800-53 compliance for virtualization layers handling controlled unclassified information, tightening vendor qualification barriers. The EU AI Act and GDPR cross-reference infrastructure transparency obligations that affect how European enterprises select hypervisor platforms with auditable data residency controls. Stakeholders must monitor whether sovereign cloud mandates in India, Germany, and Saudi Arabia fragment previously standardized procurement specifications into geography-specific certification requirements.
Market Dynamics
Container-to-virtual-machine convergence is compressing infrastructure procurement cycles as enterprises abandon siloed orchestration stacks for unified platforms that collapse compute abstraction layers into single vendor relationships.
Growth Catalysts
- NIST SP 800-53 mandates:US federal agencies now require compliant virtualization layers for controlled unclassified information, hardening procurement specifications and disqualifying uncertified vendors from defense and healthcare contracts.
- Healthcare cloud migration:Hospital systems and payers are exiting owned data centers at accelerating velocity, expanding the addressable base for hybrid-ready hypervisor platforms with HIPAA-aligned audit trails.
- Climate-driven continuity planning:Enterprise disaster recovery budgets are absorbing virtualization spend as extreme weather events force geographic redundancy requirements across financial services and critical infrastructure operators.
Market Restraints
- Proprietary licensing concentration:Dominant hypervisor vendors extract recurring maintenance streams that consume 40-60% of enterprise IT infrastructure budgets, constraining migration flexibility.
- Western market access barriers:Chinese technology providers face procurement blacklists and export restrictions across US federal and allied European government contracts, fragmenting vendor selection pools.
- Container-native workload substitution:Kubernetes-orchestrated containerization is capturing net-new cloud-native deployments that previously defaulted to virtual machines, compressing greenfield hypervisor demand.
Strategic Opportunities
- India sovereign cloud mandates:Data localization requirements under RBI and MeitY directives are forcing global cloud providers to establish domestic hypervisor infrastructure, creating captive demand for compliant local partnerships.
- Edge virtualization convergence:5G distributed core networks and industrial IoT gateways are extending hypervisor footprints to factory floors and cell towers, opening latency-sensitive workloads previously served by bare metal.
- EU AI Act infrastructure transparency:Auditable data residency controls are becoming procurement differentiators for European enterprises selecting hypervisor platforms with embedded compliance tooling.
Industry Challenges
- Multi-hypervisor skill scarcity:Enterprise IT organizations lack personnel proficient across VMware, Hyper-V, KVM, and emerging container-native virtualization stacks, delaying heterogeneous environment deployments.
- FedRAMP authorization timelines:Cloud service providers face 12-18 month certification cycles for virtualization layers handling government workloads, freezing revenue recognition and competitive positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Server Virtualization Software Market |
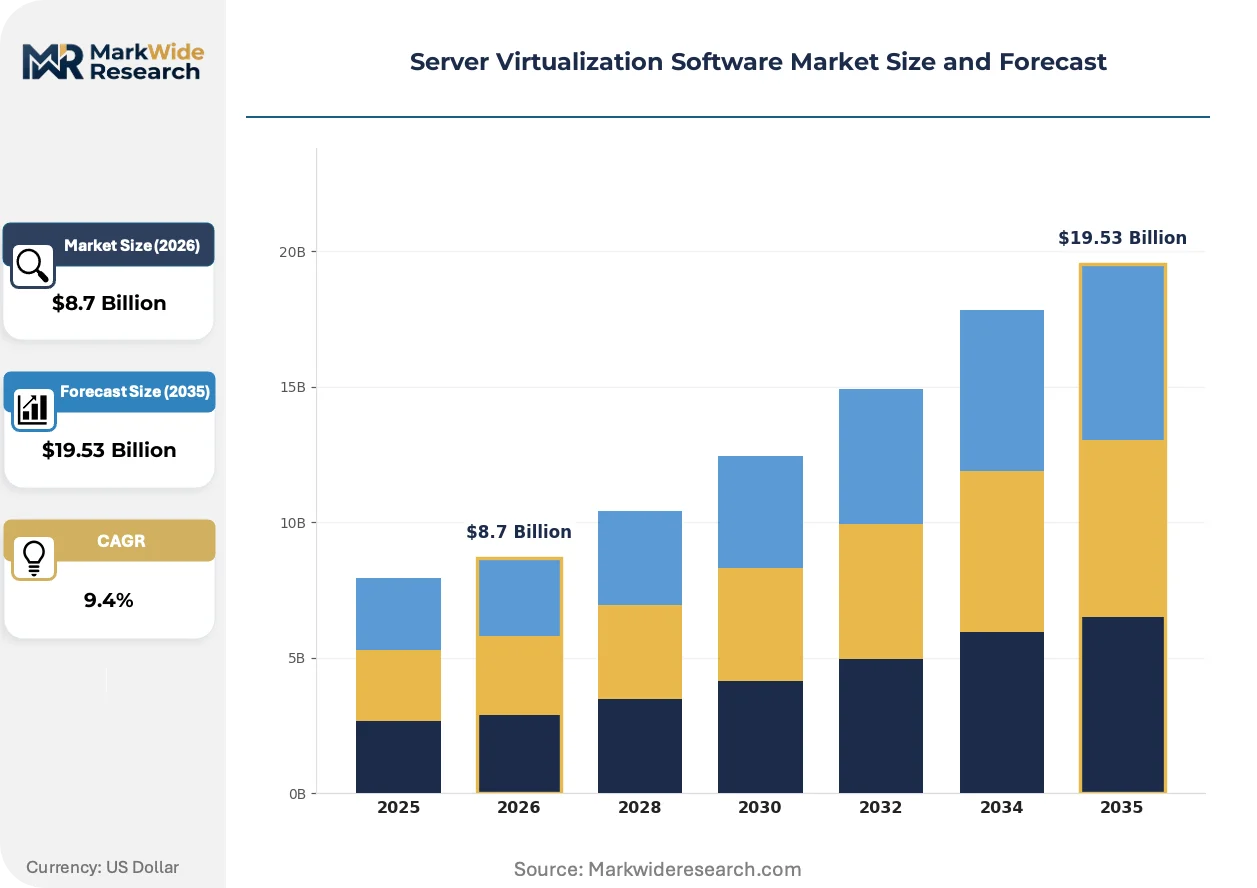
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Application: Data Center Optimization, Disaster Recovery, Testing & Development, Server Consolidation End User: IT Services, BFSI, Healthcare, Telecommunications Solution: Open Source, Proprietary, Virtual Desktop Infrastructure, Hypervisor |
| Companies Covered | Broadcom Inc., Microsoft Corporation, VMware Inc., Cisco Systems Inc., Dell Technologies Inc., Hewlett Packard Enterprise, IBM Corporation, Oracle Corporation, Huawei Technologies Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Server Virtualization Software Market Strategic Shifts
Unified orchestration platforms are dissolving the historical boundary between virtual machine management and container deployment, forcing infrastructure software vendors to consolidate previously separate control planes or cede enterprise relationships.
Kernel-based virtual machine enhancements with nested virtualization support are collapsing the performance gap between Type-1 and Type-2 hypervisors. Cloud service providers are adopting these open-source stacks to reduce licensing exposure. This compression is enabling commodity hardware to host multi-tenant workloads previously requiring proprietary silicon.
The EU AI Act's infrastructure transparency obligations are mandating auditable data lineage through virtualization layers processing training datasets. German automotive manufacturers and French financial institutions are selecting hypervisors with embedded logging and residency controls. Compliance tooling is becoming a procurement gate rather than a post-sale add-on.
Enterprise buying committees are consolidating vendor relationships around integrated cloud-native platforms that bundle compute abstraction, storage orchestration, and network virtualization. Systems integrators and value-added resellers are losing attach revenue as direct procurement from hyperscalers displaces channel-mediated transactions. This concentration is most visible in US Fortune 500 accounts with centralized cloud centers of excellence.
Server Virtualization Software Market Segmentation
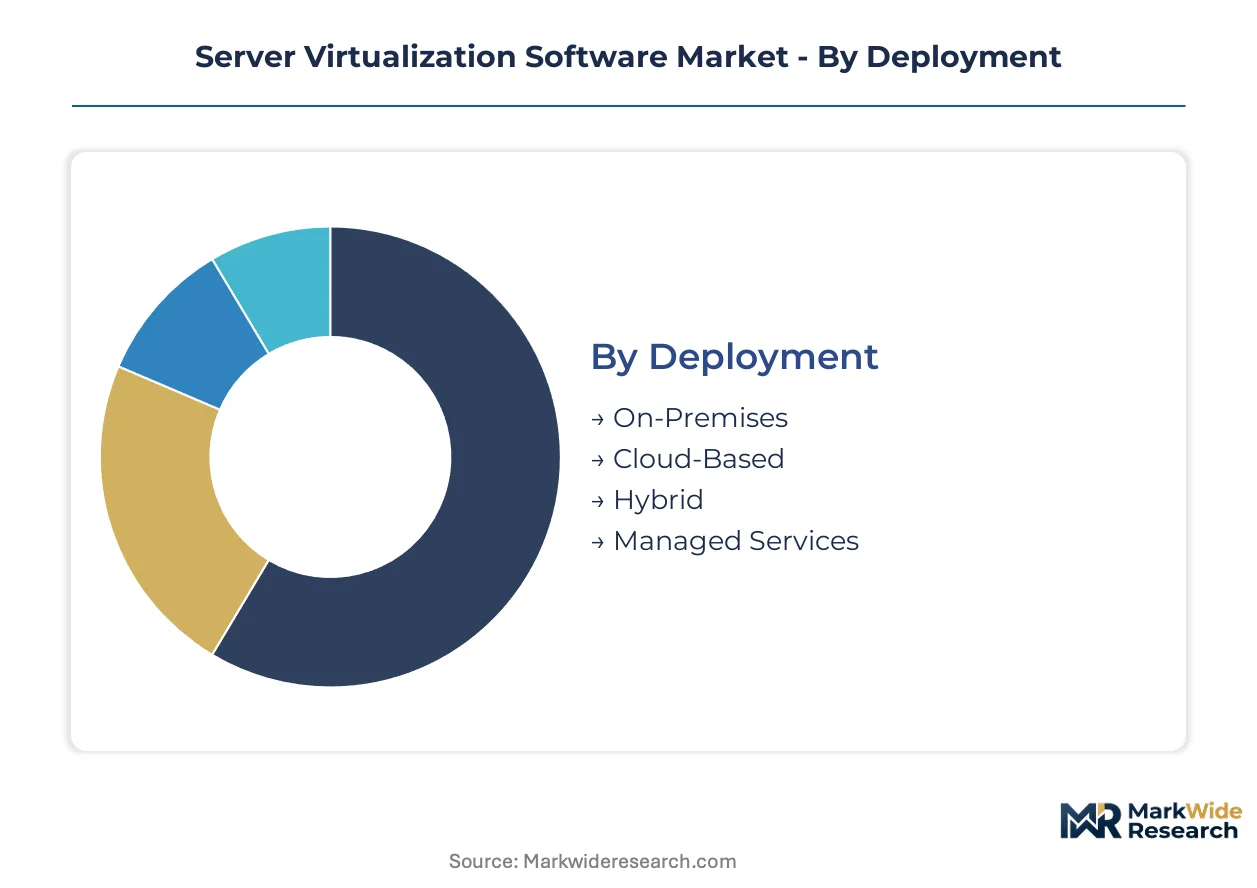
Server virtualization software procurement splits across deployment models, workload applications, industry verticals, and licensing structures. These divisions determine vendor selection criteria, pricing architecture, and compliance obligations for enterprise buyers.
Deployment:
Cloud-based deployments turn over fastest as enterprises exit owned infrastructure, while managed services contracts exhibit the longest renewal cycles due to embedded operational dependencies.
- On-Premises:Traditional hypervisor installations within enterprise data centers deliver sub-millisecond latency for latency-sensitive financial trading and manufacturing control systems. Demand concentrates among German automotive manufacturers and US defense contractors subject to FedRAMP and ITAR data sovereignty requirements that prohibit off-premise processing.
- Cloud-Based:Hyperscaler-hosted virtualization layers abstract hardware management while enabling elastic scaling. Hospital systems in India and payers in the United States are migrating here fastest, driven by RBI data localization mandates and HIPAA-aligned audit trail requirements that favor cloud-native compliance tooling.
- Hybrid:Unified control planes orchestrate workloads across on-premises and cloud infrastructure. Indian IT services firms and Saudi government entities deploy this model to satisfy sovereign cloud directives while retaining burst capacity.
- Managed Services:Third-party operators assume full hypervisor lifecycle responsibility. BFSI institutions in Germany and telecommunications providers in India favor this option to address internal skill scarcity.
On-premises dominates installed base. Cloud-based is where expansion concentrates.
Application:
Cost tier stratification separates capital-intensive data center builds from operational disaster recovery spending.
- Data Center Optimization:Workload consolidation onto fewer physical hosts through dynamic resource allocation. US Fortune 500 enterprises and Indian IT services firms drive volume here, seeking to defer hardware refresh cycles amid elevated silicon costs.
- Disaster Recovery:Geographic redundancy through replicated virtual machines with automated failover. Financial services operators in Germany and critical infrastructure providers in the United States are expanding budgets fastest as climate-related business continuity risks intensify.
- Testing & Development:Ephemeral virtual machine provisioning for software engineering pipelines. Technology firms in India and US SaaS providers consume this segment heavily.
- Server Consolidation:Legacy workload migration from physical to virtual infrastructure. Government agencies in Saudi Arabia and healthcare systems in Germany pursue this to extend asset lifecycles.
Data center optimization commands the deepest margin pools. Disaster recovery is climbing the fastest.
End User:
Customer type determines procurement sophistication and compliance burden intensity.
- IT Services:Multi-tenant hosting providers and systems integrators resell virtualization capacity. Indian IT services firms represent the largest addressable base, driven by RBI-mandated domestic infrastructure requirements.
- BFSI:Banks, insurers, and payment processors with stringent audit and residency obligations. German and US institutions lead procurement here, prioritizing GDPR and SEC-aligned data lineage controls.
- Healthcare:Hospital systems and payers exiting owned data centers. US healthcare providers dominate this segment under HIPAA and NIST SP 800-53 procurement specifications.
- Telecommunications:5G core network virtualization and edge infrastructure deployment. Indian and Saudi operators are expanding fastest under sovereign cloud mandates.
IT services dominates transaction volume. Healthcare is gaining share fastest.
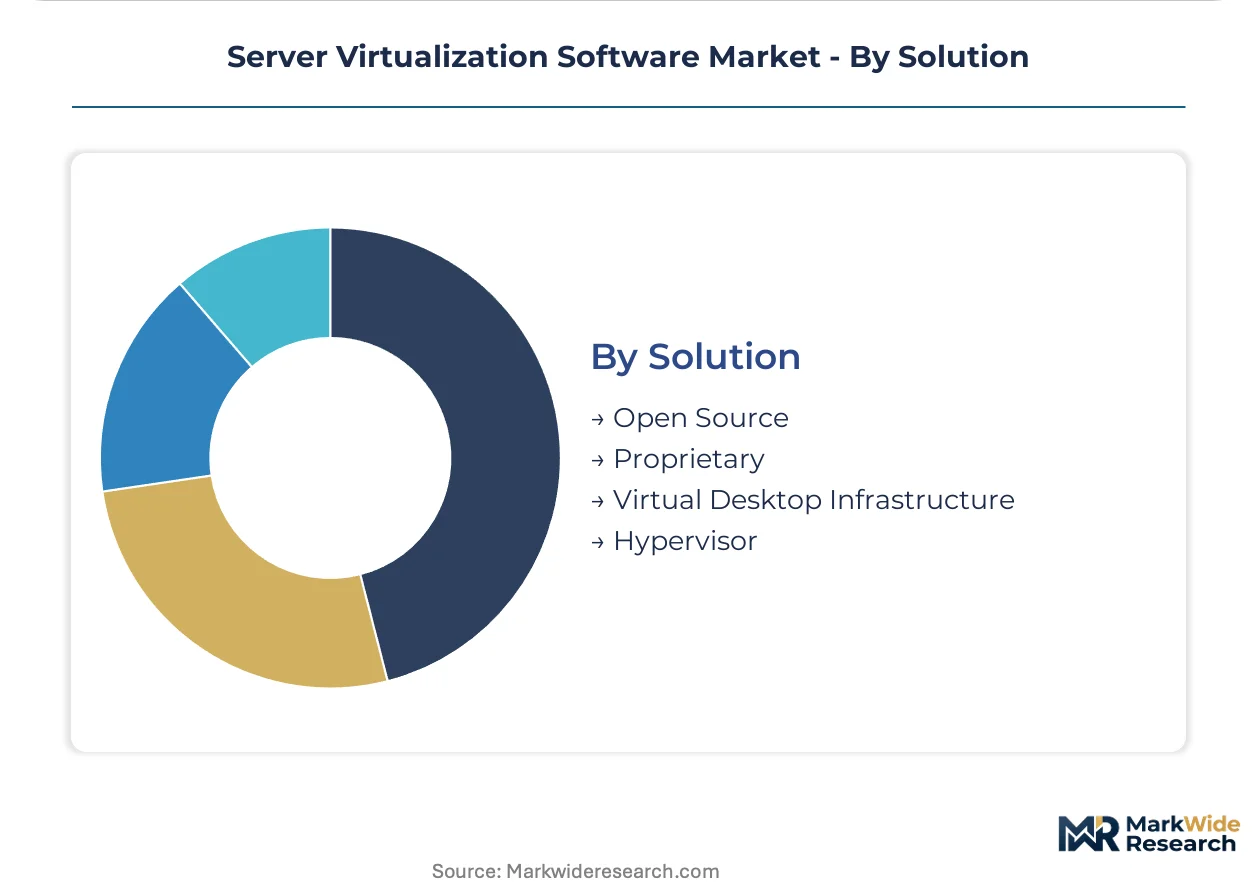
Solution:
Margin structure separates integrated proprietary stacks from commodity open-source alternatives.
- Proprietary:Licensed hypervisor platforms with embedded support ecosystems. US federal agencies and German automotive manufacturers concentrate demand here, prioritizing vendor accountability and FedRAMP authorization.
- Open Source:KVM and Xen-based deployments with community or commercial support. Indian IT services firms and European cloud providers favor this model to reduce licensing exposure.
- Virtual Desktop Infrastructure:Desktop-as-a-service delivery through centralized virtual machines. Healthcare systems in the United States and BFSI institutions in Germany deploy this for endpoint security and remote workforce enablement.
- Hypervisor:Bare-metal virtualization layers as discrete software procurement. Telecommunications operators in India and Saudi Arabia select this for 5G distributed core customization.
Proprietary solutions dominate enterprise wallet share. Open source is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based virtualization vendors export licensing and support services to enterprise buyers across Germany and India, where data localization mandates and federal compliance requirements are accelerating procurement cycles for hybrid-ready hypervisor platforms.
United States
Federal agencies and healthcare systems drive domestic demand through FedRAMP-authorized procurement channels. NIST SP 800-53 mandates harden vendor qualification for defense and civilian contracts handling controlled unclassified information. Northern Virginia's data center corridor concentrates hyperscaler expansion as cloud providers establish sovereign-compliant infrastructure for government workloads.
Germany
Automotive manufacturers and financial institutions prioritize hypervisor platforms with embedded GDPR audit trails and data residency controls. The EU AI Act's infrastructure transparency obligations mandate auditable data lineage through virtualization layers processing training datasets. Bavaria's industrial automation cluster leads edge virtualization deployment for factory-floor latency requirements.
India
IT services firms and telecommunications operators expand fastest under RBI data localization directives and MeitY sovereign cloud mandates. Domestic infrastructure requirements force global providers to establish captive hypervisor partnerships with local operators. Mumbai and Bangalore concentrate multi-tenant hosting capacity as hospital systems and banks exit owned data centers.
Saudi Arabia
Government entities and critical infrastructure operators drive procurement under national cloud-first policies and data sovereignty frameworks. The central communications regulator enforces domestic processing requirements for sensitive workloads. Riyadh's government district anchors hyperscaler regional headquarters established to capture public sector virtualization contracts.
United Kingdom
Financial services regulators and defense procurement offices enforce stringent audit and residency obligations for virtualization layers handling transaction data and classified workloads. The Information Commissioner's Office cross-references infrastructure transparency requirements with operational risk frameworks. London's fintech corridor demands sub-millisecond latency hypervisor deployments for algorithmic trading platforms.
Server Virtualization Software Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated vendor landscape where recurring maintenance streams consume substantial enterprise infrastructure budgets. Three strategic archetypes dominate: heritage hypervisor vendors with decades-long data center relationships, cloud-native platform providers extending on-premises integration, and telecommunications equipment suppliers leveraging domestic market protection. M&A activity concentrates around portfolio diversification into container orchestration, while strategic partnerships address multi-hypervisor skill scarcity in enterprise IT organizations.
Within the heritage hypervisor tier, VMware Inc. and Broadcom Inc. occupy positions shaped by decades of enterprise data center penetration. Microsoft Corporation anchors the cloud-native convergence archetype through Azure Stack integration for hybrid workloads. Huawei Technologies Co. Ltd. represents the geographically constrained specialist model, dominating procurement pools where Western market access restrictions fragment vendor selection. These three exemplify how competitive positioning depends on channel control depth, federal authorization status, and geographic market access rather than pure technology differentiation.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Microsoft Corporation |
| VMware Inc. |
| Cisco Systems Inc. |
| Dell Technologies Inc. |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Oracle Corporation |
| Huawei Technologies Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian IT services data centers is compressing licensing margins for global hypervisor vendors while simultaneously accelerating local partnership requirements under RBI data localization mandates.
Pricing Analysis
Current-generation proprietary hypervisors with embedded FedRAMP authorization command substantial premiums over prior-generation KVM-based stacks and next-generation container-native virtualization layers. Three-tier pricing structure across premium, standard, and economy levels separates US federal contractors with compliance requirements from mid-market enterprises and cost-sensitive Indian IT services firms. Pricing pressure stems from open-source alternatives eroding maintenance revenue streams in European cloud provider accounts. Healthcare systems in the United States exhibit lowest price sensitivity due to HIPAA-mandated audit trail requirements, while Indian telecommunications operators demonstrate highest sensitivity under sovereign cloud procurement budgets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for semiconductor-dependent hypervisor hardware acceleration. Software development concentrates in the United States, Germany, and India, with support services anchored in Bangalore and Munich engineering centers. Raw material dependencies include x86 silicon from Intel and AMD, memory modules from South Korean fabs, and networking ASICs from Taiwan. Single-source vulnerability in proprietary hypervisor licensing creates downstream concentration risk for Fortune 500 enterprises. Distribution runs through direct hyperscaler relationships and systems integrator channels, with channel-mediated transactions declining in US Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server virtualization software demand is recovering from infrastructure budget freezes as federal compliance mandates and climate-driven continuity planning force enterprise refresh cycles.
For Market Incumbents: Insulate recurring maintenance revenue by embedding compliance tooling directly into hypervisor platforms before open-source alternatives capture FedRAMP authorization. Pursue backward integration into container orchestration layers to defend against Kubernetes-orchestrated workload substitution threatening greenfield virtual machine deployments. Prioritize certification investment in Indian domestic infrastructure partnerships under MeitY sovereign cloud directives. For New Entrants and Emerging Players: Edge virtualization deployments in German automotive manufacturing clusters represent the most penetrable entry point for latency-sensitive bare-metal replacement workloads. Saudi government entities under national cloud-first policies offer captive procurement pools with reduced incumbent penetration. Target go-to-market execution through telecommunications equipment suppliers already embedded in 5G distributed core networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across open-source KVM-based virtualization stacks as cloud providers reduce proprietary licensing exposure. Long-term viability favors acquisition targets with embedded compliance tooling and federal authorization status rather than pure technology differentiation. Monitor FedRAMP authorization timelines as the critical inflection signal for revenue recognition velocity in government-facing virtualization vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies virtual machine and container control planes for hybrid cloud orchestration across Fortune 500 accounts. |
| Strategic Partnership | Establishes domestic hypervisor infrastructure with Indian IT services firms under RBI data localization mandates. |
| Acquisition of Specialist Firm | Adds embedded GDPR audit trail capabilities for German automotive and financial institution procurement requirements. |
| Geographic Expansion | Captures Saudi government virtualization contracts under national cloud-first data sovereignty frameworks. |
| Product Launch | Introduces edge-optimized hypervisor for 5G distributed core networks in Indian telecommunications infrastructure. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across the United States, Germany, and India. Secondary validation drew from SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and RBI circulars on data localization. Bottom-up triangulation against top-down market sizing ensured segment-level consistency across deployment models and industry verticals.
Calibration against historical virtualization spend patterns and infrastructure refresh cycles shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from growth rate convergence techniques applied to cloud migration velocity indicators and federal procurement authorization timelines.
Macroeconomic conditions sit as an overlay; deviation in enterprise capital expenditure budgets and sovereign cloud mandate enforcement timelines would shift the trajectory. Forecasts reflect assumptions about container-to-virtual-machine convergence pace and open-source adoption elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Construction Project Management Software Market
Software & Services
Global Intranet Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Multiexperience Development Platforms Market
Software & Services
Logistics Services Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Team Collaboration Software Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Software Repository Market
Software & Services
Landing Page Creation Software Market
Software & Services
Global Bug Tracking Software Market