
 Personal Budgeting Software Market | 2026-2036
Personal Budgeting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Budgeting Software Market Insights
Silicon Valley cloud infrastructure providers is repositioning delivery economics for personal budgeting platforms. Intuit leverages its tax software ecosystem to cross-sell budgeting tools at scale. YNAB sustains a subscription-only model that commands higher lifetime value per household. Quicken anchors the desktop-to-cloud transition with hybrid data migration services.
Personal budgeting software comprises digital applications that aggregate financial account data, categorize expenditures, and project cash flows against user-defined spending limits. These systems rely on encrypted API connections to banking networks, real-time transaction parsing engines, and machine-learning classification models to automate ledger maintenance. Mobile App deployments capture the fastest expansion as smartphone-native users reject desktop-bound workflows. Subscription-Based pricing dominates recurring revenue pools, while Freemium tiers serve as conversion funnels toward premium feature unlocks.
FCC guidelines on financial data transmission shape encryption standards for US-hosted platforms, while GDPR compliance obligations in Europe restrict cross-border aggregation of consumer banking records. Open banking regulations in the United Kingdom and Australia mandate standardized API access, lowering barriers for new entrants. Stakeholders must weigh regulatory fragmentation against the cost of region-specific compliance architectures.
Market Dynamics
Open banking API standardization is dismantling data silos that once protected incumbent budgeting platforms, forcing a wholesale rebuild of aggregation infrastructure around real-time consent protocols.
Growth Catalysts
- PSD2 Open Banking Mandate:European regulations compel retail banks to expose standardized APIs, slashing data acquisition costs for budgeting app developers.
- Cloud-Native Mobile Architectures:Smartphone-native users reject desktop-bound workflows, accelerating displacement of legacy installed software.
- Machine-Learning Classification:Automated transaction categorization engines reduce manual ledger maintenance to near-zero for household subscribers.
Market Restraints
- GDPR Cross-Border Friction:European data residency requirements block seamless aggregation of consumer banking records hosted outside EU jurisdiction.
- Encryption Compliance Burden:FCC guidelines on financial data transmission force US-hosted platforms to maintain parallel technical architectures.
- Screen Scraping Instability:Reliance on brittle non-API data extraction methods exposes budgeting tools to unilateral bank interface changes.
Strategic Opportunities
- Underpenetrated Emerging Markets:India and Brazil lack mature open banking frameworks, creating first-mover advantage for API-native entrants.
- Embedded Finance Convergence:Budgeting functionality is converging with neobank operating systems, collapsing standalone subscription models.
- Consumer Data Right Expansion:Australia's CDR regime extends beyond banking to utilities and telecommunications, broadening household financial visibility.
Industry Challenges
- Plaid-Style API Dependency:Concentrated third-party aggregator risk creates single-point-of-failure exposure for downstream budgeting platforms.
- Consent Fatigue Management:Repeated re-authentication requirements under OAuth 2.0 protocols degrade user retention curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Budgeting Software Market |
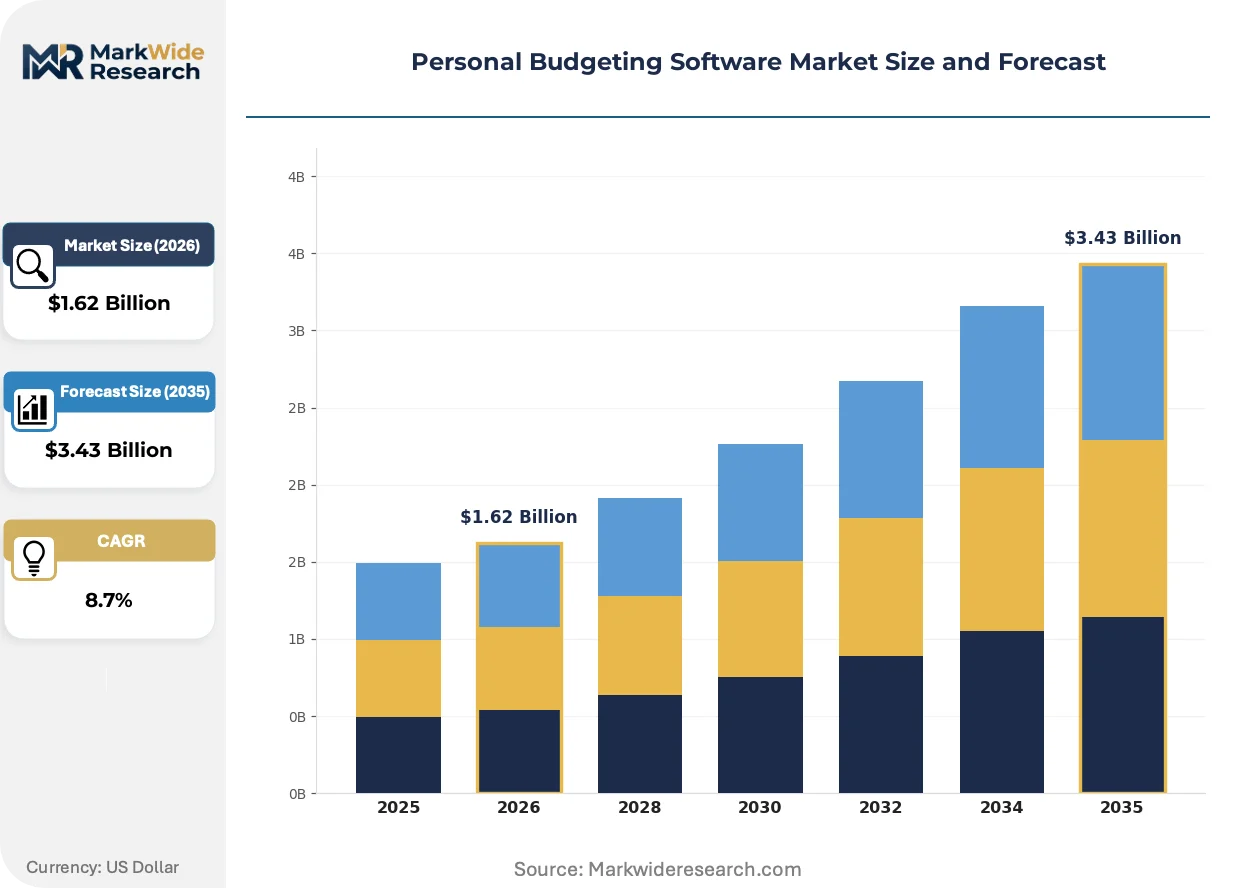
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile App, Web App, Desktop Software, Software as a Service End User: Individuals, Families, Small Businesses, Financial Advisors Feature: Expense Tracking, Budget Planning, Financial Reporting, Goal Setting Pricing Model: Subscription-Based, One-Time Purchase, Freemium, Pay-Per-Use |
| Companies Covered | Mint, You Need a Budget (YNAB), Quicken, Personal Capital, Intuit, Buxfer, Mvelopes, Tiller Money, BankTree Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Budgeting Software Market Trends and Innovations
Real-time financial data streaming is collapsing the latency between transaction occurrence and budget impact visibility, compressing household decision cycles from monthly to instantaneous.
Embedded AI coaching engines are converging with behavioral psychology frameworks to deliver just-in-time spending interventions. Young professionals in the United States adopt these proactive nudge systems fastest. The technology is converging with subscription management tools to automate cancellation recommendations for redundant services.
GDPR Article 20 portability rights are forcing budgeting platforms to engineer seamless data export capabilities. Compliance teams now embed portability by design rather than retrofitting post-audit. European households leverage these rights to switch providers without losing historical transaction context.
Aggregator-agnostic procurement is displacing single-vendor bank data contracts. Mid-sized fintechs now demand multi-source redundancy in their data supply agreements. This pattern is most visible among United Kingdom neobanks building resilience against open banking provider consolidation.
Personal Budgeting Software Market Segmentation
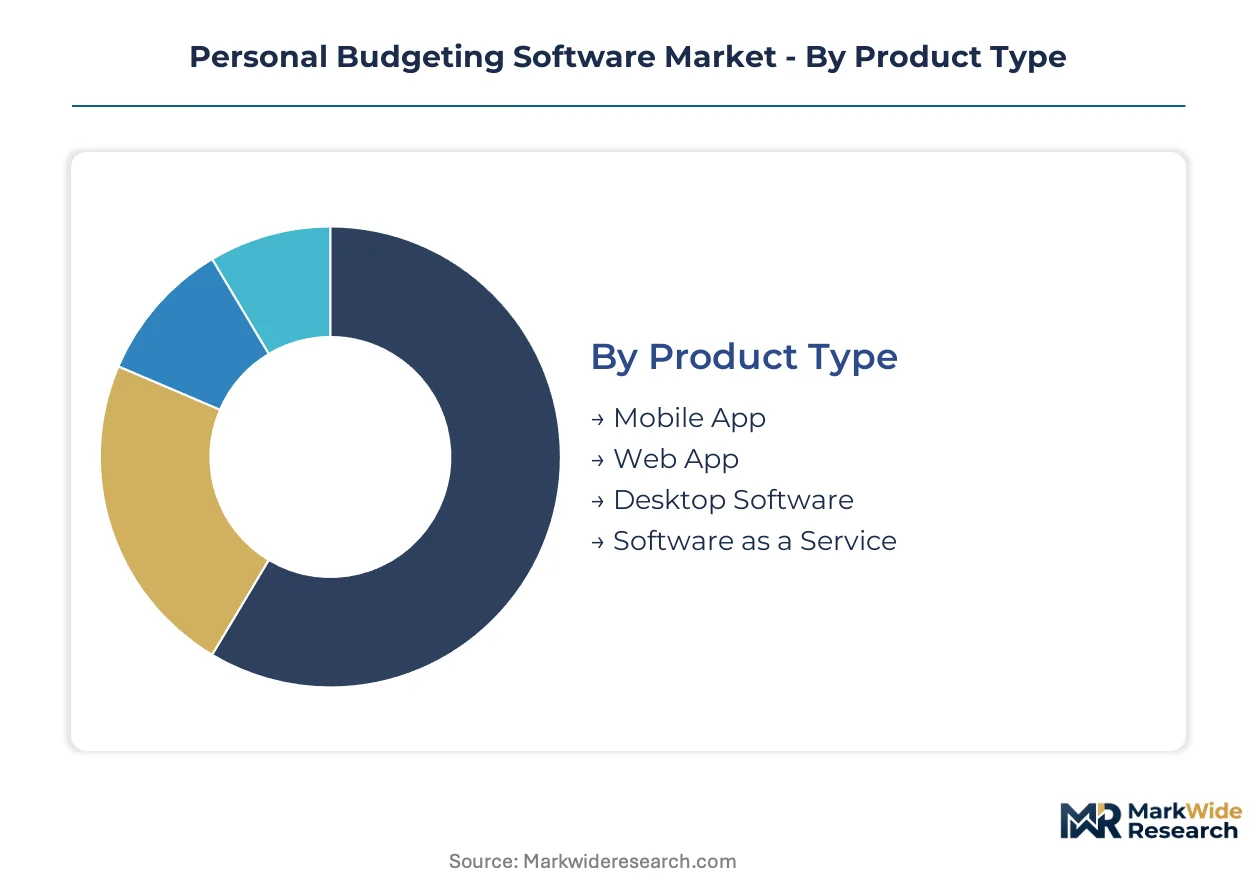
Personal budgeting software segments fragment across deployment architectures, user contexts, and monetization mechanics. Each dimension carries distinct technical requirements and compliance obligations that reshape competitive positioning.
Product Type:
Mobile App deployments integrate most deeply with smartphone-native banking workflows, while Desktop Software retains standalone installation footprints for privacy-conscious households.
- Mobile App:Native iOS and Android applications leverage biometric authentication and push notification pipelines for real-time spending alerts. Demand concentrates among young professionals in the United States where smartphone banking penetration runs deepest, though FCC encryption guidelines force parallel technical architectures for data transmission.
- Web App:Browser-based platforms deliver cross-device synchronization without app store distribution friction. Small business adoption in the United Kingdom accelerates under PSD2 open banking mandates that standardize API access across retail banks.
- Desktop Software:Local-install applications store financial data on-device, appealing to households with heightened privacy sensitivity. Legacy migration services now dominate vendor roadmaps as cloud displacement accelerates.
- Software as a Service:Multi-tenant cloud architectures amortize infrastructure costs across subscriber bases. GDPR Article 20 portability requirements reshape engineering priorities for European deployments.
Volume placements concentrate in Mobile App; the faster expansion belongs to Software as a Service.
End User:
Cost tier stratification separates premium subscription households from freemium individual adopters, with advisory channels commanding the highest per-seat pricing.
- Individuals:Single-household subscribers prioritize automated transaction categorization and goal visualization dashboards. Consent fatigue under OAuth 2.0 protocols degrades retention curves for this price-sensitive cohort.
- Families:Multi-user license structures enable parental oversight of dependent spending with granular permission controls. Shared budget visibility drives adoption in dual-income United States households managing complex cash flow coordination.
- Small Businesses:Self-employed operators require tax-ready expense segregation and quarterly estimated payment projections. Australia's Consumer Data Right regime extends utility and telecommunications aggregation, broadening financial visibility for this segment.
- Financial Advisors:White-label platforms embed client-facing dashboards with advisor-branded reporting. Compliance documentation features satisfy SEC record-keeping obligations for United States registered investment advisers.
Revenue concentration sits with Individuals; Financial Advisors deliver the steepest expansion trajectory.
Feature:
Application maturity varies from basic ledger maintenance to predictive behavioral intervention systems.
- Expense Tracking:Real-time transaction ingestion via encrypted banking APIs forms the foundational layer of all budgeting platforms. Machine-learning classification engines reduce manual categorization to near-zero for household subscribers.
- Budget Planning:Envelope-style allocation systems and zero-based budgeting frameworks target debt reduction behaviors. YNAB's subscription-only model commands premium lifetime value through intensive user education.
- Financial Reporting:Customizable cash flow statements and net worth tracking satisfy tax preparation workflows. Intuit leverages its tax software ecosystem to cross-sell reporting tools at scale.
- Goal Setting:AI coaching engines converge with behavioral psychology frameworks to deliver just-in-time spending interventions. Young professionals in the United States adopt these proactive nudge systems fastest.
Deployment breadth favors Expense Tracking; Goal Setting gains share fastest through embedded finance convergence.
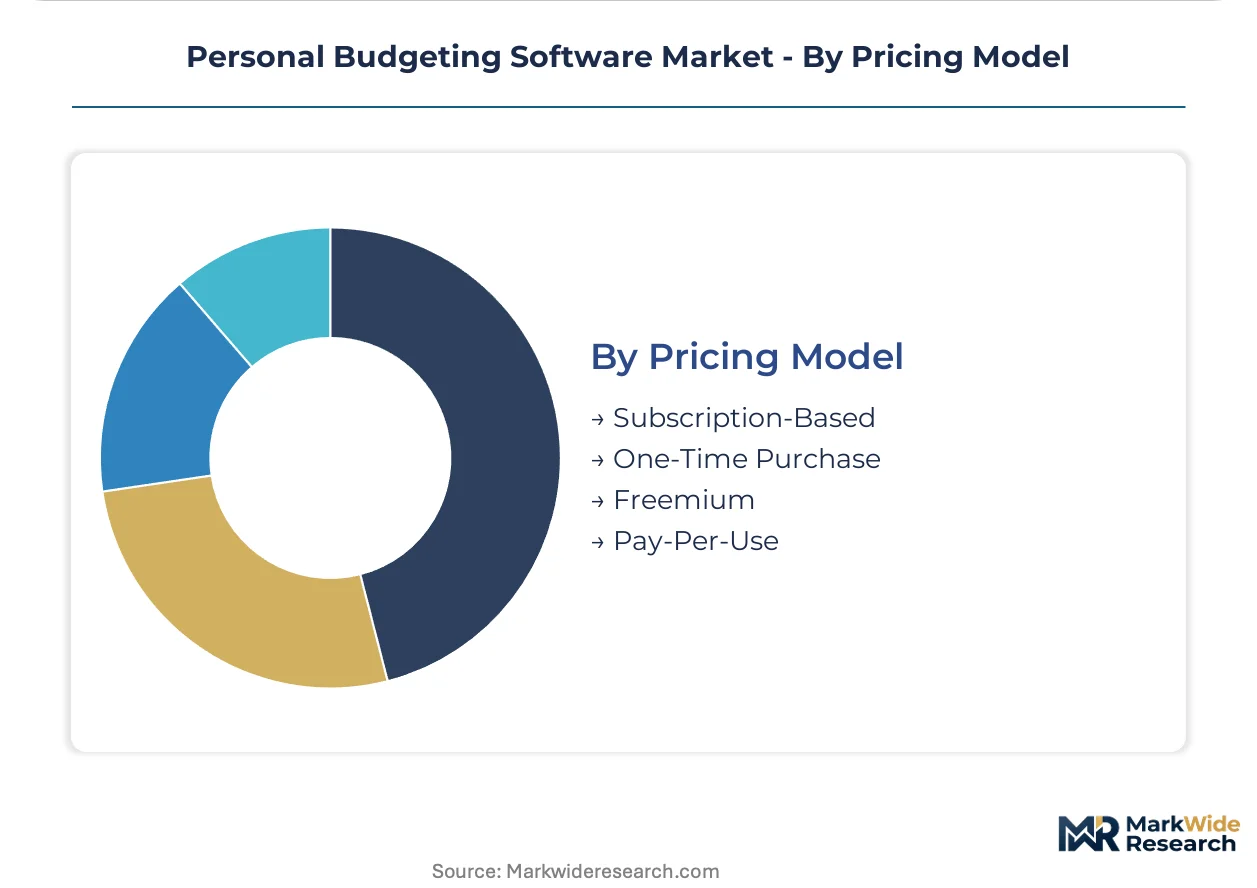
Pricing Model:
Monetization architecture determines customer acquisition economics and lifetime value extraction patterns.
- Subscription-Based:Recurring monthly or annual fees sustain predictable revenue streams with premium feature gating. This model dominates vendor preference for household budgeting tools.
- One-Time Purchase:Perpetual licenses with optional upgrade fees persist in desktop software segments. Declining share reflects cloud displacement and mobile-first user expectations.
- Freemium:Tiered feature unlocks convert non-paying users to premium subscriptions through usage-based triggers. Conversion funnels optimize around bank account aggregation depth.
- Pay-Per-Use:Transaction-volume or report-generation fees target intermittent users with sporadic financial planning needs. Limited adoption reflects subscription preference for ongoing budget maintenance.
Revenue capture concentrates in Subscription-Based; Freemium delivers the fastest user base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure clusters in Silicon Valley supply the server backbone for North American budgeting platforms, while open banking API standardization in London and Sydney redraws data aggregation economics across multiple jurisdictions.
United States
Young professionals in metropolitan tech corridors drive mobile-first adoption of AI coaching engines and real-time spending alerts. FCC encryption guidelines on financial data transmission force parallel technical architectures for domestic hosting. Silicon Valley cloud providers reposition delivery economics for subscription-based platforms competing on lifetime value extraction.
United Kingdom
PSD2 open banking mandates slash data acquisition costs for neobank-integrated budgeting tools across Greater London and Manchester fintech clusters. The Financial Conduct Authority enforces standardized API access that lowers barriers for new entrants building real-time consent protocols. Edinburgh and Bristol host emerging white-label platforms serving financial advisory channels.
Australia
The Consumer Data Right regime extends banking aggregation to utilities and telecommunications, broadening household financial visibility in Sydney and Melbourne. Australian Competition and Consumer Commission oversight shapes consent management frameworks for cross-sector data portability. Brisbane neobanks embed budgeting functionality directly into operating systems, collapsing standalone subscription models.
Germany
Privacy-conscious households in Bavaria and North Rhine-Westphalia sustain demand for desktop-localized data storage amid cloud displacement trends. BaFin supervision of financial data processors imposes stringent residency requirements that block seamless cross-border aggregation. Berlin fintech clusters experiment with aggregator-agnostic procurement to build resilience against open banking provider consolidation.
India
Account aggregator frameworks under RBI supervision create first-mover opportunities for API-native entrants in Mumbai and Bangalore. The central bank's data localization directives reshape engineering priorities for foreign platforms seeking household market access. Hyderabad and Pune host emerging mobile-first platforms targeting self-employed operators with tax-ready expense segregation tools.
Personal Budgeting Software Market Competitive Landscape
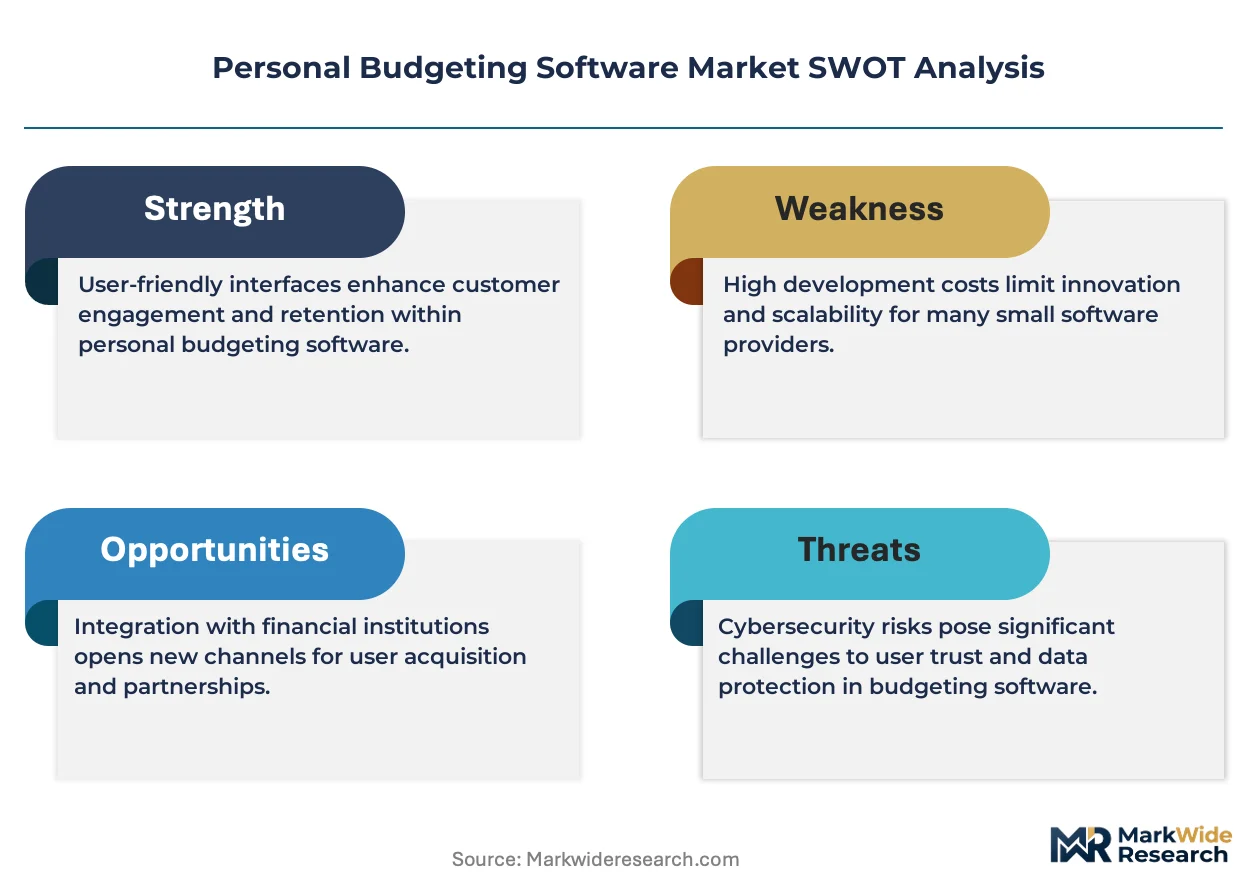
Global majors compete with regional champions across data aggregation infrastructure and subscription monetization models. The vendor base stratifies into three tiers: ecosystem-anchored incumbents with cross-sell capabilities, subscription-pure specialists commanding premium lifetime value, and freemium-native challengers optimizing conversion funnels. Dominant competitive moves include hybrid data migration services for desktop-to-cloud transitions and embedded finance convergence with neobank operating systems.
Within the ecosystem-anchored tier, Intuit leverages tax software cross-sell infrastructure while Quicken occupies a position bridging legacy desktop retention with cloud-native acquisition. YNAB exemplifies the subscription-pure specialist archetype through intensive user education frameworks that sustain premium pricing. These three entities represent distinct monetization philosophies competing for household budget management share across North American and European markets.
| Leading Market Players |
|---|
| Mint |
| You Need a Budget (YNAB) |
| Quicken |
| Personal Capital |
| Intuit |
| Buxfer |
| Mvelopes |
| Tiller Money |
| BankTree Software |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure costs originating from Silicon Valley hyperscalers cascade through subscription pricing tiers, with compute and storage outlays absorbing margin compression before reaching end-user rate cards across mobile-first deployments.
Pricing Analysis
Warranty-style service bundling separates premium subscriptions from stripped-down freemium tiers, with white-glove onboarding and dedicated customer success managers reserved for financial advisory channels. Subscription-based recurring revenue dominates household budgeting tools, while price differentiation hinges on bank account aggregation depth and AI coaching engine sophistication. Pricing pressure stems from embedded finance convergence collapsing standalone subscription models into neobank operating systems. Individual subscribers exhibit highest price sensitivity, whereas financial advisory channels tolerate premium positioning for compliance documentation features.
Supply Chain Analysis
Single-source vulnerability sits with Plaid-style API aggregators concentrated in the United States, creating downstream exposure for budgeting platforms dependent on unified banking data pipes. Supply concentration clusters in the United States, the United Kingdom, and Australia where open banking frameworks mature fastest. Raw material dependencies center on encrypted API connections, real-time transaction parsing engines, and machine-learning classification models. Tariff exposure remains minimal, though regulatory fragmentation across FCC encryption guidelines and GDPR residency requirements forces parallel technical architectures. Distribution runs through direct-to-consumer app stores and white-label partnerships with neobank platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open banking API standardization is forcing consolidation as data aggregation economics shift toward real-time consent protocols, squeezing platforms lacking multi-source redundancy or embedded finance partnerships.
For Market Incumbents: To counter Plaid-style API dependency threatening single-point-of-failure exposure, incumbents must engineer aggregator-agnostic procurement with multi-source data supply agreements and deepen embedded finance integration with neobank operating systems to defend subscription revenue pools against convergence pressures. For New Entrants and Emerging Players: Enter via underpenetrated emerging markets lacking mature open banking frameworks, specifically targeting self-employed operators in India with tax-ready expense segregation tools and leveraging account aggregator frameworks under RBI supervision to establish API-native positioning before incumbent hybrid migration services arrive. For Investors and Strategic Acquirers: Australia's Consumer Data Right expansion beyond banking to utilities and telecommunications is the leading indicator that regulatory-driven data portability will reshape competitive moats, suggesting five-to-ten-year viability favors acquisition targets with compliance-embedded engineering teams and cross-sector aggregation capabilities rather than single-vertical specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded finance convergence with neobank operating systems collapses standalone subscription models. |
| Geographic Expansion | First-mover entry into India and Brazil exploits immature open banking frameworks before incumbent arrival. |
| Strategic Partnership | Aggregator-agnostic data supply agreements build resilience against Plaid-style provider consolidation. |
| Product Launch | AI coaching engines with behavioral psychology frameworks capture young professional adoption fastest. |
| Acquisition of Specialist Firm | White-label platform capabilities satisfy SEC record-keeping obligations for registered investment advisers. |
Research Methodology
Document review covered SEC filings from public fintech platforms, App Annie mobile engagement metrics, and open banking regulatory disclosures from the FCA and ACCC, complemented by interviews with CTOs at subscription-based budgeting platforms, neobank product officers, financial advisory compliance leads, and API aggregator partnership directors. Secondary validation drew from FCC encryption guideline updates, GDPR Article 20 portability rulings, and RBI account aggregator framework circulars. Bottom-up subscriber modeling triangulated against top-down addressable household calculations.
Market sizing outputs combined deployment architecture splits with monetization model penetration curves across the projection horizon. Segmentation dimensions spanned product type, end user context, feature maturity tier, and pricing model architecture. CAGRs derived from cohort-based retention analysis and cross-sell elasticity parameters. Forecast inputs incorporated OAuth 2.0 consent fatigue decay rates and open banking API adoption velocity by regulatory jurisdiction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt open banking mandate delays or unilateral bank interface changes disrupting screen-scraping fallback methods. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Parametric Design Software Market
Software & Services
Content Distribution Software Market
Software & Services
Runtime Software Market
Software & Services
Servicenow Tech Services Market
Software & Services
Vacation Rental Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Salesforce Services Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Server Software Market
Software & Services
Global Open API Market
Software & Services
RFP Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Global Restaurant Management Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Content Curation Software Market