
 Education Data Security Market | 2026-2036
Education Data Security Market Size, Share, and Industry Trends Forecast 2026-2036
Education Data Security Market Analysis
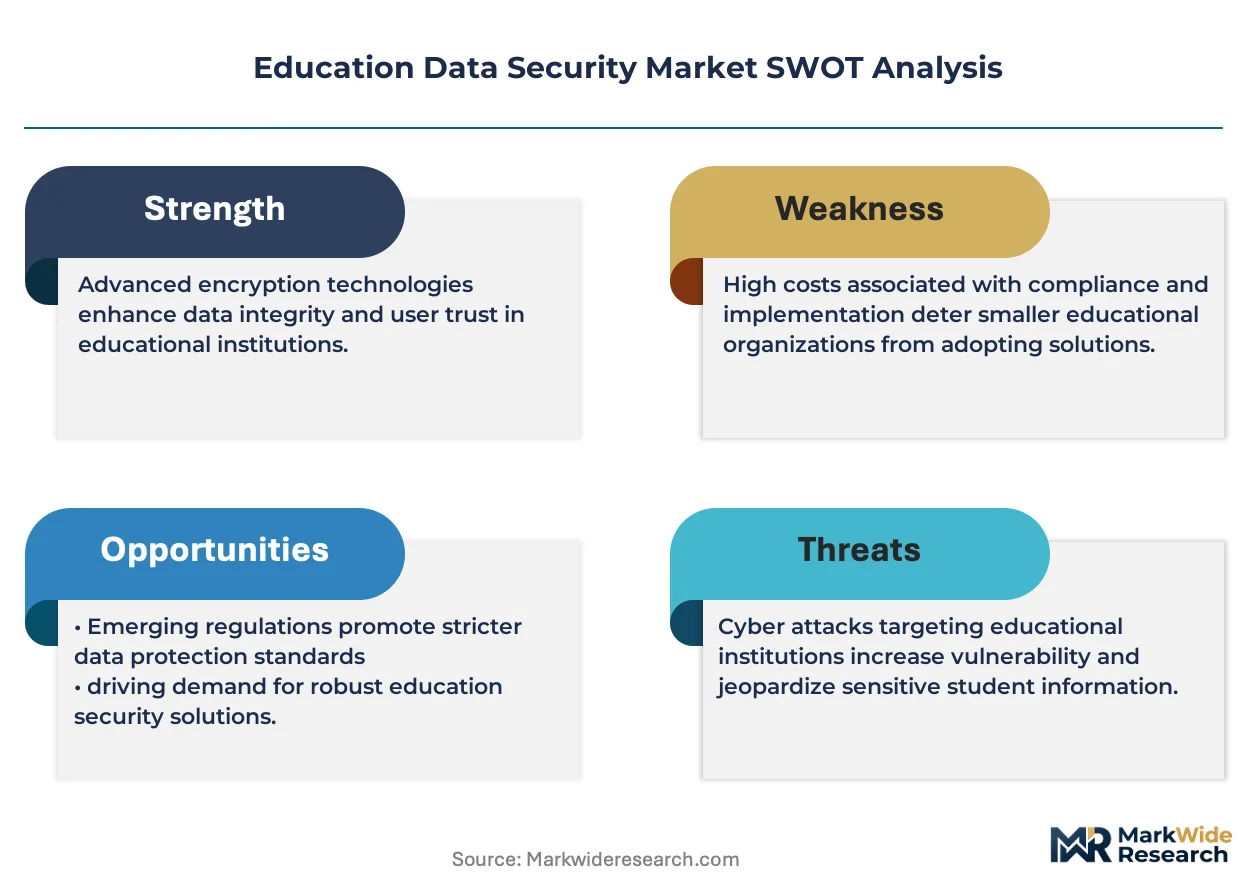
Multi-source vendor strategies is recalibrating how education institutions procure data security capabilities. IBM sustains broad platform integration across hybrid cloud environments, while Cisco dominates network-layer security for campus infrastructure. Varonis specializes in data access governance tailored to academic research datasets.
Education data security encompasses technical systems, protocols, and administrative controls designed to protect student records, institutional research, and administrative databases from unauthorized access, breach, or loss, typically operating across encryption standards of 256-bit AES or higher and zero-trust network architectures. Cloud-based deployment is outpacing on-premises alternatives as universities seek elastic capacity for enrollment spikes and remote learning surges. Identity management solutions command premium positioning within the solution stack due to federated access requirements spanning multiple campus systems and external learning platforms.
FERPA mandates in the United States, GDPR across European Union jurisdictions, and ISO 27001 certification frameworks collectively shape procurement specifications and vendor qualification criteria for education buyers. HIPAA intersects where institutions operate teaching hospitals or health sciences programs, adding layered compliance obligations. Stakeholders must weigh interoperability against compliance scope when selecting architectures that span K-12, higher education, and online platform environments.
Market Dynamics
Universities are dismantling perimeter-based security architectures in favor of zero-trust frameworks that verify every access request regardless of network location. This architectural pivot is compressing procurement cycles and forcing legacy vendors to requalify under new technical specifications.
Growth Catalysts
- Federated identity requirements:Multi-campus systems and external learning management platforms are mandating single-sign-on protocols that scale across thousands of concurrent users. Institutions are prioritizing vendors with SAML and OIDC native support.
- GDPR Article 32 mandates:European universities face explicit encryption and breach notification obligations for student data processing. Compliance deadlines are accelerating replacement of unencrypted legacy databases.
- Research data monetization:Academic medical centers and public health programs are commercializing longitudinal datasets under HIPAA business associate agreements. This creates demand for granular access logging and data loss prevention tooling.
Market Restraints
- Specialized cybersecurity talent scarcity:Higher education IT departments compete with financial services and defense contractors for personnel holding CISSP or GIAC certifications. Salaries in university systems lag private sector benchmarks by 30-40 percent.
- Fragmented procurement authority:State university systems in the United States delegate security purchasing to individual campuses, preventing volume consolidation. This structural dispersion limits vendor negotiation leverage and extends sales cycles.
- Technical debt in on-premises infrastructure:Decades-old student information systems lack API compatibility with modern security orchestration platforms. Migration costs often exceed annual cybersecurity budgets at mid-tier institutions.
Strategic Opportunities
- India's National Education Policy implementation:The 2020 framework mandates digital infrastructure upgrades across 40,000 higher education institutions. Centralized procurement through the National Informatics Centre creates a unified addressable market for cloud-native security suites.
- Convergence of AI and privacy-preserving analytics:Differential privacy and federated learning techniques are enabling institutions to share research insights without raw data exposure. Vendors integrating these cryptographic methods gain preference in multi-institution consortia.
- K-12 endpoint protection gaps:Primary and secondary districts in the United States deploy one-to-one device programs without corresponding security staffing. Managed security service providers are capturing this underserved segment through subscription models.
Industry Challenges
- Interoperability certification timelines:FERPA-compliant systems must demonstrate audit logging compatibility with state longitudinal data systems. Certification delays of 12-18 months stall product rollouts and strain vendor cash flows.
- Incident response capability gaps:Most institutions lack 24/7 security operations centers. Ransomware attacks during enrollment periods expose operational fragility and drive reactive rather than strategic purchasing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education Data Security Market |
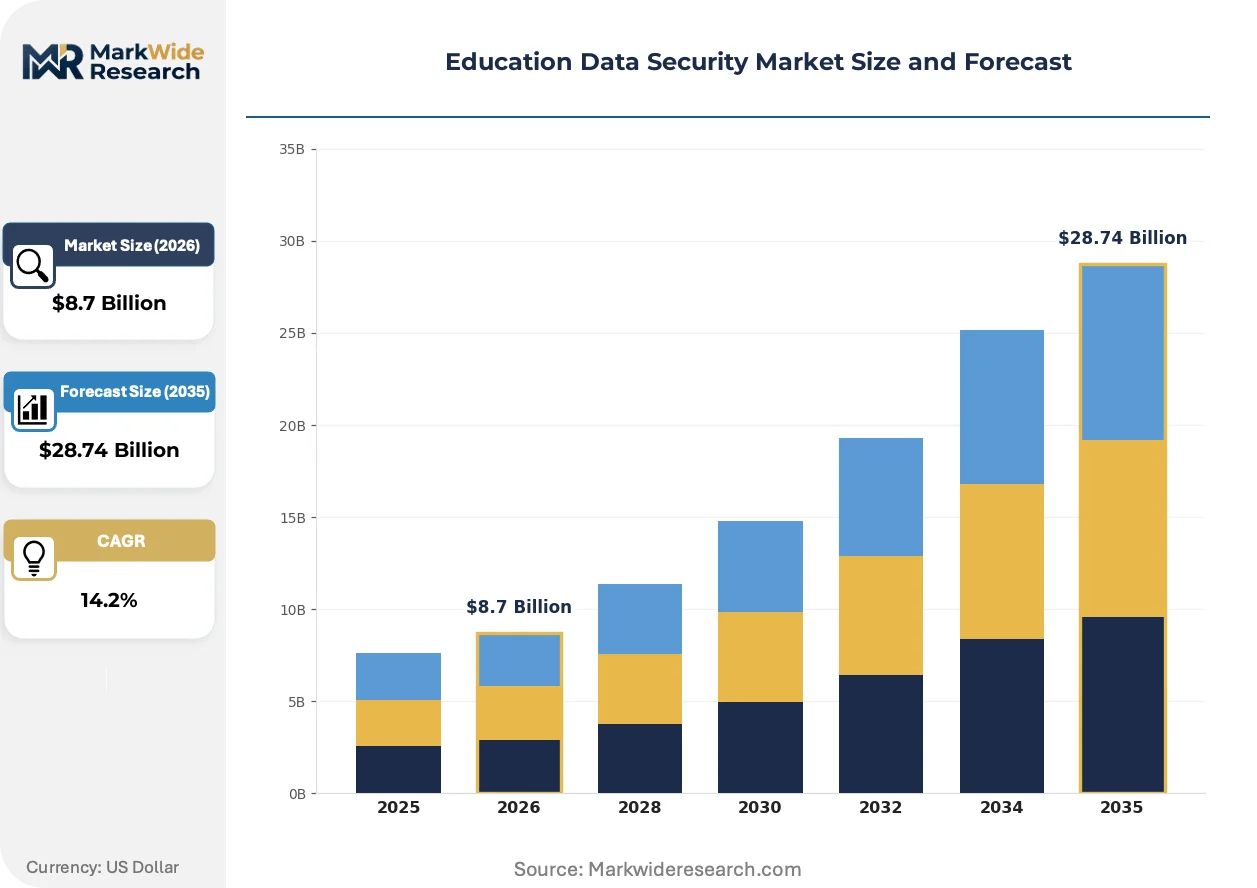
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Encryption, Firewall, Identity Management, Antivirus End User: Higher Education Institutions, K-12 Schools, Online Learning Platforms, Educational Publishers Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Regulatory Compliance: FERPA, GDPR, HIPAA, ISO Standard |
| Companies Covered | Sentra, IBM, Varonis, Cisco, Microsoft, BigID, Cyera, Blackbaud, Immuta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education Data Security Market Emerging Trajectories
Security architectures are converging around identity-centric models that treat user credentials as the primary attack surface. This reorientation is elevating privileged access management from a compliance checkbox to a core infrastructure decision.
Secure access service edge (SASE) platforms are unifying network security and wide-area networking into cloud-delivered services. Mid-sized universities with distributed satellite campuses are adopting these consolidated stacks to eliminate hardware refresh cycles. The technology is unifying procurement decisions that previously required separate vendor relationships for firewalls, SD-WAN, and cloud access security brokers.
GDPR enforcement actions by CNIL in France and ICO in the United Kingdom are establishing precedent for fines against universities processing alumni data without explicit consent. Institutions are responding by deploying consent management platforms and data mapping exercises that were previously limited to corporate environments. Research-intensive universities with international student populations face the highest exposure and are accelerating privacy-by-design investments.
Subscription-based security service models are displacing perpetual license purchases in North American higher education. Chief information officers prefer operational expenditure treatment that aligns costs with enrollment fluctuations. This preference shift is most pronounced among community colleges and regional public universities with volatile state funding cycles.
Education Data Security Market Segmentation
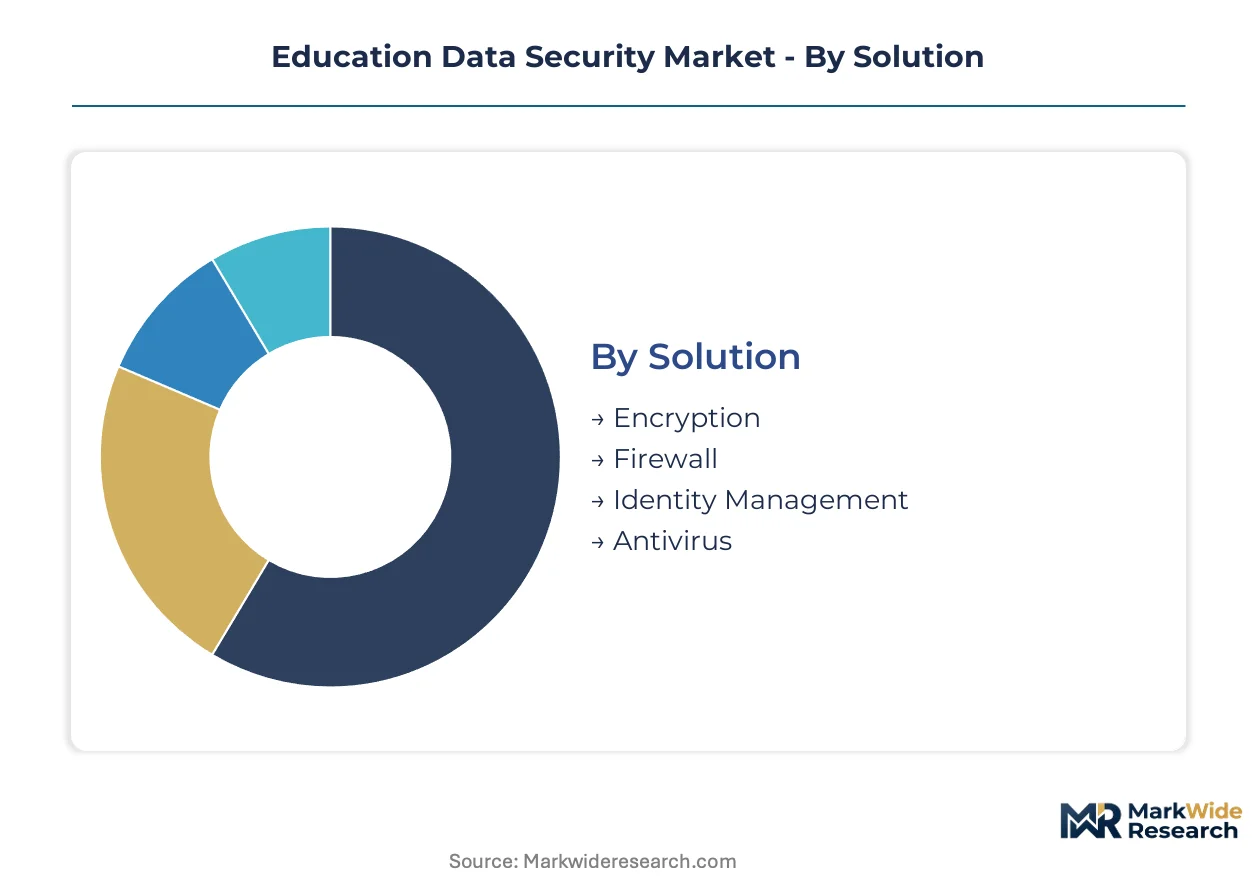
Education data security procurement varies sharply by institutional scale and regulatory exposure. Buyers configure solution stacks differently depending on whether they operate centralized research universities, distributed K-12 districts, or commercial learning platforms.
Solution:
Customization intensity spans from commodity antivirus to bespoke identity architectures, with premium tiers commanding specialized implementation services.
- Identity Management:SAML and OIDC protocols federate access across campus ERP, LMS, and cloud productivity suites. Demand concentrates in multi-campus university systems in the United States and United Kingdom where FERPA and GDPR obligations overlap for international student populations.
- Encryption:256-bit AES standards protect longitudinal research datasets and student transcripts at rest and in transit. Medical schools and academic health centers under HIPAA business associate agreements drive hardware security module deployments for key management.
- Firewall:Next-generation platforms inspect SSL/TLS traffic for research collaboration networks.
- Antivirus:Endpoint detection and response tools cover one-to-one device programs in primary and secondary districts.
Leading the category by volume: Antivirus. Expanding most quickly: Identity Management.
End User:
Procurement authority and budget cycles diverge across institutional types, from centralized university CIO offices to fragmented school district IT departments.
- Higher Education Institutions:Research-intensive universities deploy zero-trust architectures across hybrid cloud environments. Demand clusters in R1 doctoral institutions with medical centers, where FERPA, HIPAA, and NIH data sharing requirements create layered compliance obligations.
- K-12 Schools:Primary and secondary districts prioritize endpoint protection for student Chromebooks and tablets. Budget constraints favor subscription-based managed security services over in-house security operations centers.
- Online Learning Platforms:Commercial providers process cross-border enrollment data requiring GDPR Article 32 encryption and breach notification capabilities.
- Educational Publishers:Assessment platforms and adaptive learning systems protect proprietary item banks and student performance analytics.
Dominant by procurement value: Higher Education Institutions. Gaining share fastest: Online Learning Platforms.
Deployment:
Capital expenditure preferences and technical debt levels shape architecture choices across legacy-dependent and cloud-native institutions.
- Cloud-Based:Elastic capacity accommodates enrollment spikes and remote learning surges without hardware refresh cycles. Mid-sized regional universities in the United States and Canada prefer operational expenditure treatment aligned with volatile state funding.
- Hybrid:Split architectures preserve on-premises student information systems while migrating research collaboration tools to cloud platforms. European universities under GDPR maintain local data residency for core administrative records.
- Managed Services:24/7 security operations center coverage addresses talent scarcity at institutions competing with private sector cybersecurity salaries.
- On-Premises:Legacy deployments persist where decades-old student information systems lack API compatibility with modern orchestration platforms.
Deployment mode with steepest expansion trajectory: Cloud-Based. Retaining largest installed base: On-Premises.
Regulatory Compliance:
Certification requirements function as vendor qualification filters, with overlapping mandates complicating procurement for multi-jurisdictional institutions.
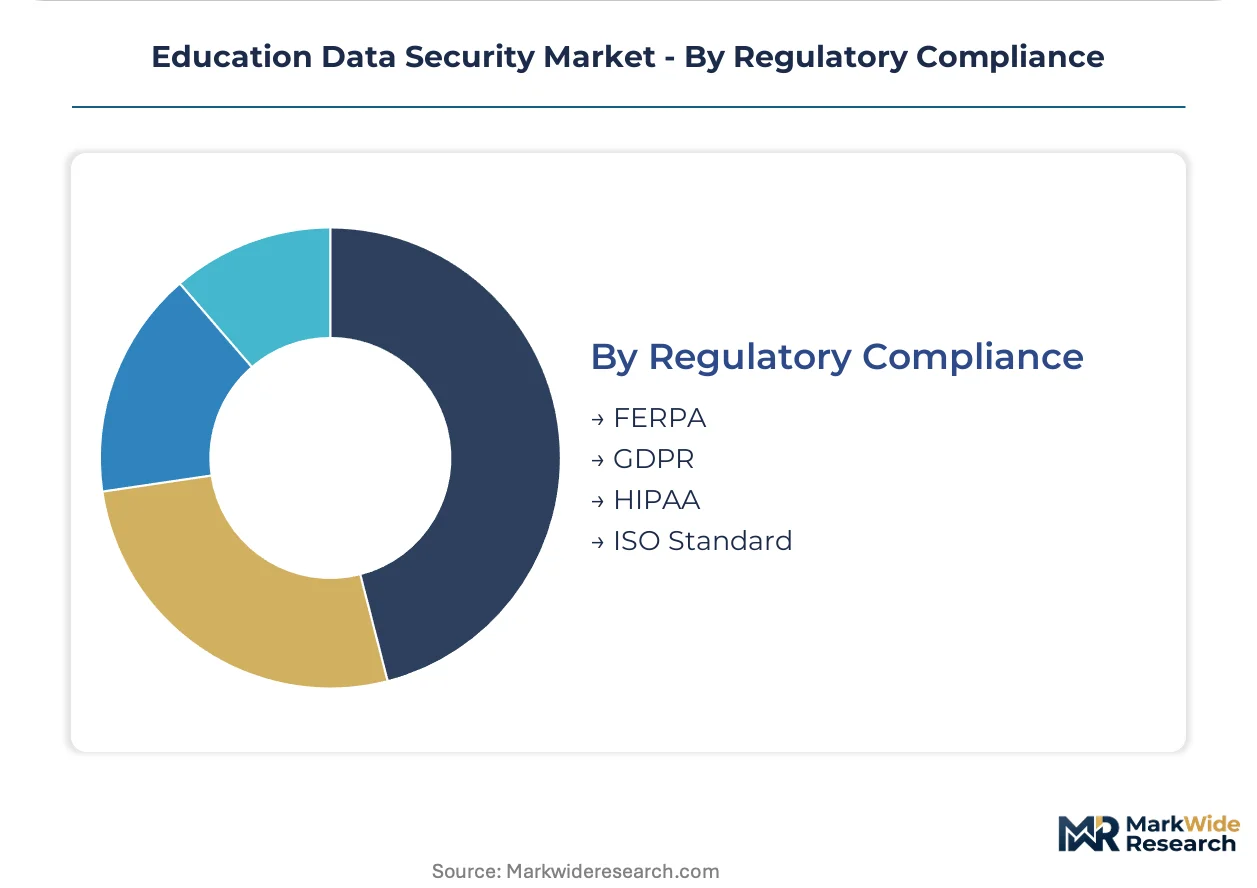
- GDPR:Article 32 mandates explicit encryption and 72-hour breach notification for student data processing. CNIL enforcement actions against French universities processing alumni data without consent are accelerating privacy-by-design investments.
- FERPA:Audit logging compatibility with state longitudinal data systems requires 12-18 month certification timelines that stall product rollouts.
- HIPAA:Intersects where institutions operate teaching hospitals or health sciences programs, adding business associate agreement obligations for research data monetization.
- ISO Standard:27001 certification frameworks provide vendor-neutral assurance for international procurement evaluations.
Compliance framework with broadest geographic coverage: GDPR. Most institution-specific: FERPA.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Education data security procurement concentrates in jurisdictions with overlapping regulatory mandates and substantial digital infrastructure investments. Institutions in the United States, United Kingdom, Germany, India, and Australia generate disproportionate demand due to federated campus systems and research data monetization pressures.
United States
Higher education institutions deploy zero-trust architectures across hybrid cloud environments to accommodate enrollment volatility. FERPA mandates audit logging compatibility with state longitudinal data systems, compelling vendors to undergo 12-18 month certification cycles. Research-intensive universities in Massachusetts and California drive demand for granular access governance tools protecting longitudinal health datasets.
United Kingdom
Universities process cross-border enrollment data from EU and Commonwealth markets under GDPR Article 32 encryption requirements. ICO enforcement actions against institutions processing alumni data without explicit consent accelerate privacy-by-design investments. London-based research consortia adopt differential privacy techniques for multi-institution analytics without raw data exposure.
Germany
Technical universities maintain on-premises student information systems while migrating research collaboration tools to cloud platforms under GDPR data residency constraints. The country's national data protection authority enforces strict breach notification timelines for academic medical centers. Bavarian institutions lead adoption of hardware security modules for key management in health sciences programs.
India
The 2020 National Education Policy mandates digital infrastructure upgrades across 40,000 higher education institutions. Centralized procurement through the National Informatics Centre creates unified addressable markets for cloud-native security suites. Karnataka and Telangana host concentrated EdTech corridors where institutions seek elastic capacity for remote learning surges.
Australia
Universities with substantial international student populations face layered compliance obligations spanning GDPR for EU enrollees and domestic privacy legislation. Research-intensive institutions in New South Wales and Victoria commercialize longitudinal datasets under stringent access logging requirements. Subscription-based security service models displace perpetual licenses amid volatile state funding cycles.
Education Data Security Market Vendor Landscape
Platform consolidation dominates the current landscape as vendors bundle identity, network, and data governance capabilities into unified stacks. The vendor base organizes around three strategic archetypes: cloud-native specialists, legacy infrastructure incumbents with hybrid cloud pivots, and managed security service providers addressing talent scarcity. M&A activity concentrates in identity management and data loss prevention segments, while strategic partnerships between hardware security module manufacturers and cloud platforms accelerate.
Within the legacy infrastructure tier, IBM and Cisco occupy positions representing decades-long campus relationships now extending into zero-trust architectures. Microsoft exemplifies the cloud-native archetype through productivity suite integration that captures federated identity procurement decisions. Varonis anchors the data governance specialist segment with academic research dataset protections. These three entities collectively illustrate how vendor qualification criteria now prioritize SAML and OIDC protocol support alongside encryption standards.
| Leading Market Players |
|---|
| Sentra |
| IBM |
| Varonis |
| Cisco |
| Microsoft |
| BigID |
| Cyera |
| Blackbaud |
| Immuta |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up identity management specialists now control substantial vendor consolidation in education data security, compressing margin structures for mid-tier encryption providers while concentrating pricing power among platform-integrated incumbents. This ownership pattern reshapes procurement negotiations as universities face bundled SaaS offerings that obscure component-level cost transparency.
Pricing Analysis
Volume concentrates in subscription-based endpoint protection for K-12 districts while margins accrue to identity management suites with SAML and OIDC native support. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth, with FERPA-audit-ready configurations commanding substantial premiums over baseline encryption tiers. Pricing pressure stems from managed security service providers undercutting in-house security operations center costs for resource-constrained regional universities. Community colleges exhibit highest price sensitivity due to volatile state funding cycles, whereas research-intensive R1 institutions prioritize compliance-grade configurations regardless of cost.
Supply Chain Analysis
Dual-sourcing requirements from university procurement offices mandate qualified secondary vendors for hardware security modules and cloud access security brokers, preventing single-source lock-in despite integration preferences. Component manufacturing concentrates in Taiwan for semiconductor-based encryption processors, the United States for zero-trust network architecture software, and Germany for hardware security module fabrication. Supply chains draw from specialized cryptographic chip foundries, open-source identity protocol libraries, and certified data center infrastructure. Single-source vulnerability persists in FERPA-compliant audit logging modules where only three vendors maintain state longitudinal data system certification. Distribution runs through value-added resellers with education sector specialization and direct hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Education data security is becoming a vertical-integration race as platform vendors capture federated identity decisions upstream and managed security service providers consolidate downstream operational capabilities. Incumbents and challengers alike must secure control over SAML and OIDC protocol implementation to anchor procurement relationships.
For Market Incumbents: Anticipate displacement by cloud-native entrants offering SASE-unified stacks that eliminate separate firewall and SD-WAN procurement decisions. Defensive consolidation moves require acquiring data loss prevention specialists with academic research dataset expertise and embedding zero-trust architecture certification into existing campus relationships. Capacity addition in India's National Informatics Centre procurement channels secures volume positioning against sovereign-backed competitors. For New Entrants and Emerging Players: Launch via subscription-based managed security service models targeting underserved K-12 districts with one-to-one device programs and minimal in-house cybersecurity staffing. White-space targets include privacy-preserving analytics tooling for multi-institution research consortia and consent management platforms responding to CNIL and ICO enforcement precedents. The most penetrable segment comprises regional public universities with hybrid cloud migrations stalled by technical debt in legacy student information systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor data governance specialists with HIPAA business associate agreement credentials in the United States and United Kingdom, where research data monetization pressures accelerate replacement demand. Long-term viability hinges on positioning for GDPR Article 32 compliance convergence across European and Asia-Pacific education corridors. The signal to watch is National Informatics Centre centralization velocity in India, which would validate cloud-native platform bets and compress margins for on-premises legacy vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | FedRAMP-authorized vendors capture U.S. research university procurement decisions against perimeter-based legacy alternatives. |
| Privacy-Preserving Analytics Integration | Differential privacy and federated learning capabilities differentiate vendors in multi-institution research consortia facing GDPR constraints. |
| Managed Security Service Expansion | 24/7 security operations center coverage addresses talent scarcity at mid-tier institutions competing with private sector salaries. |
| Hardware Security Module Partnership | Key management certification for HIPAA business associate agreements unlocks academic medical center and health sciences program revenue. |
| SASE Platform Unification | Consolidated network security and SD-WAN offerings eliminate separate procurement cycles for distributed satellite campuses. |
Methodological Framework
SEC filings from publicly traded cybersecurity vendors, hyperscaler education sector capex disclosures, and EMA regulatory submission databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with chief information security officers at R1 research universities, K-12 district technology directors, and procurement officers at India's National Informatics Centre validated deployment architecture preferences and budget cycle timing. Bottom-up and top-down triangulation cross-checked vendor revenue disclosures against institutional procurement survey data.
Bottom-up modeling aggregated individual solution category expenditures across identity management, encryption, firewall, and endpoint protection segments, while top-down analysis calibrated aggregate market figures against education sector IT spending ratios. Segmentation dimensions modeled include deployment architecture, institutional type, regulatory compliance framework, and geographic procurement authority structure. CAGRs were derived from enrollment volatility projections and digital infrastructure policy implementation timelines, with specific inputs from FERPA audit logging certification backlogs and GDPR enforcement action frequencies.
The model assumes a particular technology adoption path; alternative pathways for on-premises-to-cloud migration would alter the outlook if legacy student information system API compatibility improves faster than projected. Deviation in India's National Education Policy implementation velocity or GDPR fine escalation against alumni data processing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
M2M Network Security Market
Cybersecurity
Global Network Security Firewall Market
Cybersecurity
Server Security Market
Cybersecurity
Network Security Market
Cybersecurity
India Network Security and Cyber Risk Management Market
Cybersecurity
Banking Cyber Security Market
Cybersecurity
Benelux Cybersecurity Market
Cybersecurity
Cloud Encryption Gateways Market
Cybersecurity
Firewall-As-A-Service (Fwaas) Market
Cybersecurity
Threat Intelligence Market
Cybersecurity
Cloud Security Gateway Market
Cybersecurity
Morocco Cybersecurity Market
Cybersecurity
Spear Phishing Solution Market
Cybersecurity
Hong Kong Cybersecurity Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
V2X Cybersecurity Market