
 Global Online Expense Management Software Market | 2026-2036
Global Online Expense Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Expense Management Software Market Foresight
Market Context
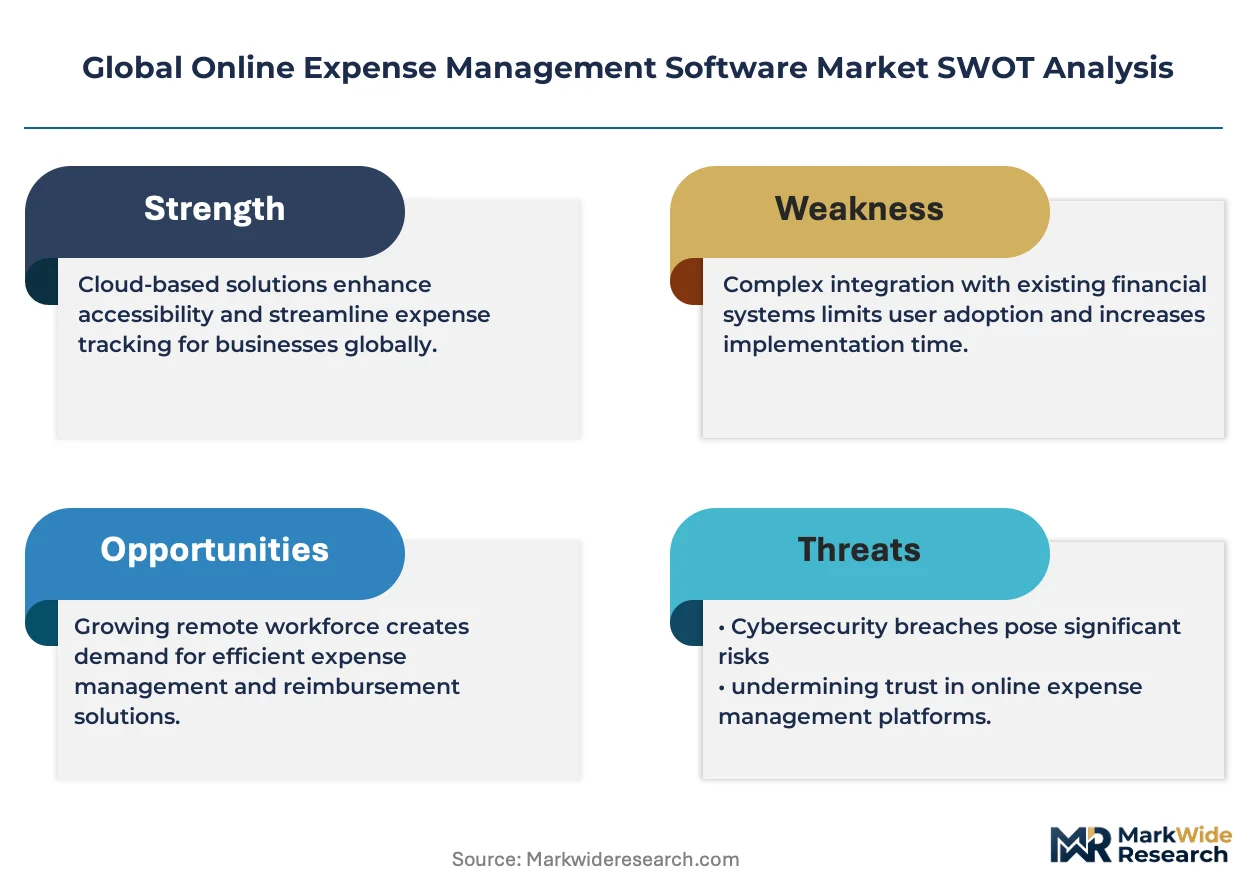
Mid-market professional services is consolidating travel and spend management onto single-vendor platforms. SAP Concur Technologies dominates enterprise-grade policy automation across multinational deployments. Expensify Inc leverages mobile-first receipt capture to anchor its position among freelancer and SMB segments. Zoho Corporation Pvt. Ltd competes on integrated suite economics, bundling expense modules with CRM and payroll workflows.
Technical Definition and Segment Structure
Online expense management software comprises cloud-native applications that automate receipt digitization, policy enforcement, reimbursement routing, and spend analytics through API-connected corporate card and ERP integrations. The primary commercial purpose is reducing manual reconciliation labor while tightening pre-approval controls and real-time budget visibility. Cloud-Based deployment leads absolute revenue contribution as finance teams abandon on-premises legacy systems for browser-accessible, multi-entity consolidation. SMBs represent the fastest-growing end-user pool, though Large Enterprises still occupy the deepest margin tier due to multi-module contract values and dedicated implementation support.
Regulatory Frame and Outlook
The US Internal Revenue Service mandates contemporaneous documentation standards that software vendors encode as automated audit trails, while the EU GDPR shapes cross-border employee data residency requirements for reimbursement platforms processing PII across member states. India's GST framework and digital invoice-matching protocols force vendors to localize tax computation engines or cede market access to domestic competitors. Stakeholders must monitor how real-time payment infrastructure and open banking APIs reshape vendor switching costs and platform stickiness.
Market Dynamics
AI-powered receipt extraction is compressing manual reconciliation labor across finance teams, forcing vendors to embed machine learning pipelines directly into mobile capture workflows or cede accounts to automated-first competitors.
Growth Catalysts
- Remote-First Workforce Policies:Distributed teams in the United States, Germany, and India now require real-time reimbursement routing. Platforms capturing this demand are consolidating travel and expense modules into unified dashboards.
- GST Invoice-Matching Mandates:India's digital tax infrastructure forces software providers to localize computation engines. Vendors with compliant engines gain preferential procurement slots in Indian mid-market professional services.
- Open Banking API Proliferation:Real-time payment rails in the United Kingdom and European Union are reducing reimbursement settlement cycles from days to hours. Finance teams select platforms with native bank connectivity over legacy batch processors.
Market Restraints
- Data Residency Compliance Costs:The EU GDPR mandates employee PII storage within member-state borders. Vendors must provision region-specific cloud instances, raising operational overhead for cross-border deployments.
- Legacy ERP Integration Friction:SAP and Oracle on-premises installations persist in Fortune 500 accounts. API connectivity gaps force expensive custom middleware development that erodes SaaS margin structures.
- Domestic Vendor Protectionism:India's BIS certification requirements and PLI scheme incentives favor local software providers. Foreign platforms face procurement exclusion in government-linked professional services contracts.
Strategic Opportunities
- Embedded Finance Convergence:Corporate card issuance is merging with expense software. Platforms integrating virtual card provisioning capture interchange revenue streams unavailable to pure software competitors.
- Carbon Accounting Integration:The EU CSRD mandates Scope 3 emissions disclosure. Expense platforms embedding flight and hotel carbon calculators capture ESG compliance budgets from multinational professional services firms.
- Underpenetrated LATAM Markets:Brazil and Mexico exhibit low cloud-ERP penetration among mid-market services firms. Vendors with Portuguese and Spanish localization capture first-mover procurement relationships.
Industry Challenges
- Machine Learning Engineering Talent Scarcity:Receipt extraction accuracy requires specialized computer vision expertise. Vendors compete for limited ML engineers against larger technology employers in San Francisco and Bangalore.
- Multi-Entity Consolidation Complexity:Professional services firms operating across 15+ jurisdictions require real-time currency conversion and tax engine orchestration. Implementation timelines stretch 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Expense Management Software Market |
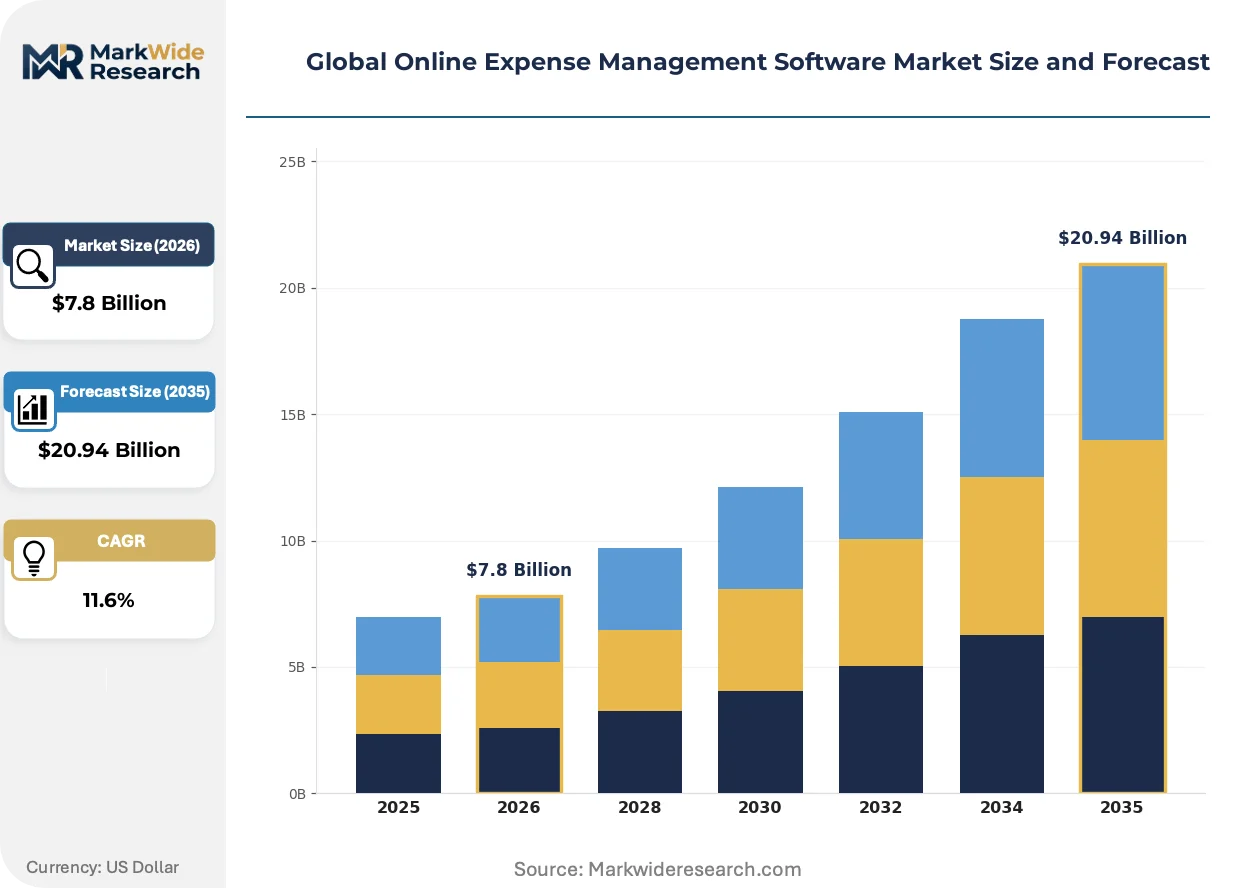
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.94 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: SMBs, Large Enterprises, Freelancers, Corporations Functionality: Expense Reporting, Receipt Scanning, Budgeting, Analytics Pricing Model: Subscription, Pay-per-Use, Tiered Pricing, Freemium |
| Companies Covered | Zoho Corporation Pvt. Ltd, Workday Inc, SAP Concur Technologies, Brex, Emburse Inc, Coupa Software Incorporated, Oracle Corporation, Navan, Expensify Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Expense Management Software Market Shifts & Advancements
Blockchain-based expense verification is emerging as a trust architecture for cross-border reimbursement, while real-time payment infrastructure and ESG disclosure mandates are reshaping platform feature roadmaps.
Optical character recognition combined with natural language processing is decentralizing data entry authority away from centralized finance teams toward individual employees. Mid-market professional services firms in Germany and the Netherlands are deploying these tools at 40% annual adoption velocity. The technology is decentralizing audit trail custody, embedding compliance verification at the point of capture rather than downstream reconciliation.
The EU AI Act classifies automated expense approval systems as high-risk AI applications requiring human-in-the-loop oversight. Vendors must redesign policy enforcement engines to surface explainable decision logic or face deployment restrictions in European Union member states. Large enterprise contracts in France and Germany now mandate algorithmic transparency documentation as a procurement prerequisite.
Subscription fatigue among finance software buyers is compressing vendor consolidation cycles. Professional services firms previously maintaining separate travel, expense, and procurement tools are unbundling point solutions in favor of suite-native modules from ERP incumbents. This pattern is most visible in the United States, where SAP and Oracle customers prioritize integration depth over best-of-breed functionality.
Global Online Expense Management Software Market Segmentation
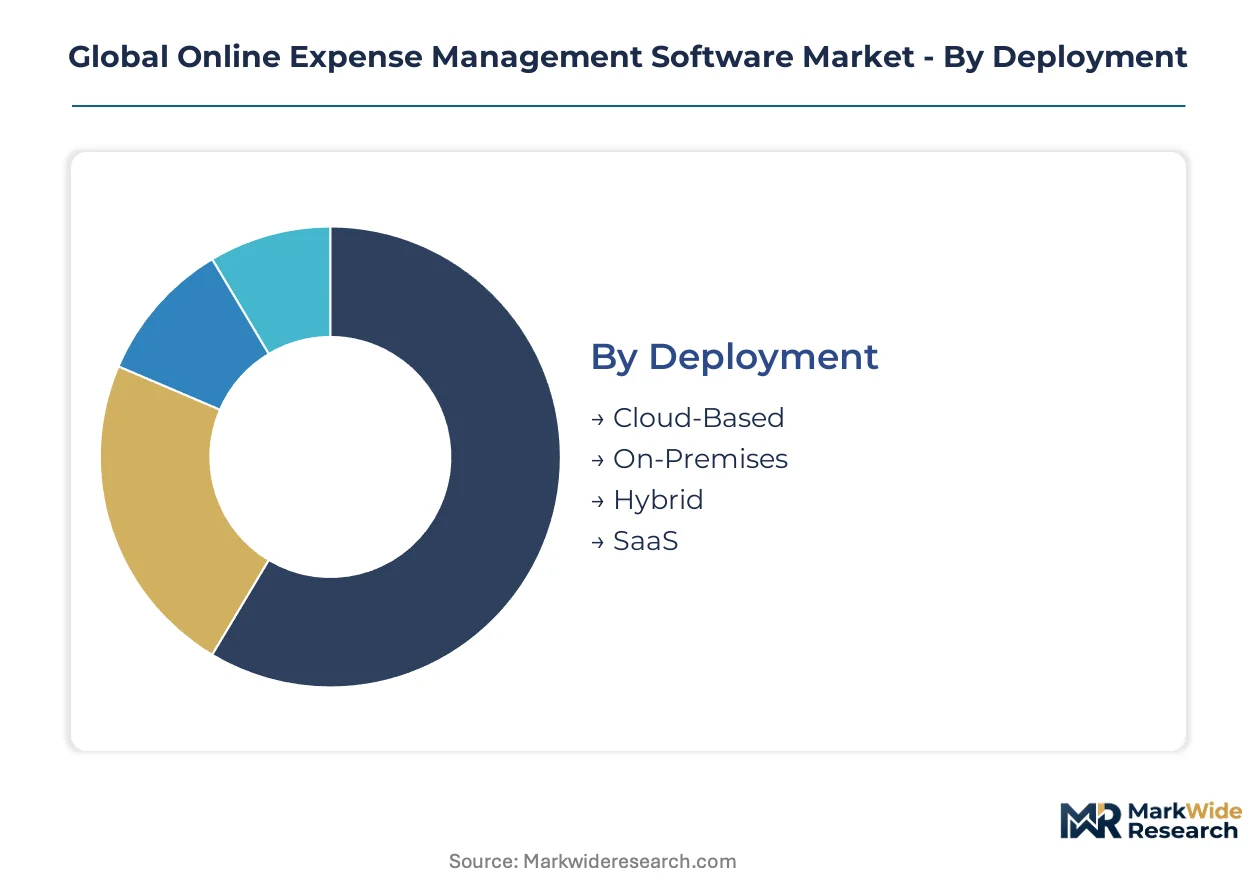
Deployment architecture determines integration complexity and data sovereignty compliance for finance teams across multinational professional services firms. End-user scale shapes feature depth requirements, from freelancer receipt capture to multi-entity consolidation engines.
Deployment:
Standardization dominates at the infrastructure layer while customization proliferates at the policy configuration tier, creating a bifurcated vendor landscape between pure-play SaaS and hybrid ERP extensions.
- Cloud-Based:Browser-accessible multi-tenant architectures eliminate server maintenance overhead. United States mid-market professional services firms drive demand as remote-first policies mandate anywhere-accessible reimbursement workflows without VPN dependency.
- On-Premises:Single-tenant installations behind corporate firewalls persist in German automotive and industrial conglomerates with legacy SAP ERP cores. IT departments retain full audit trail custody, though maintenance contracts erode TCO advantages versus cloud alternatives.
- Hybrid:Sensitive employee PII resides on-premises while analytics processing shifts to cloud instances. Indian IT services exporters adopt this architecture to satisfy RBI data localization mandates without sacrificing real-time dashboard performance.
- SaaS:Pre-configured policy templates accelerate deployment timelines to under 30 days. Freelancer segments in the United Kingdom and Netherlands favor SaaS for zero-setup onboarding and per-seat billing granularity.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as GDPR and RBI compliance requirements harden.
End User:
Customer scale inversely correlates with price sensitivity but directly correlates with implementation complexity and contract duration.
- SMBs:Organizations under 500 employees prioritize mobile-first receipt capture and rapid reimbursement cycles. Indian mid-market professional services firms represent the steepest expansion trajectory as GST invoice-matching mandates force digitization.
- Large Enterprises:Fortune 500 deployments require multi-entity currency conversion and 15+ jurisdiction tax engine orchestration. German industrial conglomerates anchor this segment with 12-18 month implementation timelines and dedicated customer success resources.
- Freelancers:Sole proprietors and gig economy workers demand zero-training interfaces with automated mileage tracking. United States independent consultants drive volume through Expensify and similar mobile-native platforms.
- Corporations:Mid-market entities between 500-5,000 employees balance policy sophistication with implementation speed. Netherlands professional services clusters favor this segment for integrated travel and expense consolidation.
Revenue concentration sits with Large Enterprises due to module bundling and multi-year commitments. SMBs are climbing the fastest as vendor self-serve onboarding reduces customer acquisition costs.
Functionality:
Core automation capabilities commoditize while predictive analytics and carbon accounting emerge as differentiation layers commanding premium pricing.
- Expense Reporting:Digital submission workflows with automated policy flagging replace spreadsheet-based reconciliation. United States accounting firms mandate this functionality for SOC 2 audit compliance, driving baseline adoption across all customer tiers.
- Receipt Scanning:OCR-NLP pipelines extract merchant, date, and amount data from mobile camera captures. German mid-market deployments achieve 40% annual adoption velocity as EU AI Act transparency requirements reshape vendor selection criteria.
- Budgeting:Real-time spend visibility against departmental forecasts with pre-approval threshold enforcement. Indian professional services firms deploy budgeting modules to prevent GST input credit leakage through uncategorized expenditures.
- Analytics:Predictive spend forecasting and vendor benchmarking using aggregated transaction patterns. Large Enterprises in the United Kingdom leverage analytics for Scope 3 emissions calculations under CSRD disclosure mandates.
Receipt Scanning captures the highest daily active user engagement. Analytics modules are gaining share fastest as ESG compliance budgets expand.
Pricing Model:
Revenue predictability trades off against customer flexibility, with vendor portfolio mix reflecting risk tolerance and cash flow optimization priorities.
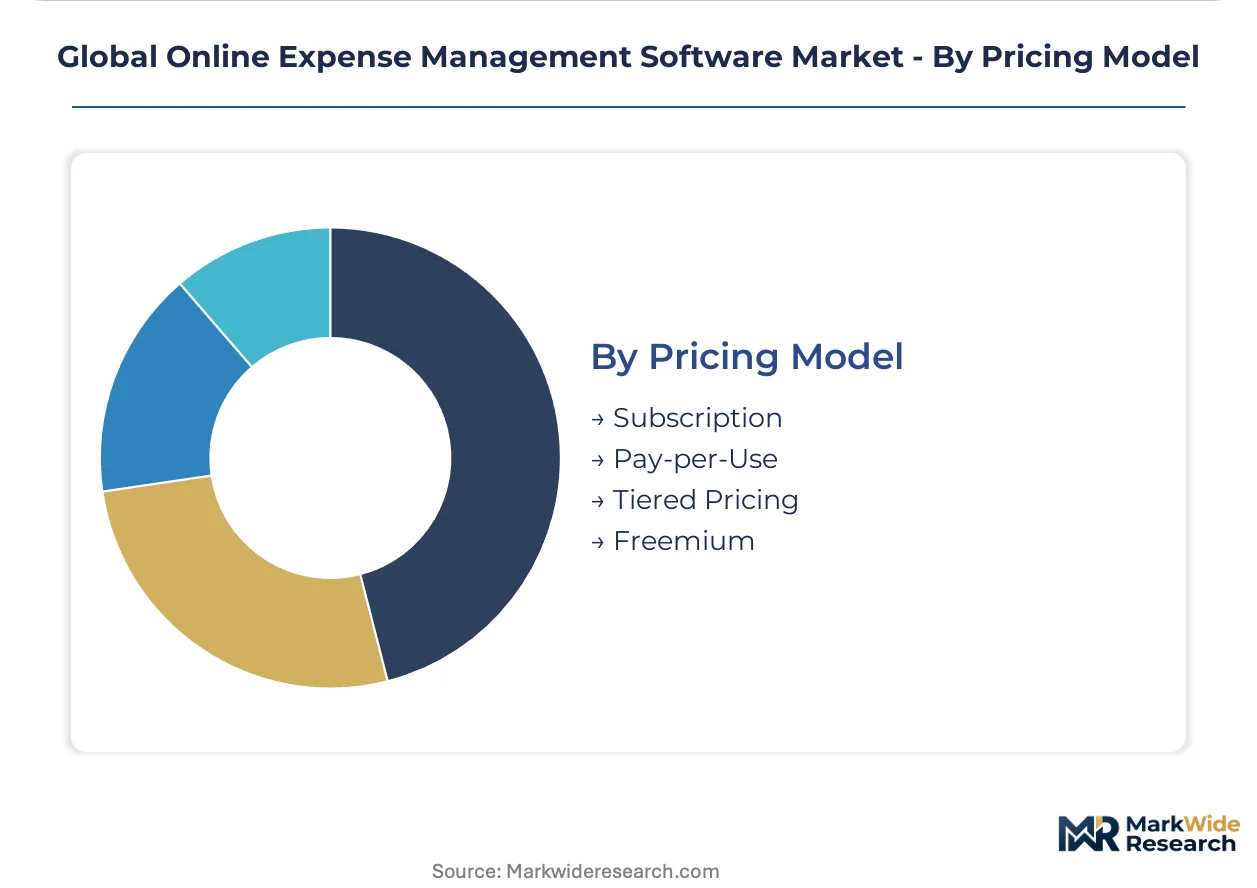
- Subscription:Fixed monthly or annual per-seat fees with tiered feature entitlements. Large Enterprises in Germany prefer annual subscriptions for budget certainty and procurement approval efficiency.
- Pay-per-Use:Transaction-volume billing aligns costs with actual expense submission frequency. Freelancers in the United States favor this model for seasonal income variability.
- Tiered Pricing:Premium-mid-economy differentiation across policy complexity, support levels, and integration depth. Indian mid-market professional services firms cluster at mid-tier for GST compliance without enterprise implementation overhead.
- Freemium:Basic receipt capture and single-user reporting at zero cost with paid upgrades for multi-user policy enforcement. Netherlands freelancer communities drive viral adoption before organizational procurement consolidation.
Subscription billing dominates vendor revenue recognition. Freemium conversion rates are expanding most quickly as product-led growth strategies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market professional services clusters in the United States, Germany, and India are consolidating travel and expense workflows onto unified cloud platforms as remote-first employment policies normalize distributed reimbursement operations.
United States
Remote-first workforce policies across technology and consulting sectors drive real-time reimbursement routing demand. The IRS mandates contemporaneous documentation standards that vendors encode as automated audit trails. San Francisco and New York metro areas anchor procurement decisions for Fortune 500 deployments requiring multi-entity consolidation.
Germany
Industrial conglomerates and automotive suppliers demand single-tenant installations behind corporate firewalls for legacy SAP ERP integration. The EU AI Act classifies automated expense approval systems as high-risk applications requiring human-in-the-loop oversight. Munich and Stuttgart clusters prioritize algorithmic transparency documentation in procurement specifications.
India
GST invoice-matching mandates force mid-market professional services firms to digitize spend workflows or forfeit input tax credits. The RBI data localization requirements push IT services exporters toward hybrid deployment architectures. Bangalore and Hyderabad technology corridors exhibit the steepest adoption velocity for mobile-first receipt capture.
United Kingdom
Open banking API proliferation reduces reimbursement settlement cycles from days to hours across London financial services clusters. The FCA regulatory framework shapes real-time payment rail integration requirements. Manchester and Leeds professional services hubs select platforms with native bank connectivity over legacy batch processors.
Netherlands
Freelancer communities drive viral freemium adoption before organizational procurement consolidation in Amsterdam and Rotterdam consulting clusters. The EU GDPR mandates employee PII storage within member-state borders, raising operational overhead for cross-border deployments. Mid-market entities between 500-5,000 employees balance policy sophistication with implementation speed.
Global Online Expense Management Software Market Competitive Landscape
Platform consolidation dominates the current landscape as finance teams abandon point solutions for suite-native modules. The vendor base stratifies across three tiers: ERP incumbents with embedded expense modules, pure-play SaaS specialists with mobile-first architectures, and corporate card issuers converging into software. Strategic archetypes include integration depth leaders, receipt automation specialists, and embedded finance platforms. M&A activity and API ecosystem expansion represent the dominant competitive vectors reshaping procurement relationships.
Within the ERP-embedded tier, SAP Concur Technologies and Oracle Corporation occupy positions defined by multi-module contract values and dedicated implementation support. Among pure-play specialists, Expensify Inc exemplifies mobile-native receipt capture targeting freelancer and SMB segments. Zoho Corporation Pvt. Ltd represents integrated suite economics, bundling expense modules with adjacent CRM and payroll workflows to reduce vendor fragmentation for mid-market buyers.
| Leading Market Players |
|---|
| Zoho Corporation Pvt. Ltd |
| Workday Inc |
| SAP Concur Technologies |
| Brex |
| Emburse Inc |
| Coupa Software Incorporated |
| Oracle Corporation |
| Navan |
| Expensify Inc |
| Others |
Supply & Pricing Matrix
The EU CSRD mandates Scope 3 emissions disclosure across corporate value chains, gating qualified supply relationships for vendors embedding carbon accounting modules and enabling premium-tier pricing access among ESG-compliant procurement officers at multinational professional services firms.
Pricing Analysis
Channel-margin compression runs through indirect sales routes as SaaS vendors bypass traditional distributors for direct-to-finance-team subscriptions. Premium-mid-economy pricing differentiation stratifies across policy complexity tiers, with enterprise multi-module contracts commanding the widest spreads. Cost compression in the SMB tier intensifies because freemium conversion engines subsidize user acquisition. Freelancer segments exhibit highest price sensitivity, while Fortune 500 procurement teams prioritize integration depth over per-seat economics.
Supply Chain Analysis
India's PLI scheme incentives and BIS certification requirements reshape sourcing patterns for foreign platforms seeking government-linked professional services contracts. Cloud infrastructure provisioning concentrates in the United States, Ireland, and Singapore for data residency compliance. Raw material dependencies center on GPU compute capacity for machine learning pipelines, API gateway services, and identity verification modules. Single-source vulnerability sits with hyperscaler cloud concentration. Distribution runs through direct sales teams for enterprise accounts and self-serve product-led funnels for SMB penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage returns through India's GST compliance engine requirements, where localization investments unlock procurement access unavailable to standardized global deployments.
For Market Incumbents: Anticipate embedded finance convergence threatening pure-software margin structures by integrating virtual card issuance capabilities before corporate banking partners capture interchange revenue streams. Reinforce API ecosystem depth against ERP incumbents bundling expense modules into suite-native offerings. Prioritize machine learning engineering retention in Bangalore and San Francisco talent markets. For New Entrants and Emerging Players: Mid-market professional services firms in Brazil and Mexico represent an underserved buyer archetype with low cloud-ERP penetration and Portuguese-Spanish localization gaps. White-space capture runs through LATAM-first mobile receipt capture and open banking API integration ahead of incumbent geographic expansion. Go-to-market leverage rests on channel partnerships with regional accounting software distributors. For Investors and Strategic Acquirers: Roll-up economics work for vertical expense specialists because policy engine fragmentation across jurisdictions prevents single-vendor dominance. Long-term viability hinges on platforms capturing both software subscription and embedded finance revenue streams. Acquisition target archetypes include receipt automation specialists with computer vision IP and regional compliance engines. Watch open banking API proliferation velocity as inflection signal for platform switching cost erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-native expense modules displace best-of-breed point solutions in SAP and Oracle accounts. |
| Acquisition of Specialist Firm | Computer vision teams with receipt extraction IP command premium valuations from consolidation buyers. |
| Geographic Expansion | Portuguese and Spanish localization captures first-mover procurement in Brazilian and Mexican mid-markets. |
| Strategic Partnership | Open banking API alliances with UK and EU payment rails compress reimbursement settlement cycles. |
| Product Launch | Carbon accounting modules embed flight and hotel emissions calculators for CSRD compliance budgets. |
Research Methodology
Direct dialogue with CFOs, IT procurement officers, platform integration specialists, and channel partners grounded qualitative findings, cross-referenced against SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and EU regulatory filings. Bottom-up and top-down triangulation validated segment sizing across deployment architectures and end-user tiers.
Bottom-up modeling tracked individual vendor revenue disclosures and customer count estimates, while top-down approaches calibrated against total addressable spend management software investment pools. Segmentation dimensions spanned deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from historical trajectory analysis and technology diffusion curve positioning, with AI-powered automation penetration and open banking API maturity as primary forecast inputs across the analysis window.
Underlying measurement precision varies by segment; cloud-based deployment and SMB end-user categories carry tighter precision than hybrid architectures and freelancer estimates due to vendor disclosure granularity. Forecasts incorporate assumptions regarding regulatory enforcement timelines and technology adoption velocity. Platform consolidation pace and embedded finance convergence represent specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Content Curation Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Global Web Scraper Software Market
Software & Services
Lead Management Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
Relational Database Management System Market
Software & Services
Global Equity Management Software Market
Software & Services
Global Customer Service Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
Photo Editor App Market
Software & Services
North America Deck Design Software Market
Software & Services
Europe CMMS Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Press Release Distribution Software Market