
 Outsourced Customer Care Services Market | 2026-2036
Outsourced Customer Care Services Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourced Customer Care Services Market Analysis
Philippine call center capacity is rebalancing toward higher-value technical assistance and multichannel engagement as wage pressures erode pure voice-agent economics. Teleperformance SE leverages its hybrid delivery footprint across four continents to sustain margin stability. Tata Consultancy Services Limited anchors its competitive position through deep CRM software integration and captive technology stacks. Alorica differentiates via specialized healthcare and BFSI compliance protocols that command premium contract terms.
Outsourced customer care services encompass third-party management of consumer interactions spanning voice, digital, and automated channels, typically governed by service-level agreements specifying average handle time, first-contact resolution rates, and customer satisfaction thresholds. These services functionally absorb frontline operational burdens from enterprises seeking variable-cost structures rather than fixed contact-center investments. Inbound support and multichannel engagement currently occupy the largest revenue pools, though AI chatbot-enabled technical assistance represents the fastest-expanding margin segment as enterprises pursue deflection rates above sixty percent without human escalation. Cloud computing infrastructure underpins delivery model flexibility, allowing onshore-offshore-hybrid configurations to shift dynamically based on seasonal demand spikes and data sovereignty requirements.
FDA information-handling standards shape healthcare customer care outsourcing requirements in the United States, while GDPR and the EU AI Act constrain automated data processing and bot disclosure protocols across European contracts. India's TRAI telecom regulations and RBI data-localization mandates for BFSI clients create compliance thresholds that determine vendor eligibility for domestic and export-facing operations. Stakeholders must monitor evolving AI transparency obligations and cross-border data flow restrictions as these frameworks increasingly dictate contract structure and technology architecture decisions.
Market Dynamics
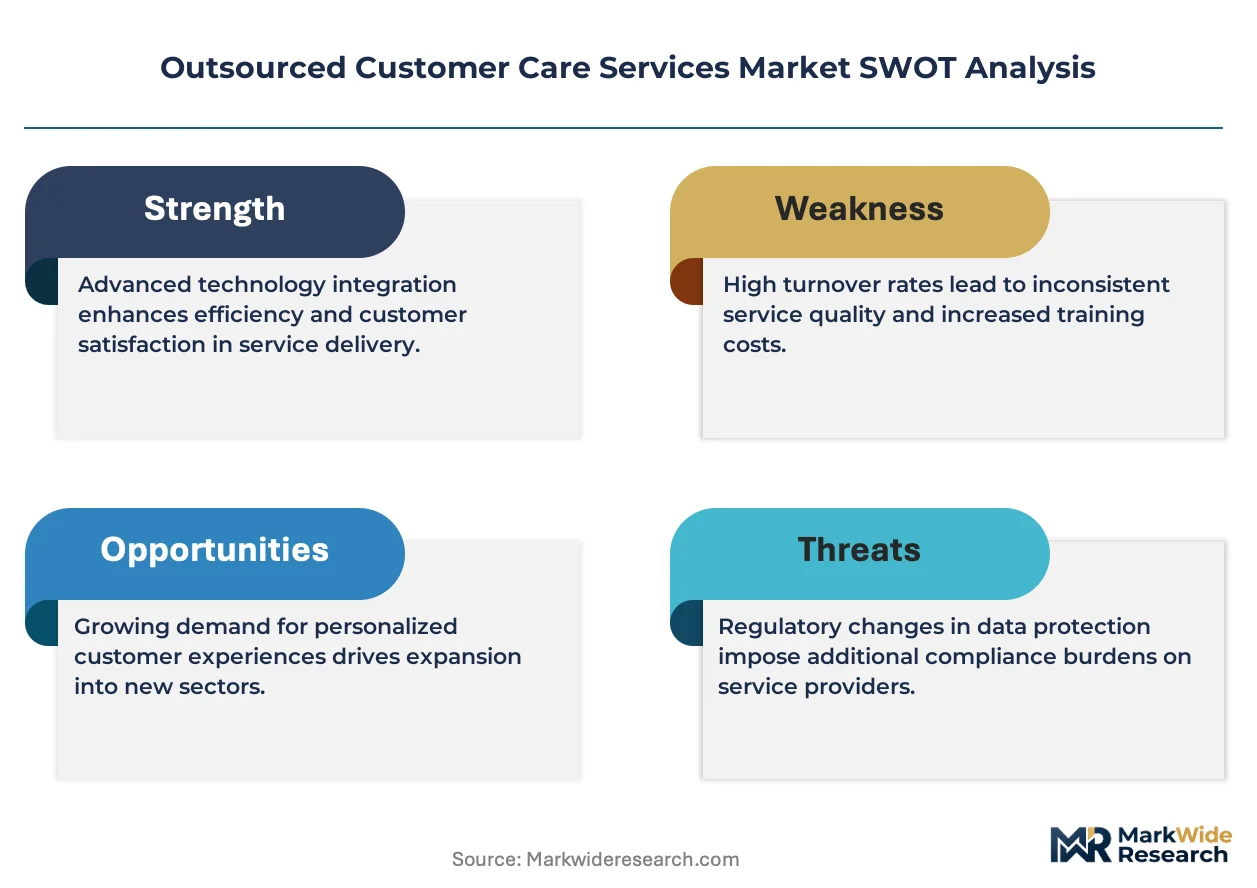
The EU AI Act's mandatory disclosure requirements for automated customer interfaces are forcing wholesale rearchitecture of chatbot deployment strategies, compressing vendor timelines for compliance certification while simultaneously opening premium contract tiers for human-verified service guarantees.
Growth Catalysts
- E-commerce order surges:Platform return-handling complexity and seasonal volume spikes drive demand for variable-cost contact center capacity rather than fixed infrastructure investments.
- GDPR and EU AI Act:European regulatory frameworks mandate transparent bot-to-human handoff protocols, creating specialized compliance service revenue streams for certified vendors.
- Cloud infrastructure elasticity:Onshore-offshore-hybrid configurations now shift dynamically based on data sovereignty requirements and demand seasonality.
Market Restraints
- Wage arbitrage erosion:Philippine agent compensation inflation of eight to twelve percent annually undermines pure voice-service economics that anchored historical outsourcing decisions.
- Data localization mandates:India's RBI requirements for BFSI client data residency restrict vendor flexibility and force redundant infrastructure investments.
- AI deflection ceiling:Technical query complexity above sixty percent deflection rates triggers mandatory human escalation, limiting pure automation margin expansion.
Strategic Opportunities
- Healthcare compliance specialization:FDA information-handling standards for US pharmaceutical clients command premium pricing for vendors with validated quality management systems.
- Multichannel integration:Convergence of voice, chat, and social media engagement platforms enables unified customer view products that reduce client churn.
- Technical assistance tiering:Higher-value IT support and device troubleshooting segments remain underpenetrated by offshore pure-plays, offering margin expansion for capability-upgraded providers.
Industry Challenges
- Agent attrition management:Contact center annual turnover rates exceeding forty percent in major delivery locations drain recruitment resources and degrade service consistency.
- Legacy CRM integration:Client-specific software environments require custom API development and extended implementation timelines that compress project profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outsourced Customer Care Services Market |
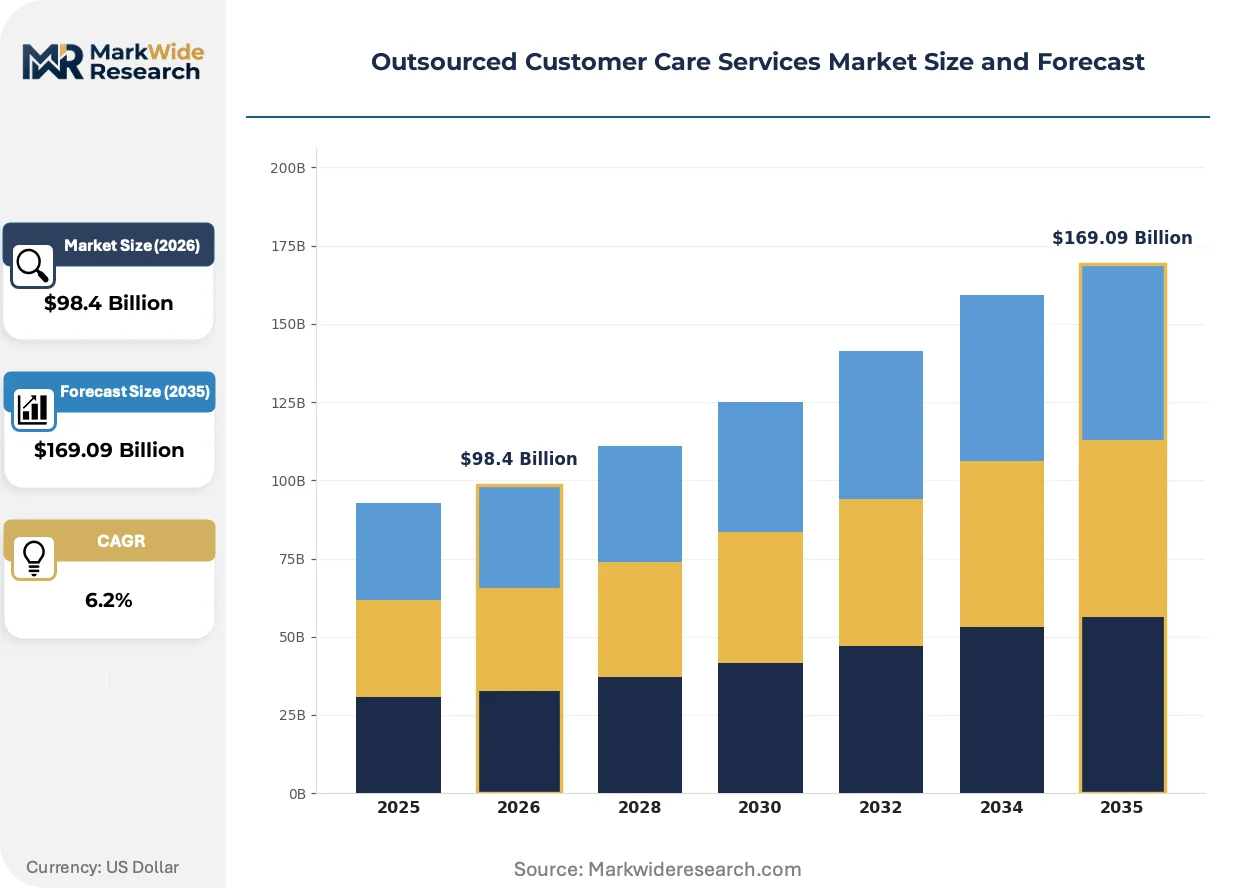
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $169.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inbound Support, Outbound Support, Technical Assistance, Multichannel Engagement End User: BFSI, E-commerce, Telecommunications, Healthcare Technology: AI Chatbots, Cloud Computing, CRM Software, Voice Recognition Delivery Model: Onshore, Offshore, Nearshore, Hybrid |
| Companies Covered | Teleperformance SE, Accenture plc, Tata Consultancy Services Limited, Cognizant, Genpact, Sitel Group, Alorica, Sutherland Global Services, iQor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourced Customer Care Services Market Emerging Trajectories
Generative AI capabilities are compressing the traditional voice-digital-automation hierarchy into integrated service stacks where intent recognition and response generation occur across unified platforms rather than channel-siloed systems.
Conversational AI orchestration layers are unifying previously fragmented chatbot, voicebot, and live agent systems into single routing engines. E-commerce platforms and financial services providers are deploying these stacks fastest, with deployment cycles compressing from eighteen months to under six. This unification is collapsing the traditional price premium between multichannel and voice-only service contracts.
The EU AI Act's Article 52 disclosure mandates now require explicit bot identity announcement before any automated interaction begins. Vendors serving European contracts must retrain natural language processing models and redesign conversation flows to embed compliance checkpoints. Healthcare and BFSI segments face the steepest rework costs given their higher regulatory scrutiny and existing automation penetration.
Enterprise buyers are unbundling after-sales support from product warranties and sourcing these services separately through specialized customer care contracts. Industrial equipment and consumer electronics manufacturers lead this shift, particularly in Germany and Japan where service-level expectations remain stringent. The separation creates procurement leverage and exposes incumbent OEM captive operations to competitive displacement.
Outsourced Customer Care Services Market Segmentation
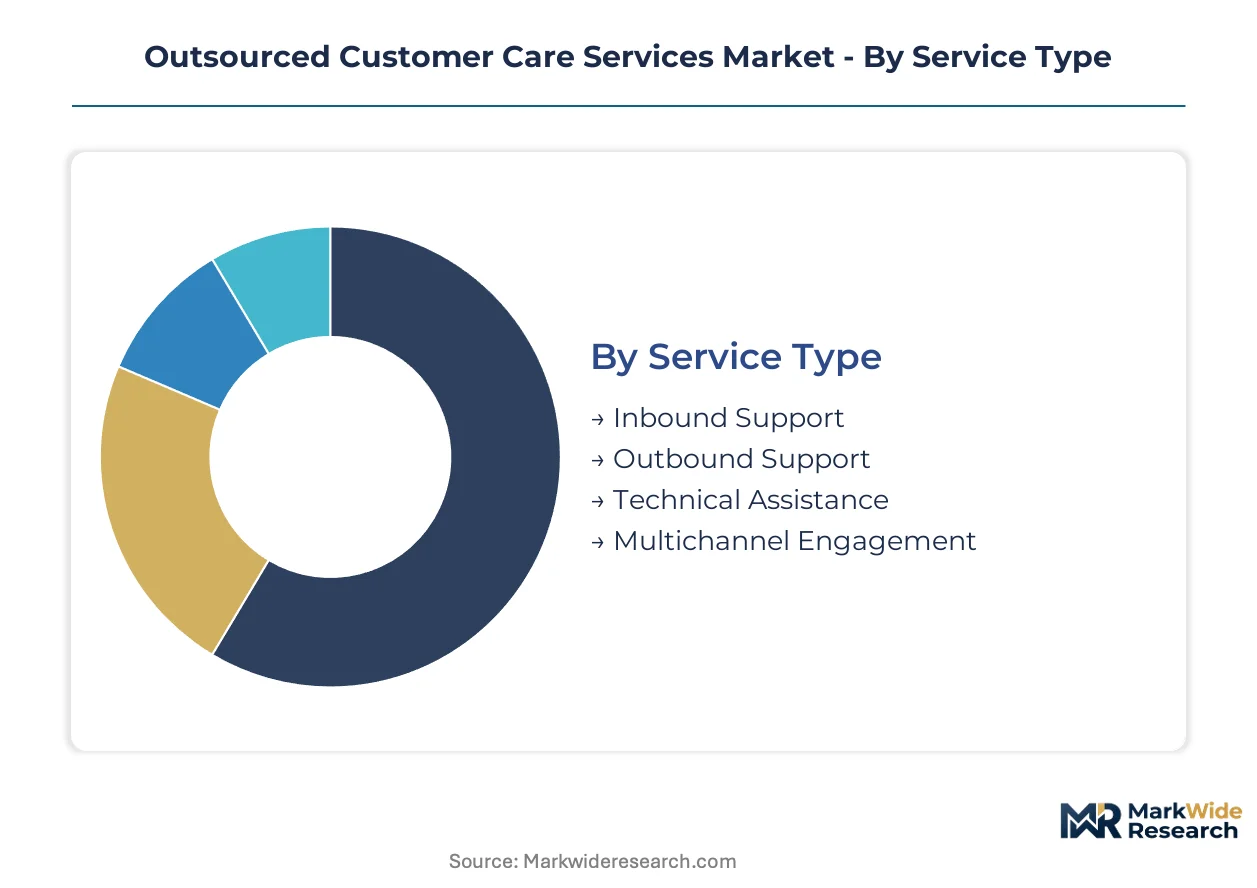
Service differentiation determines contract value and margin capture in outsourced customer care. Vendors structure capabilities around interaction complexity, regulatory exposure, and technology integration depth rather than generic scale.
Service Type:
Cost tier separates commoditized voice handling from premium technical and integrated engagements.
- Inbound Support:Voice and digital query handling for order status, billing disputes, and general account management. E-commerce platforms in India and the Philippines absorb the highest call volumes during seasonal peaks, though wage inflation is compressing margins.
- Technical Assistance:Device troubleshooting, software configuration, and IT helpdesk services requiring certified agent training. Healthcare and BFSI clients in the United States pay premium rates for FDA and HIPAA-compliant handling of sensitive technical queries.
- Outbound Support:Proactive customer outreach for sales, collections, and satisfaction surveys. Telecommunications providers deploy this for churn prevention and upsell campaigns.
- Multichannel Engagement:Unified management of voice, chat, email, and social media touchpoints. Retail banking clients demand this for consistent customer experience across platforms.
Inbound Support leads volumes today; Technical Assistance is gaining share fastest.
End User:
Application complexity dictates compliance burden and pricing power.
- E-commerce:Order management, returns processing, and delivery exception handling at massive scale. Surging volumes in India and seasonal spikes in Germany strain variable-cost contract structures.
- Healthcare:Patient scheduling, claims support, and pharmaceutical information services under strict regulatory oversight. FDA validation requirements in the United States create vendor certification barriers that protect incumbent pricing.
- BFSI:Account servicing, fraud alerts, and loan origination support with RBI data-localization mandates in India forcing infrastructure decisions.
- Telecommunications:Subscriber technical support and billing inquiry management. EU AI Act disclosure requirements reshape chatbot deployment for European carrier contracts.
E-commerce dominates transaction volumes; Healthcare commands the steepest expansion trajectory in contract value.
Technology:
Customer maturity determines automation depth and integration spend.
- AI Chatbots:Natural language processing for first-line query resolution and intent classification. GDPR and EU AI Act transparency mandates in Europe force conversation flow redesigns.
- Cloud Computing:Elastic infrastructure enabling dynamic scaling across delivery locations. BFSI clients leverage this for RBI-compliant data residency in India.
- CRM Software:Client-specific customer data platforms requiring custom API development. Salesforce and ServiceNow integrations dominate enterprise procurement.
- Voice Recognition:Biometric authentication and conversational IVR systems. Healthcare adoption accelerates for HIPAA-compliant caller verification.
Cloud Computing anchors current deployments; AI Chatbots show the most rapid capability advancement.
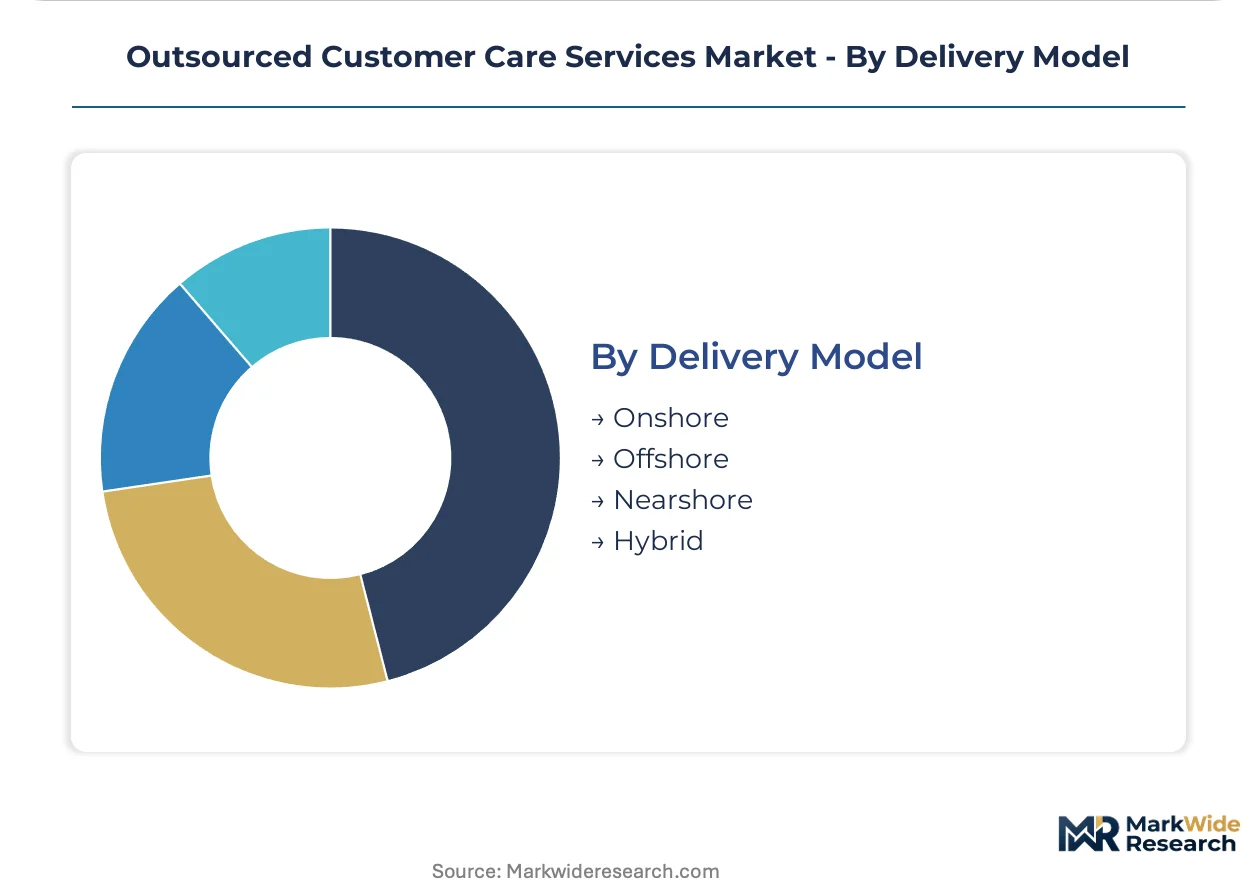
Delivery Model:
Geography drives labor arbitrage, regulatory compliance, and service level trade-offs.
- Offshore:India and the Philippines deliver English-language voice and digital services at compressed cost structures. Annual wage inflation of eight to twelve percent in Philippine metro areas erodes historical advantages.
- Hybrid:Dynamic routing between onshore, nearshore, and offshore resources based on query complexity and data sensitivity. GDPR-constrained European contracts favor this for personal data handling.
- Onshore:Domestic delivery for regulated industries and high-escalation scenarios. FDA-audited healthcare operations in the United States require this for quality system validation.
- Nearshore:Regional delivery from adjacent time zones, typically Eastern Europe for Western European clients or Latin America for North American markets.
Offshore delivery captures the largest contract volume; Hybrid models are expanding most quickly as data sovereignty requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping delivery location decisions as vendors seek compliance-cost advantages. Enterprises migrate contracts toward jurisdictions with lighter disclosure burdens or established English-language agent pools. Data localization mandates and wage inflation are compressing historical offshore economics.
United States
Healthcare and BFSI verticals drive premium contract demand as FDA information-handling standards and HIPAA compliance requirements filter vendor eligibility. The FDA enforces validated quality management systems for pharmaceutical customer care operations. Dallas-Fort Worth and Phoenix anchor major delivery clusters where technical assistance capabilities concentrate.
India
English-language agent availability and cost structures continue attracting North American and European contract migrations despite infrastructure pressures. RBI data-localization mandates for BFSI clients and TRAI telecom regulations determine vendor eligibility for domestic and export-facing operations. Bengaluru and Hyderabad host the densest technical support talent pools as multichannel engagement capabilities expand.
Philippines
Metro Manila and Cebu City operations are rebalancing toward higher-value technical assistance as eight to twelve percent annual wage inflation erodes pure voice-agent economics. The country's national telecom regulator maintains quality standards for international voice services. Davao emerges as a secondary hub where vendors test specialized healthcare and BFSI compliance protocols.
Germany
Industrial equipment and consumer electronics manufacturers are unbundling after-sales support from product warranties, exposing OEM captive operations to competitive displacement. The EU AI Act's Article 52 disclosure mandates force conversation flow redesigns for automated customer interfaces. Berlin and Munich house the largest multilingual contact center operations serving EU-wide contracts.
United Kingdom
GDPR-constrained financial services contracts favor hybrid delivery models for personal data handling as Brexit-related regulatory divergence complicates cross-border service provision. The Information Commissioner's Office enforces transparency requirements for automated decision-making systems. Glasgow and Manchester attract nearshore voice operations serving London-based banking clients.
Outsourced Customer Care Services Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized compliance and technical assistance niches. The vendor base stratifies across scale-driven generalists, vertical specialists, and technology-integrated platforms. Three archetypes dominate: offshore pure-plays with geographic concentration, hybrid-network operators with dynamic routing capabilities, and captive-technology providers with deep CRM integration. Consolidation through strategic acquisitions and vertical capability expansion represent the dominant competitive moves.
Within the hybrid-network tier, Teleperformance SE and Sitel Group exemplify operators sustaining margin stability through dynamic onshore-offshore-hybrid configurations. Tata Consultancy Services Limited anchors the technology-integrated archetype through captive software stacks and enterprise CRM integration depth. Alorica occupies a position within the vertical-specialist segment where healthcare and BFSI compliance protocols command premium contract terms.
| Leading Market Players |
|---|
| Teleperformance SE |
| Accenture plc |
| Tata Consultancy Services Limited |
| Cognizant |
| Genpact |
| Sitel Group |
| Alorica |
| Sutherland Global Services |
| iQor |
| Others |
Supply Flow & Price Mechanics
Agent wage inflation in Philippine metro areas cascades through contract pricing tiers, compressing margins on voice-only services while elevating premiums for technical assistance capabilities in India and hybrid delivery configurations.
Pricing Analysis
Distributor margins on offshore voice contracts are thinning as eight to twelve percent annual wage growth in Manila erodes historical cost advantages. Pricing stratifies across premium compliance-certified tiers, standard multichannel engagements, and economy voice-only bundles, with FDA-validated healthcare operations commanding the widest spreads. Cost compression in Philippine pure-voice services is intensifying because clients demand deflection-rate guarantees without rate increases. E-commerce platforms exhibit the highest price sensitivity, while healthcare and BFSI buyers prioritize compliance certification over unit cost.
Supply Chain Analysis
Workforce availability in Bengaluru, Hyderabad, and Manila determines service delivery capacity for English-language contracts. Talent pipelines draw from university systems in India, vocational institutes in the Philippines, and Eastern European language specialists for EU-facing operations. Supply chain risk centers on single-source vulnerability in Philippine voice operations where wage inflation concentrates. Distribution runs through direct enterprise contracts, with systems integrators and consulting firms capturing implementation layers for CRM-integrated deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where e-commerce volume growth and regulatory complexity sustain recurring contract demand across economic cycles.
For Market Incumbents: Anchor margin stability through backward integration into proprietary AI orchestration platforms that reduce third-party licensing exposure. Expand technical assistance certification in FDA-audited healthcare operations to defend against emerging vertical specialists. Hybrid delivery network density remains the critical lever against pure-play offshore competitors.
For New Entrants and Emerging Players: Mid-market industrial equipment manufacturers represent an underserved buyer archetype seeking unbundled after-sales support separate from OEM warranties. German and Japanese manufacturing clusters offer the most penetrable geography given stringent service-level expectations and limited incumbent specialization. A compliance-first go-to-market angle targeting EU AI Act disclosure mandates opens contracting conversations faster than price-based positioning.
For Investors and Strategic Acquirers: Roll-up economics work for vertical-specialist customer care platforms because healthcare and BFSI compliance protocols create sticky contract renewal profiles and limited client churn. Long-term viability rests on automation-to-human handoff architecture rather than pure labor arbitrage. Watch AI deflection ceiling thresholds as the inflection signal: technical query complexity breaching sixty percent automation rates triggers mandatory capability upgrades across vendor portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Healthcare Compliance Certification | FDA-validated quality management systems unlock premium contract tiers in pharmaceutical customer care. |
| Hybrid Delivery Network Expansion | Dynamic onshore-offshore routing captures GDPR-constrained European contracts requiring data sovereignty. |
| AI Chatbot Orchestration Platform | Unified intent recognition engines collapse implementation timelines from eighteen months to under six. |
| Technical Assistance Capability Build | Device troubleshooting and IT helpdesk services command pricing power as wage arbitrage erodes. |
| Vertical Market Specialization | Healthcare and BFSI compliance protocols create vendor certification barriers protecting incumbent positions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with contact center operations directors, enterprise procurement leads, CRM platform engineers, and regulatory compliance officers with secondary validation against SEC filings, TRAI telecom reports, RBI circulars, and EU regulatory databases. Bottom-up contract value estimates and top-down market sizing triangulated across delivery model, service type, and end-user vertical dimensions.
Segment-weighting approaches distributed value across inbound support, technical assistance, outbound support, and multichannel engagement categories, with end-user concentration in e-commerce, healthcare, BFSI, and telecommunications further disaggregating projections. CAGRs were derived from historical contract migration patterns and forward-looking automation penetration assumptions, with wage inflation trajectories in India and the Philippines, EU AI Act implementation timelines, and cloud infrastructure elasticity serving as core forecast inputs across the projection horizon.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time contract pricing transparency introduce uncertainty bands around vendor-level market share estimates. Forecasts reflect documented assumptions regarding automation deflection ceilings, cross-border data flow restrictions, and agent attrition rates. Material deviation in named triggers—particularly EU AI Act enforcement intensity or Philippine wage inflation acceleration—warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Employee Engagement Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Digital Mailroom Services Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Asia Pacific Field Service Management Market