
 Finland E-Commerce Market | 2026-2036
Finland E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Finland E-Commerce Market Analysis
Headless commerce architecture is narrowing the gap between front-end experience and back-end inventory systems across Finnish retail. Verkkokauppa.com leverages its proprietary logistics network to control delivery speed in the electronics vertical. Zalando SE anchors Nordic fashion demand through localized sizing and return infrastructure. K-Ruoka competes by integrating offline grocery locations with real-time digital inventory.
Finland E-Commerce denotes the digital exchange of goods and services conducted through internet-connected platforms, encompassing transaction processing, payment gateway integration, and last-mile fulfillment orchestration. Its primary commercial purpose is to disintermediate traditional retail by reducing geographic friction between sellers and dispersed Finnish consumers across a sparsely populated territory. Electronics commands substantial margin pools due to high average order values and warranty attachment rates. B2C channels dominate transaction volume, though B2B procurement through digital platforms is expanding fastest among small and medium enterprises. Mobile apps capture disproportionate engagement share among younger demographics, while online marketplaces aggregate liquidity for niche product categories.
The Finnish Consumer Authority and the Finnish Transport and Communications Agency Traficom shape market access through enforcement of distance-selling regulations and digital service standards. The Finnish Data Protection Authority applies GDPR-derived rules to customer data handling, raising compliance costs for cross-border operators. Stakeholders must monitor evolving platform liability frameworks and payment authentication requirements that will determine competitive entry barriers.
Market Dynamics
Headless commerce architecture is compressing the latency between Finnish consumer interfaces and legacy inventory systems, forcing retailers to rebuild their technology stacks around API-first fulfillment orchestration rather than monolithic platform upgrades.
Growth Catalysts
- Helsinki-Uusimaa Logistics Density:Urban concentration in southern Finland enables same-day delivery networks that rural geographies cannot replicate, anchoring fulfillment investment in the capital region.
- GDPR-Compliant Data Infrastructure:The Finnish Data Protection Authority's enforcement of customer data handling standards has created competitive moats for domestic operators with embedded compliance architecture.
- Real-Time Inventory Synchronization:Grocery retailers are deploying edge computing nodes to bridge offline stock visibility with digital storefronts, reducing substitution rates in perishable categories.
Market Restraints
- Last-Mile Cost Structure:Finland's sparse population density outside Helsinki-Uusimaa inflates per-delivery costs beyond the break-even threshold for standard parcel economics.
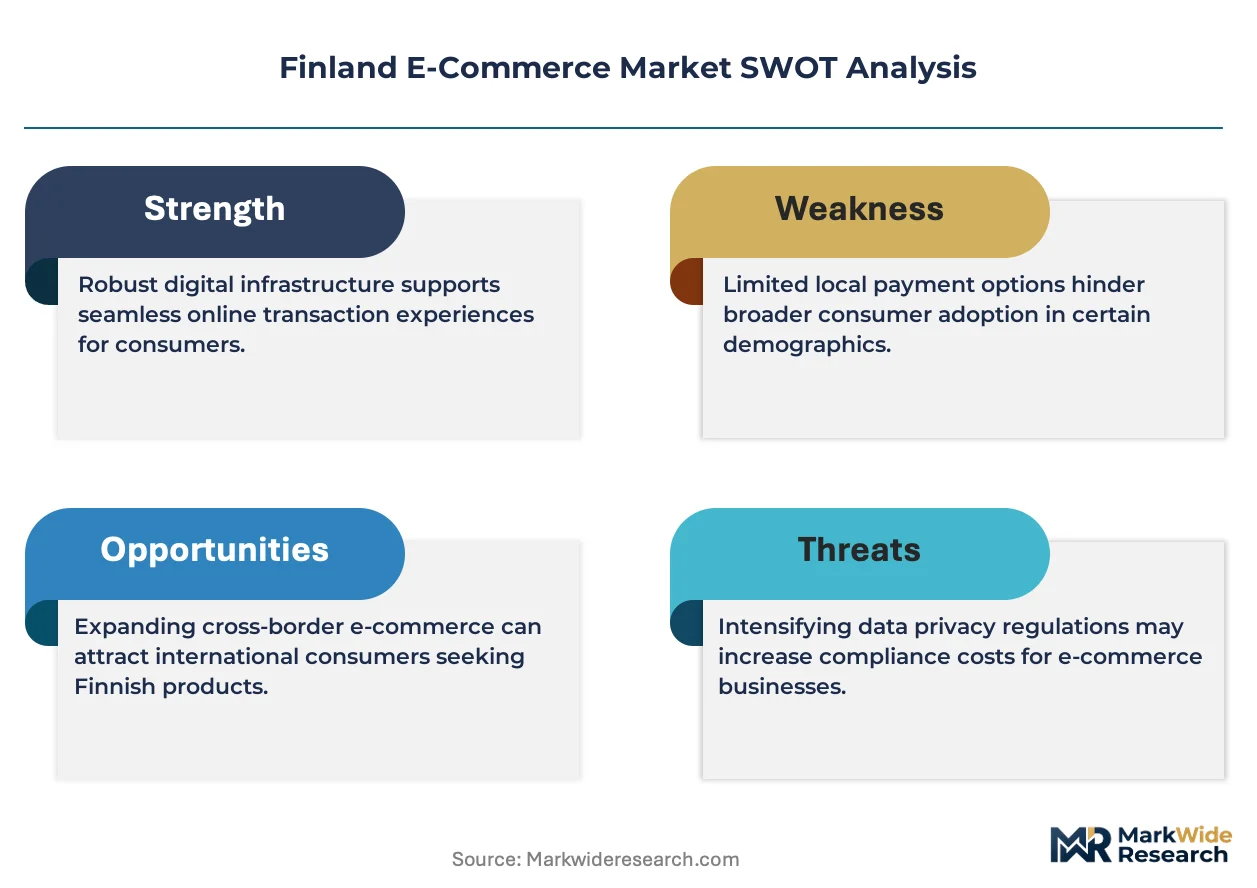
- Traficom Platform Liability Rules:The Finnish Transport and Communications Agency's evolving digital service standards impose compliance burdens that disproportionately affect cross-border marketplace entrants.
- Seasonal Demand Volatility:Arctic climate patterns concentrate e-commerce volume into narrow winter windows, straining warehouse labor availability and carrier capacity.
Strategic Opportunities
- Pirkanmaa and Tampere Cluster:Finland's second-largest urban region remains underpenetrated by dedicated fulfillment infrastructure, offering first-mover advantages for regional distribution hubs.
- B2B Procurement Digitization:Small and medium enterprises across manufacturing verticals are migrating purchasing workflows to integrated platforms, outpacing B2C growth velocity.
- Return Infrastructure Arbitrage:Zalando SE's localized sizing and reverse logistics networks demonstrate how Nordic return rates can be converted from cost center to retention tool.
Industry Challenges
- Legacy ERP Integration:Incumbent Finnish retailers operate on decades-old inventory management systems that resist API connectivity without expensive middleware layers.
- Specialized Fulfillment Talent:The shortage of engineers experienced in cold-chain orchestration and urban route optimization constrains operational scaling in grocery verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland E-Commerce Market |
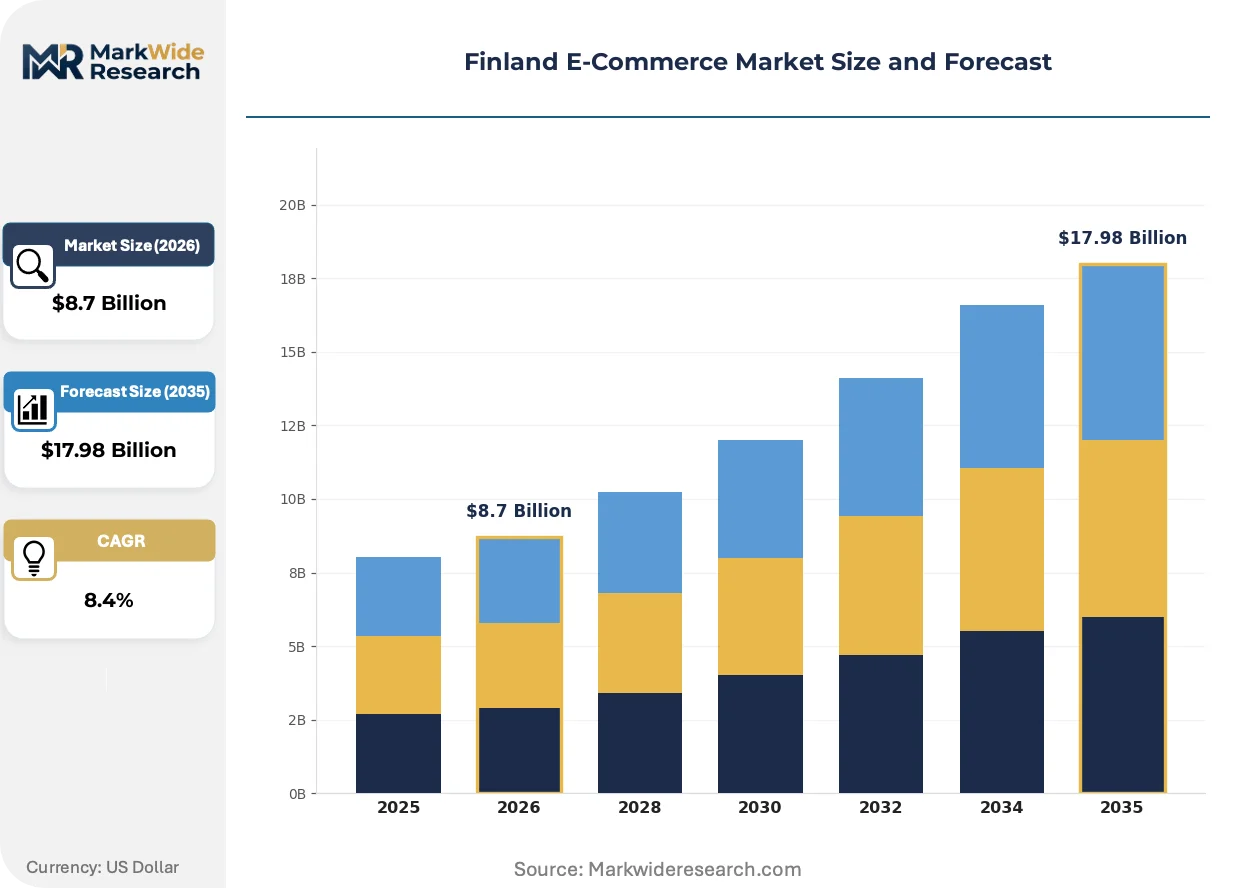
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Home Goods, Beauty Products Customer Type: B2C, B2B, C2C, Government Distribution Channel: Online Marketplaces, Retail Websites, Mobile Apps, Social Media Payment Method: Credit Card, PayPal, Bank Transfer, Mobile Payment |
| Companies Covered | Verkkokauppa.com, Zalando SE, Gigantti Oy, K-Ruoka, Tori.fi, Tokmanni Group, Motonet Oy, S-Group, Prisma.fi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland E-Commerce Market Emerging Trajectories
Finnish retail infrastructure is pivoting from channel-specific operations to unified commerce stacks where inventory, payment, and fulfillment layers operate as interchangeable services rather than fixed assets.
Composable commerce platforms are digitizing how Finnish retailers assemble their technology stacks. Mid-market merchants in the electronics and fashion verticals are adopting microservices architectures at accelerating pace. This modular approach is digitizing the traditional tradeoff between customization speed and operational stability, enabling smaller operators to match enterprise-grade personalization without captive engineering teams.
Finnish Consumer Authority distance-selling transparency enforcement is tightening disclosure requirements for pricing, delivery timelines, and return conditions. The regulatory pressure is elevating operational standards across domestic and cross-border operators alike. Electronics marketplaces with complex warranty terms face the steepest compliance adaptation costs, driving consolidation toward operators with embedded legal infrastructure.
Subscription-based replenishment models are displacing transactional purchasing in household consumables. Younger demographics in Helsinki-Uusimaa are migrating grocery and personal care spending to auto-replenishment platforms that bypass traditional search-and-select interfaces. This behavioral shift is most visible in urban Finnish households where delivery density supports economically viable subscription economics.
Finland E-Commerce Market Segmentation
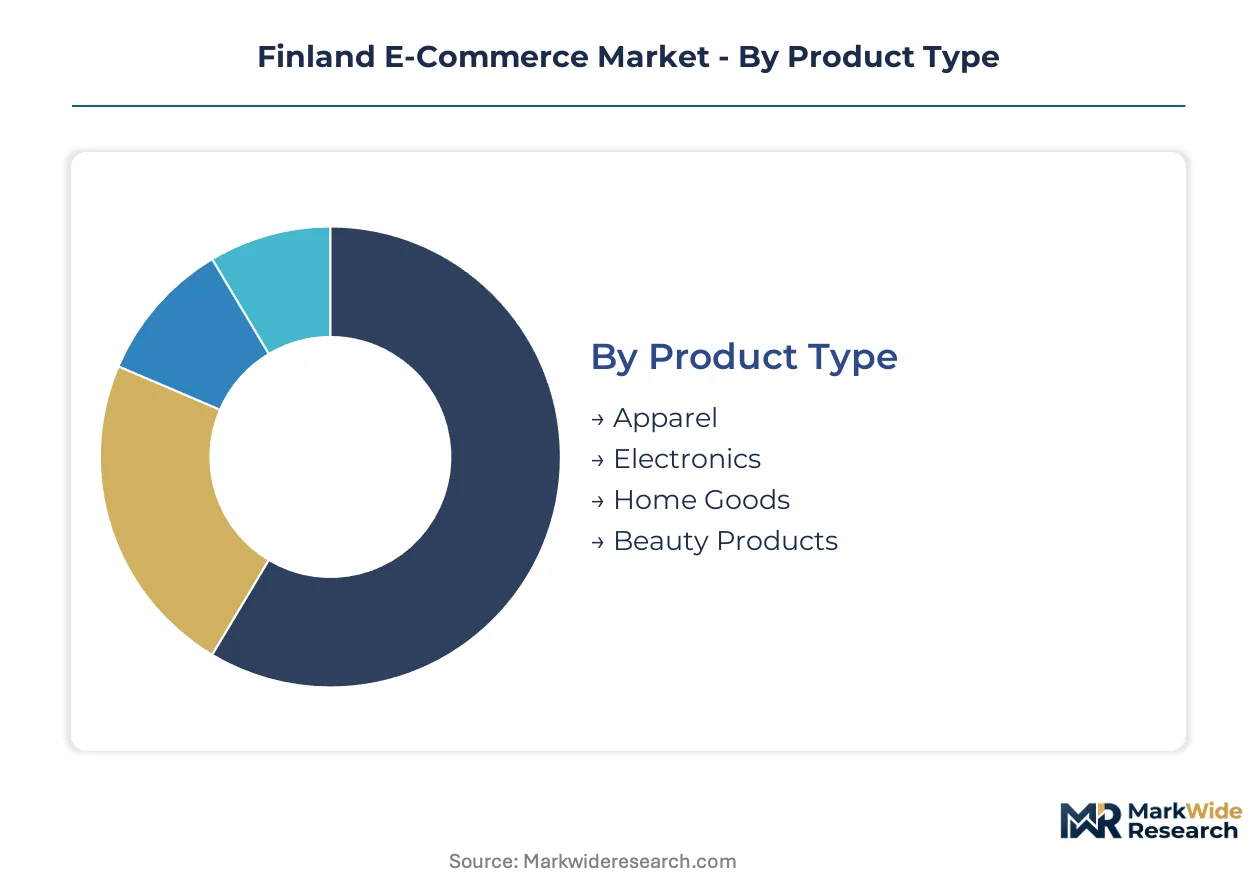
Finnish e-commerce segmentation reveals how purchasing behavior fragments across product categories and transaction contexts. Understanding these divides helps operators allocate fulfillment infrastructure and compliance resources where returns concentrate.
Product Type:
Cost tier differentiation separates high-consideration durable goods from replenishment-driven consumables in Finnish digital retail.
- Electronics:High average order values and warranty attachment rates define this segment. Helsinki-Uusimaa households drive demand for smartphones, laptops, and home appliances where delivery speed influences vendor selection.
- Apparel:Return rates run elevated due to sizing uncertainty, yet localized reverse logistics by Nordic operators have converted this friction into retention infrastructure. Urban Finnish consumers prioritize free returns over absolute price minimization.
- Home Goods:Bulky fulfillment requirements favor retailers with proprietary last-mile networks. Sparse population density outside southern Finland constrains addressable market for furniture and large appliances.
- Beauty Products:Subscription models are displacing transactional purchasing among younger demographics in capital region households. Auto-replenishment platforms bypass traditional search interfaces for skincare and personal care categories.
Electronics holds installed capacity. Beauty Products is rotating up the share rankings.
Customer Type:
Application context determines platform architecture requirements and payment integration complexity across Finnish digital commerce.
- B2C:Transaction volume concentrates here, with mobile apps capturing disproportionate engagement share among under-35 demographics. Helsinki-Uusimaa logistics density enables same-day fulfillment economics that rural geographies cannot replicate.
- B2B:Manufacturing and wholesale procurement workflows are migrating fastest to integrated platforms. Small and medium enterprises across Finnish industrial verticals drive expansion velocity exceeding consumer channels.
- C2C:Peer-to-peer marketplaces aggregate liquidity for secondhand goods and niche collectibles. Finnish Consumer Authority disclosure requirements elevate operational standards for individual sellers.
- Government:Public procurement digitization proceeds through centralized frameworks with stringent authentication protocols. Traficom digital service standards shape platform access for public sector vendors.
B2C anchors transaction volume. B2B is climbing the fastest among customer categories.
Distribution Channel:
Volume concentration patterns reveal where Finnish retailers must rebuild technology stacks around API-first fulfillment orchestration.
- Online Marketplaces:Aggregator platforms dominate electronics and fashion liquidity, concentrating consumer search behavior. Cross-border operators face elevated compliance costs under Finnish Consumer Authority distance-selling enforcement.
- Retail Websites:Direct-to-consumer channels enable margin capture and data ownership for established Finnish merchants. Headless commerce architecture narrows the gap between front-end experience and legacy inventory systems.
- Mobile Apps:Disproportionate engagement share among younger demographics drives platform investment priorities. Grocery retailers deploy edge computing nodes to bridge offline stock visibility with digital storefronts.
- Social Media:Discovery-driven purchasing concentrates in beauty and apparel verticals where influencer content reduces search friction. Purchase completion rates lag dedicated retail apps due to payment authentication friction.
Online Marketplaces holds installed capacity. Mobile Apps is gaining share fastest among distribution channels.
Payment Method:
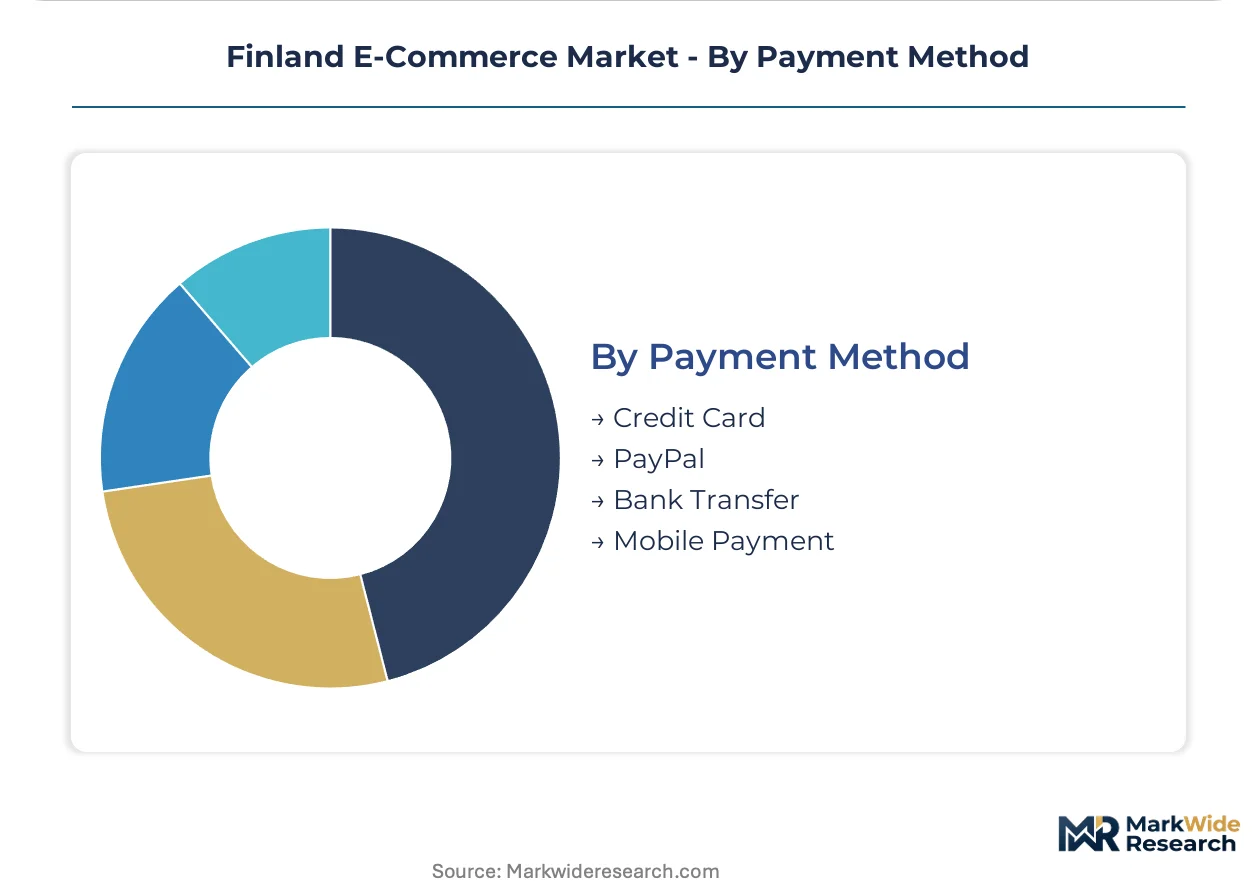
Customer trust patterns and transaction value thresholds segment Finnish payment infrastructure across authentication requirements.
- Credit Card:Dominates high-value electronics purchases where consumer protection frameworks provide dispute recourse. Finnish banks maintain strict authentication protocols under PSD2-derived standards.
- Bank Transfer:Preferred for B2B procurement and high-consideration purchases where settlement finality matters. Integration with Finnish online banking infrastructure reduces abandonment rates among established demographics.
- Mobile Payment:Expanding most quickly in urban grocery and convenience purchasing where transaction speed outweighs absolute security perception. Helsinki-Uusimaa density supports tap-to-pay infrastructure deployment.
- PayPal:Cross-border marketplace transactions favor this intermediary for buyer protection and currency handling. Finnish Data Protection Authority GDPR enforcement raises compliance costs for foreign payment aggregators.
Credit Card holds installed capacity. Mobile Payment is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German e-commerce platforms export consumer electronics and industrial components into Nordic markets, while Finnish fulfillment networks reciprocate with design-forward home goods and specialized outdoor equipment.
Helsinki-Uusimaa
Same-day delivery density and urban logistics infrastructure anchor Finnish e-commerce volume. The Finnish Consumer Authority enforces distance-selling transparency rules that elevate operational standards for all operators. Helsinki metropolitan concentration supports subscription-based replenishment models in grocery and personal care categories.
Pirkanmaa
Tampere's manufacturing base generates B2B procurement digitization demand among small and medium enterprises. Traficom digital service standards shape platform access requirements for industrial vendors. The Tampere cluster remains underpenetrated by dedicated fulfillment infrastructure, creating first-mover opportunities for regional distribution hubs.
Southwest Finland
Turku's port logistics and cross-border trade flows concentrate maritime-adjacent e-commerce fulfillment. The Finnish Data Protection Authority applies GDPR-derived rules to customer data handling across Baltic Sea shipping corridors. Turku logistics parks are attracting cold-chain investment for perishable goods distribution.
North Ostrobothnia
Oulu's technology sector drives electronics purchasing through digital channels with high average order values. Arctic climate patterns concentrate e-commerce volume into narrow winter windows, straining warehouse labor availability. Oulu's remote location inflates last-mile costs beyond standard parcel economics.
Lapland
Tourism-dependent seasonal demand creates volatile e-commerce spikes concentrated in hospitality and outdoor equipment. Sparse population density outside urban centers constrains economically viable delivery networks. Rovaniemi logistics operations focus on click-and-collect models anchored to retail physical presence.
Finland E-Commerce Market Vendor Landscape
Channel-controlling players compete with product-specialist players across Finnish digital retail. The market structure concentrates around three archetypes: vertically integrated retailers with proprietary logistics networks, marketplace aggregators leveraging Nordic return infrastructure, and grocery incumbents bridging offline stock visibility with digital storefronts. Dominant competitive moves include headless commerce architecture investments and real-time inventory synchronization capabilities.
Within the vertically integrated tier, Verkkokauppa.com and Gigantti Oy represent electronics-focused operators controlling delivery speed through captive fulfillment networks. Zalando SE anchors the marketplace aggregator position, exemplifying how localized sizing and reverse logistics convert Nordic return rates from cost center to retention infrastructure. K-Ruoka occupies the grocery incumbent archetype, integrating offline locations with digital inventory systems.
| Leading Market Players |
|---|
| Verkkokauppa.com |
| Zalando SE |
| Gigantti Oy |
| K-Ruoka |
| Tori.fi |
| Tokmanni Group |
| Motonet Oy |
| S-Group |
| Prisma.fi |
| Others |
Supply Flow & Price Mechanics
Baltic Sea shipping corridors from Germany and Poland feed Finnish e-commerce fulfillment centers, where freight cost volatility translates directly into margin compression for electronics retailers and subscription-based grocery operators competing on delivery speed.
Pricing Analysis
Technology-generation pricing gaps separate legacy monolithic platforms from API-first headless architectures and emerging edge-computing fulfillment stacks. Three-tier pricing structure across premium same-day, standard next-day, and economy multi-day delivery tiers dominates Finnish urban logistics. Price differentiation hinges on cold-chain certification for perishables and real-time inventory visibility guarantees. Pricing pressure stems from Helsinki-Uusimaa logistics density enabling aggressive speed-based competition. Small and medium enterprises in manufacturing verticals exhibit highest price sensitivity, while capital region households prioritize convenience over absolute cost minimization.
Supply Chain Analysis
Extended payment terms from Finnish grocery incumbents to regional food suppliers are compressing upstream working capital, accelerating consolidation toward distributors with supply-chain finance facilities. Geographic supply concentration centers on Germany for consumer electronics, Poland for cross-border fulfillment infrastructure, and domestic Helsinki-Uusimaa for last-mile density. Raw material dependencies span semiconductors for device inventory, packaging materials for cold-chain integrity, and cloud computing capacity for platform scalability. Single-source vulnerability in Baltic Sea shipping lanes poses structural risk. Distribution runs through proprietary logistics networks for speed-critical verticals and third-party aggregators for long-tail categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated grocery and electronics retailers with captive fulfillment networks, fragmenting margin capture away from pure marketplace operators dependent on third-party logistics.
For Market Incumbents: Build data moats through real-time inventory synchronization across offline and digital channels. Incumbents should deepen backward integration into cold-chain orchestration to defend against platform-native entrants with edge-computing infrastructure. Priority investment in GDPR-compliant customer data architecture creates regulatory defensibility against cross-border marketplace competition.
For New Entrants and Emerging Players: Pirkanmaa and Tampere's manufacturing cluster offers underpenetrated fulfillment infrastructure with first-mover economics for B2B procurement digitization. New entrants should target small and medium enterprise purchasing workflows with integrated platform solutions that bypass legacy ERP fragmentation. Go-to-market positioning around subscription-based replenishment models captures urban household retention in Helsinki-Uusimaa.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy retail conglomerates with stranded logistics assets and fragmented digital storefronts. Long-term viability favors operators with unified commerce stacks replacing channel-specific silos. Acquisition archetypes include grocery incumbents with real-time inventory capabilities and electronics specialists with proprietary last-mile networks. Signal to watch: Traficom platform liability rule evolution as inflection indicator for cross-border marketplace entry costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Headless Commerce Migration | API-first architecture enables Finnish retailers to decouple front-end experience from legacy inventory systems without full platform replacement. |
| Edge Computing Deployment | Localized processing nodes bridge offline grocery stock visibility with digital storefronts, reducing substitution rates in perishable categories. |
| Cold-Chain Infrastructure Investment | Proprietary temperature-controlled networks convert Nordic return rates from cost center to customer retention infrastructure. |
| B2B Procurement Platform Launch | Integrated purchasing workflows for Finnish manufacturing SMEs outpace consumer channel growth velocity. |
| GDPR-Compliant Data Architecture | Embedded compliance frameworks create competitive moats against cross-border operators facing Finnish Data Protection Authority enforcement. |
Methodological Framework
Cross-validation between executive interviews at Finnish retail operators and secondary trade data anchors the qualitative findings. Primary sources included CTOs at electronics marketplaces, grocery supply chain directors, platform engineers specializing in headless commerce, and logistics procurement leads at third-party fulfillment providers. Secondary validation drew from Finnish Consumer Authority enforcement disclosures, Traficom digital service standard filings, customs records for Baltic Sea trade flows, and hyperscaler cloud infrastructure expansion announcements. Bottom-up transaction volume estimates triangulated against top-down regional GDP consumption patterns.
Calibration against historical penetration rates and logistics density benchmarks shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, customer type, distribution channel, payment method, and regional logistics cluster. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and technology substitution patterns. Industry-specific forecast inputs incorporated cold-chain capacity expansion timelines and B2B procurement digitization adoption curves.
Practitioners should monitor Traficom platform liability rule evolution and Finnish Consumer Authority enforcement intensity for early signals. Forecasts reflect assumptions about sustained Helsinki-Uusimaa logistics density advantages and continued GDPR compliance cost elevation for cross-border operators. Macroeconomic contraction, regulatory deviation, or breakthrough in drone-based last-mile delivery would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Asia-Pacific Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Omnichannel Commerce Software Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Hong Kong E-Commerce Market
E-Commerce Solutions
LAMEA Dropshipping Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
New Zealand E-Commerce Market