
 Automotive Head Up Display (HUD) Market | 2026-2036
Automotive Head Up Display (HUD) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Head Up Display (HUD) Market Intelligence
Luxury vehicle manufacturers are realigning cockpit electronics procurement toward augmented reality HUD modules. Visteon Corporation leverages its display integration expertise to sustain OEM relationships across North American and European assembly plants. Continental AG anchors its position through in-house waveguide optics development, while Robert Bosch GmbH competes on software-defined HUD platforms that merge navigation with ADAS overlays.
An automotive head up display projects instrument cluster data, navigation cues, and safety alerts onto a transparent surface within the driver's forward field of view, typically employing TFT-LCD or laser-scanning projection engines with brightness exceeding 10,000 candela per square meter to maintain legibility under direct sunlight. The device eliminates downward eye movement, reducing driver reaction latency in critical braking scenarios. Augmented reality HUD systems command premium positioning due to their larger virtual image distances and real-world object overlay capabilities, while conventional combiner HUDs occupy cost-sensitive sedan segments where OEMs prioritize bill-of-material containment. LCD technology dominates current shipments, though laser-based architectures are gaining traction in luxury vehicle programs for their superior color saturation and thermal efficiency.
NHTSA guidelines on driver visual distraction, ECE R48 lighting and light-signaling device regulations, and ISO 15008 road vehicle ergonomic standards collectively define optical performance thresholds and installation geometries for HUD deployment. These frameworks elevate compliance costs for aftermarket providers while reinforcing OEM-Tier-1 captive supply relationships. Stakeholders must monitor regulatory convergence between cybersecurity mandates for connected displays and evolving autonomous vehicle HMI requirements that will redefine information layering priorities.
Market Dynamics
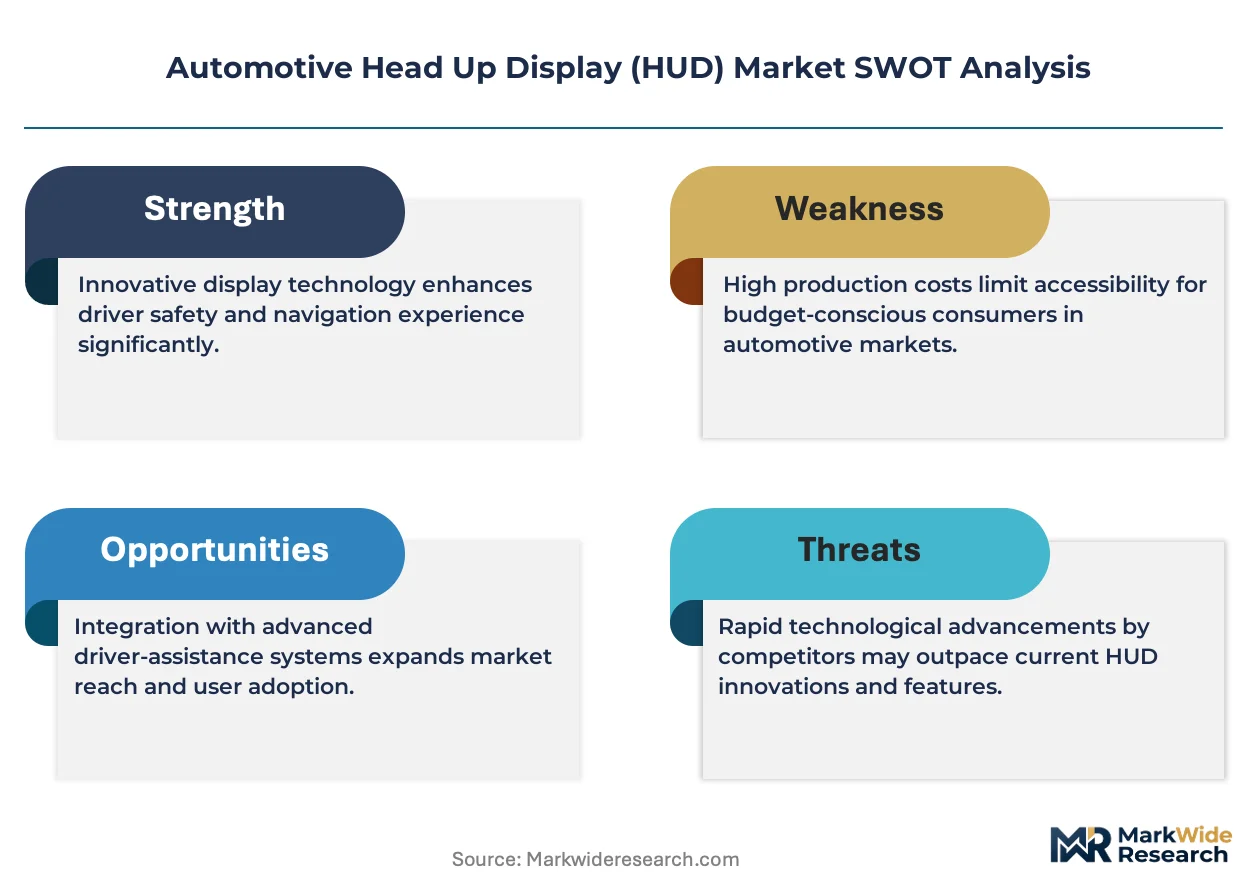
The automotive HUD sector faces intensifying pressure from augmented reality integration mandates as premium OEMs restructure cockpit electronics architectures around larger field-of-view projections and real-time object overlay capabilities.
Growth Catalysts
- NHTSA Visual Distraction Guidelines:Federal mandates on driver attention metrics are accelerating OEM adoption of eyes-forward display systems that minimize downward gaze duration during vehicle operation.
- Waveguide Optics Maturation:Advances in holographic waveguide manufacturing are collapsing the physical depth requirements of AR-HUD enclosures, enabling integration into compact vehicle platforms previously excluded from HUD programs.
- German Luxury Production Cluster:Stuttgart and Munich assembly corridors anchor concentrated demand for high-brightness projection systems as domestic OEMs compete on cockpit differentiation.
Market Restraints
- High-Brightness Display Input Costs:TFT-LCD and laser phosphor components with 10,000+ candela per square meter ratings command disproportionate bill-of-material allocations versus conventional instrument clusters.
- Windshield Lamination Concentration:Specialized wedge-angle glass production for combiner HUDs depends on a limited supplier base concentrated in Japanese and German automotive glass corridors.
- ECE R48 Certification Friction:European lighting device regulations impose extended homologation timelines for HUD optical performance validation, compressing program launch windows.
Strategic Opportunities
- Indian Passenger Vehicle HUD Penetration:Domestic OEMs in Pune and Chennai manufacturing corridors are initiating first-generation combiner HUD programs for executive sedan segments.
- ADAS-HUD Convergence:Integration of pedestrian detection alerts and lane-keeping warnings into unified augmented reality overlays creates premium pricing leverage for Tier-1 system integrators.
- China Dual Carbon Policy Alignment:Energy efficiency mandates favor laser-scanning projection architectures over thermal-intensive LED backlighting in domestic electric vehicle programs.
Industry Challenges
- Optical Design Talent Scarcity:Waveguide engineering and freeform mirror design expertise remains concentrated among a narrow cohort of specialists with automotive display backgrounds.
- ISO 15008 Ergonomic Validation:Road vehicle ergonomic standards require extensive human-factors testing for virtual image distance and eyebox positioning, extending development cycles.
- Legacy Cluster Integration Complexity:HUD deployment alongside analog instrument retention in mid-tier vehicle programs demands redundant data architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Head Up Display (HUD) Market |
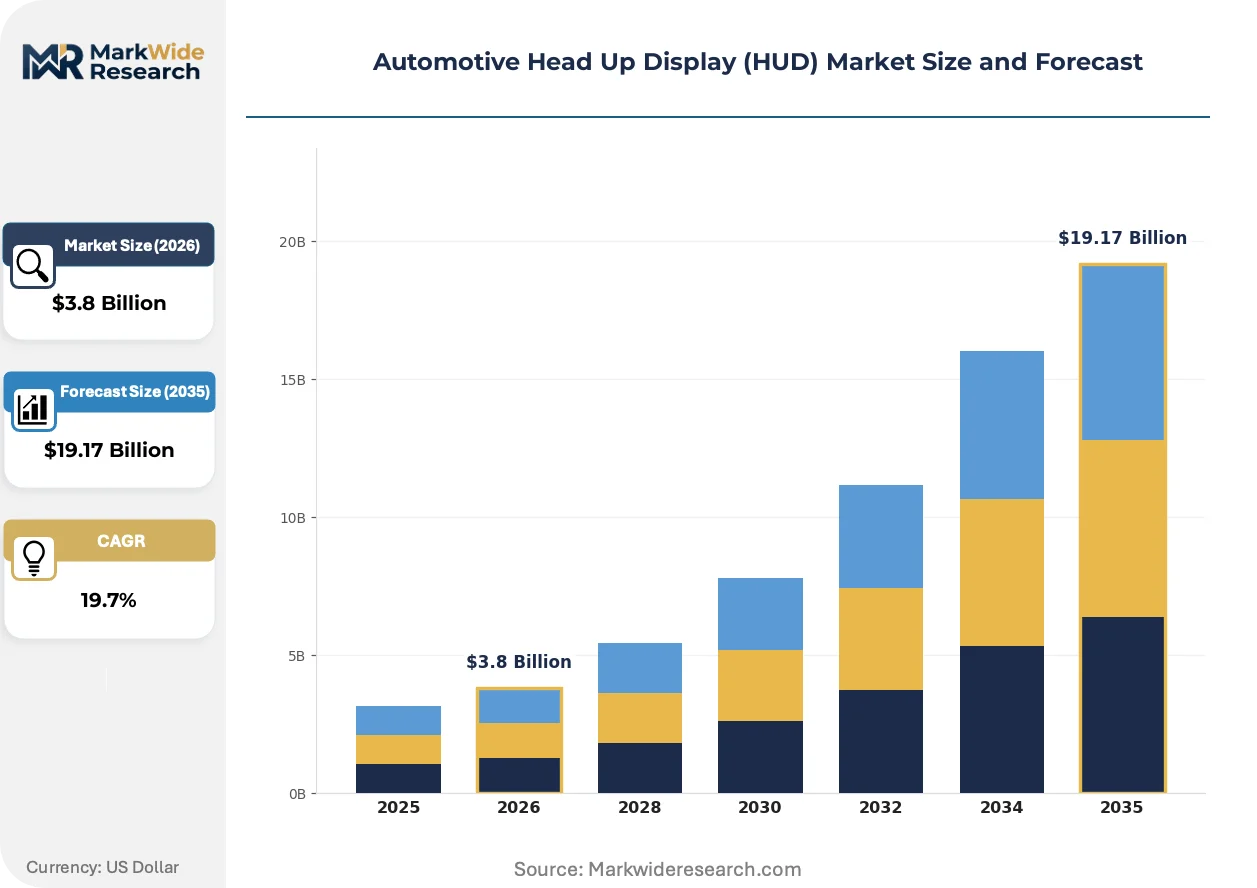
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional HUD, Augmented Reality HUD, Combiner HUD, Embedded HUD Technology: LCD, OLED, Laser, Digital Light Processing Vehicle Type: Sedan, SUV, Truck, Luxury Vehicle End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Designers |
| Companies Covered | Visteon Corporation, Valeo, Continental AG, Yazaki Corporation, Harman International, Nippon Seiki Co., Ltd., Panasonic Holdings Corporation, Robert Bosch GmbH, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Head Up Display (HUD) Market Strategic Shifts & Innovations
Projection engine architectures are fragmenting across competing technical philosophies as brightness requirements, thermal constraints, and form-factor limitations force divergent engineering commitments from system suppliers.
Laser-scanning microelectromechanical projection is converging with thermal management innovations to enable compact AR-HUD modules that previously required dashboard-occupying enclosures. German and Japanese luxury OEMs are accelerating sourcing programs around these architectures for 2027-2028 vehicle platforms. The technology is converging with autonomous vehicle HMI roadmaps by enabling dynamic information layering that scales with automation level transitions.
ECE R48 lighting regulations are tightening optical performance thresholds for head-up displays marketed within European Union member states, specifically mandating luminance uniformity metrics that challenge conventional TFT-LCD edge-lit designs. Compliance investments are elevating barriers for aftermarket providers while reinforcing captive supply relationships between OEMs and Tier-1 integrators. Premium vehicle segments bear disproportionate compliance costs as AR-HUD field-of-view expansion triggers additional photometric testing protocols.
Fleet procurement of augmented reality HUD systems is consolidating around vertically integrated cockpit electronics suppliers capable of delivering software-defined overlay platforms. North American commercial vehicle operators are prioritizing ADAS-integrated HUD specifications in heavy-duty truck replacement cycles. This concentration is most visible across long-haul freight corridors connecting Dallas-Fort Worth distribution hubs with Midwest manufacturing centers, where driver retention concerns amplify cockpit technology investments.
Automotive Head Up Display (HUD) Market Segmentation
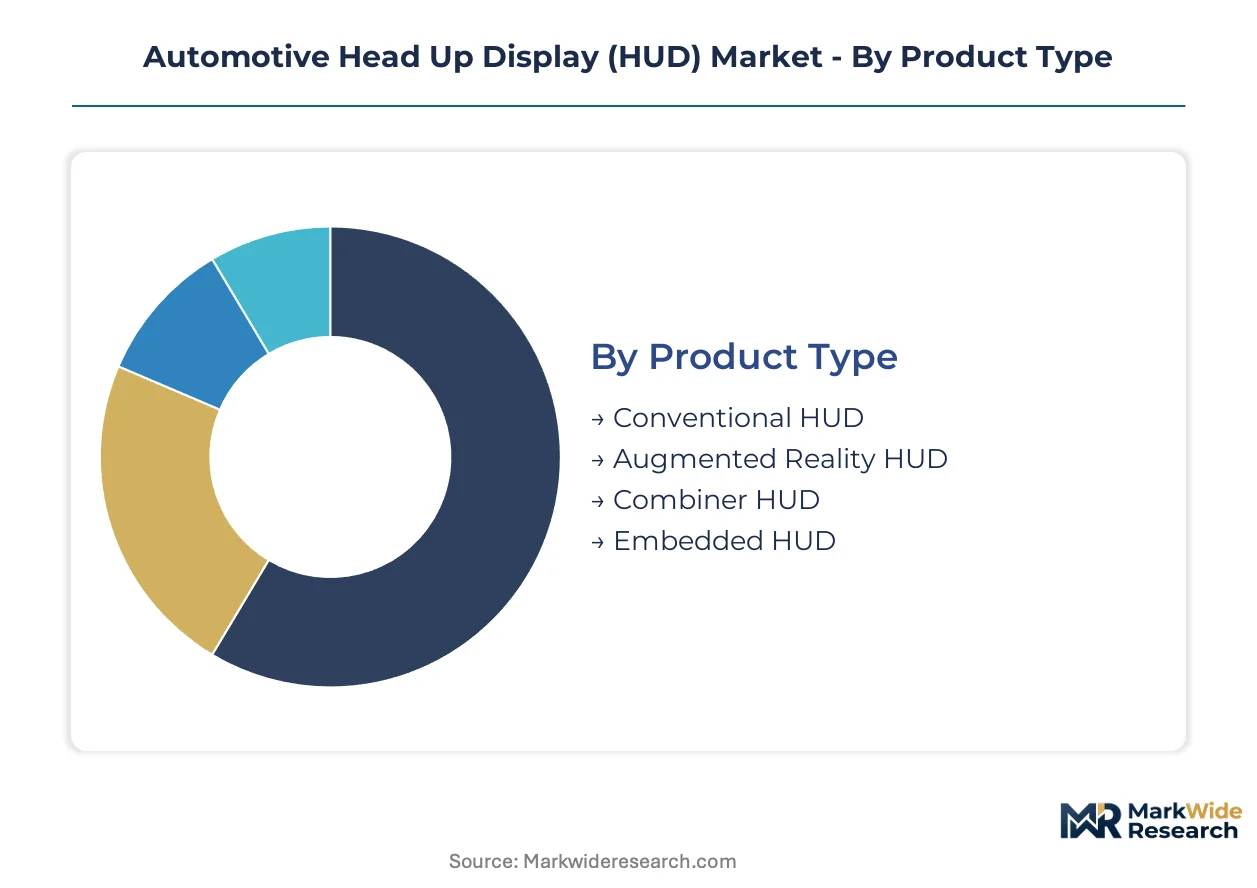
HUD procurement patterns diverge sharply across vehicle programs based on cockpit architecture constraints, thermal budgets, and regulatory exposure. Understanding these segment boundaries clarifies where component suppliers can defend margin versus where cost engineering dominates supplier selection.
Product Type:
Premium OEMs differentiate cockpit offerings through virtual image distance and field-of-view specifications that dictate enclosure depth and windshield complexity.
- Augmented Reality HUD:Projects navigation cues and ADAS alerts at 7.5-10 meter virtual distances using waveguide optics or freeform mirrors. German luxury manufacturers anchor demand in Stuttgart and Munich production corridors where cockpit differentiation commands procurement priority.
- Conventional HUD:Combines instrument cluster data onto windshield or combiner glass with 2-3 meter virtual image distances. Japanese OEMs in Nagoya and Toyota City manufacturing clusters sustain volume demand for cost-constrained sedan programs.
- Combiner HUD:Standalone transparent screens reduce windshield lamination costs for entry-luxury segments.
- Embedded HUD:Integrates projection modules within instrument panel structures for compact vehicle platforms.
Conventional HUD leads volumes today; Augmented Reality HUD is gaining share fastest.
Technology:
Thermal management requirements and color gamut specifications separate procurement tiers across projection engine architectures.
- LCD:Edge-lit TFT-LCD panels dominate current shipments with 10,000+ candela per square meter brightness ratings. Supply concentrates among Korean and Taiwanese display manufacturers serving cost-optimized vehicle programs where thermal budgets constrain alternative architectures.
- Laser:MEMS-scanning laser phosphor systems deliver superior color saturation and reduced thermal load. German and Japanese luxury OEMs are accelerating sourcing programs for 2027-2028 platforms where energy efficiency mandates favor laser over LED backlighting.
- OLED:Self-emissive organic panels enable thinner form factors but face brightness limitations under direct sunlight.
- Digital Light Processing:DLP chipsets from Texas Instruments enable high-resolution projection with minimal motion blur.
LCD commands installed base; Laser is climbing the fastest as efficiency regulations tighten.
Vehicle Type:
Cockpit electronics budgets scale with vehicle segment positioning and average selling price brackets.
- Luxury Vehicle:AR-HUD integration rates approach saturation among German premium OEMs competing on HMI sophistication. Stuttgart-based manufacturers mandate 12-degree horizontal field-of-view minimums that drive waveguide optics adoption.
- SUV:Higher dashboard profiles accommodate larger HUD enclosures without compromising legroom. North American production lines in Michigan and Tennessee anchor SUV HUD penetration where driver assistance feature bundling accelerates display adoption.
- Sedan:Compact cockpit dimensions constrain AR-HUD deployment to conventional combiner systems.
- Truck:Commercial vehicle operators prioritize ADAS-integrated specifications for long-haul freight applications.
Luxury Vehicle dominates revenue contribution; SUV shows steepest expansion trajectory.
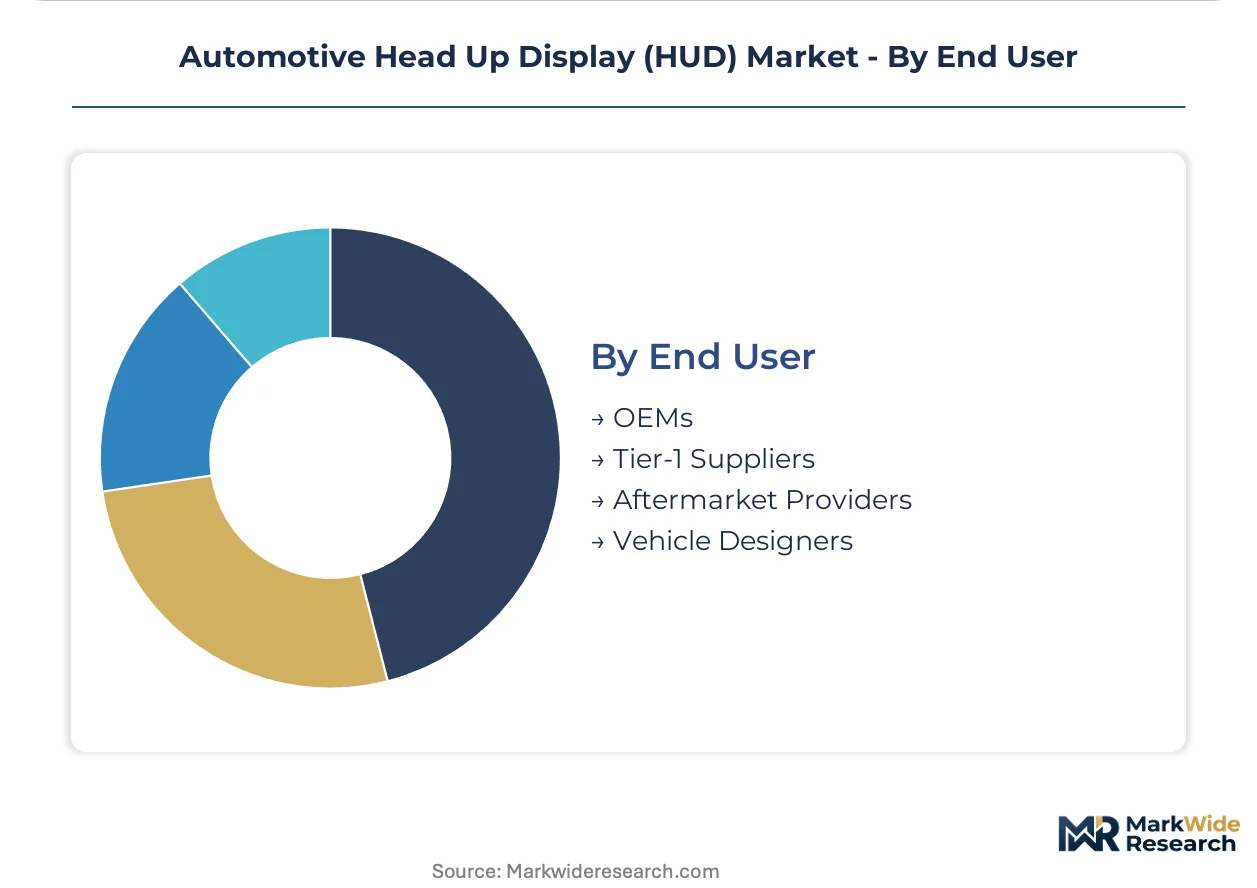
End User:
Supply chain position determines regulatory exposure and software integration responsibilities.
- OEMs:Captive cockpit electronics divisions at BMW, Mercedes-Benz, and Audi specify AR-HUD architectures that merge navigation with autonomous vehicle HMI roadmaps. Direct procurement of waveguide optics and projection engines bypasses traditional Tier-1 relationships for flagship programs.
- Tier-1 Suppliers:Continental, Bosch, and Denso integrate display modules with vehicle network architectures. These suppliers bear ECE R48 homologation costs and ISO 15008 ergonomic validation burdens that aftermarket providers cannot absorb.
- Aftermarket Providers:Face elevated certification friction under NHTSA visual distraction guidelines and limited access to wedge-angle windshield supply.
- Vehicle Designers:Influence early-stage cockpit architecture decisions that lock in HUD form-factor constraints.
Tier-1 Suppliers capture majority volume; OEM direct procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global HUD demand through Mercedes-Benz and Porsche cockpit electronics programs. German luxury OEMs mandate augmented reality specifications that drive waveguide optics adoption. Japanese and North American production corridors follow with concentrated sourcing for conventional combiner systems.
United States
NHTSA visual distraction guidelines accelerate OEM adoption of eyes-forward display architectures. Federal mandates on driver attention metrics compress certification timelines for Tier-1 suppliers. Michigan and Tennessee assembly plants anchor SUV HUD penetration where driver assistance feature bundling accelerates display procurement.
Germany
ECE R48 lighting regulations impose extended homologation timelines for HUD optical performance validation. KBA certification requirements elevate compliance costs for aftermarket providers. Stuttgart and Munich manufacturing corridors sustain concentrated demand for high-brightness projection systems as domestic OEMs compete on cockpit differentiation.
Japan
METI energy efficiency mandates favor laser-scanning projection architectures over thermal-intensive LED backlighting in domestic electric vehicle programs. JIS standards govern ergonomic performance thresholds for virtual image positioning. Nagoya and Toyota City manufacturing clusters sustain volume demand for cost-constrained sedan programs.
China
Dual carbon policy alignment favors laser-based HUD architectures in domestic NEV programs. MIIT technical standards govern display brightness and thermal management specifications. Yangtze River Delta production corridors concentrate waveguide optics manufacturing for export-oriented luxury vehicle supply chains.
South Korea
Domestic OEMs accelerate AR-HUD integration for Genesis and Kia premium platforms. MFDS automotive electronics guidelines intersect with KATRI testing protocols for display legibility. Seoul Capital Area R&D centers concentrate freeform mirror design expertise for next-generation projection modules.
Automotive Head Up Display (HUD) Market Key Industry Players
Strategic partnerships dominate the current landscape as Tier-1 suppliers secure captive supply relationships with premium OEMs. The vendor base organizes around three tiers: vertically integrated cockpit electronics divisions, specialized optical component fabricators, and software-defined overlay platform developers. Two strategic archetypes prevail—waveguide optics specialists and laser-scanning projection engineers. M&A activity concentrates on holographic waveguide manufacturing capabilities, while capacity expansion focuses on compact AR-HUD modules for compact vehicle platforms.
Within the integrated systems tier, Visteon Corporation and Continental AG exemplify full-stack HUD platform development. Robert Bosch GmbH occupies a position bridging optical hardware with software-defined overlay architectures. Japanese specialists including Nippon Seiki Co., Ltd. and Yazaki Corporation anchor the conventional combiner segment through long-standing supply relationships with domestic OEMs.
| Leading Market Players |
|---|
| Visteon Corporation |
| Valeo |
| Continental AG |
| Yazaki Corporation |
| Harman International |
| Nippon Seiki Co., Ltd. |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Laser-scanning MEMS projection maturation simultaneously collapses thermal management costs and concentrates procurement leverage among German and Japanese optics specialists capable of volume manufacturing. This technological pivot reshapes supplier selection criteria as OEMs trade upfront module premiums against lifetime energy efficiency gains in electric vehicle programs.
Pricing Analysis
Input-cost pass-through from specialized wedge-angle windshield glass and high-brightness laser phosphor components governs module economics. Three-tier pricing structure across AR-HUD, conventional combiner, and embedded entry systems reflects certification grade and field-of-view specifications. Pricing pressure stems from TFT-LCD oversupply in Korean and Taiwanese display corridors compressing margins in cost-optimized vehicle programs. Fleet procurement teams at North American commercial operators exhibit highest price sensitivity, while German luxury OEMs prioritize optical performance over bill-of-material containment.
Supply Chain Analysis
Dual-sourcing requirements for waveguide optics and freeform mirror components mandate multi-supplier qualification across German, Japanese, and South Korean manufacturing corridors. Raw material dependencies center on rare-earth phosphors for laser excitation, specialized optical-grade polymers, and precision-machined aluminum housings. Single-source vulnerability concentrates in holographic waveguide etching equipment held by a narrow equipment vendor cohort. Distribution runs through captive Tier-1 integrator relationships rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential between ECE R48 certification burdens in Europe and NHTSA's comparatively streamlined visual distraction guidelines in the United States, creating cost-differential opportunities for suppliers with dual-homologation capabilities.
For Market Incumbents: Acquire holographic waveguide manufacturing assets to secure captive supply of AR-HUD optical engines. Backward integration into precision glass lamination mitigates windshield supplier concentration risk. Capacity expansion in Yangtze River Delta production corridors captures Chinese NEV program demand while hedging against European homologation timeline compression. For New Entrants and Emerging Players: Launch via direct OEM engagement in Indian executive sedan segments where first-generation combiner HUD programs lack established supplier relationships. White-space opportunities concentrate in aftermarket fleet retrofit specifications for North American long-haul freight operators. Target software-defined overlay platforms as the most penetrable layer, avoiding capital-intensive optical hardware fabrication. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized waveguide engineering boutiques with automotive display backgrounds but limited production scale. Long-term viability hinges on 5-10 year autonomous vehicle HMI roadmap alignment. Monitor ADAS-HUD convergence contract announcements as the primary inflection signal for premium pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Waveguide Optics Acquisition | Captures scarce holographic etching expertise concentrated in German optical corridors. |
| Laser Projection Platform Launch | Aligns with METI energy efficiency mandates favoring MEMS-scanning architectures. |
| India Manufacturing Footprint | Positions for Pune and Chennai OEM combiner HUD procurement programs. |
| ADAS Integration Partnership | Merges pedestrian detection overlays with navigation cues for premium Tier-1 pricing. |
| Dual Certification Investment | Enables simultaneous ECE R48 and NHTSA compliance for cross-regional OEM supply. |
Research Approach
Bottom-up vehicle production modeling reconciled against top-down projection engine shipment tracking forms the analytical core. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists cross-validated against vehicle registration databases, IHS Markit production forecasts, and customs trade records. Secondary sources include ECE R48 homologation filings, NHTSA visual distraction guideline documentation, and ISO 15008 ergonomic standard protocols.
Historical trendline analysis across LCD and laser projection technology cost curves informed adoption trajectory assumptions. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from fitted growth curves applied to technology-specific penetration rates, with electric vehicle HUD attach rates and AR-HUD field-of-view expansion serving as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory convergence scenarios between cybersecurity mandates and autonomous vehicle HMI requirements. Deviation in waveguide optics manufacturing yield rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Ventilated Seats Market