
 Ethylenediaminetetraacetic Acid Market | 2026-2036
Ethylenediaminetetraacetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylenediaminetetraacetic Acid Market Analysis
ISO 22000 certification for food-grade chemical handling is unwinding the competitive landscape for smaller EDTA manufacturers lacking integrated quality systems. BASF SE leverages its Ludwigshafen integrated production complex to sustain captive supply of ethylenediamine feedstock. Dow Inc. anchors North American supply through its Midland manufacturing infrastructure and direct channel relationships with industrial water treatment operators. Nouryon competes on specialty-grade derivatives for pharmaceutical and personal care applications where residual metal control commands premium positioning.
Ethylenediaminetetraacetic acid is a hexadentate aminopolycarboxylic acid with the molecular formula C₁₀H₁₆N₂O₈, synthesized via condensation of ethylenediamine with formaldehyde and sodium cyanide or via the Strecker route, functioning primarily as a sequestering agent that binds divalent and trivalent metal ions to prevent catalytic degradation, scale formation, and oxidative spoilage across industrial and consumer systems. Pharmaceutical-grade EDTA leads value generation due to stringent USP and EP monograph compliance burdens that limit qualified supply, while food-grade powder formats are expanding fastest in beverage stabilization and preservative applications where clean-label pressures intensify metal-chelate demand. Industrial-grade liquid concentrates remain the volume anchor in boiler water treatment and textile processing, though margin compression from commoditized Asian supply constrains profitability for non-integrated Western producers.
EPA effluent limitation guidelines and REACH Annex XVII restrictions on persistent chelating agents in European waterways are forcing reformulation toward biodegradable alternatives in select industrial discharge applications, though no drop-in substitute matches EDTA's cost-performance ratio across all use cases. FDA food additive regulations and USP-NF monograph updates for pharmaceutical-grade material govern purity thresholds, lot traceability, and impurity profiling that directly determine supplier qualification status for North American and European formulators. China's NMPA and evolving GB standards for food-contact chemicals add parallel compliance layers for exporters serving Asian pharmaceutical and food processing markets. Stakeholders must monitor regulatory divergence between biodegradability mandates in Europe and performance-driven specification standards in Asia-Pacific to anticipate where formulation switching versus specification tightening will reshape procurement priorities.
Market Dynamics
REACH Annex XVII restrictions on persistent chelating agents are forcing European industrial water treatment operators toward biodegradable alternatives, while Chinese domestic production capacity expansion reshapes export pricing power for Western manufacturers lacking integrated ethylenediamine supply.
Growth Catalysts
- Boiler water treatment standards:Power generation facilities in India and Southeast Asia are adopting automated dosing systems that specify high-purity EDTA for scale inhibition, tightening supplier qualification requirements.
- REACH compliance timelines:ECHA registration dossier updates for existing chelating agents are accelerating replacement demand in metal plating applications where process validation cycles exceed 18 months.
- Food-contact material migration limits:China's SAMR is enforcing stricter GB standards for beverage can linings, expanding metal-chelate demand in acidic drink stabilization.
Market Restraints
- Ethylenediamine feedstock volatility:Natural gas-derived ethylene and ammonia cost swings compress margins for non-integrated producers lacking captive amine supply.
- Biodegradable substitute performance gap:Glutamic acid diacetic acid and methylglycinediacetic acid fail to match EDTA's thermal stability above 150°C in oilfield applications.
- Chinese supply concentration:Shandong and Jiangsu province producers control 60% of global industrial-grade liquid output, creating procurement risk for European compounders.
Strategic Opportunities
- Pharmaceutical-grade certification scarcity:USP-NF and EP monograph compliance burdens limit qualified suppliers for parenteral drug metal sequestration, supporting premium positioning.
- Personal care preservative reformulation:Clean-label pressure in Western European cosmetics is displacing parabens with metal-chelate systems in emulsion stabilization.
- Textile dyeing effluent recovery:Zero liquid discharge mandates in India's Tiruppur cluster are creating closed-loop chelating agent reuse specifications.
Industry Challenges
- Analytical method validation timelines:ICP-MS impurity profiling for pharmaceutical-grade lots requires 12-16 week stability studies, delaying new supplier qualification.
- Legacy water treatment infrastructure:Municipal boiler systems in Eastern Europe lack automated dosing compatibility, forcing manual handling protocols that increase contamination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylenediaminetetraacetic Acid Market |
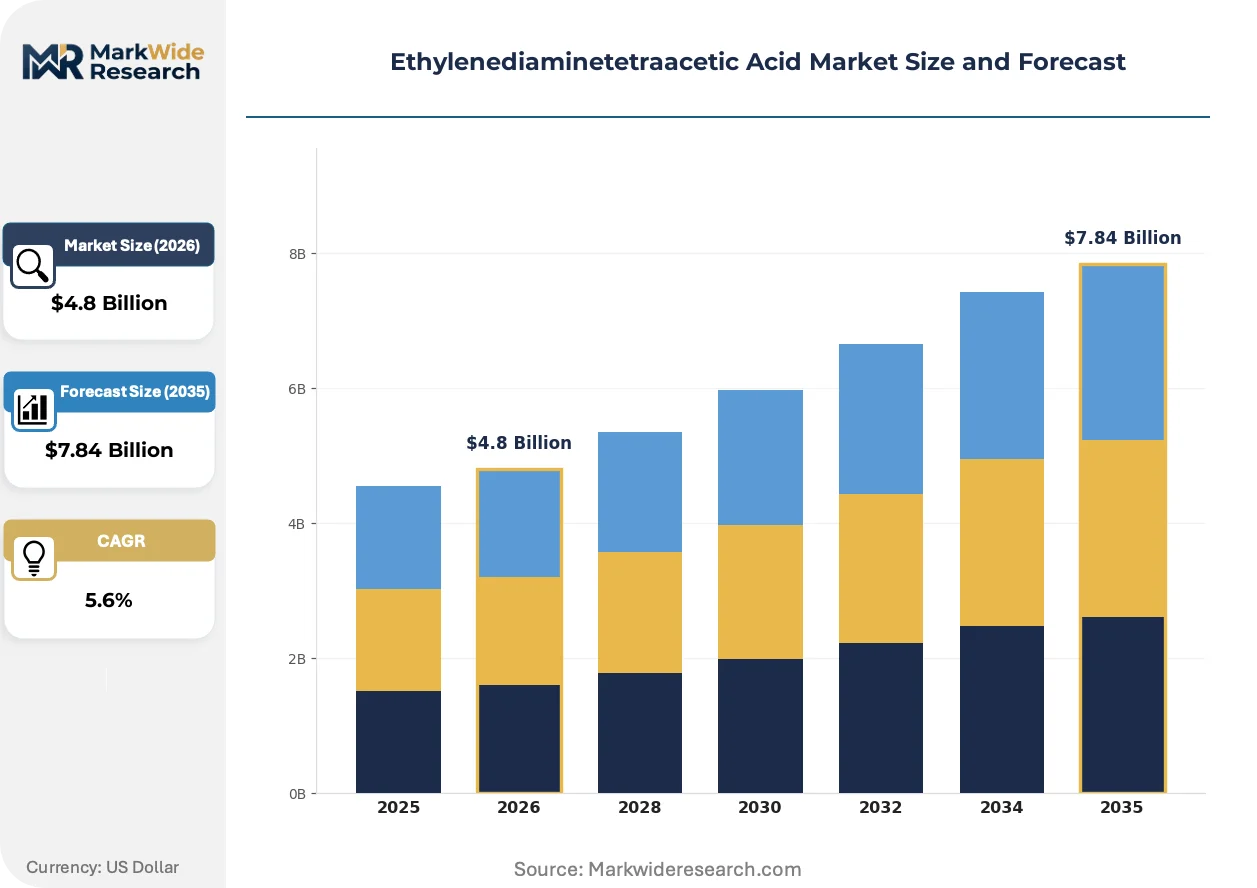
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Crystals End Use Industry: Pharmaceuticals, Agriculture, Food & Beverage, Industrial Packaging Type: Bags, Drums, Containers, Bottles Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade |
| Companies Covered | BASF SE, Dow Inc., AkzoNobel N.V., LG Chem Ltd., ChengXin, Nouryon, Nippon Shokubai Co., Ltd., FMC Corporation, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylenediaminetetraacetic Acid Market Emerging Trajectories
Formulation science is converging with regulatory toxicology to redefine acceptable chelating agent performance, while digital traceability systems reshape how purity documentation flows through pharmaceutical and food-contact supply chains.
Green synthesis routes using enzymatic catalysis rather than cyanide-based Strecker chemistry are displacing conventional production methods in European pharmaceutical-grade manufacturing. Bayer and Lonza pilot facilities in Germany and Switzerland have validated fermentation-derived ethylenediamine feedstocks for USP-compliant output. This displacement is compressing capital efficiency advantages for legacy Chinese producers dependent on petrochemical ethylene oxide routes.
ECHA's 2024 updated assessment of EDTA environmental persistence is tightening discharge consent limits for industrial laundries and metal finishing operations across Germany, France, and the Netherlands. The regulation forces operators to install tertiary treatment or switch to biodegradable alternatives in non-critical temperature applications. Nordic paper pulp bleaching facilities are responding fastest, with Stora Enso and UPM piloting GLDA substitution in peroxide stabilization.
Certificate-of-analysis verification is migrating from paper documentation to blockchain-anchored digital twins for pharmaceutical-grade shipments. European generic drug manufacturers and their API suppliers are adopting this traceability layer to satisfy FDA data integrity expectations during pre-approval inspections. The shift is most visible in Indian export corridors, where CDSCO-aligned facilities serving US and EU markets are upgrading ERP systems to auto-populate eCTD submission packages.
Ethylenediaminetetraacetic Acid Market Segmentation
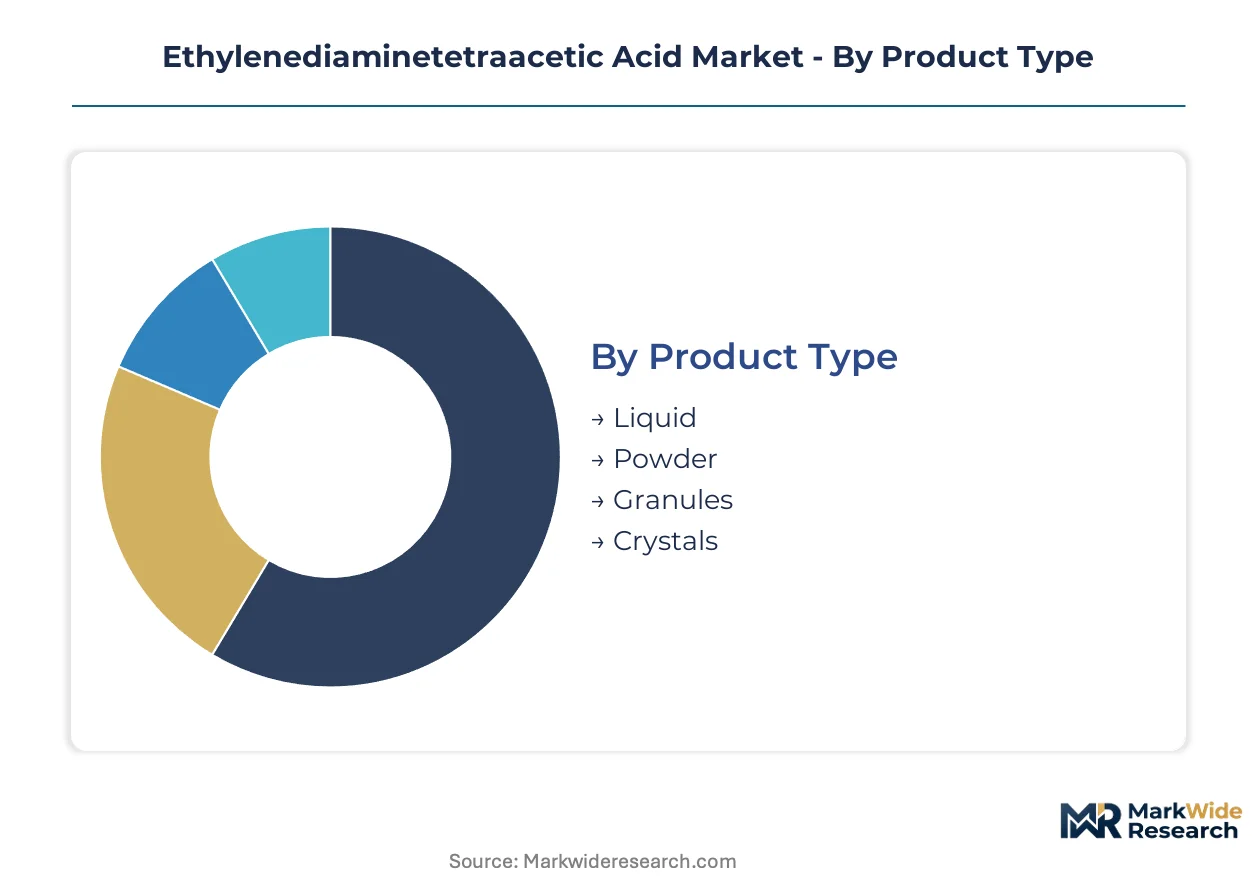
EDTA's molecular versatility creates divergent value capture across physical formats and purity tiers. Substitution pressure from biodegradable alternatives varies sharply by segment, reshaping investment priorities for manufacturers navigating regulatory fragmentation.
Product Type:
Liquid and powder formats face divergent substitution threats based on thermal stability requirements and handling infrastructure compatibility.
- Liquid:Aqueous solutions at concentrations typically deliver ready-to-dose convenience for continuous industrial processes. Demand concentrates in US power plant boiler water treatment where automated injection systems specify stabilized formulations; REACH-driven reformulation in German metal finishing is compressing growth in legacy applications.
- Powder:Spray-dried or milled solid forms enable precise dry-blending in food and pharmaceutical compounding. Japanese beverage manufacturers and Indian generic drug formulators are expanding procurement of low-dust, free-flowing grades; clean-label packaging requirements in Western Europe are accelerating specification tightening.
- Granules:Agglomerated particles balance flowability with reduced caking tendency for agricultural chelate manufacturing.
- Crystals:High-purity recrystallized forms serve analytical reagent and specialty electronics cleaning applications.
Liquid retains volume leadership; powder holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates premium-certified applications from commoditized industrial consumption.
- Pharmaceuticals:Parenteral drug formulations and API manufacturing demand USP-NF and EP monograph compliance with exhaustive impurity profiling. US generic injectable producers and European biosimilar manufacturers are consolidating qualified supplier lists; CDSCO-aligned Indian exporters face 12-16 week analytical validation timelines.
- Industrial:Boiler water treatment, textile processing, and metal plating consume standardized chelating capacity at scale. Chinese Shandong and Jiangsu producers dominate supply to Southeast Asian power utilities; EPA effluent guidelines are forcing tertiary treatment investment at US discharge points.
- Agriculture:Micronutrient chelation for foliar fertilizers and soil amendments drives demand for cost-optimized technical grades.
- Food & Beverage:Metal sequestration in canned acidic drinks and preservative systems requires food-contact migration compliance under FDA and China's SAMR GB standards.
Industrial commands absolute volume; pharmaceuticals generate the highest margin realization.
Packaging Type:
Customer type and handling sophistication dictate format selection across institutional and artisanal scale operations.
- Drums:Standard 200-liter steel or polymer drums serve mid-scale industrial compounders with established material handling infrastructure. Brazilian metal finishers and Mexican food processors rely on drum logistics; drum deposit return schemes in Germany add operational complexity.
- Bags:Multi-layer paper or woven polypropylene sacks enable bulk dry handling for agricultural and technical grade distribution. Indian fertilizer blenders and Indonesian textile dyers specify 25-50 kg units; moisture barrier specifications vary by monsoon exposure risk.
- Containers:Intermediate bulk containers and totes support high-volume continuous manufacturing with reduced handling labor.
- Bottles:Laboratory and pilot-scale packaging for analytical reagent and pharmaceutical R&D sampling.
Drums anchor institutional procurement; bags dominate emerging market agricultural distribution.
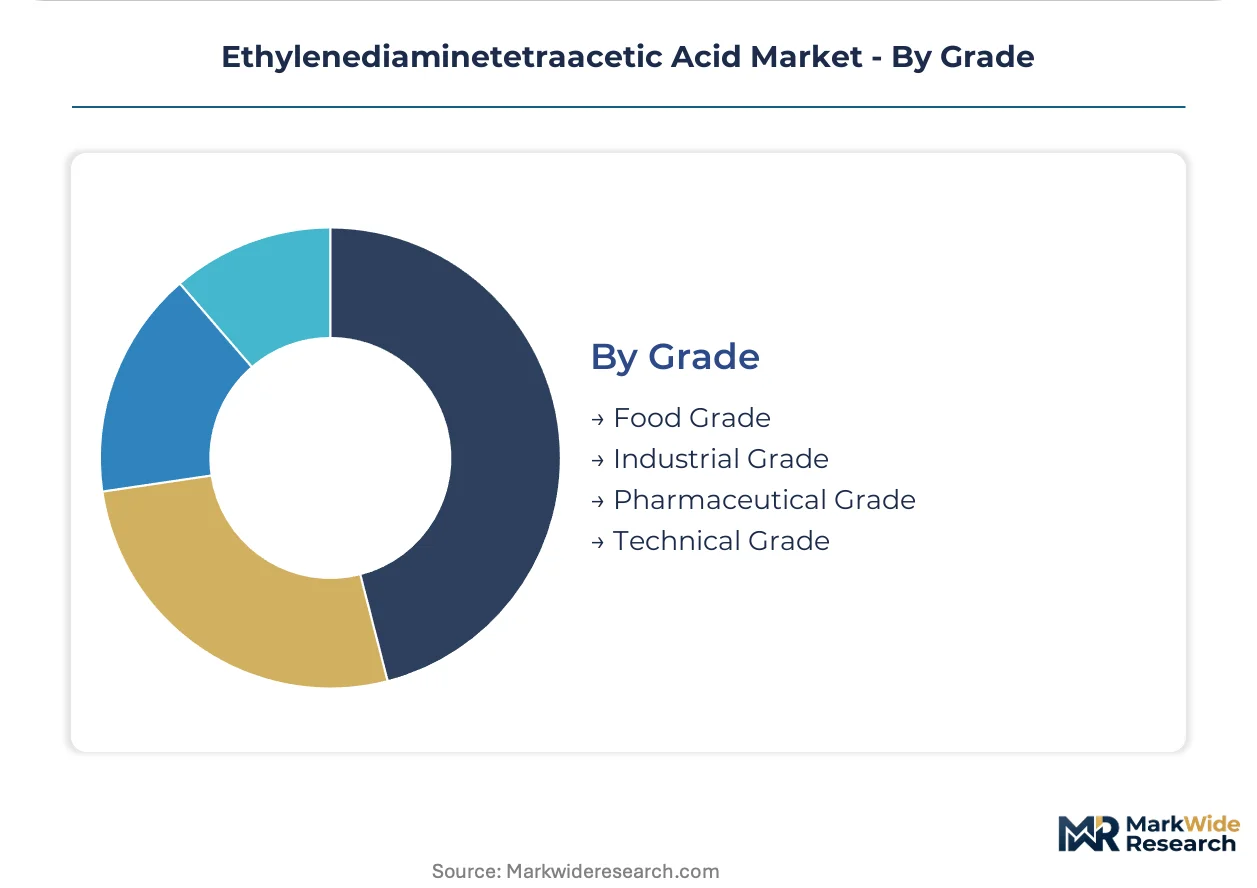
Grade:
Supply concentration in certified grades creates qualification barriers that protect incumbent positioning.
- Pharmaceutical Grade:USP-NF and EP monograph compliance with ICH Q3D elemental impurity limits commands systematic documentation. Lonza's Swiss facilities and select Indian CDSCO-aligned plants maintain active qualification; new supplier entry requires 18-24 month process validation cycles.
- Food Grade:ISO 22000 certification and FDA food additive regulation compliance enable beverage stabilization and preservative applications. European clean-label pressure is displacing parabens with metal-chelate systems; China's SAMR enforcement of GB migration limits is tightening exporter documentation.
- Industrial Grade:Standardized chelating value specifications for non-critical temperature applications face intense price competition.
- Technical Grade:Minimum purity thresholds for agricultural and basic chemical synthesis applications.
Industrial Grade maintains volume dominance; Pharmaceutical Grade captures the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Annex XVII restrictions on persistent chelating agents are redirecting procurement patterns across European industrial water treatment, while Chinese capacity expansion and Indian pharmaceutical export growth reshape competitive positioning in Asia-Pacific.
China
Shandong and Jiangsu province producers control sixty percent of global industrial-grade liquid output, serving both domestic agrochemical formulation and export-oriented pharmaceutical manufacturing. NMPA and evolving GB standards for food-contact chemicals add parallel compliance layers for exporters. The Yangtze River Delta concentration of chelating agent plants is scaling fermentation-derived ethylenediamine pilot capacity to meet pharmaceutical-grade certification demand.
Germany
ECHA registration dossier updates for existing chelating agents are accelerating replacement demand in metal plating applications where process validation cycles exceed eighteen months. The country's national chemical regulator enforces discharge consent limits that force operators toward biodegradable alternatives in non-critical temperature applications. Ludwigshafen's integrated production complex sustains captive supply advantages for pharmaceutical-grade output serving European biosimilar manufacturers.
United States
EPA effluent limitation guidelines are tightening purity specifications and reshaping supplier qualification requirements for industrial water treatment operators. FDA food additive regulations and USP-NF monograph updates govern purity thresholds and lot traceability for North American formulators. The Midland manufacturing infrastructure anchors North American supply through direct channel relationships with power generation facilities adopting automated dosing systems.
India
CDSCO-aligned facilities serving US and EU markets face twelve-to-sixteen week analytical validation timelines for ICP-MS impurity profiling of pharmaceutical-grade lots. The country's national pharmaceutical regulator enforces data integrity expectations during pre-approval inspections that drive ERP system upgrades. The Tiruppur textile cluster's zero liquid discharge mandates are creating closed-loop chelating agent reuse specifications for effluent recovery systems.
Japan
PMDA oversight of pharmaceutical-grade material maintains stringent impurity profiling requirements that limit qualified supplier lists for parenteral drug formulations. The country's national standards body governs specifications for beverage can lining applications where metal sequestration prevents acidic drink degradation. Japanese beverage manufacturers are expanding procurement of low-dust, free-flowing powder grades for clean-label packaging requirements.
Ethylenediaminetetraacetic Acid Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with integrated petrochemical giants and regional chelating agent producers dividing the market between premium-grade scarcity and industrial-volume commoditization. The vendor base fragments across three strategic archetypes: backward-integrated chemical conglomerates with captive ethylenediamine supply, specialty-grade pure-plays focused on pharmaceutical and personal care certification, and cost-optimized Asian producers serving agricultural and technical applications. Dominant competitive moves include capacity expansion in Chinese Shandong and Jiangsu provinces and strategic partnerships between European formulators and Indian CDSCO-aligned exporters.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. exemplify backward-integrated positioning through Ludwigshafen and Midland production complexes respectively. Nouryon occupies a position among specialty-grade pure-plays where residual metal control commands premium positioning in pharmaceutical and personal care applications.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| AkzoNobel N.V. |
| LG Chem Ltd. |
| ChengXin |
| Nouryon |
| Nippon Shokubai Co., Ltd. |
| FMC Corporation |
| Tosoh Corporation |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII restrictions on persistent chelating agents simultaneously gate supplier qualification and amplify price differentiation between biodegradable-compliant and legacy formulations across European industrial procurement. This regulatory interface compresses margins for non-integrated producers while rewarding backward-integrated manufacturers with captive ethylenediamine supply.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade USP-NF monograph material and industrial-grade liquid concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects USP-NF/EP compliance burdens, ISO 22000 food-grade handling, and technical-grade agricultural applications. Cost compression in industrial-grade segments is intensifying because Shandong and Jiangsu province producers flood export markets with standardized output. Municipal water treatment operators exhibit highest price sensitivity; parenteral drug formulators accept premium positioning for qualified supply security.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade procurement where 12-16 week analytical validation timelines necessitate forward coverage, while just-in-time liquid delivery serves automated boiler dosing systems. Manufacturing gravity centers on China, Germany, and the United States for integrated production; India and Switzerland anchor pharmaceutical-grade finishing. Feedstock supply draws from natural gas-derived ethylene and ammonia streams, sodium cyanide or fermentation-derived ethylenediamine routes, and formaldehyde condensation chemistry. Single-source vulnerability concentrates in Chinese industrial-grade liquid output controlling sixty percent of global volume. Distribution runs through direct channel relationships with power generation facilities and pharmaceutical compounders, supplemented by drum and bag logistics for mid-scale industrial and agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green synthesis route maturation represents a technological inflection that will displace cyanide-based Strecker chemistry and reshape competitive positioning across certification tiers. This disruption compresses capital efficiency advantages for legacy producers while opening qualification pathways for enzymatic-catalysis specialists.
For Market Incumbents: Consolidate backward integration into fermentation-derived ethylenediamine feedstocks to neutralize Chinese petrochemical route cost advantages and secure pharmaceutical-grade certification scarcity. Lock in long-term offtake agreements with Indian CDSCO-aligned exporters before analytical validation timelines extend supplier lists. Capacity addition in Yangtze River Delta pharmaceutical-grade fermentation facilities offers defensive positioning against European green chemistry mandates. For New Entrants and Emerging Players: Anchor in biodegradable alternative formulation services for German metal finishing and Nordic paper pulp bleaching facilities facing REACH-driven substitution deadlines. Target US generic injectable producers consolidating qualified supplier lists around USP-NF compliance. White-space exists in blockchain-anchored certificate-of-analysis verification systems for Indian export corridors serving FDA pre-approval inspection requirements. For Investors and Strategic Acquirers: ECHA's updated environmental persistence assessment reshapes the acquisition landscape toward fermentation-capable pharmaceutical-grade assets with active USP-NF qualification. Long-term viability favors producers with enzymatic catalysis pilots validated for USP compliance over legacy cyanide-dependent infrastructure. Watch for CDSCO enforcement of data integrity expectations during pre-approval inspections as the signal indicating accelerated ERP upgrade demand across Indian export facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Feedstock | Bayer and Lonza pilot facilities validate enzymatic routes that displace petrochemical ethylene oxide dependence. |
| Pharmaceutical-Grade Certification Investment | USP-NF and EP monograph compliance burdens limit qualified supply for parenteral drug metal sequestration applications. |
| Biodegradable Alternative Formulation Partnership | Stora Enso and UPM pilot GLDA substitution in peroxide stabilization responding to ECHA discharge consent limits. |
| Blockchain-Anchored Traceability System Deployment | European generic drug manufacturers adopt digital twins to satisfy FDA data integrity expectations during inspections. |
| Zero Liquid Discharge Reuse Specification Development | India's Tiruppur textile cluster mandates closed-loop chelating agent recovery creating technical service opportunities. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical formulation, industrial water treatment, and agricultural chelate manufacturing domains. Primary interviews captured plant managers at Shandong and Jiangsu production facilities, procurement leads at European metal finishing operations, technical R&D directors at fermentation pilot facilities, and regulatory affairs specialists navigating REACH Annex XVII compliance. Secondary validation drew from ECHA registration dossiers, FDA food additive regulations, USP-NF monograph updates, customs and trade data for chelating agent flows, and SEC filings from integrated chemical conglomerates. Bottom-up volume builds across grade tiers and end-use segments were cross-checked against top-down market sizing from production capacity assessments.
Across the analysis window, projections reflect segmented modeling across pharmaceutical, industrial, agricultural, and food-grade purity tiers; liquid, powder, granule, and crystal physical formats; and drum, bag, container, and bottle packaging types. CAGRs were derived from regression analysis of historical consumption patterns against regulatory milestone timelines and capacity expansion announcements. Forecast inputs incorporated ethylenediamine feedstock cost trajectories, REACH compliance timeline acceleration scenarios, and CDSCO data integrity enforcement intensity assumptions.
Material uncertainties — ethylenediamine feedstock volatility, REACH biodegradability mandate expansion, Chinese environmental enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about continued pharmaceutical-grade certification scarcity and sustained industrial-grade commoditization pressure. Revision becomes warranted when ECHA environmental persistence assessments trigger broader discharge consent limit tightening beyond German, French, and Dutch pilot jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Malic Acid Market
Chemicals
Menadione Market
Chemicals
Household Insecticides Market
Chemicals
Hexachloroethane Market
Chemicals
Formalin Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Bakers Ammonia Market
Chemicals
Global Amines Market
Chemicals
Brazil Methanol Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
US Methanol Market
Chemicals
Global Construction Chemical Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Glycerol Carbonate Market
Chemicals
Allyl Alcohol Market