
 Cumene Hydroperoxide Market | 2026-2036
Cumene Hydroperoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Cumene Hydroperoxide Market Outlook
Aftermarket catalyst regeneration revenue is fragmenting as producers internalize spent peroxide recovery. Dow Chemical Company sustains integrated cumene-to-phenol operations across Gulf Coast complexes. BASF SE anchors European supply through Ludwigshafen-based continuous process units. Arkema S.A. differentiates via specialty organic peroxide derivatives downstream of cumene hydroperoxide.
Cumene hydroperoxide is an organic peroxide intermediate produced through liquid-phase air oxidation of cumene, typically containing 80-90% active peroxide content and functioning as the primary precursor in the Hock process for co-producing phenol and acetone. The continuous process technology segment commands the dominant share of installed capacity due to superior thermal safety profiles and higher throughput economics. Pharmaceutical manufacturing applications represent the fastest-growing demand channel as active pharmaceutical ingredient producers adopt peroxide-mediated oxidation routes. Batch process installations occupy niche positions in custom synthesis and small-volume specialty chemical production where formula flexibility outweighs unit cost.
The EPA regulates cumene hydroperoxide under TSCA Section 8(a) reporting requirements, while OSHA mandates Process Safety Management compliance for facilities handling threshold quantities of this highly reactive organic peroxide. REACH restrictions on aromatic solvent emissions in Europe are redirecting investment toward closed-loop oxidation systems with vapor recovery. Stakeholders must monitor how China's MEE enforcement of dual carbon goals reshapes cumene oxidation energy intensity standards and cross-border feedstock trade flows.
Market Dynamics
China's dual carbon enforcement is compressing energy intensity allowances for cumene oxidation, forcing producers to absorb carbon accounting costs or relocate capacity to jurisdictions with looser MEE oversight.
Growth Catalysts
- REACH solvent emission caps:ECHA's tightening aromatic solvent limits are redirecting European investment toward closed-loop oxidation systems with vapor recovery infrastructure.
- Pharmaceutical oxidation demand:Active pharmaceutical ingredient producers are adopting peroxide-mediated synthetic routes for high-value intermediates.
- Phenol-acetone capacity expansion:Domestic Hock process additions in China are absorbing regional cumene hydroperoxide output at scale.
Market Restraints
- Cumene feedstock volatility:Benzene-propylene cost spreads compress margins for non-integrated producers lacking captive cumene supply.
- Thermal hazard classification:OSHA Process Safety Management mandates impose threshold quantity restrictions on storage and handling infrastructure.
- Acetone oversupply drag:Co-product acetone gluts in Asian markets are depressing phenol-acetone economics and feedstock pull-through.
Strategic Opportunities
- Specialty organic peroxide derivatives:Downstream functionalization into polymerization initiators and curing agents commands price premiums over commodity phenol-acetone routes.
- Closed-loop oxidation retrofits:Vapor recovery and energy integration upgrades qualify for EU Green Deal transition financing.
- India pharmaceutical chemical synthesis:CDSCO-aligned API producers represent underpenetrated demand for GMP-grade peroxide intermediates.
Industry Challenges
- Organic peroxide safety engineering expertise:Thermal stability modeling and runaway reaction prevention require specialized chemical engineering talent pools concentrated at legacy producers.
- Continuous process validation timelines:FDA and EMA quality certifications for pharmaceutical-grade output extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cumene Hydroperoxide Market |
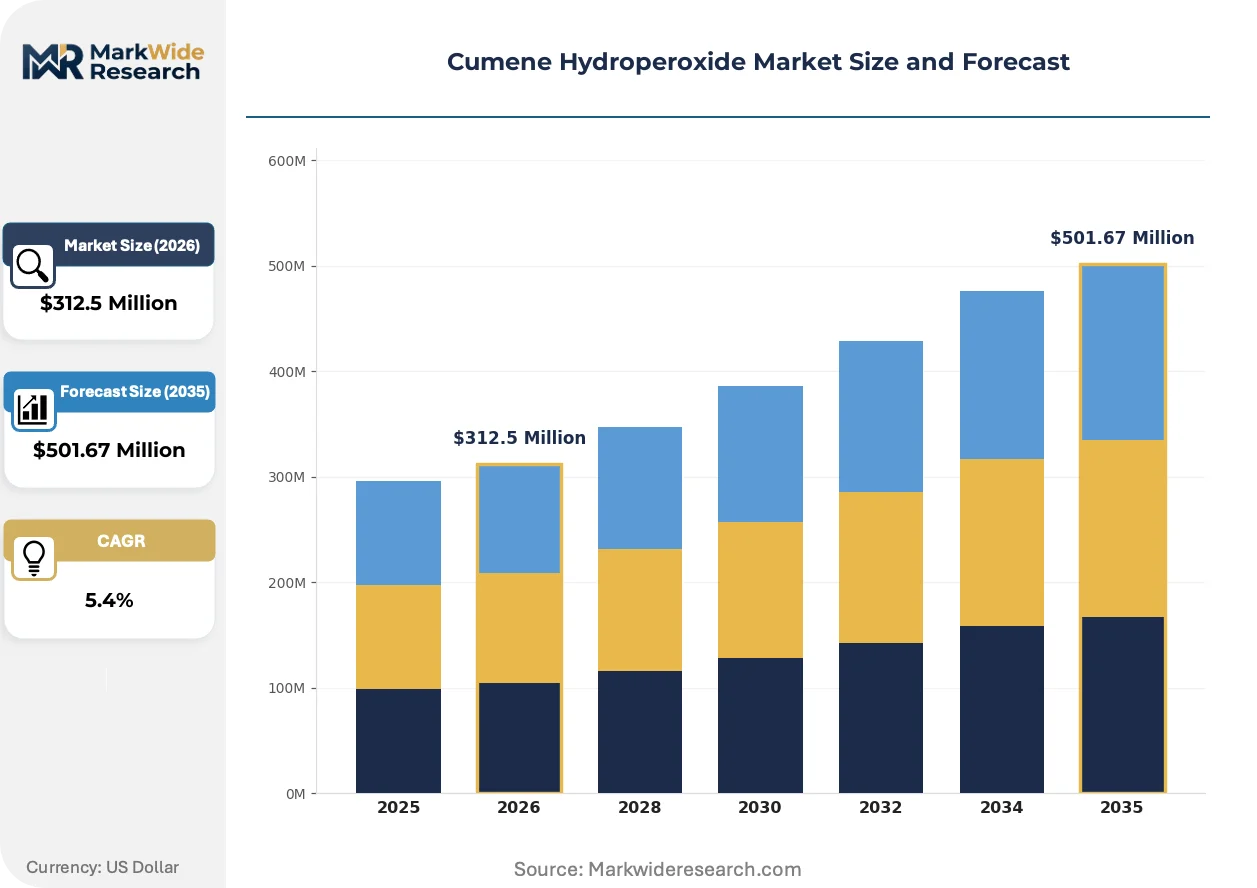
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cumene Hydroperoxide, Phenol, Acetone, Alkyl Aromatics Application: Polymer Synthesis, Chemical Processing, Pharmaceutical Manufacturing, Water Treatment End User: Plastic Manufacturers, Chemical Companies, Pharmaceutical Firms, Textile Producers Technology: Batch Process, Continuous Process, Catalytic Process, Thermal Process |
| Companies Covered | Cepsa, Dow Chemical Company, AdvanSix Inc., ExxonMobil Chemical Company, Eastman Chemical Company, Arkema S.A., Chevron Phillips Chemical Company, INEOS Group Holdings S.A., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cumene Hydroperoxide Market Strategic Shifts
Process control architectures and regulatory disclosure frameworks are reshaping how cumene hydroperoxide capacity gets built, operated, and certified across geographies.
Advanced process control systems with real-time thermal monitoring are digitizing safety management for highly reactive organic peroxide operations. Pharmaceutical and fine chemical producers are adopting these platforms fastest. The technology is digitizing compliance documentation and compressing incident response latency.
EPA's TSCA Section 8(a) reporting expansion is tightening substance-level transparency for organic peroxide intermediates. Facilities must now disclose production volumes and exposure pathways annually. Custom synthesis operators face disproportionate compliance burdens relative to integrated phenol-acetone majors.
Specification-grade procurement is consolidating buyer power among pharmaceutical and electronics chemical distributors. Long-term offtake contracts with embedded quality audits are displacing spot market transactions. This pattern concentrates most visibly in German and Swiss chemical trading hubs serving EU pharmaceutical manufacturing.
Cumene Hydroperoxide Market Segmentation
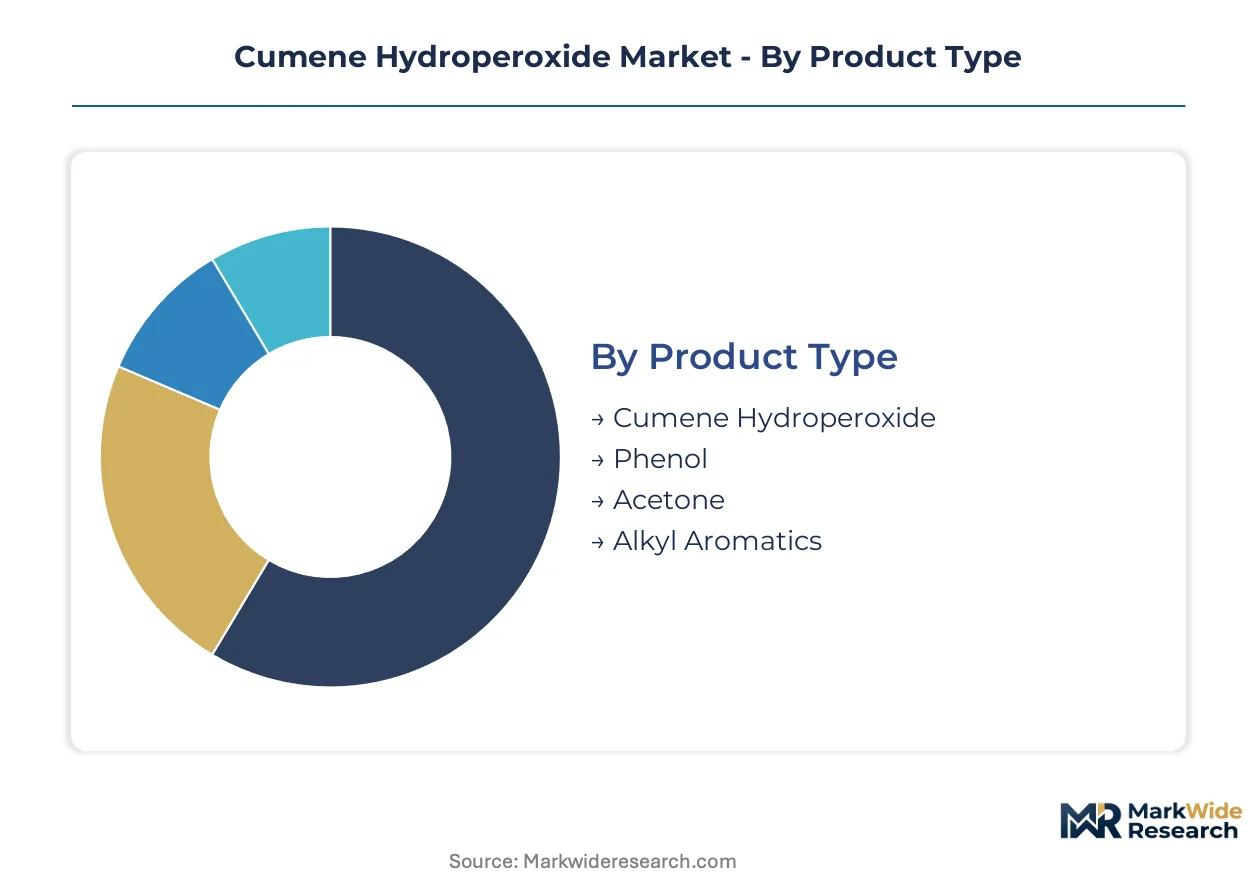
Cumene hydroperoxide market segmentation reveals divergent margin profiles and capital intensity across production modalities. Technology choice and application purity requirements create distinct competitive arenas with asymmetric entry barriers.
Product Type:
Inventory velocity varies dramatically: cumene hydroperoxide turns weekly as phenol-acetone feedstock, while alkyl aromatics sit for months in specialty chemical channels.
- Cumene Hydroperoxide:The 80-90% active peroxide intermediate serves as the primary oxidation feedstock for Hock process installations. Chinese phenol-acetone capacity expansions are absorbing regional output volumes, tightening spot availability for non-integrated buyers.
- Phenol:Co-product from cumene hydroperoxide cleavage commands the largest revenue share in phenol-acetone economics. Bisphenol-A producers in the US Gulf Coast and German chemical clusters anchor steady offtake.
- Acetone:Secondary co-product facing oversupply pressure in Asian markets, compressing integrated process economics.
- Alkyl Aromatics:Downstream derivatives for specialty solvent applications with elongated sales cycles and specification-driven procurement.
Cumene hydroperoxide anchors the volume base while phenol gains share at the steepest rate through bisphenol-A capacity additions.
Application:
Customer switching costs stratify sharply: pharmaceutical manufacturers lock in multi-year qualification cycles while water treatment buyers rotate suppliers quarterly on price.
- Polymer Synthesis:Plastic manufacturers demand higher-purity intermediates for polycarbonate and epoxy resin production. REACH solvent emission caps are redirecting European investment toward closed-loop oxidation systems with vapor recovery.
- Pharmaceutical Manufacturing:Active pharmaceutical ingredient producers adopt peroxide-mediated oxidation routes for high-value intermediates. FDA and EMA quality certifications extend commercialization cycles by 18-24 months.
- Chemical Processing:Intermediate demand from fine chemical and agrochemical synthesis with moderate purity requirements.
- Water Treatment:Oxidant applications with price-elastic demand and minimal specification barriers.
Polymer synthesis anchors the volume base while pharmaceutical manufacturing climbs the fastest as API producers diversify oxidation chemistry.
End User:
Procurement sophistication divides the customer base: pharmaceutical firms mandate embedded quality audits while textile producers transact on spot indices.
- Plastic Manufacturers:Integrated phenol-acetone consumers and standalone polymer compounders with divergent purity requirements. Dow Chemical Company sustains captive supply across Gulf Coast complexes.
- Pharmaceutical Firms:CDSCO-aligned API producers in India represent underpenetrated demand for GMP-grade peroxide intermediates.
- Chemical Companies:Diversified intermediates demand from agrochemical and fine chemical synthesis.
- Textile Producers:Bleaching and finishing applications with commodity-grade specifications and volatile order patterns.
Plastic manufacturers anchor the volume base while pharmaceutical firms expand most quickly through peroxide-mediated synthetic route adoption.
Technology:
Capital deployment timelines stretch from 6 months for batch retrofits to 4 years for continuous process greenfield validation.
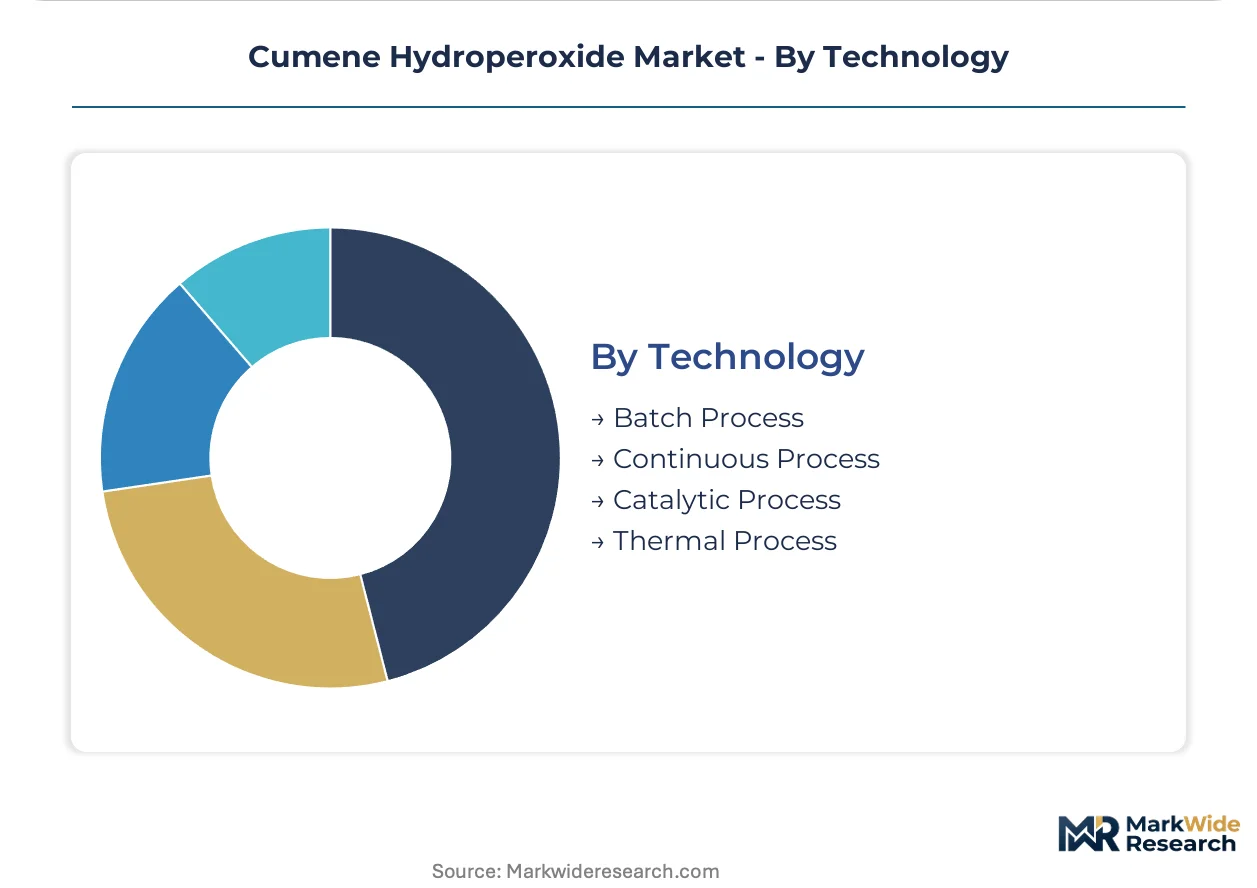
- Continuous Process:Dominates installed capacity with superior thermal safety profiles and higher throughput economics. OSHA Process Safety Management mandates favor this modality for threshold quantity handling.
- Batch Process:Occupies niche positions in custom synthesis and small-volume specialty chemical production where formula flexibility outweighs unit cost. Advanced process control systems with real-time thermal monitoring are digitizing safety management fastest here.
- Catalytic Process:Emerging efficiency improvements in oxidation selectivity with extended pilot validation timelines.
- Thermal Process:Legacy installations facing energy intensity compression under China's MEE dual carbon enforcement.
Continuous process anchors the volume base while catalytic process gains share at the steepest rate through selectivity improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China absorb cumene hydroperoxide volumes at scale with minimal price elasticity, while European specialty chemical purchasers negotiate specification premiums. Indian pharmaceutical producers represent the most price-sensitive demand channel, rotating suppliers on quarterly contract cycles.
United States
Gulf Coast phenol-acetone complexes anchor integrated demand for cumene hydroperoxide as bisphenol-A capacity expands. EPA TSCA Section 8(a) reporting mandates tighten substance-level transparency for organic peroxide intermediates. Dow Chemical Company sustains captive supply chains across Texas and Louisiana installations with closed-loop oxidation infrastructure.
China
Domestic Hock process additions absorb regional cumene hydroperoxide output as phenol-acetone capacity scales. MEE dual carbon enforcement compresses energy intensity allowances for cumene oxidation, forcing carbon accounting cost absorption. Yangtze River Delta chemical clusters retrofit vapor recovery systems to meet tightening emission benchmarks.
Germany
Ludwigshafen-based continuous process units anchor European cumene hydroperoxide supply for polymer synthesis applications. ECHA REACH aromatic solvent emission caps redirect investment toward closed-loop oxidation with vapor recovery infrastructure. BASF SE maintains integrated cumene-to-phenol operations serving bisphenol-A producers across German chemical clusters.
India
CDSCO-aligned API producers adopt peroxide-mediated oxidation routes for high-value pharmaceutical intermediates. Central Drugs Standard Control Organization quality certifications extend commercialization cycles for GMP-grade peroxide suppliers. Maharashtra and Gujarat pharmaceutical manufacturing corridors represent underpenetrated demand for specification-grade cumene hydroperoxide.
Japan
Specialty organic peroxide derivative demand from electronics chemical producers commands price premiums over commodity routes. METI chemical safety standards impose rigorous thermal stability documentation for organic peroxide handling. Kansai and Chubu industrial regions concentrate custom synthesis operations serving semiconductor materials supply chains.
Cumene Hydroperoxide Market Competitive Environment
Capability concentration sits with integrated petrochemical majors possessing captive cumene supply and Hock process expertise; scale advantage sits with regional phenol-acetone specialists leveraging proximity to derivative demand. The market structures around three archetypes: vertically integrated oil-to-chemicals conglomerates, standalone phenol-acetone operators, and specialty organic peroxide derivative producers. Dominant competitive moves include backward integration into cumene feedstock and capacity expansion co-located with bisphenol-A downstream.
Within the integrated petrochemical tier, Dow Chemical Company and BASF SE exemplify scale-driven positioning through Gulf Coast and Ludwigshafen manufacturing footprints. Arkema S.A. occupies the specialty derivative archetype, translating cumene hydroperoxide into higher-margin polymerization initiators and curing agents. Cepsa represents the regional phenol-acetone specialist model with Mediterranean basin supply concentration. Chevron Phillips Chemical Company and INEOS Group Holdings S.A. anchor mid-scale positions through Texas and European corridor assets.
| Leading Market Players |
|---|
| Cepsa |
| Dow Chemical Company |
| AdvanSix Inc. |
| ExxonMobil Chemical Company |
| Eastman Chemical Company |
| Arkema S.A. |
| Chevron Phillips Chemical Company |
| INEOS Group Holdings S.A. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Chinese cumene oxidation capacity concentration anchors feedstock pricing power, while margin pools concentrate with pharmaceutical-grade producers commanding specification premiums downstream. Carbon accounting costs under MEE dual carbon enforcement are compressing energy-intensive process economics and redistributing profitability toward closed-loop retrofit operators.
Pricing Analysis
Aftermarket catalyst regeneration revenue fragments as producers internalize spent peroxide recovery, eroding third-party service margins. Contract-based long-term offtake dominates integrated phenol-acetone procurement, while spot transactions persist for non-captive buyers. Price differentiation hinges on pharmaceutical certification tier and captive cumene supply status. Cost compression in commodity phenol-acetone channels intensifies as acetone oversupply depresses co-product economics. Pharmaceutical firms exhibit lowest price sensitivity due to multi-year qualification lock-ins, while water treatment buyers rotate suppliers quarterly on oxidant cost.
Supply Chain Analysis
Toll manufacturers and custom synthesis operators in Germany, India, and Japan hold contract-manufacturing capacity for GMP-grade peroxide intermediates. The supply chain draws from benzene and propylene feedstocks, with cumene supply concentrated among integrated petrochemical complexes. Single-source vulnerability runs through Chinese phenol-acetone capacity additions absorbing regional cumene hydroperoxide output. Distribution runs through chemical trading hubs serving pharmaceutical and electronics chemical channels, with specification-grade procurement consolidating buyer power among German and Swiss distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal stability modeling and runaway reaction prevention expertise sits in scarce supply, concentrated at legacy producers with decades of organic peroxide safety engineering. This capability gap creates defensive moats for incumbents while raising entry barriers for new operators lacking specialized chemical engineering talent pools.
For Market Incumbents: Pre-empt specialty organic peroxide derivative expansion before pharmaceutical oxidation demand consolidates around qualified suppliers. Backward integration into cumene feedstock secures margin capture against benzene-propylene volatility. Capacity additions co-located with bisphenol-A downstream in the US Gulf Coast reinforce integrated positioning. FDA and EMA certification investments extend qualification timelines that emerging competitors cannot shortcut. For New Entrants and Emerging Players: CDSCO-aligned API producers in Maharashtra and Gujarat pharmaceutical manufacturing corridors represent the most penetrable entry point for GMP-grade peroxide intermediates. Closed-loop oxidation retrofits with vapor recovery infrastructure qualify for EU Green Deal transition financing and unlock European polymer synthesis demand. A go-to-market angle anchored to carbon-accounting compliance services differentiates against commodity phenol-acetone incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward specialty organic peroxide derivative producers with pharmaceutical certification pipelines and captive R&D capabilities. Long-term viability across the analysis window favors operators with thermal safety engineering depth and regulatory validation track records. The signal to watch is MEE enforcement intensity reshaping Chinese cumene oxidation energy intensity standards and cross-border feedstock trade flows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cumene Feedstock | Captive benzene-propylene supply secures margin capture against feedstock volatility for Dow and BASF. |
| Closed-loop Oxidation Retrofit | Vapor recovery upgrades qualify for EU Green Deal financing and meet ECHA REACH aromatic solvent caps. |
| Pharmaceutical-grade Certification Investment | FDA and EMA quality certifications extend commercialization cycles but lock in multi-year API producer contracts. |
| Specialty Organic Peroxide Derivative Expansion | Downstream functionalization into polymerization initiators commands price premiums over commodity phenol-acetone routes. |
| Long-term Supply Agreement with Bisphenol-A Producers | Embedded offtake contracts with polycarbonate manufacturers anchor volume visibility for integrated phenol-acetone operators. |
Study Parameters
Operator-level perspectives from plant managers, procurement leads at downstream polymer manufacturers, distribution channel partners, and technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings for listed chemical producers. Bottom-up capacity and demand modeling triangulated against top-down macro chemical consumption trends.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation modeled by grade tier, end-use industry, and regional production hub. CAGRs derived from production capacity announcements, regulatory filing timelines, and derivative demand elasticity coefficients. Forecast inputs incorporated MEE dual carbon enforcement trajectories and pharmaceutical oxidation route adoption curves.
Macroeconomic conditions sit as an overlay; deviation in benzene-propylene cost spreads, acetone market clearing prices, or carbon credit valuations would shift the trajectory. Quarterly review of Chinese phenol-acetone capacity utilization rates and ECHA REACH implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Muriatic Acid Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Flooring Chemicals Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Paint Stripper Market
Chemicals
Potassium Iodide Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Allyl Chloride Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Piroctone Olamine Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Aircraft Cleaning Chemicals Market