
 Chemical As a Service Market | 2026-2036
Chemical As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical As a Service Market Intelligence
Buyer concentration in automotive and electronics manufacturing is restructuring procurement relationships across the chemical services value chain. BASF SE anchors its position through integrated supply chain control over coating and adhesive formulations delivered under long-term service contracts. Ecolab Inc. differentiates via water-chemistry expertise bundled with on-site technical service teams. Diversey Holdings Ltd. specializes in hygiene and cleaning chemical programs for institutional and industrial clients.
Chemical As a Service denotes a commercial model where chemical ownership remains with the supplier, who charges customers based on functional output—cleaned parts, coated surfaces, or bonded components—rather than volume of chemical consumed. This model typically specifies performance parameters such as surface preparation quality, coating thickness uniformity, or cleaning efficacy rates measured against ISO or ASTM standards. Coatings and adhesives represent mature, high-margin service categories where formulation complexity sustains supplier leverage, while surfactant-based cleaning services in textile treatment and personal care applications demonstrate faster growth due to sustainability-driven reformulation demands. Subscription-based and just-in-time delivery models are gaining traction as manufacturers seek to transfer inventory risk and regulatory compliance burden to chemical service providers.
EPA hazardous waste regulations and OSHA process safety standards in the United States impose strict cradle-to-grave liability on chemical users, directly incentivizing outsourced chemical management. REACH registration requirements and the EU Green Deal's chemical sustainability targets in Europe similarly push manufacturers toward service relationships that transfer regulatory compliance to specialized suppliers. Stakeholders must monitor how evolving extended producer responsibility frameworks and carbon border adjustments reshape the cost structure of chemical ownership versus service-based alternatives.
Market Dynamics
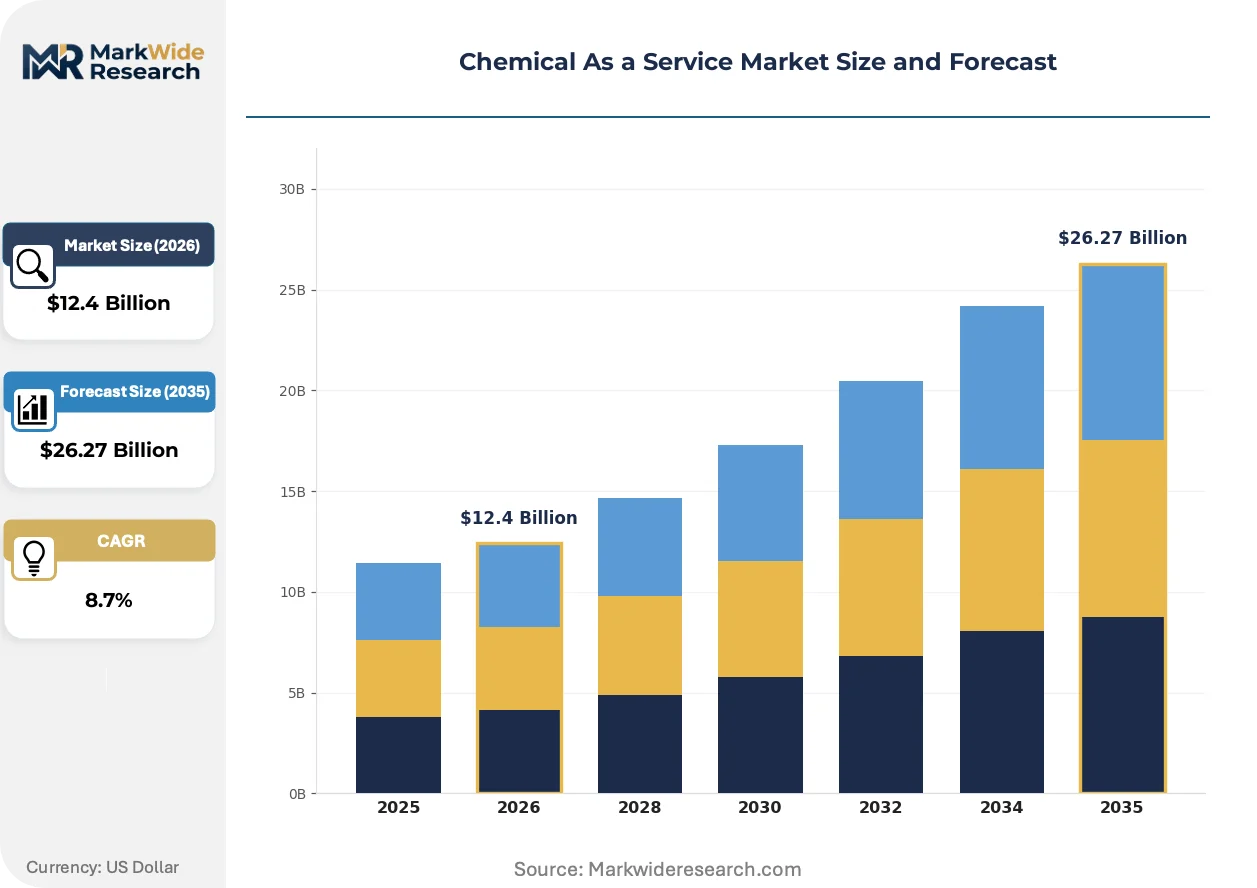
Manufacturers are transferring chemical ownership risk to specialized service providers as EPA cradle-to-grave liability rules and REACH compliance costs render in-house chemical management economically unsustainable. This structural shift from product sales to functional-performance contracts is restructuring supplier-customer power dynamics across industrial chemical value chains.
Growth Catalysts
- REACH registration burdens:European manufacturers face escalating compliance costs for chemical substance registration, driving adoption of service models where suppliers retain regulatory liability.
- Automotive lightweighting:Bonding and coating service contracts for aluminum and composite assembly are displacing traditional mechanical fastening in vehicle manufacturing.
- China:Industrial cluster concentration in the Yangtze River Delta and Pearl River Delta creates scale economies for centralized chemical delivery and waste recovery systems.
Market Restraints
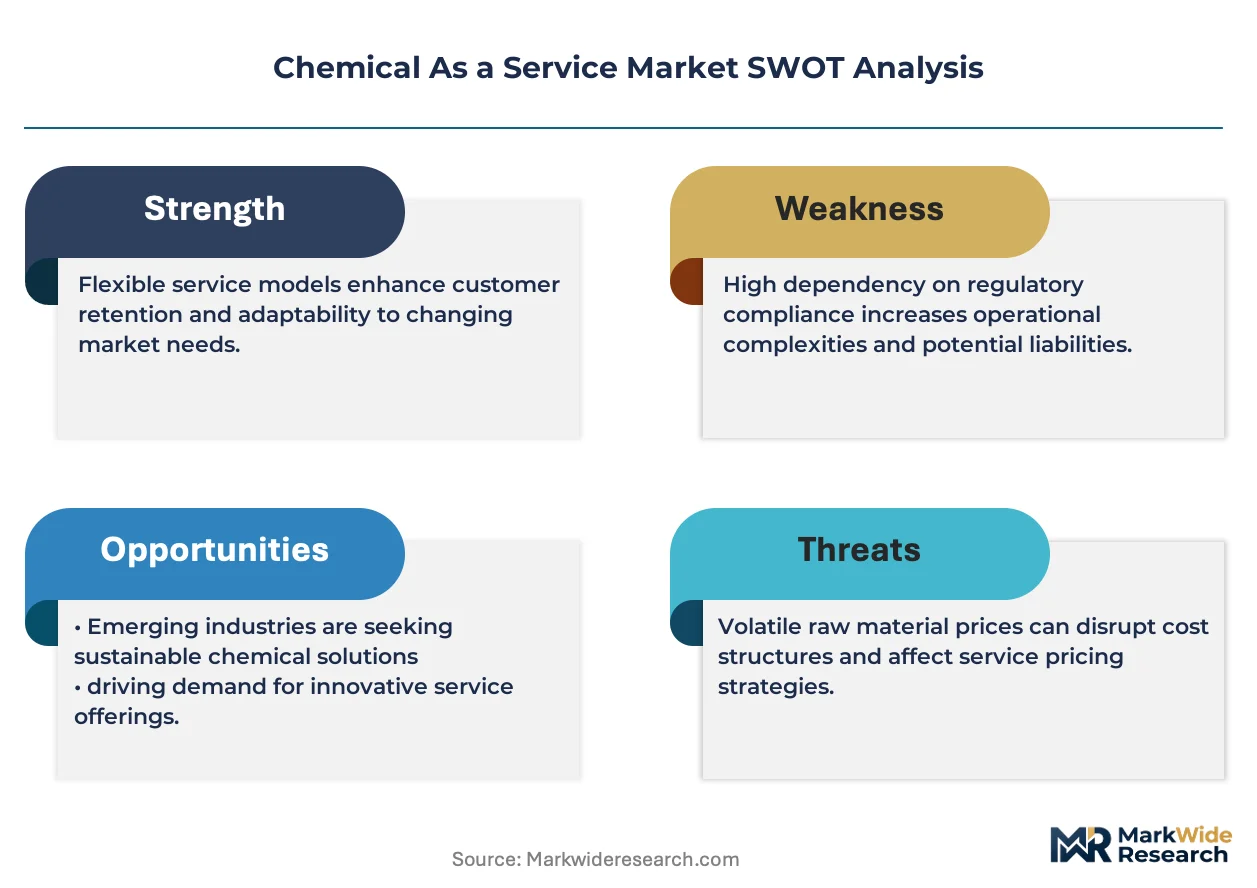
- Petrochemical feedstock volatility:Crude oil and natural gas price swings compress service provider margins on fixed-price performance contracts.
- Specialized formulation expertise:Concentration of advanced coating and adhesive chemistry knowledge among a limited supplier base creates supply risk for critical manufacturing inputs.
- Legacy equipment incompatibility:Existing process lines designed for conventional chemical application resist retrofitting to closed-loop service delivery systems.
Strategic Opportunities
- India:Manufacturing capacity expansion under the PLI scheme for electronics and automotive sectors creates first-mover advantage for chemical service providers establishing localized technical service teams.
- Carbon border adjustment mechanisms:EU carbon pricing on imports incentivizes European manufacturers to outsource chemical-intensive processes to service providers with verified low-carbon supply chains.
- Digital process monitoring:IoT-enabled dosing and quality control systems are converging with predictive analytics to enable real-time performance optimization in coating and cleaning applications.
Industry Challenges
- Cross-functional technical staffing:Service providers struggle to recruit chemists, process engineers, and regulatory specialists capable of integrating formulation science with on-site manufacturing support.
- ISO 14001 and ISO 45001 certification timelines:Extended audit and documentation requirements delay market entry for regional service providers seeking multinational manufacturing contracts.
- Enterprise system integration:Chemical service platforms must connect with customer ERP and MES systems, creating implementation friction and data security complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical As a Service Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Sealants, Surfactants End User: Manufacturing, Construction, Automotive, Electronics Application: Textile Treatment, Paints & Coatings, Cleaning Agents, Personal Care Delivery Model: On-Demand, Subscription-based, Bulk Supply, Just-in-Time |
| Companies Covered | Ecolab Inc., BASF SE, Diversey Holdings Ltd., Henkel AG & Co. KGaA, Dow Inc., Safechem Europe GmbH, Quaker Chemical Corporation, Evonik Industries AG, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical As a Service Market Strategic Shifts & Innovations
Digital instrumentation and closed-loop chemistry are transforming how industrial chemicals are delivered, monitored, and recovered. Service providers are embedding sensors and automation into chemical application equipment to enable real-time performance verification and predictive replenishment.
Closed-loop solvent recovery systems are expanding into automotive and aerospace manufacturing operations. These systems capture spent cleaning and degreasing agents for on-site or centralized reprocessing. BMW and Airbus suppliers in Germany are adopting equipment-as-a-service models where machinery vendors retain ownership of recovery units. This arrangement compresses virgin solvent demand while transferring hazardous waste generator status to specialized recovery operators.
The EU Green Deal's chemical sustainability targets and the proposed revision to REACH are forcing reformulation of legacy coating and adhesive portfolios. Manufacturers must demonstrate substitution of substances of very high concern with safer alternatives or face market exclusion. Automotive OEMs in Germany and France are accelerating supplier audits to verify compliance with restricted substance lists, favoring service providers with transparent chemical composition data and certified green chemistry portfolios.
Performance-based contracting is displacing traditional volume-based chemical purchasing in North American metal fabrication and electronics assembly. Buyers now specify functional outcomes—defect rates, throughput speeds, surface preparation grades—rather than chemical quantities. Tier-1 automotive suppliers in Michigan and Ohio are consolidating vendor relationships around full-service chemical management programs that bundle formulation, equipment, technical support, and waste handling under single-source agreements with gain-sharing provisions tied to measurable efficiency improvements.
Chemical As a Service Market Segmentation
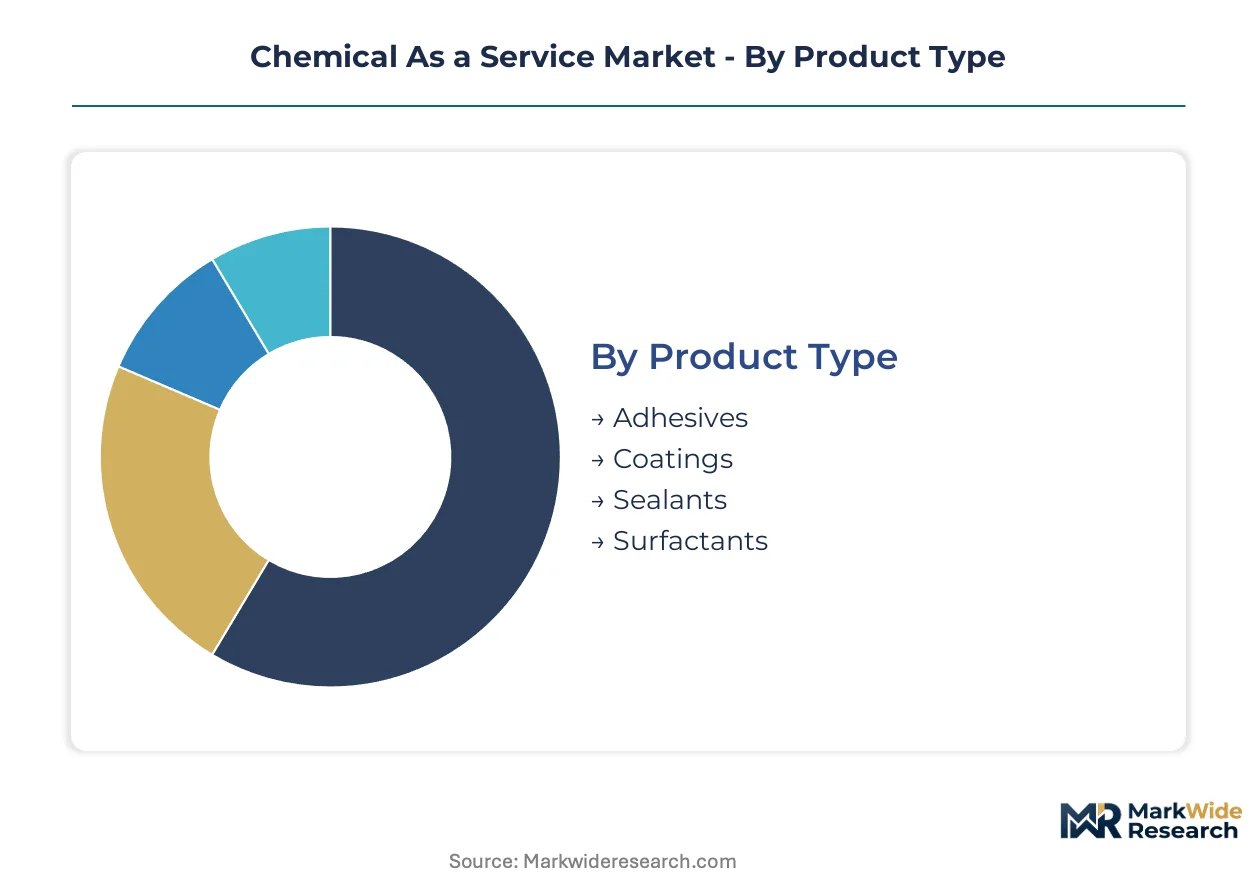
Segmentation in Chemical As a Service reveals how capital intensity, regulatory exposure, and performance requirements reshape supplier economics across distinct service categories. Each dimension exposes different risk-reward profiles for providers managing chemical ownership on behalf of industrial customers.
Product Type:
Capital intensity varies sharply across chemical categories, with formulation complexity and equipment requirements determining upfront service infrastructure investment.
- Adhesives:Structural bonding formulations for automotive and aerospace assembly demand precision dispensing systems and real-time quality monitoring. German automotive OEMs are consolidating supplier relationships around full-service adhesive programs that integrate application equipment with performance guarantees for aluminum-composite joints.
- Coatings:Protective and decorative film-forming systems require spray booths, curing ovens, and thickness verification instrumentation. US metal fabricators in Michigan and Ohio are adopting outcome-based coating contracts where suppliers assume liability for corrosion resistance and appearance specifications.
- Sealants:Elastomeric gap-filling compounds for construction and transportation applications.
- Surfactants:Surface-active agents for cleaning, emulsification, and wetting operations.
Coatings absorb the bulk of installed capacity; surfactants are expanding most quickly.
End User:
Customer type determines contract structure, with asset-heavy manufacturers transferring chemical ownership risk most aggressively.
- Manufacturing:Metal fabrication, machinery assembly, and general industrial operations constitute the core demand base for outsourced chemical management. Chinese industrial clusters in the Yangtze River Delta are deploying centralized chemical delivery systems that consolidate inventory across multiple manufacturing tenants.
- Automotive:Vehicle and component production demands high-performance coatings, adhesives, and cleaning chemistry with zero-defect specifications. European REACH compliance costs are pushing German and French OEMs toward service models where suppliers retain substance registration liability.
- Construction:Building material treatment and on-site application services.
- Electronics:Precision cleaning and conformal coating for semiconductor and circuit board manufacturing.
Manufacturing commands the deepest service penetration; automotive is climbing the fastest.
Application:
Application focus shapes technical service intensity, with process-critical operations demanding embedded on-site support teams.
- Textile Treatment:Dyeing auxiliaries, finishing agents, and pre-treatment chemistry delivered through continuous processing lines. Italian and Portuguese textile manufacturers are adopting pay-per-meter service contracts that align chemical costs with production output.
- Cleaning Agents:Degreasing, precision cleaning, and maintenance chemistry for industrial equipment and manufactured parts. Closed-loop solvent recovery systems in German automotive supply chains are compressing virgin chemical demand while transferring hazardous waste generator status to specialized operators.
- Paints & Coatings:Decorative and protective film application for industrial and consumer products.
- Personal Care:Ingredient supply and formulation services for cosmetic and hygiene product manufacturing.
Cleaning agents dominate current service revenue; textile treatment is gaining share fastest.
Delivery Model:
Delivery configuration determines working capital requirements and inventory risk allocation between supplier and customer.
- Subscription-based:Fixed-fee arrangements covering chemical supply, equipment, technical support, and waste management under multi-year contracts. US EPA cradle-to-grave liability rules make this model attractive for manufacturers seeking to transfer compliance burden.
- Just-in-Time:Synchronized delivery coordinated with production schedules to minimize on-site inventory. Japanese automotive suppliers are implementing kanban-based chemical replenishment systems integrated with customer MES platforms.
- On-Demand:Transactional purchasing for variable or emergency requirements.
- Bulk Supply:Volume-based delivery for stable, high-throughput operations with predictable consumption patterns.
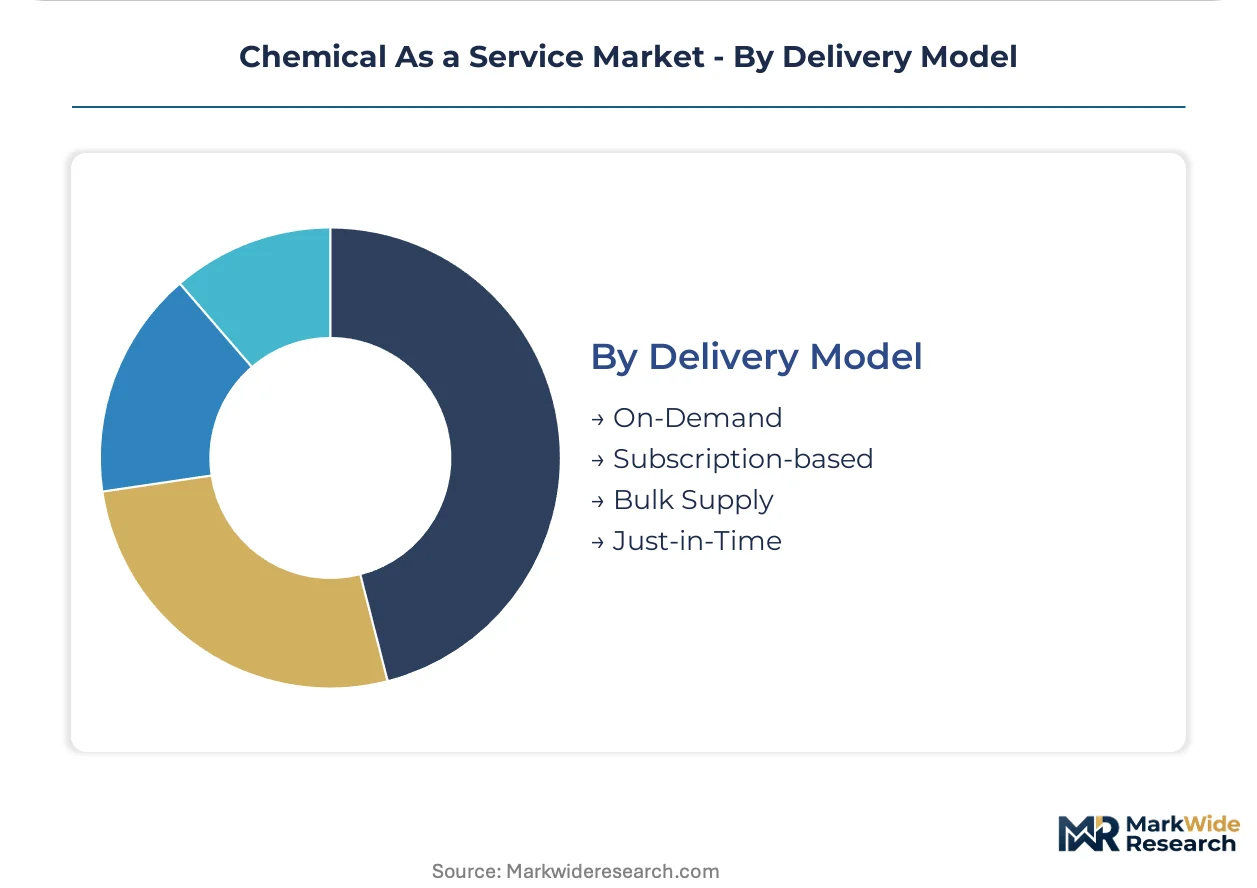
Subscription-based models capture the largest contract value; just-in-time delivery is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial chemical demand concentrates in manufacturing corridors where environmental enforcement and liability frameworks push ownership risk toward specialized service providers. German automotive OEMs, Chinese industrial clusters, and US metal fabricators are transferring chemical inventory and compliance burdens to external operators.
Germany
REACH registration costs and EU Green Deal chemical sustainability targets compel automotive and aerospace manufacturers to outsource substance liability. ECHA enforcement in Frankfurt and Leverkusen chemical corridors accelerates pay-per-use coating and adhesive contracts. Bavarian automotive suppliers around Munich and Ingolstadt are consolidating vendor relationships around full-service chemical management programs with embedded technical teams.
China
Yangtze River Delta and Pearl River Delta industrial clusters generate scale economies for centralized chemical delivery and waste recovery infrastructure. MEE environmental inspections and dual carbon goals pressure manufacturers to reduce on-site hazardous inventory. Suzhou and Wuxi precision manufacturing parks are deploying just-in-time solvent delivery systems with closed-loop recovery units operated by third-party specialists.
United States
EPA cradle-to-grave hazardous waste rules and OSHA process safety standards impose strict liability on chemical users in metal fabrication and electronics assembly. Michigan and Ohio automotive suppliers are adopting subscription-based chemical service contracts that transfer compliance burden and inventory risk. Detroit-area Tier-1 manufacturers consolidate procurement around single-source agreements with gain-sharing provisions tied to efficiency metrics.
India
PLI scheme incentives for electronics and automotive manufacturing create first-mover opportunities for chemical service providers establishing localized technical infrastructure. BIS certification requirements and state-level pollution control board enforcement raise compliance barriers for in-house chemical management. Tamil Nadu and Karnataka industrial corridors near Chennai and Bangalore are attracting outsourced cleaning and coating programs for semiconductor and component assembly operations.
Japan
METI chemical management guidelines and JIS standards for industrial process safety encourage functional-performance contracting over volume-based purchasing. Kanban-based replenishment systems integrated with customer MES platforms dominate automotive supply chains. Nagoya-area Toyota suppliers and Osaka electronics manufacturers are implementing predictive chemical dosing systems with real-time quality verification.
Chemical As a Service Market Key Industry Players
German and Swiss chemical conglomerates anchor the premium service tier; US water-chemistry and hygiene specialists hold differentiated positions in technical service delivery. The market structure is moderately consolidated, with formulation-integrated providers commanding pricing power in coatings and adhesives while regional operators compete on logistics responsiveness. Three archetypes dominate: integrated chemical majors with captive formulation portfolios, water and process specialists bundling equipment with technical service, and regional distributors retrofitting into service models. Competitive dynamics center on long-term contract capture through embedded technical teams and backward integration into waste recovery infrastructure.
Within the integrated chemical major tier, BASF SE and Evonik Industries AG represent formulation-anchored service providers leveraging proprietary coating and adhesive chemistry to secure performance-based contracts. US-based Ecolab Inc. exemplifies the water-chemistry specialist archetype, bundling process equipment with on-site technical support teams. Diversey Holdings Ltd. occupies a position in hygiene and cleaning chemical programs for institutional and industrial clients. These three companies illustrate how geographic origin and historical specialization shape competitive positioning across service model variants.
| Leading Market Players |
|---|
| Ecolab Inc. |
| BASF SE |
| Diversey Holdings Ltd. |
| Henkel AG & Co. KGaA |
| Dow Inc. |
| Safechem Europe GmbH |
| Quaker Chemical Corporation |
| Evonik Industries AG |
| Solvay SA |
| Others |
Cost & Logistics Intelligence
Brent crude and natural gas benchmarks cascade through petrochemical feedstock costs, compressing margins on fixed-price performance contracts while forcing service providers to tier subscription offerings by formulation complexity and technical support intensity.
Pricing Analysis
Volume-based spot purchasing yields to subscription and pay-per-use models as manufacturers transfer inventory risk. Pricing stratifies across premium formulation tiers with embedded technical teams, standard service levels with remote monitoring, and economy bulk supply for stable consumption patterns. Cost compression in surfactant-based cleaning services intensifies due to sustainability-driven reformulation demands. Automotive OEMs exhibit lowest price sensitivity given zero-defect specifications and regulatory liability transfer, while general metal fabricators remain most price-sensitive and consolidate procurement aggressively.
Supply Chain Analysis
Direct-to-OEM channels handle automotive and electronics manufacturer demand through embedded technical service teams, while regional distributors serve fragmented metal fabrication and construction clients. Feedstock supply concentrates in Germany, China, and the United States where integrated chemical majors control proprietary coating and adhesive formulations. Service provider margins hinge on crude oil and natural gas price volatility, specialized formulation expertise concentration, and backward integration into waste recovery infrastructure. Distribution runs through long-term performance contracts with gain-sharing provisions rather than transactional spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance burdens and EPA cradle-to-grave liability rules are forcing consolidation as smaller regional operators lack capital for certification timelines and embedded technical staffing.
For Market Incumbents: Acquire closed-loop solvent recovery infrastructure to anchor customer retention in automotive and aerospace supply chains. BASF SE and Ecolab Inc. demonstrate how captive formulation portfolios combined with on-site technical teams create switching costs. Defensive moves should prioritize ISO 14001 and ISO 45001 certification acceleration to capture multinational manufacturing contracts before regional competitors close capability gaps. For New Entrants and Emerging Players: Digital-channel routes through IoT-enabled dosing and predictive analytics platforms offer lower-friction entry than asset-heavy formulation ownership. White-space targets concentrate in India's PLI scheme corridors for electronics and automotive assembly, where localized technical service teams remain underdeveloped. A direct go-to-market angle bundles equipment-as-a-service with chemical performance contracts, mirroring BMW and Airbus supplier models in Germany. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with established logistics networks in China's Yangtze River Delta industrial clusters. Long-term viability over a multi-year horizon rests on providers achieving backward integration into waste recovery and regulatory compliance infrastructure. The signal to watch is carbon border adjustment mechanism implementation pace, which would accelerate outsourcing of chemical-intensive processes to verified low-carbon service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waste Recovery | Captures hazardous waste generator status transfer from automotive OEMs under EPA rules. |
| Green Chemistry Portfolio Certification | Aligns with EU Green Deal substitution mandates for substances of very high concern. |
| Long-term Performance Contracting | Locks in Michigan and Ohio Tier-1 suppliers through gain-sharing efficiency provisions. |
| Joint Venture with Equipment Manufacturers | Replicates German equipment-as-a-service models for closed-loop solvent recovery systems. |
| Geographic Expansion into India PLI Corridors | Captures first-mover advantage in Tamil Nadu and Karnataka semiconductor assembly operations. |
Research Approach
Trade publications, chemical industry association reports, and regulatory filings formed the secondary backbone for market sizing and competitive mapping. Primary interviews with chemical service procurement managers at automotive OEMs, plant engineers at metal fabrication facilities, regulatory compliance officers, and technical R&D directors at formulation suppliers validated demand drivers and contract structures. Bottom-up and top-down triangulation cross-checked service revenue estimates against chemical consumption volumes and pricing benchmarks.
Bottom-up modeling built country-level projections from industrial cluster concentration, manufacturing output indices, and regulatory enforcement intensity across the analysis window. Segmentation dimensions included product type by formulation complexity, end-use industry by asset intensity, application by technical service requirements, and delivery model by working capital allocation. CAGRs derived from regression analysis against manufacturing value-added growth and environmental liability cost trends, with petrochemical feedstock price scenarios stress-tested for margin sensitivity.
The model holds under stable regulatory enforcement intensity; deviation in EPA rulemaking timelines or REACH revision implementation would shift service adoption curves. Forecasts reflect assumptions about continued manufacturing outsourcing and carbon border mechanism expansion. Periodic stress-testing of base assumptions against MEE inspection intensity in China and EU Green Deal chemical sustainability target revisions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global E Series Glycol Ether Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Maleic Acid Market
Chemicals
Germany Methanol Market
Chemicals
Tin Chemicals Market
Chemicals
Fireworks Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Aerosol Insecticides Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Myclobutanil Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Acetic Ether Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Global Commodity Chemicals Market