
 Artificial Marble Products Market | 2026-2036
Artificial Marble Products Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Marble Products Market Insights
Resin-infusion automation is reconfiguring slab production economics across the artificial marble value chain. Aristech Surfaces LLC leverages captive acrylic resin supply to control formulation consistency. DuPont anchors its position through deep R&D investment in solid-surface chemistry. Guangdong Legend Stone Co. Ltd dominates regional distribution networks across Southeast Asian construction markets.
Artificial marble comprises engineered stone formed from crushed natural minerals bound with polyester or acrylic resins, typically pressed under vacuum and cured at controlled temperatures to achieve densities exceeding 2,200 kg/m³ for structural surfacing applications. Engineered stone commands the largest volume share among product types due to granite-alternative performance at lower installed cost. The hospitality end-user segment generates premium margin pools as five-star properties specify custom veining and large-format slabs for lobby and bathroom environments.
EPA oversees volatile organic compound emissions from resin manufacturing facilities in the United States, while REACH governs chemical substance registration and hazard communication across European supply chains. China's GB standards mandate formaldehyde release limits for interior building materials, directly affecting cultured marble formulations sold domestically. Stakeholders must track evolving silica-exposure regulations in multiple jurisdictions, as occupational health rules increasingly influence raw-material substitution and factory automation investment priorities.
Market Dynamics
Resin-infusion automation is compressing cycle times and reconfiguring cost structures across artificial marble fabrication, forcing legacy polyester-based producers to retool or cede share to acrylic-optimized competitors.
Growth Catalysts
- REACH crystalline silica thresholds:European Union restrictions on silica content in composite formulations are accelerating substitution toward engineered stone with lower occupational exposure profiles.
- Luxury hospitality specification:Five-star properties in Dubai and Singapore are mandating custom-veined, large-format slabs for lobby and bathroom environments, creating premium margin pools.
- Guangdong fabrication clusters:Concentrated production capacity in China's Guangdong province serves both domestic real estate and export markets with integrated supply chains.
Market Restraints
- Acrylic resin price volatility:Petrochemical feedstock fluctuations directly compress margins for solid-surface manufacturers dependent on methyl methacrylate supply.
- Quartz substitution threat:Engineered quartz surfaces with superior hardness ratings are displacing artificial marble in high-traffic commercial flooring applications.
- EPA VOC enforcement:Stricter volatile organic compound emission controls on resin manufacturing facilities in the United States are raising compliance capital requirements.
Strategic Opportunities
- Healthcare surface specifications:Antimicrobial-integrated solid surfaces are penetrating hospital and clinic environments where infection control protocols favor non-porous materials.
- China GB standard alignment:Domestic producers achieving formaldehyde release compliance under GB standards gain preferential access to government-backed infrastructure projects.
- Digital templating integration:Convergence of CNC fabrication with 3D surface scanning is enabling mass-customization of veining patterns for residential kitchen renovations.
Industry Challenges
- Vacuum-press technician scarcity:Specialized operators capable of managing resin-infusion parameters across variable slab thicknesses command wage premiums that inflate production costs.
- Dual certification timelines:Simultaneous pursuit of CE marking and EPA compliance extends product launch cycles by eight to fourteen months for export-focused manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Marble Products Market |
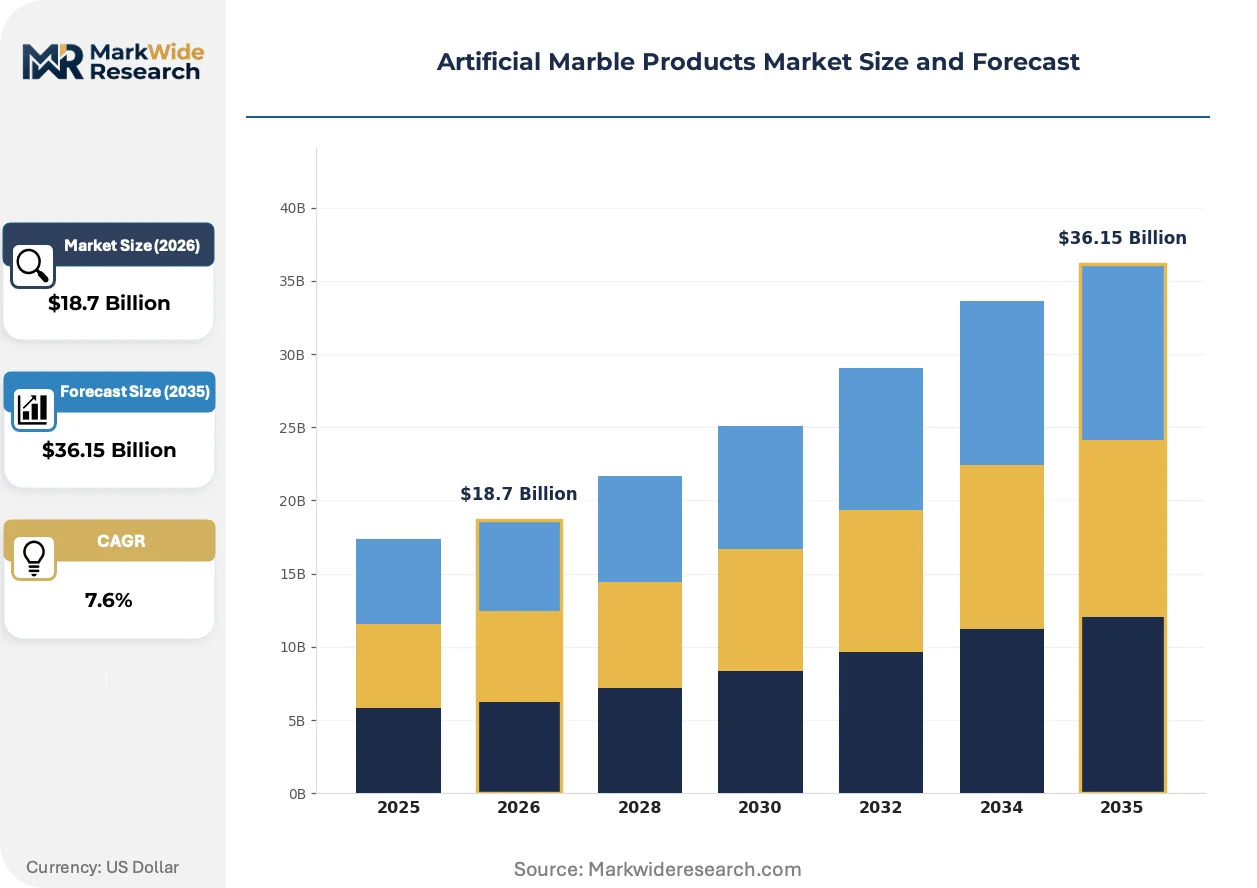
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Surface, Cultured Marble, Engineered Stone, Composite Marble Application: Countertops, Flooring, Wall Cladding, Vanities End User: Residential, Commercial, Hospitality, Industrial Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Aristech Surfaces LLC, LX HAUSYS, DuPont, Lotte Chemical, Hyundai L & C Europe GMBH, MARMIL S.A, Guangdong Legend Stone Co. Ltd, Cupa Group, Hari Stones Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Marble Products Market Trends and Innovations
Digital fabrication and regulatory chemistry are converging to redefine competitive advantage in artificial marble, separating automated, low-silica producers from conventional polyester-dependent operations.
Bio-based resin formulations are hybridizing with conventional acrylic binders to reduce petrochemical dependency while maintaining density specifications above 2,200 kg/m³. Hospitality procurement teams in Singapore and Dubai are piloting these materials for LEED-aligned projects. The hybridizing technology is compressing the cost gap between sustainable and conventional formulations, forcing incumbents to reformulate or lose specification battles.
ECHA's evolving stance on respirable crystalline silica under REACH is mandating reformulation across European supply chains and triggering parallel compliance investments in North American export facilities. Manufacturers are substituting calcium carbonate fillers for quartz aggregates to reduce silica content below occupational exposure thresholds. Solid-surface categories with sub-10% crystalline silica content are capturing specification share in German and French commercial fit-out markets.
Specification decisions are consolidating around large-format slab availability, with architects in Dubai and Singapore mandating single-piece dimensions exceeding 3,000 mm by 1,400 mm for seamless lobby installations. Distributors are shifting inventory risk onto fabricators through just-in-time slab allocation rather than warehouse stocking. This pattern is most visible in China's tier-one cities where developer consolidation favors direct mill relationships over fragmented distributor networks.
Artificial Marble Products Market Segmentation
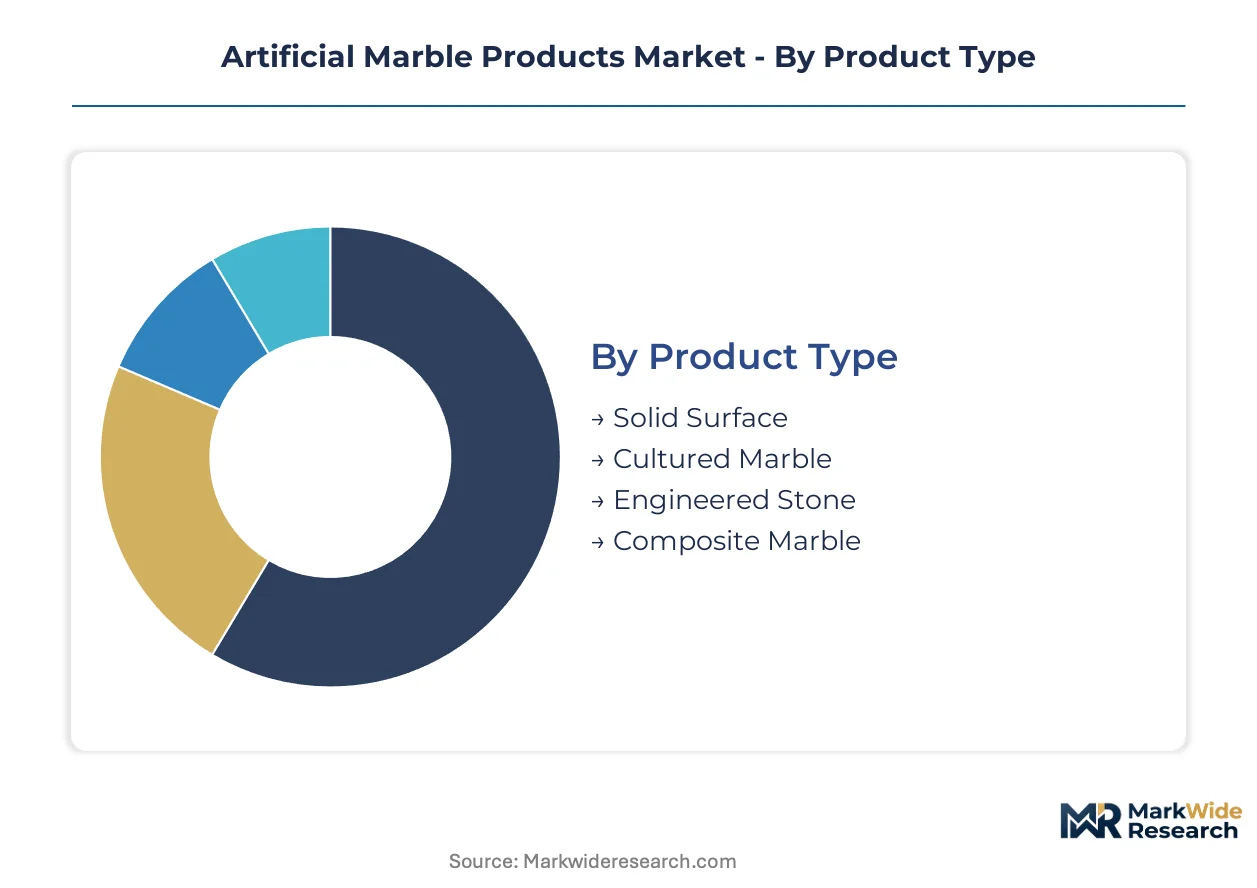
Artificial marble producers configure production lines around distinct material chemistries and cure cycles. Segment-specific tooling investments lock manufacturers into particular margin structures and specification tiers.
Product Type:
Engineered stone cycles through vacuum presses in under 90 minutes, while cultured marble cure times stretch past four hours, creating divergent capital efficiency profiles across the category.
- Solid Surface:Acrylic-resin matrices with aluminum trihydrate fillers achieve seamless thermoformed joints for healthcare and food-service environments. Five-star properties in Singapore specify solid surface for integrated vanity-basin units where bacterial ingress must be eliminated.
- Cultured Marble:Polyester-bound calcium carbonate formulations with gel-coat surface layers dominate budget bathroom renovation segments. Guangdong fabrication clusters ship cultured marble vanity tops to North American home improvement retailers under private-label arrangements.
- Engineered Stone:Vacuum-vibrated quartz aggregates bound with polyester resins achieve Mohs hardness ratings exceeding 7.
- Composite Marble:Hybrid formulations blending natural marble chips with engineered binders occupy mid-tier pricing bands.
Engineered stone dominates installed base. Solid surface is where expansion concentrates.
Application:
Countertop templating demands precision CNC routing, while flooring specifications prioritize abrasion resistance testing, splitting procurement criteria between fabrication skill and material density.
- Countertops:Kitchen and bath surfaces require heat resistance above 180°C and stain impermeability for residential specification. Dubai luxury developments mandate 40mm thickness with custom veining for island installations exceeding three meters in length.
- Flooring:High-traffic commercial environments specify engineered stone with PEI wear ratings above 4 for airport terminals and hotel lobbies. Singapore Changi renovation contracts specify slip-resistant finishes with coefficient of friction above 0.5 wet.
- Wall Cladding:Lightweight honeycomb-backed panels enable vertical installation in elevator cabs and elevator lobbies.
- Vanities:Integrated basin designs with molded drain slopes dominate hospitality procurement.
Countertops anchor volume shipments. Flooring commands the steepest expansion trajectory.
End User:
Hospitality procurement teams consolidate specifications across property portfolios, while residential demand fragments across individual renovation decisions with divergent quality tolerances.
- Residential:Single-family renovation and new construction drive standard slab sizes of 3,000mm by 1,400mm for kitchen island fabrication. China's tier-one cities exhibit preference for light-veined patterns mimicking Calacatta marble in luxury apartment fit-outs.
- Hospitality:Five-star chains in Dubai and Singapore enforce brand-standard material libraries with pre-approved veining patterns and slab dimensions. Marriott and Hilton procurement specifications mandate antimicrobial surface integration for guest bathroom environments.
- Commercial:Office and retail fit-outs prioritize rapid installation and durability under lease-term horizons.
- Industrial:Laboratory and cleanroom applications specify chemical resistance and electrostatic dissipation.
Residential absorbs the highest absolute volume. Hospitality generates premium margin capture.
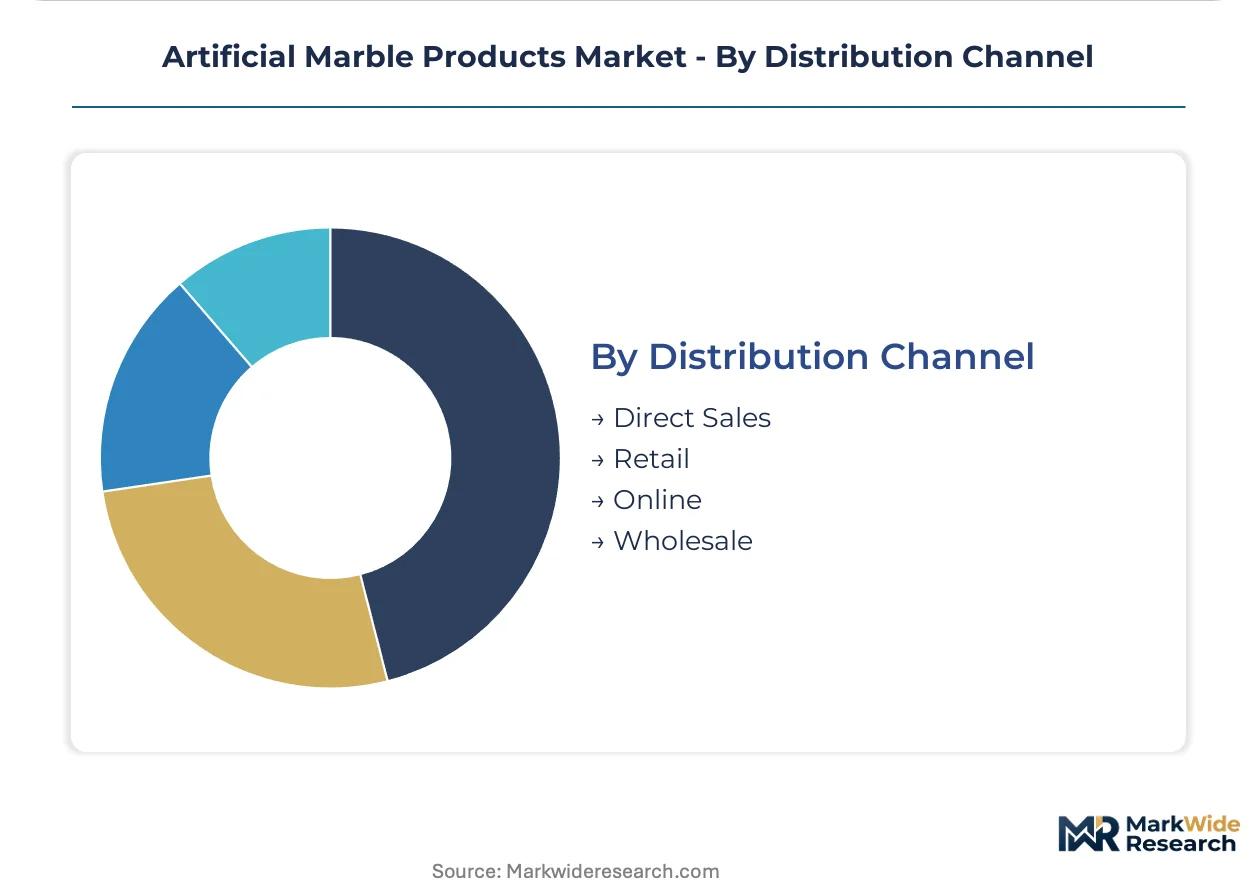
Distribution Channel:
Direct mill relationships concentrate among project developers with recurring volume, while retail fragmentation forces inventory carrying costs onto independent fabricators.
- Direct Sales:Large-scale developers and hospitality groups negotiate slab allocation directly with Guangdong and Fujian manufacturers. Dubai-based Aldar and Emaar procure through direct contracts specifying custom veining and just-in-time delivery to construction sites.
- Wholesale:Regional distributors maintain slab yards in Texas, Florida, and California to serve fabrication shops with 48-hour availability. Inventory risk shifts from mills to distributors under consignment arrangements.
- Retail:Home improvement chains stock limited dimensional ranges for consumer selection.
- Online:Digital templating services with remote measurement and CNC programming expand reach.
Direct sales lock in the largest project volumes. Wholesale channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong province exports engineered stone slabs to Dubai and Singapore hospitality developers under direct mill contracts. Italian fabricators ship composite marble to German commercial fit-out contractors navigating REACH silica thresholds. Turkish producers route polyester-bound cultured marble to North American home improvement retailers.
United States
Residential kitchen renovation drives countertop demand across Florida, Texas, and California metro corridors. EPA VOC enforcement on resin manufacturing facilities in Ohio and Georgia raises compliance capital requirements for domestic producers. Fabrication clusters in Atlanta and Dallas-Fort Worth serve regional distribution networks with 48-hour slab availability.
China
Guangdong province hosts concentrated vacuum-press capacity serving domestic real estate and Southeast Asian export markets. GB standards mandate formaldehyde release limits for interior building materials, directly affecting cultured marble formulations sold domestically. Foshan and Yunfu fabrication clusters integrate resin supply with CNC templating services for tier-one city developers.
Germany
Commercial office and healthcare fit-out specifications favor low-silica engineered stone for LEED-aligned projects. ECHA's evolving REACH stance on respirable crystalline silica mandates reformulation across supply chains. Fabricators in North Rhine-Westphalia distribute solid-surface slabs to French and Benelux contractors.
United Arab Emirates
Dubai's five-star hospitality chains specify custom-veined, large-format slabs exceeding 3,000 mm by 1,400 mm for seamless lobby installations. MOHAP building material regulations align with international fire-safety and chemical-emission standards. Aldar and Emaar procure directly from Guangdong mills specifying just-in-time delivery to construction sites.
Singapore
Marriott and Hilton procurement specifications mandate antimicrobial surface integration for guest bathroom environments. The Building and Construction Authority enforces strict material performance standards for commercial interiors. Fabricators serve Changi renovation contracts specifying slip-resistant finishes with coefficient of friction above 0.5 wet.
Artificial Marble Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Acrylic-resin formulators with captive chemistry supply face off against polyester-dependent fabricators purchasing feedstock on spot markets. Three archetypes dominate: vertically integrated resin-to-slab producers, regional fabrication specialists with CNC templating capabilities, and private-label suppliers serving home improvement retailers. Competitive moves concentrate on backward integration into resin supply and geographic expansion through direct mill relationships with Dubai and Singapore developers.
Among Asia-Pacific-based producers, Guangdong Legend Stone Co. Ltd exemplifies the regional fabrication archetype with concentrated distribution networks across Southeast Asian construction markets. DuPont occupies a position representing deep R&D investment in solid-surface chemistry among multinational material science portfolios. Aristech Surfaces LLC anchors the captive-resin-supply archetype, leveraging in-house acrylic production to control formulation consistency.
| Leading Market Players |
|---|
| Aristech Surfaces LLC |
| LX HAUSYS |
| DuPont |
| Lotte Chemical |
| Hyundai L & C Europe GMBH |
| MARMIL S.A |
| Guangdong Legend Stone Co. Ltd |
| Cupa Group |
| Hari Stones Ltd |
| Others |
Pricing and Supply Chain Analysis
Foshan and Yunfu fabrication clusters in Guangdong province anchor global engineered stone capacity, translating concentrated vacuum-press infrastructure into asymmetric pricing power over North American and Middle Eastern importers. REACH silica thresholds and EPA VOC enforcement cascade through resin formulation costs, compressing margins for polyester-dependent producers while acrylic-optimized competitors capture specification premiums in Dubai and Singapore hospitality procurement.
Pricing Analysis
Prior-generation polyester-bound cultured marble trades at commodity-grade levels, current-generation engineered stone commands mid-tier positioning through Mohs hardness certification, and next-generation bio-resin hybrid formulations are compressing sustainable-premium spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by silica content, with sub-10% crystalline silica slabs capturing LEED-aligned project premiums in German commercial fit-outs. Cost compression in standard-grade engineered stone is intensifying because Guangdong mills are absorbing methyl methacrylate volatility through captive resin supply. Residential renovation buyers exhibit highest price sensitivity, while hospitality procurement teams prioritize large-format availability over unit cost.
Supply Chain Analysis
Extended payment terms from Guangdong mills to Southeast Asian distributors are financing inventory risk transfer, with consignment arrangements now covering 60-day slab allocation cycles. Supply concentrates in China, Turkey, and Italy, with vacuum-press capacity clustering in Guangdong and composite marble finishing distributed across North Rhine-Westphalia and Istanbul. Raw material dependencies rest on petrochemical-derived methyl methacrylate, aluminum trihydrate fillers, and calcium carbonate aggregates. Single-source vulnerability runs through acrylic resin supply chains tethered to Korean and Japanese petrochemical feedstock. Distribution runs through direct mill contracts for Dubai developers and wholesale slab yards serving Texas and Florida fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with REACH and GB standard compliance creating switching costs that lock hospitality specifiers into pre-qualified supplier libraries.
For Market Incumbents: Build captive-resin supply moats through backward integration into methyl methacrylate production or long-term offtake agreements with Korean petrochemical suppliers. DuPont and Aristech Surfaces LLC exemplify this archetype, controlling formulation consistency while polyester-dependent competitors face margin compression from spot-market resin volatility. Defend specification share by accelerating low-silica reformulation ahead of ECHA's evolving REACH stance, converting regulatory compliance into procurement lock-in with Marriott and Hilton brand-standard libraries. For New Entrants and Emerging Players: Establish a beachhead in antimicrobial-integrated solid surface for healthcare environments, where infection control protocols favor non-porous materials and incumbent penetration remains limited outside Singapore and Dubai hospitality. Target German and French commercial fit-out contractors navigating silica thresholds with sub-10% engineered stone formulations. Pursue digital templating integration as go-to-market angle, converging CNC fabrication with 3D surface scanning to enable mass-customization without legacy vacuum-press technician dependencies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated resin-to-slab producers with direct mill relationships to Dubai and Singapore developers, generating contracted slab allocation visibility across multi-year hospitality build-out cycles. Acquisition target archetype: regional fabrication specialists with CNC templating capabilities and GB standard certification serving China's tier-one city infrastructure pipeline. Signal to watch is consolidation among Guangdong fabrication clusters as formaldehyde compliance mandates raise capital barriers for smaller cultured marble producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Supply | Aristech Surfaces LLC controls formulation consistency through captive methyl methacrylate production. |
| Low-Silica Reformulation Investment | REACH compliance below 10% crystalline silica captures specification share in German LEED projects. |
| Digital Templating Capability Acquisition | CNC-3D scanning convergence enables mass-customization for residential kitchen renovation demand. |
| Direct Mill Contract Expansion | Aldar and Emaar procurement in Dubai favors just-in-time slab allocation over distributor inventory. |
| Antimicrobial Surface Certification | Marriott and Hilton specifications mandate integrated infection control for guest bathroom environments. |
Research Methodology
A standing panel of vacuum-press plant managers, hospitality procurement directors, resin formulation chemists, and CNC fabrication shop owners provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from customs trade data, SEC 10-K filings of listed material science companies, ECHA REACH substance registrations, and China GB standard compliance databases. Bottom-up triangulation across fabrication cluster output estimates converged with top-down demand modeling from construction permit data in Dubai, Singapore, and China's tier-one cities.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled include product chemistry (acrylic vs polyester resin matrices), application (countertop, flooring, wall cladding), end-user vertical (residential, hospitality, commercial), and regional regulatory cluster (REACH-aligned, EPA-enforced, GB-standard). CAGRs were derived from elasticity-adjusted demand curves incorporating hospitality construction pipelines and renovation cycle timing. Industry-specific inputs included methyl methacrylate price indices and silica-exposure regulatory trajectory assumptions.
Sensitivities concentrate around ECHA crystalline silica threshold revisions, Guangdong real estate construction permit volatility, and petrochemical feedstock price shocks. Forecasts reflect documented assumptions on regulatory enforcement timing and hospitality development completion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Lithium Tantalate Crystal Market
Advanced Materials
Borophene Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Corundum Market