
 Long-Range Ordered Porous Carbon (LOPC) Market | 2026-2036
Long-Range Ordered Porous Carbon (LOPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Range Ordered Porous Carbon (LOPC) Market Foresight
A capital-intensity divergence between players is bifurcating the competitive landscape. Kuraray Co. Ltd. leverages its synthetic polymer heritage to sustain precision carbonization capabilities that smaller rivals cannot replicate. BASF SE anchors European supply through integrated precursor chemistry, while Entegris Inc. specializes in contamination-controlled formats for semiconductor cleanrooms.
Long-Range Ordered Porous Carbon denotes carbonaceous materials with periodic, tunable pore architectures—typically 0.5–50 nm in dimension—engineered via soft-templating or hard-templating routes for molecular sieving, ion transport, or catalytic support. Mesoporous Carbon dominates current energy storage procurement due to optimal electrolyte wetting and ionic conductivity in supercapacitor electrodes. Hybrid Carbon represents the fastest-expanding category as manufacturers blend micropore capacitance with mesopore rate capability for automotive fast-charge applications.
Japan's METI funds ordered carbon development under next-generation battery roadmaps, while the EU's REACH framework governs precursor chemical registration and the F-Gas Regulation shapes carbon manufacturing energy profiles. South Korea's MFDS and KATS standards influence medical and industrial filtration grades exported from the region. Stakeholders must track how precursor supply constraints and evolving battery cell form factors reshape procurement specifications before committing capacity.
Market Dynamics
Precursor chemical scarcity is compressing production timelines across the Long-Range Ordered Porous Carbon sector, forcing manufacturers to secure synthetic polymer feedstocks before committing to capacity expansions for lithium-sulfur battery anodes.
Growth Catalysts
- China's dual carbon goals:Tightened MEE emissions standards are accelerating domestic pilot production of precision carbon structures for energy storage applications.
- Supercapacitor electrode demand:Mesoporous Carbon procurement is intensifying from Korean cathode material hubs seeking optimal electrolyte wetting properties.
- METI funding mechanisms:Japan's next-generation battery roadmaps are directing public capital toward ordered carbon development for automotive fast-charge systems.
Market Restraints
- Phenolic resin cost volatility:Synthetic polymer precursor prices fluctuate with petrochemical feedstock markets, squeezing margin predictability for carbonization specialists.
- East Asian supply concentration:Critical soft-templating expertise clusters around South Korean and Japanese production bases, creating geographic vulnerability for European and North American buyers.
- Hard-templating throughput limits:Silica template removal steps constrain batch sizes, preventing scale economies that soft-templating competitors achieve.
Strategic Opportunities
- EU F-Gas Regulation compliance:Carbon manufacturing energy profiles face tightening constraints, rewarding early adopters of electrified pyrolysis who can document reduced fluorinated gas footprints.
- Semiconductor cleanroom formats:Contamination-controlled LOPC grades for wafer processing represent an underpenetrated premium segment outside traditional energy storage.
- Hybrid Carbon formulation patents:Blending micropore capacitance with mesopore rate capability opens automotive fast-charge white space distinct from established supercapacitor supply contracts.
Industry Challenges
- Carbonization engineering talent scarcity:Synthetic polymer heritage expertise resides at a handful of legacy chemical conglomerates, constraining workforce mobility for emerging producers.
- REACH precursor registration timelines:ECHA chemical dossier preparation for novel templating agents delays European commercialization by 18-36 months versus Asian regulatory pathways.
- Legacy supercapacitor specification lock-in:Existing electrode designs optimized for conventional activated carbon resist requalification for ordered porous architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Range Ordered Porous Carbon (LOPC) Market |
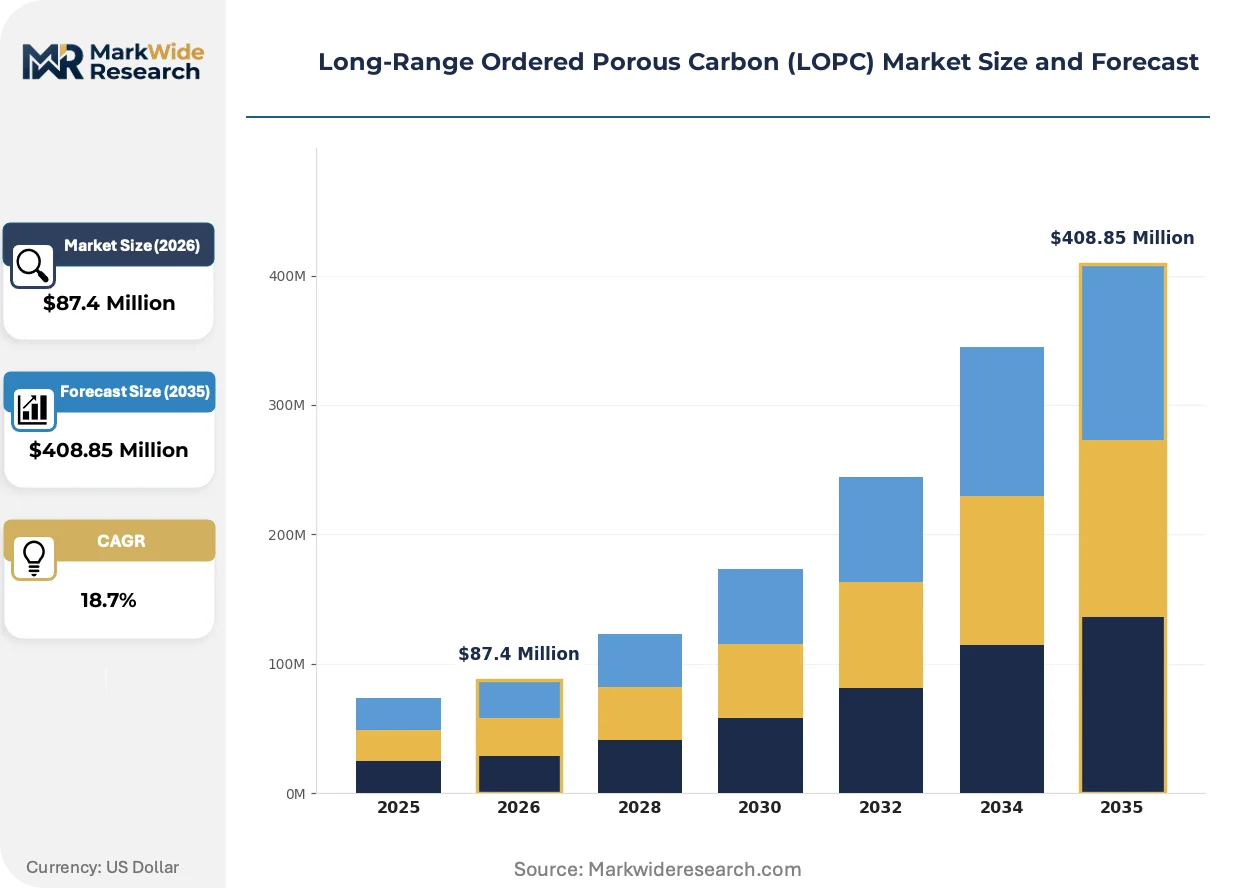
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $408.85 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microporous Carbon, Mesoporous Carbon, Macroporous Carbon, Hybrid Carbon Application: Energy Storage, Filtration, Catalysis, Adsorption End User: Aerospace, Automotive, Electronics, Industrial Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Kuraray Co. Ltd., Calgon Carbon Corporation, Cabot Corporation, Entegris Inc., Norit Activated Carbon, Mitsubishi Chemical Corporation, Sumitomo Chemical Co. Ltd., Nippon Carbon, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Range Ordered Porous Carbon (LOPC) Market Shifts & Advancements
Ordered carbon architectures are undergoing functional specialization as end-users demand pore geometries matched to specific ion transport regimes rather than generic high-surface-area materials.
Hard-templating synthesis is miniaturizing. This precision manufacturing route engineers periodic pore architectures between 0.5–50 nm for molecular sieving applications. Japanese capacitor makers are adopting sub-micron template techniques for next-generation electrodes. The technology is miniaturizing production equipment footprints while enabling previously unattainable pore size distributions.
REACH framework amendments are tightening precursor chemical registration requirements for carbon manufacturing inputs. ECHA scrutiny of phenolic resin derivatives is extending dossier preparation timelines. European supercapacitor electrode producers are responding by qualifying Asian-sourced pre-registered polymer feedstocks to maintain supply continuity.
Buyer concentration around South Korean cathode material hubs is consolidating procurement leverage. Tier-one battery manufacturers are bypassing distributors to negotiate direct templating-agent supply agreements. This channel compression is most visible in the Gwangju-Daejeon industrial corridor where three buyers account for dominant LOPC offtake.
Long-Range Ordered Porous Carbon (LOPC) Market Segmentation
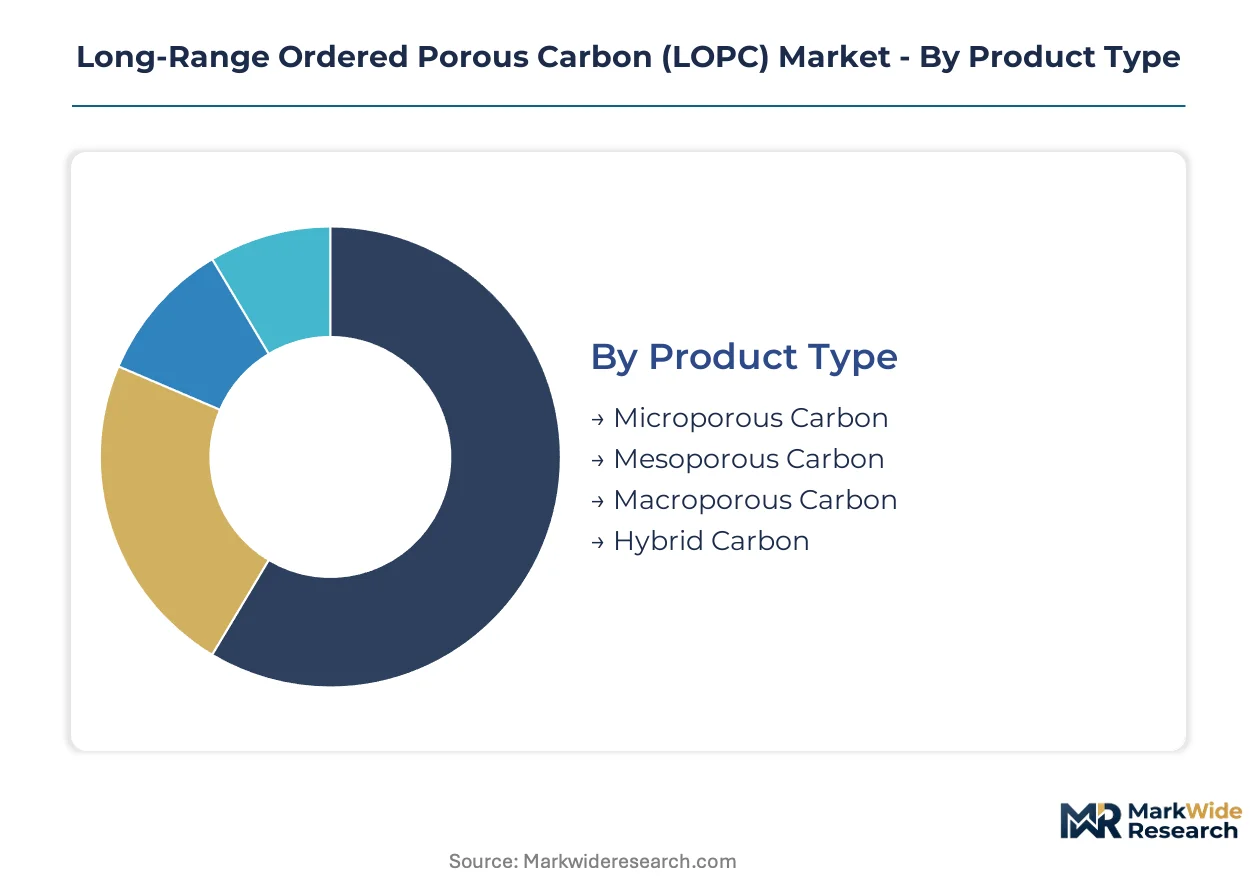
Segmentation in the LOPC market reveals how pore architecture and application specificity determine procurement premiums. Buyers segment suppliers by carbonization precision rather than surface area alone, creating distinct competitive arenas.
Product Type:
Mesoporous Carbon faces intensifying substitution pressure from activated carbon in commodity filtration, while Microporous and Hybrid grades defend premium positions through battery-specific ion transport engineering.
- Mesoporous Carbon:Engineered with 2–50 nm pore channels optimized for electrolyte wetting and rapid ion diffusion. Korean cathode material hubs in Gwangju-Daejeon corridor dominate procurement for supercapacitor electrodes where rate capability trumps energy density.
- Hybrid Carbon:Architectures blend micropore capacitance with mesopore transport pathways for automotive fast-charge applications. Japanese capacitor makers under METI-funded roadmaps are qualifying these formulations for next-generation electrodes requiring sub-minute charge cycles.
- Microporous Carbon:Sub-2 nm pore structures engineered for molecular sieving and gas adsorption. Industrial gas separation plants specify these grades for CO2 capture retrofits.
- Macroporous Carbon:Greater than 50 nm pore channels serving as catalytic supports for bulk chemical processes. Petrochemical catalyst manufacturers specify these for heavy hydrocarbon conversion.
Mesoporous Carbon anchors the volume base while Hybrid Carbon gains share at the steepest rate.
Application:
Application segmentation tracks how end-use performance requirements reshape carbon architecture specifications, with energy storage commanding the most stringent pore size distribution tolerances.
- Energy Storage:Lithium-sulfur battery anodes and supercapacitor electrodes demand periodic pore architectures with sub-nanometer precision. South Korean battery manufacturers bypass distributors to negotiate direct templating-agent supply agreements.
- Filtration:Medical and industrial membrane applications require contamination-controlled formats. MFDS and KATS standards in South Korea influence filtration grade specifications exported regionally.
- Catalysis:Heterogeneous catalyst supports leverage ordered pore channels for reactant accessibility. Petrochemical producers specify macroporous architectures for heavy feedstock conversion.
- Adsorption:Gas separation and purification applications exploit micropore size selectivity. Industrial CO2 capture retrofits drive procurement of molecular sieving grades.
Energy Storage commands the highest specification premiums while Filtration offers the most stable contract volumes.
End User:
End user segmentation exposes how sector-specific certification requirements fragment procurement channels, with automotive and electronics demanding the most intensive supplier qualification protocols.
- Automotive:Fast-charge battery systems require Hybrid Carbon formulations with validated cycle life. Tier-one EV manufacturers specify pore architectures through direct material agreements rather than distributor channels.
- Electronics:Semiconductor cleanroom formats demand contamination-controlled LOPC grades for wafer processing. Entegris Inc. specializes in formats meeting these stringent particulate specifications.
- Aerospace:Lightweight structural composites and thermal management applications specify ordered carbon for satellite and aircraft systems. Defense procurement drives qualification timelines.
- Industrial:Bulk chemical processing and environmental remediation consume standardized mesoporous grades. Price sensitivity here exposes suppliers to activated carbon substitution.
Electronics maintains the longest supplier qualification cycles while Industrial generates the highest shipment volumes.
Distribution Channel:
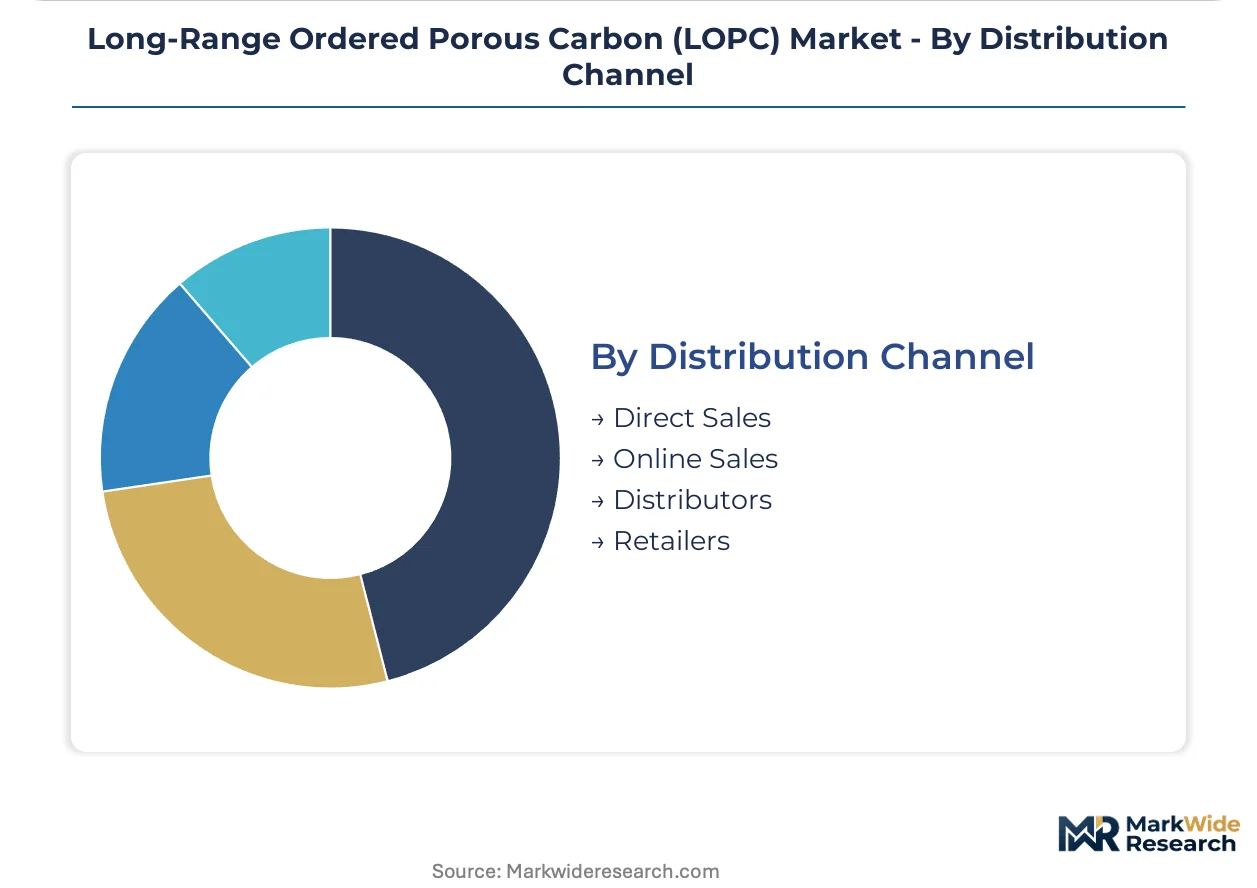
Channel segmentation tracks the compression of intermediaries as battery manufacturers consolidate procurement leverage around production clusters.
- Direct Sales:Tier-one battery and capacitor makers negotiate templating-agent supply agreements directly with carbonization specialists. This channel dominates East Asian procurement around South Korean cathode hubs.
- Distributors:Regional chemical distributors serve mid-scale industrial and filtration customers requiring technical support. European buyers rely on these channels given REACH registration delays for novel precursors.
- Online Sales:Standardized research-grade materials move through specialized chemical marketplaces. Academic and pilot-scale buyers favor this channel for rapid procurement.
- Retailers:Minimal presence in LOPC given technical specification requirements. Limited to commodity activated carbon substitutes in peripheral markets.
Direct Sales captures the steepest growth trajectory while Distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. East Asian battery manufacturers prioritize mesoporous architectures for supercapacitor electrodes, while European industrial buyers emphasize REACH-compliant precursor chains for filtration applications. North American demand concentrates in semiconductor-grade contamination control formats.
China
Domestic lithium-sulfur battery pilot lines in Jiangsu and Fujian provinces drive mesoporous carbon procurement. The Ministry of Ecology and Environment tightened emissions standards for carbonization facilities in 2024. Ningbo and Suzhou industrial clusters host emerging soft-templating capacity serving CATL and BYD supply chains.
Japan
Automotive fast-charge systems from Toyota and Honda require hybrid carbon formulations with sub-minute cycle validation. METI's next-generation battery roadmap directs public funding toward ordered carbon development. Osaka-based capacitor makers are qualifying sub-micron hard-templating techniques for next-generation electrode production.
South Korea
LG Energy Solution and Samsung SDI bypass distributors to negotiate direct templating-agent agreements for cathode material production. MFDS standards influence medical filtration grades exported throughout Asia. The Gwangju-Daejeon corridor concentrates procurement leverage among three dominant buyers.
Germany
BASF anchors European precursor chemistry through integrated phenolic resin supply chains. The EU F-Gas Regulation shapes carbon manufacturing energy profiles, rewarding electrified pyrolysis investments. Ludwigshafen and Leverkusen chemical complexes maintain legacy carbonization expertise for specialty industrial applications.
United States
Entegris specializes in contamination-controlled formats for semiconductor wafer processing in Arizona and Texas fabs. EPA emissions oversight constrains new carbonization facility permitting. The Pacific Northwest hosts pilot-scale hard-templating operations serving aerospace thermal management programs.
Long-Range Ordered Porous Carbon (LOPC) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Long-Range Ordered Porous Carbon sector. Synthetic polymer conglomerates leverage captive precursor supply to defend margin positions against carbonization-only competitors. Three archetypes dominate: diversified chemical majors with backward integration into phenolic resins, precision materials specialists serving semiconductor cleanrooms, and regional carbonization houses dependent on merchant feedstock. Capacity expansion and strategic precursor partnerships constitute the primary competitive vectors as manufacturers secure templating-agent supply before committing to lithium-sulfur battery anode production.
Among Japanese synthetic polymer conglomerates, Kuraray Co. Ltd. and Mitsubishi Chemical Corporation exemplify the integrated leader archetype through their heritage in precision carbonization capabilities. BASF SE occupies a parallel position in Europe, anchoring regional supply through captive precursor chemistry. Entegris Inc. represents the contamination-control specialist tier, serving semiconductor fabrication requirements with formats that command specification premiums distinct from energy storage procurement.
| Leading Market Players |
|---|
| Kuraray Co. Ltd. |
| Calgon Carbon Corporation |
| Cabot Corporation |
| Entegris Inc. |
| Norit Activated Carbon |
| Mitsubishi Chemical Corporation |
| Sumitomo Chemical Co. Ltd. |
| Nippon Carbon |
| BASF SE |
| Others |
Supply & Pricing Matrix
Phenolic resin substitution by pre-registered Asian polymer feedstocks simultaneously relocates procurement leverage toward South Korean cathode hubs and compresses margin buffers for European carbonization specialists facing REACH dossier delays.
Pricing Analysis
After-sales technical service contracts and templating-agent supply agreements drive lifetime value beyond base material transactions. Three-tier pricing structure across semiconductor-grade, battery-grade, and industrial-grade levels separates contamination-controlled formats commanding specification premiums from standardized mesoporous carbon facing activated carbon substitution. Cost compression in industrial filtration tiers intensifies because buyers qualify lower-cost Asian-sourced feedstocks. Battery manufacturers demonstrate the least price sensitivity given direct templating-agent negotiations, while industrial gas separation plants resist specification premiums.
Supply Chain Analysis
Strategic stockpiling of synthetic polymer precursors dominates over just-in-time approaches as phenolic resin volatility forces manufacturers to secure feedstocks before capacity commitments. Supply concentrates in Japan, South Korea, and China, with Osaka-based capacitor makers and Gwangju-Daejeon cathode hubs anchoring procurement. Production draws from phenolic resins, silica templating agents, and electrified pyrolysis equipment. Single-source vulnerability around soft-templating expertise clusters creates geographic concentration risk. Distribution runs through direct sales agreements for tier-one battery makers, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Long-Range Ordered Porous Carbon market represents early-cycle expansion as lithium-sulfur battery pilot lines accelerate procurement of precision carbon anodes beyond established supercapacitor applications.
For Market Incumbents: Fortify synthetic polymer heritage advantages through captive precursor supply agreements that emerging carbonization-only competitors cannot replicate. Secure templating-agent partnerships in Jiangsu and Fujian industrial clusters before Chinese domestic capacity matures. Invest in electrified pyrolysis documentation to capture F-Gas Regulation compliance premiums in European procurement. For New Entrants and Emerging Players: Technical qualification support for hard-templating miniaturization represents an underserved service layer where legacy conglomerates under-invest. Target semiconductor cleanroom formats for wafer processing in Arizona and Texas fabs, where Entegris-style contamination control commands specification premiums unavailable in commoditized energy storage. Pursue joint development agreements with Japanese capacitor makers qualifying sub-micron template techniques. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional carbonization houses dependent on merchant phenolic resin feedstocks and lacking backward integration into precursor chemistry. Five-to-ten year viability hinges on securing templating-agent supply partnerships before lithium-sulfur battery anode specifications crystallize. Watch for cathode material hub consolidation in the Gwangju-Daejeon corridor as inflection indicator for procurement leverage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | BASF's captive phenolic resin supply anchors European margin defense against Asian feedstock competitors. |
| Electrified Pyrolysis Capacity Buildout | Early adopters document reduced fluorinated gas footprints to capture EU F-Gas Regulation compliance premiums. |
| Hard-Templating Miniaturization Investment | Japanese capacitor makers adopt sub-micron template techniques for next-generation electrode pore precision. |
| Direct Templating-Agent Supply Agreements | LG Energy Solution and Samsung SDI bypass distributors to secure mesoporous carbon offtake in Gwangju-Daejeon. |
| Semiconductor Cleanroom Format Certification | Contamination-controlled LOPC grades for Arizona and Texas wafer fabs command specification premiums distinct from battery procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC chemical company filings, and Ministry of Ecology and Environment emissions disclosures across the analysis window. Carbonization plant managers, procurement leads at Korean cathode material hubs, technical R&D directors at Japanese capacitor makers, and semiconductor fab materials engineers provided operational perspective. Bottom-up capacity assessments triangulated against top-down demand modeling from battery roadmap projections.
Segmentation dimensions modeled include pore architecture class, application specificity, end-use certification tier, and regional regulatory cluster. CAGRs derive from supply-demand balance analysis across the projection horizon. Forecast inputs incorporate lithium-sulfur battery pilot line announcements, METI funding allocation trajectories, and REACH precursor registration timeline assumptions.
Forecasts assume regulatory continuity in EU REACH and F-Gas frameworks, China's MEE emissions standards, and South Korea's MFDS filtration specifications; material policy shifts would require re-modeling. Phenolic resin cost volatility, hard-templating throughput constraints, and cathode hub buyer consolidation represent primary revision triggers. Revision becomes warranted when direct templating-agent agreements cross threshold penetration in East Asian procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Transparent Wood Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Buckminsterfullerene Market