
 Global Diamond-Like Carbon (DLC) Market | 2026-2036
Global Diamond-Like Carbon (DLC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diamond-Like Carbon (DLC) Market Foresight
The DLC coating sector is recalibrating around a widening split between premium hydrogenated grades for medical implants and commodity non-hydrogenated films for general industrial tooling. CemeCon leverages its European R&D base to dominate high-purity medical coatings with exacting thickness control. Oerlikon Balzers anchors its position through backward integration into coating equipment and captive supply of process gases across Asian automotive lines. Platit competes on manufacturing scale, operating one of the largest independent PVD coating service networks for cutting tool manufacturers worldwide.
Diamond-like carbon denotes an amorphous carbon material containing sp3-bonded carbon clusters dispersed within an sp2-bonded matrix, typically deposited at thicknesses of 1-3 micrometers with hardness exceeding 20 GPa and friction coefficients below 0.1 against steel. Its primary industrial purpose is to provide wear-resistant, chemically inert surface protection for components subjected to abrasive contact, corrosive media, or repetitive mechanical stress. Hydrogenated DLC films lead the product type landscape due to established biocompatibility protocols for cardiovascular stents and orthopedic implants, while metal-doped variants represent the fastest-growing category as aircraft manufacturers specify titanium-doped coatings for landing gear and actuator pins. Among coating technologies, plasma enhanced CVD commands the margin pool because it enables conformal deposition on complex three-dimensional geometries at temperatures compatible with hardened steel substrates.
FDA 21 CFR Part 820 quality system requirements shape medical device coating validation protocols, while EU MDR and REACH constrain the use of hexavalent chromium pre-treatments that DLC increasingly replaces in automotive and aerospace supply chains. Japan's METI energy efficiency standards for industrial machinery create indirect demand pull for low-friction coatings that reduce parasitic power losses in rotating equipment. Stakeholders must monitor how evolving ISO 18562 biocompatibility testing for breathing gas pathways opens or constrains DLC adoption in respiratory device manufacturing, as this segment could redirect coating development priorities across the supplier base.
Market Dynamics
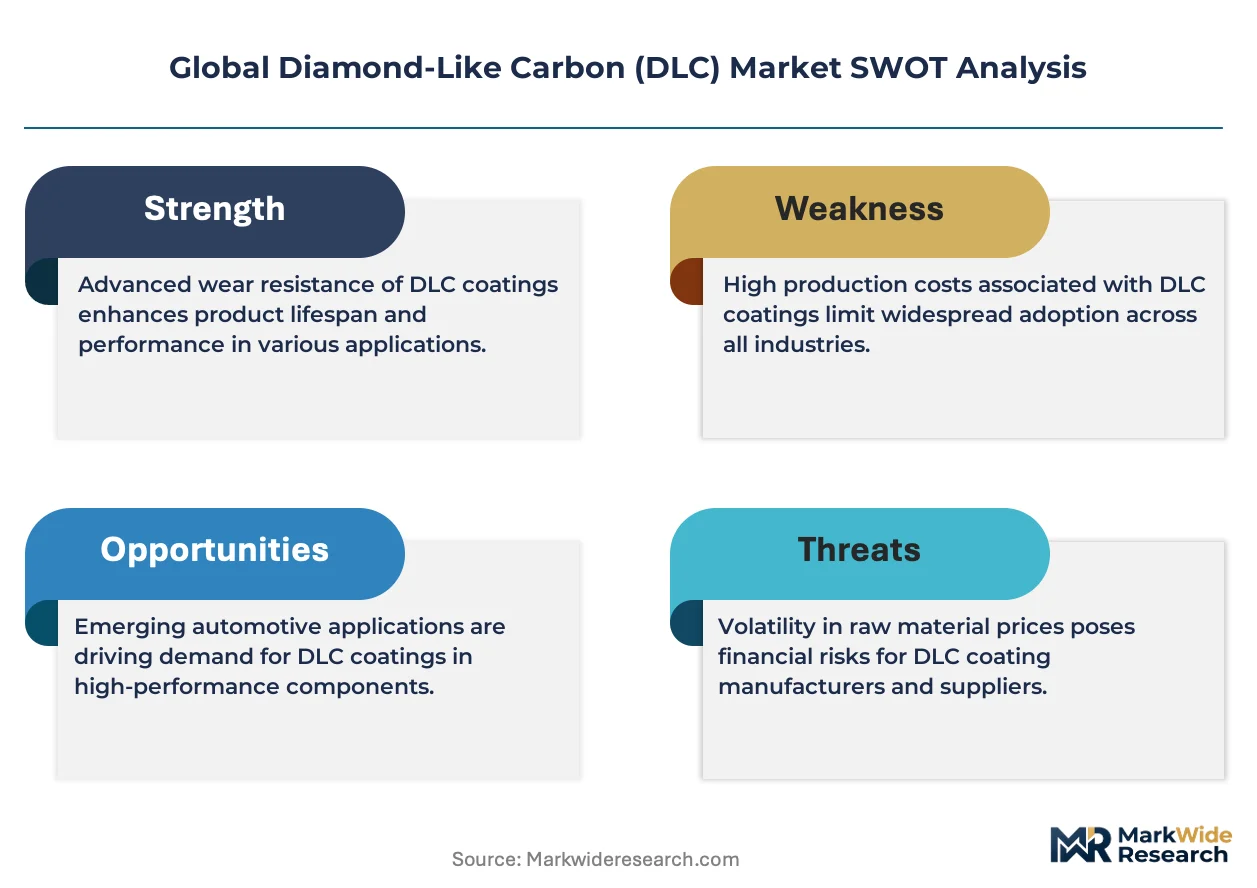
The DLC market is splitting into two distinct supply tiers: hydrogenated films for medical implants command premium validation protocols, while non-hydrogenated coatings for industrial tooling compete on throughput and unit economics.
Growth Catalysts
- EU REACH hexavalent chromium restrictions:Automotive suppliers in Germany and France are accelerating DLC substitution for hard chrome plating on piston rings and fuel injectors to meet surface treatment compliance deadlines.
- Semiconductor fabrication clusters:Tooling manufacturers in Japan and South Korea are expanding PVD coating capacity to service wafer processing equipment requiring sub-micron film uniformity.
- METI energy efficiency mandates:Industrial machinery producers across Japan are specifying low-friction DLC bearings and seals to reduce parasitic power losses in rotating equipment.
Market Restraints
- Acetylene and argon supply volatility:PECVD process gas costs fluctuate with petrochemical feedstock pricing, compressing margins for coating service providers operating at fixed contract rates.
- Equipment vendor concentration:Deposition system manufacturing concentrates among a limited set of European and Japanese suppliers, creating capex queue delays for capacity expansion projects.
- Thermal budget constraints:Plasma-enhanced CVD remains incompatible with aluminum and polymer substrates, excluding DLC from lightweighting applications in consumer electronics housings.
Strategic Opportunities
- Respiratory device biocompatibility:ISO 18562 testing protocols for breathing gas pathways could open new DLC applications in ventilator components and anesthesia equipment.
- Titanium-doped metal variants:Aircraft landing gear and actuator specifications from Boeing and Airbus suppliers are creating specification pull for metal-doped films with enhanced fatigue resistance.
- Direct equipment leasing models:Coating service providers are piloting subscription-based PVD system deployments to capture recurring revenue from mid-tier automotive suppliers.
Industry Challenges
- Thin-film metrology expertise gap:Calibration of nanoindentation and Raman spectroscopy equipment for sp3/sp2 ratio verification requires specialized technicians that coating shops struggle to recruit.
- Multi-site quality system harmonization:FDA 21 CFR Part 820 compliance across geographically distributed coating facilities demands redundant validation documentation and audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diamond-Like Carbon (DLC) Market |
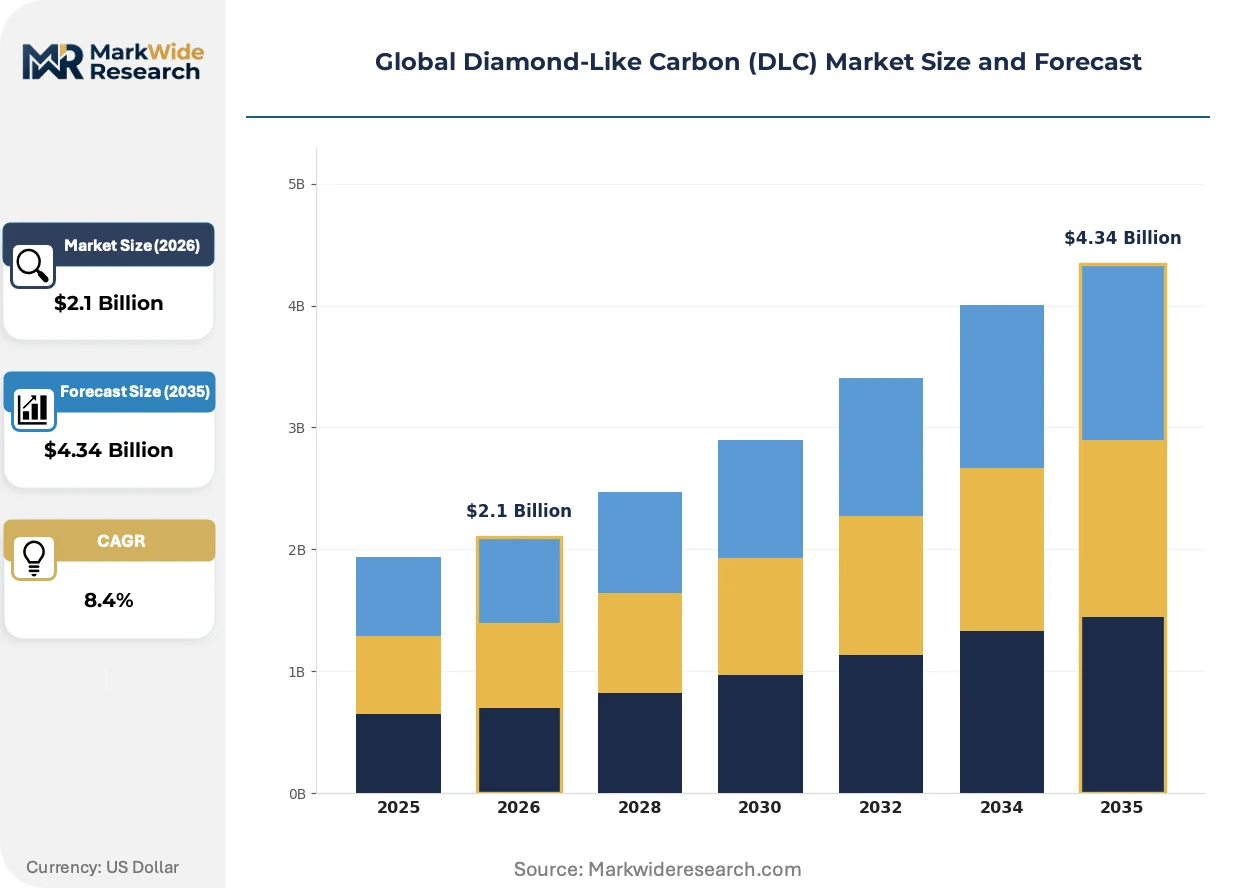
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogenated DLC, Non-Hydrogenated DLC, Fluorinated DLC, Metal-Doped DLC, DLC Nanocomposite Application: Cutting Tools, Automotive Components, Medical Devices, Electronics, Optical Coatings, Aerospace Parts Coating Technology: PVD, CVD, Plasma Enhanced CVD, Sputtering, Arc Evaporation End User Industry: Tool Manufacturing, Semiconductor Fabrication, Medical Equipment, Aircraft Manufacturing, Consumer Electronics |
| Companies Covered | CemeCon, Applied Diamond Coatings LLC, Oerlikon Balzers, Platit, Techmetals, Ionbond, Richter Precision Inc., Kurt J. Lesker Company, Calico Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diamond-Like Carbon (DLC) Market Shifts & Advancements
Process control automation and real-time thickness monitoring are compressing the gap between medical-grade and industrial-grade coating workflows, enabling volume producers to bid on regulated applications.
Multi-layer DLC architectures with gradient sp3 concentration profiles are absorbing thermal cycling stress in high-performance engine components. Motorsport and luxury automotive manufacturers in Italy and Germany are qualifying these structures for turbocharger shafts and valve train elements. The technology is absorbing market share from thermal spray coatings in applications requiring sub-5 micrometer thickness with conformal coverage.
REACH authorization requirements for chromium trioxide in functional plating are forcing automotive tier suppliers to validate DLC alternatives before 2027 sunset dates. German KBA type-approval processes now accept DLC-coated brake components as equivalent to hard chrome for corrosion resistance testing. Surface engineering departments at Volkswagen, BMW, and Mercedes-Benz suppliers are consolidating coating specifications around PVD alternatives.
Buyer consolidation among cutting tool manufacturers is compressing coating service contract durations from multi-year frameworks to quarterly price negotiations. Sandvik, Kennametal, and Mitsubishi Materials are unbundling coating from insert supply, forcing independent PVD shops to compete on turnaround time rather than captive capacity. This pattern is most visible in the Rhine-Ruhr manufacturing corridor and Japan's Aichi prefecture tooling clusters.
Global Diamond-Like Carbon (DLC) Market Segmentation
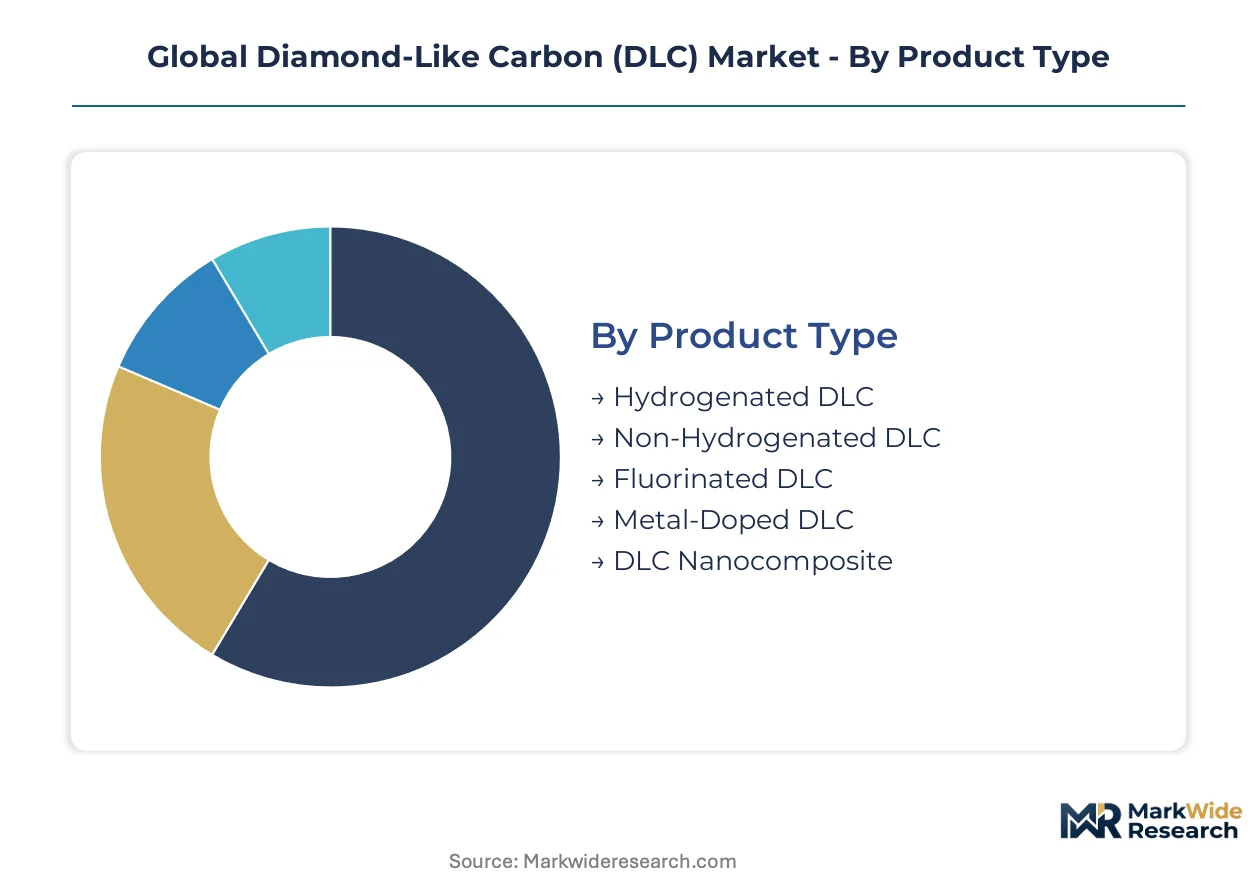
DLC coating specifications diverge sharply between regulated medical applications demanding hydrogenated purity and industrial tooling prioritizing deposition throughput. Understanding these segment boundaries enables suppliers to align validation investments with margin capture potential.
Product Type:
Hydrogen bonding configurations define performance ceilings for biocompatibility, thermal stability, and friction coefficients across end-use specifications.
- Hydrogenated DLC:Amorphous carbon films with 20-40 atomic percent hydrogen content deliver sub-0.1 friction coefficients and established biocompatibility under FDA 21 CFR Part 820 protocols. Cardiovascular stent and orthopedic implant manufacturers in Switzerland and the United States specify these grades for permanent implantation, with validation cycles extending coating lead times.
- Non-Hydrogenated DLC:Pure carbon matrices without hydrogen incorporation sacrifice some lubricity for superior thermal stability above 400°C. Cutting tool manufacturers in Japan's Aichi prefecture and Germany's Rhine-Ruhr corridor specify these films for high-speed machining where coating integrity under cutting heat matters more than friction reduction.
- Fluorinated DLC:CFx-terminated surfaces engineered for extreme chemical inertness in semiconductor etch chamber components.
- Metal-Doped DLC:Titanium or tungsten incorporation enhances toughness for aircraft landing gear and actuator pins facing fatigue cycling.
- DLC Nanocomposite:Ceramic particle dispersions targeting erosion resistance in pump seals and slurry handling equipment.
Mature deployment sits with Hydrogenated DLC. Newer deployment is concentrated in Metal-Doped DLC.
Application:
Component geometry and contact mechanics dictate coating thickness, adhesion systems, and deposition temperature constraints.
- Cutting Tools:Indexable inserts and solid carbide end mills receive 1-3 micrometer films through high-throughput PVD batch processing. Tool manufacturers in Japan and South Korea are unbundling coating from insert supply, compressing contract durations to quarterly price negotiations.
- Automotive Components:Piston rings, fuel injectors, and valve train elements substitute DLC for hexavalent chromium under EU REACH sunset deadlines. German KBA type-approval now accepts DLC-coated brake components as equivalent to hard chrome in corrosion resistance testing.
- Medical Devices:Cardiovascular stents and orthopedic bearings demand sub-micron thickness control with full batch traceability.
- Electronics:Hard disk drive read/write heads and MEMS switches leverage DLC dielectric properties and wear resistance.
- Optical Coatings:Infrared windows and laser lenses exploit DLC transparency in specific wavelength bands combined with scratch protection.
- Aerospace Parts:Landing gear and actuator pins specify metal-doped variants for fatigue resistance under Boeing and Airbus supplier frameworks.
Volume concentration centers on Cutting Tools. Specification complexity peaks in Medical Devices.
Coating Technology:
Deposition physics determine substrate temperature limits, conformality on complex geometries, and capital intensity per installed capacity.
- PVD:Physical vapor deposition dominates cutting tool coating through magnetron sputtering and cathodic arc configurations. Tool manufacturers in Japan operate the largest installed base of PVD batch systems, with cycle times optimized for insert throughput rather than medical-grade documentation.
- CVD:Chemical vapor deposition at 700-900°C suits cemented carbide substrates but excludes hardened steels and aluminum. Industrial valve and pump manufacturers specify CVD DLC where thermal budget permits and coating thickness requirements exceed 5 micrometers.
- Plasma Enhanced CVD:Lower substrate temperatures below 300°C enable conformal deposition on complex three-dimensional geometries including undercuts and internal passages. Medical implant and aerospace component manufacturers specify PECVD for hardened steel substrates where distortion must be avoided.
- Sputtering:Magnetron configurations deliver excellent thickness uniformity across large-area substrates for optical and electronic applications.
- Arc Evaporation:High-ionization deposition rates suit high-volume automotive component coating with robust film adhesion.
Margin capture concentrates in Plasma Enhanced CVD. Capacity expansion is accelerating in PVD.
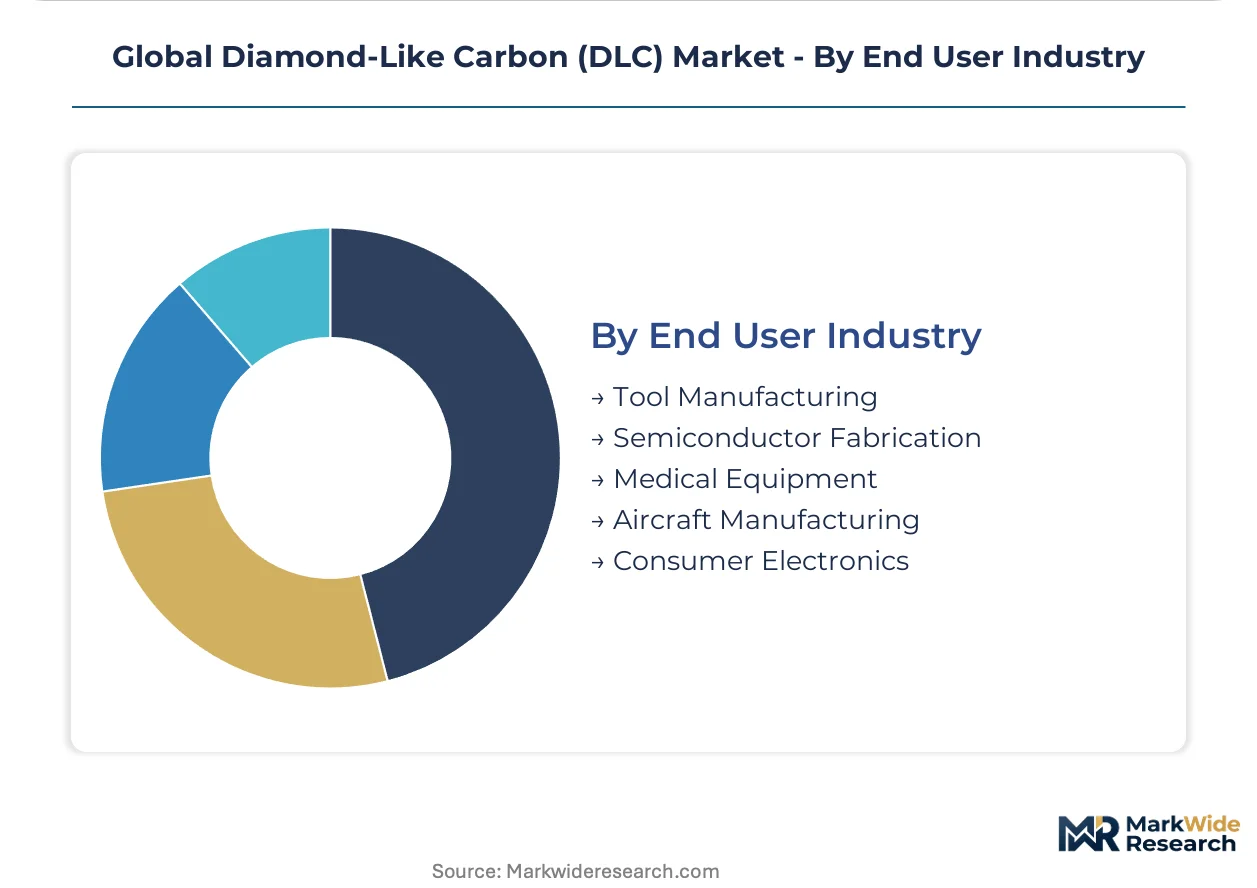
End User Industry:
Procurement sophistication ranges from commodity spot purchasing in tool manufacturing to validated supply agreements in medical equipment.
- Tool Manufacturing:Sandvik, Kennametal, and Mitsubishi Materials are consolidating coating specifications and unbundling from insert supply. Independent PVD shops compete on turnaround time in Japan's Aichi and Germany's Rhine-Ruhr clusters.
- Semiconductor Fabrication:Wafer processing equipment demands sub-micron film uniformity with particulate control. Tooling manufacturers in Japan and South Korea are expanding PVD capacity to service etch chamber components and wafer handling robotics.
- Medical Equipment:FDA 21 CFR Part 820 and EU MDR impose validation documentation burdens that favor captive coating operations or long-term supplier partnerships.
- Aircraft Manufacturing:Boeing and Airbus tier suppliers specify metal-doped DLC for landing gear with fatigue resistance certification.
- Consumer Electronics:Thermal budget constraints exclude DLC from aluminum and polymer housings, limiting adoption to internal wear components.
Contract stability characterizes Medical Equipment. Price volatility concentrates in Tool Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aichi Prefecture's precision tooling corridor outside Nagoya anchors the highest concentration of DLC coating capacity worldwide, with over two hundred PVD batch systems servicing cutting tool manufacturers. Japan's METI energy efficiency mandates for industrial machinery create sustained specification pull for low-friction bearing coatings across the archipelago.
Japan
Semiconductor fabrication equipment and cutting tool manufacturers drive coating volume in Aichi and Osaka prefectures. METI's energy efficiency standards for industrial machinery mandate low-friction bearings that reduce parasitic power losses. Tooling clusters in Nagoya and Osaka are expanding PVD capacity to meet wafer processing equipment demand.
Germany
Automotive tier suppliers in Stuttgart and Munich are validating DLC alternatives to hexavalent chromium plating ahead of EU REACH sunset deadlines. The KBA now accepts DLC-coated brake components as equivalent to hard chrome in corrosion resistance testing. Surface engineering departments at Volkswagen and BMW suppliers are consolidating specifications around PVD alternatives.
United States
Cardiovascular stent and orthopedic implant manufacturers in Minnesota and Massachusetts specify hydrogenated DLC under FDA 21 CFR Part 820 protocols. FDA quality system requirements shape medical device coating validation with full batch traceability. Medical technology clusters in the Twin Cities and Greater Boston maintain captive coating operations for regulated applications.
South Korea
Semiconductor etch chamber component manufacturers in Gyeonggi Province and Suwon are expanding PVD coating capacity for sub-micron film uniformity. The national industrial policy supports precision manufacturing clusters with tax incentives for advanced materials processing. Tooling manufacturers in the Seoul Capital Area service Samsung and SK Hynix supply chains.
Switzerland
Orthopedic bearing and dental implant manufacturers in the Jura Arc specify hydrogenated DLC with exacting thickness control for permanent implantation. Swissmedic regulations align with EU MDR for biocompatibility validation. Precision manufacturing clusters in Biel and Neuchâtel maintain medical-grade coating workflows.
Global Diamond-Like Carbon (DLC) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the medical-industrial split, with hydrogenated film specialists capturing validation-intensive contracts while high-throughput shops compete on deposition cycle times. The vendor base organizes into three strategic archetypes: European medical-grade specialists with captive R&D facilities, Asian automotive-focused service networks with equipment manufacturing arms, and independent PVD shops competing on turnaround velocity. Consolidation pressure is accelerating as cutting tool manufacturers unbundle coating from insert supply, while backward integration into process gas supply emerges as a defensive move against acetylene and argon cost volatility.
Within the European medical-grade tier, CemeCon and Ionbond exemplify specialists with established validation protocols for cardiovascular and orthopedic applications. Oerlikon Balzers occupies a position spanning equipment manufacturing and coating services across Asian automotive supply chains. Among independent high-volume operators, Platit represents the scale-driven archetype with extensive PVD service network coverage for cutting tool manufacturers.
| Leading Market Players |
|---|
| CemeCon |
| Applied Diamond Coatings LLC |
| Oerlikon Balzers |
| Platit |
| Techmetals |
| Ionbond |
| Richter Precision Inc. |
| Kurt J. Lesker Company |
| Calico Coatings |
| Others |
Supply & Pricing Matrix
Plasma-enhanced CVD adoption for hardened steel substrates simultaneously compresses unit coating costs and concentrates margin capture among equipment-integrated service providers in Japan and Germany. This technology shift rewards operators with captive process gas supply and backward integration into PVD system manufacturing, while independent shops face pricing pressure from fixed-rate automotive contracts and volatile acetylene feedstock costs.
Pricing Analysis
Outcome-based pricing anchored to component durability metrics and manufacturing yield rates dominates medical-grade hydrogenated DLC contracts, with cardiovascular stent manufacturers in Switzerland and Massachusetts paying premiums for FDA 21 CFR Part 820 validation documentation. Pricing stratifies across premium medical tiers with full batch traceability, standard industrial grades for cutting tool throughput, and economy non-hydrogenated films competing on deposition cycle times. Cost compression in the industrial tier is intensifying because Sandvik and Mitsubishi Materials have unbundled coating from insert supply, compressing contract durations to quarterly negotiations. Automotive tier suppliers in Germany exhibit highest price sensitivity due to REACH compliance deadlines, while orthopedic implant manufacturers in the Jura Arc demonstrate lowest sensitivity given biocompatibility certification requirements.
Supply Chain Analysis
Acetylene and argon feedstock supply rests on petrochemical production clusters in Germany, Japan, and the United States, with coating service providers drawing from industrial gas distributors operating on indexed pricing contracts. PVD deposition equipment manufacturing concentrates among Japanese and European vendors, creating capex queue delays for capacity expansion projects in South Korea and China's semiconductor fabrication corridors. Single-source vulnerability characterizes high-purity hydrogen supply for hydrogenated DLC medical grades, with Swiss and German coating facilities maintaining redundant validation documentation across geographically distributed sites. Distribution runs through direct equipment leasing pilots and long-term supplier partnerships for regulated medical applications, while spot purchasing dominates cutting tool coating in Japan's Aichi prefecture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PECVD technology for low-temperature conformal deposition is displacing thermal spray coatings and hexavalent chromium plating across automotive and aerospace supply chains, creating a transition window where validation investments separate premium capture from commodity margin erosion.
For Market Incumbents: Hedge against acetylene cost volatility through captive process gas supply agreements or backward integration into argon recycling systems. Consolidate coating specifications around PECVD platforms compatible with hardened steel substrates to defend against emerging entrants offering magnetron sputtering alternatives with faster turnaround times. Prioritize FDA 21 CFR Part 820 validation infrastructure across multi-site operations to maintain medical-grade contract access.
For New Entrants and Emerging Players: Begin with respiratory device components under ISO 18562 biocompatibility testing protocols, where established coating shops lack specialized expertise and validation documentation. Target semiconductor etch chamber manufacturers in Gyeonggi Province seeking sub-micron film uniformity with particulate control standards that incumbent PVD networks struggle to meet. Deploy direct equipment leasing models to capture recurring revenue from mid-tier automotive suppliers facing REACH sunset deadlines.
For Investors and Strategic Acquirers: Exit pathways concentrate in equipment-integrated service networks with captive R&D facilities and validated medical-grade workflows, as buyer consolidation among cutting tool manufacturers compresses independent shop valuations. Long-term viability favors operators with backward integration into PVD system manufacturing and process gas supply chains that buffer margin erosion across the analysis window. Monitor Boeing and Airbus supplier qualification timelines for titanium-doped DLC landing gear specifications as the inflection signal for metal-doped variant demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Process Gas Supply | Captive argon and acetylene sourcing buffers margin compression from petrochemical feedstock volatility. |
| Multi-Site FDA 21 CFR Part 820 Validation | Redundant quality documentation enables bidding on cardiovascular stent and orthopedic implant contracts. |
| Direct PVD Equipment Leasing Models | Subscription deployments capture recurring revenue from German automotive tier suppliers facing REACH deadlines. |
| ISO 18562 Respiratory Device Certification | Biocompatibility testing expertise opens ventilator and anesthesia equipment specifications ahead of incumbent shops. |
| Titanium-Doped DLC R&D Investment | Fatigue resistance certification for Boeing and Airbus landing gear specifications redirects coating development priorities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating service operations managers, biomedical engineers at orthopedic device manufacturers, procurement leads at cutting tool OEMs, and PVD equipment engineering directors. SEC 10-K disclosures from Sandvik and Kennametal, FDA 510(k) submission databases, EU ECHA REACH authorization records, and Japanese METI industrial machinery efficiency reports provided demand-side validation. Bottom-up coating volume estimates from Aichi Prefecture and Rhine-Ruhr corridor facilities were cross-referenced against top-down semiconductor fabrication equipment capex disclosures and automotive production forecasts.
Data-stream reconciliation across hydrogenated and non-hydrogenated product categories, cutting tool versus medical device application splits, and PVD versus PECVD technology deployments shaped the analytical framework across the analysis window. Segmentation modeling incorporated product type hydrogen bonding configurations, coating thickness specifications by substrate geometry, end-use industry procurement sophistication tiers, and regional regulatory cluster variations. CAGRs were derived from installed PVD capacity expansion announcements, process gas consumption trends, and validated supply agreement durations. Industry-specific inputs included KBA type-approval acceptance timelines for DLC-coated brake components and ISO 18562 testing protocol adoption curves for respiratory device applications.
Acetylene feedstock price volatility, equipment vendor delivery queue extensions, and REACH authorization timeline delays are the dominant revision risks that could reshape coating demand trajectories. Forecasts reflect assumptions regarding semiconductor fabrication cluster expansion rates and automotive hard chrome substitution schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Cathode Materials Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Global Advanced Composites Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Corundum Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Borophene Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Global Synthetic Diamond Market