
 Carbon Prepreg Market | 2026-2036
Carbon Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Prepreg Market Intelligence
Market Context
Aluminum is restructuring primary structural economics in commercial aviation as Boeing and Airbus programs specify carbon prepreg for wing boxes and fuselage sections. Toray Industries dominates upstream carbon fiber supply through captive precursor capacity and positions across Japanese, American, and European aerospace tiers. Hexcel Corporation anchors North American defense and space programs with qualified material systems for fighter aircraft and satellite structures. SGL Carbon SE specializes in automotive-grade prepregs and extends its reach through partnerships with German premium vehicle manufacturers.
Technical Definition and Segment Structure
Carbon prepreg consists of unidirectional or woven carbon fiber reinforcement pre-impregnated with thermoset resin matrices, typically epoxy formulations with controlled tack and drape properties for automated layup or hand placement, serving industries requiring high stiffness-to-weight ratios under cyclic loading. Pre-impregnated tapes lead aerospace structural applications where automated fiber placement achieves precise fiber orientation and void control, while pre-impregnated fabrics sustain broader adoption in wind energy blade manufacturing where drapability over complex molds matters more than deposition speed. Structural components command the deepest margin pools due to qualification barriers and long-term supply agreements with tier-one aerostructures suppliers.
Regulatory Framework and Outlook
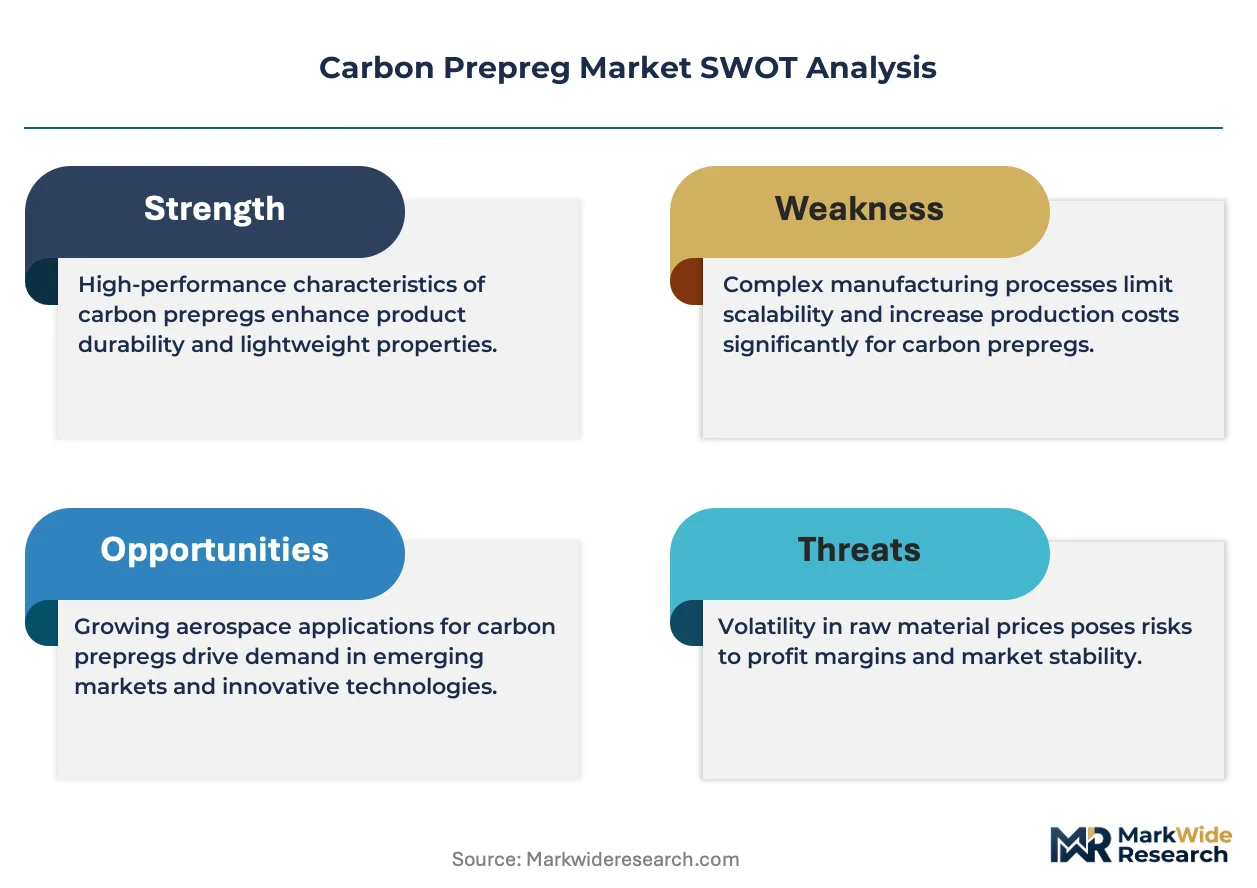
EPA enforces National Emission Standards for Hazardous Air Pollutants on composite manufacturing facilities, while REACH regulates resin chemistry and substance authorization across European supply chains, and FAA material qualification protocols govern substitution timelines in commercial aviation. These frameworks lengthen product development cycles but also entrench incumbent suppliers with certified material systems. Stakeholders must monitor evolving emissions thresholds and certification reciprocity agreements between national aviation authorities to anticipate regional sourcing shifts.
Market Dynamics
Automated fiber placement systems are compressing manufacturing cycle times while REACH and EU Green Deal emissions protocols force resin chemistry reformulation across European supply chains.
Growth Catalysts
- Automotive lightweighting mandates:German premium OEMs are qualifying carbon fiber composites for electric vehicle battery enclosures and structural members to offset battery mass.
- Wind blade scale-up:Turbine OEMs in Denmark and Spain specify pre-impregnated fabrics for 100-meter-plus blade spar caps requiring drapability over complex molds.
- Defense procurement acceleration:Fighter aircraft and satellite programs in the United States and France drive thermoset prepreg qualification for primary load-bearing structures.
Market Restraints
- Acrylonitrile cost volatility:Carbon fiber precursor pricing fluctuates with petrochemical feedstock markets, squeezing margin predictability for prepreg converters.
- Japanese supply concentration:Precursor and fiber capacity clusters disproportionately in Japanese chemical complexes, creating geographic single-point vulnerability.
- Thermoplastic substitution threat:PEEK and PPS matrix composites offer out-of-autoclave processing and recyclability advantages for non-structural applications.
Strategic Opportunities
- India aerospace tier integration:Tata Advanced Systems and similar suppliers seek qualified prepreg partners for regional aircraft and helicopter programs under offset agreements.
- Hydrogen pressure vessel demand:Type IV composite tanks for fuel cell vehicles and stationary storage create new high-volume filament winding applications.
- EU Green Deal manufacturing incentives:Carbon border adjustment mechanisms and green public procurement rules favor low-emission prepreg production methods.
Industry Challenges
- Automated fiber placement technician scarcity:Aerospace and wind sectors compete for operators skilled in AFP/ATL programming and in-situ consolidation.
- FAA/EASA dual certification timelines:Material qualification protocols require 18-36 month validation cycles before design allowable release.
Report Scope
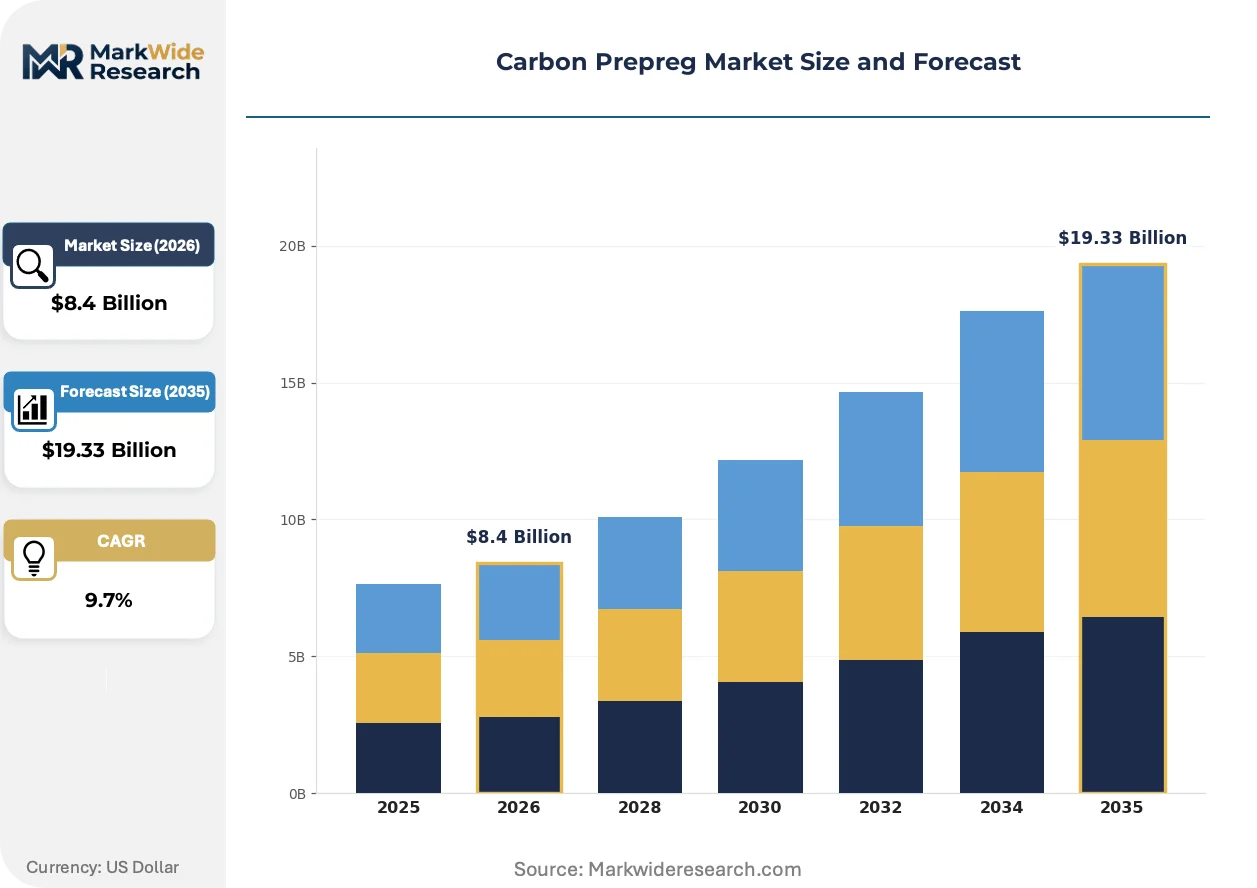
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Prepreg Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-impregnated Fabrics, Pre-impregnated Tapes, Pre-impregnated Films, Pre-impregnated Mats End User: Aerospace, Automotive, Marine, Wind Energy Manufacturing Process: Hand Layup, Automated Fiber Placement, Prepreg Process, Compression Molding Application: Structural Components, Aerospace Parts, Sporting Goods, Consumer Electronics |
| Companies Covered | Teijin Limited, Mitsubishi Chemical Corporation, Toray Industries, Inc., Axiom Materials, Gurit Holding AG, Hexcel Corporation, Solvay, Park Electrochemical Corporation, SGL Carbon SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Prepreg Market Strategic Shifts & Innovations
Resin chemistry automation and out-of-autoclave curing protocols are compressing capital intensity while digital thread integration traces fiber placement to structural performance.
Out-of-autoclave epoxy formulations are overtaking traditional autoclave-dependent prepregs in commercial aviation secondary structures. Bombardier and Gulfstream business jet programs specify OOA systems for control surfaces and fairings. This shift is overtaking the capital barrier that historically limited composite adoption to tier-one aerostructures suppliers with autoclave capacity.
REACH substance authorization requirements are restricting bisphenol-A and certain amine hardeners in European resin formulations. Formulators in Germany and France accelerate bio-based epoxy development to maintain aerospace qualification while meeting ECHA substance thresholds. Commercial aviation suppliers face the steepest compliance burden as grandfathered material systems age out of authorization windows.
Direct mill-to-aerostructures contracting is displacing distributor-mediated procurement for qualified aerospace prepregs. Tier-one suppliers in Toulouse and Hamburg negotiate long-term offtake agreements with Toray and Hexcel for qualified tape grades. This pattern concentrates most visibly in wing box and fuselage programs where material traceability requirements exceed distributor certification capabilities.
Carbon Prepreg Market Segmentation
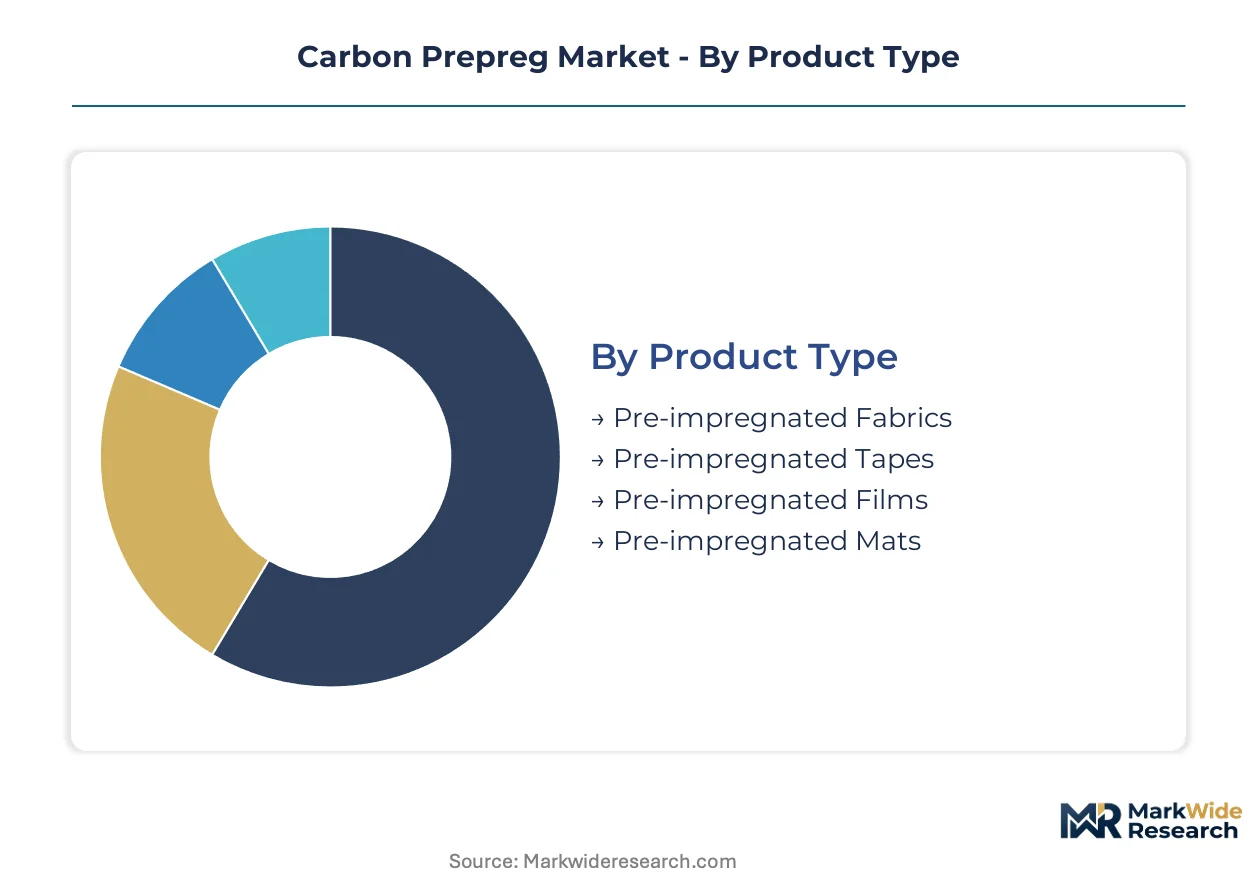
Carbon prepreg segmentation reveals divergent value pools across reinforcement formats and end-use qualification barriers. Aerospace tape grades command premium pricing through FAA-certified material systems, while fabric formats serve cost-sensitive wind energy and automotive applications with shorter qualification cycles.
Product Type:
Volume concentrates in fabric formats serving industrial scale-up, while tapes capture aerospace premium tiers through automated placement compatibility.
- Pre-impregnated Tapes:Unidirectional carbon fiber tows pre-impregnated with controlled-tack epoxy formulations enable automated fiber placement with precise fiber orientation and void control below 1%. Boeing 787 and Airbus A350 wing box programs in the United States and Germany specify qualified tape grades from Toray and Hexcel under long-term offtake agreements.
- Pre-impregnated Fabrics:Woven carbon fiber architectures pre-impregnated with drape-optimized resins conform to complex mold geometries without automated equipment. Wind blade manufacturers in Denmark and Spain specify fabric formats for 100-meter-plus spar caps where drapability outweighs deposition speed.
- Pre-impregnated Films:Thin resin films without fiber reinforcement serve as surface finish layers and adhesive interleaves in multi-material assemblies.
- Pre-impregnated Mats:Random or chopped fiber prepregs fill non-structural and cosmetic applications with lower mechanical property requirements.
Today's leader: Pre-impregnated Tapes. Tomorrow's challenger: Pre-impregnated Fabrics.
End User:
Qualification intensity separates aerospace certification cycles from automotive speed-to-market demands.
- Aerospace:Primary structural applications demand B-basis design allowables derived from statistically significant test programs. FAA and EASA material qualification protocols govern substitution timelines, entrenching incumbent suppliers with certified epoxy systems for wing boxes, fuselage sections, and control surfaces.
- Automotive:German premium OEMs qualify carbon prepreg for electric vehicle battery enclosures and structural members to offset battery mass, accepting shorter validation cycles than aviation.
- Marine:Racing yacht hulls and superyacht components specify carbon prepreg for stiffness-to-weight optimization under cyclic wave loading.
- Wind Energy:Turbine OEMs specify pre-impregnated fabrics for blade spar caps and shear webs, prioritizing drapability over fiber placement precision.
Aerospace dominates value capture; automotive represents the steepest expansion trajectory.
Manufacturing Process:
Automation penetration varies sharply between hand-intensive legacy methods and capital-intensive fiber placement systems.
- Automated Fiber Placement:Robotic deposition of prepreg tape with in-situ consolidation achieves deposition rates exceeding manual layup by an order of magnitude. Boeing and Airbus tier-one suppliers in Toulouse and Hamburg operate AFP cells for wing skin and fuselage barrel production.
- Hand Layup:Skilled technicians place and consolidate prepreg plies on open molds remains prevalent for prototype, repair, and low-rate production where capital investment in automation cannot be amortized.
- Prepreg Process:Resin film infusion and hot-melt impregnation lines constitute the upstream manufacturing stage rather than component fabrication.
- Compression Molding:Heated matched-die forming of pre-consolidated prepregs serves automotive and consumer electronics applications with moderate complexity and high volume repeatability.
Automated Fiber Placement commands capital investment; Hand Layup retains relevance in fragmented demand pockets.
Application:
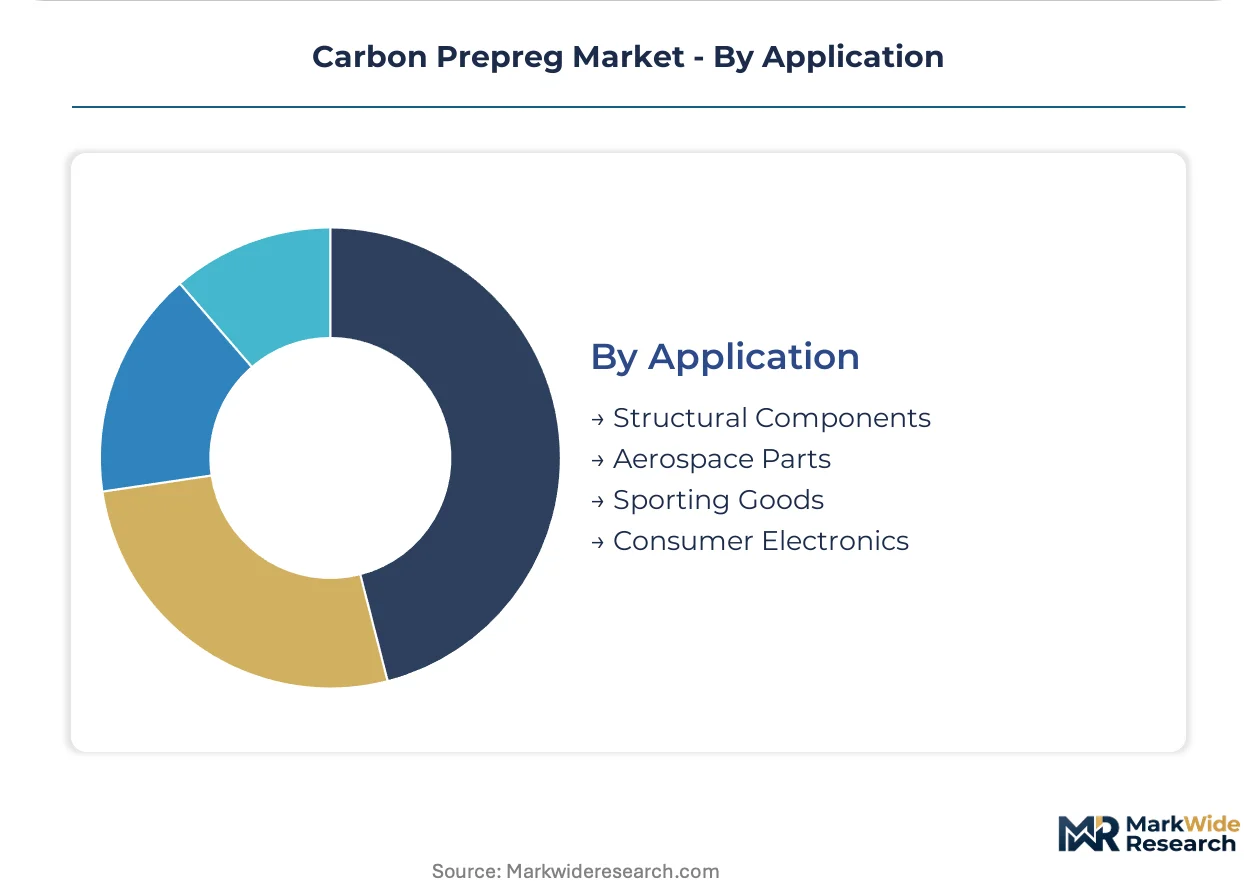
Structural qualification depth creates margin stratification between primary load-bearing and secondary non-structural uses.
- Structural Components:Primary load-bearing elements in aircraft, vehicles, and infrastructure require B-basis or A-basis statistical allowables with full traceability from fiber precursor to finished part. Long-term supply agreements with tier-one aerostructures suppliers lock in qualified material systems.
- Aerospace Parts:Secondary structures including fairings, control surfaces, and interior elements accept lower statistical basis requirements and faster qualification pathways.
- Sporting Goods:Bicycles, hockey sticks, and golf shafts prioritize stiffness-to-weight optimization with consumer-visible cosmetic finish layers.
- Consumer Electronics:Laptop chassis and wearable device housings exploit carbon prepreg for thin-wall rigidity and premium tactile properties.
Structural Components anchor supplier margins; Consumer Electronics offers volume scaling potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and American aerospace primes anchor carbon prepreg demand through qualified material programs. Japanese chemical complexes supply precursor and fiber capacity upstream. Chinese wind turbine manufacturers scale fabric consumption for blade production. Regulatory divergence between EPA emissions protocols and REACH substance authorization shapes regional sourcing patterns.
United States
Boeing and Gulfstream programs specify thermoset prepregs for wing boxes and business jet structures. FAA material qualification protocols govern 18-36 month validation cycles before design allowable release. Wichita aerostructures clusters and Seattle-area manufacturing cells operate automated fiber placement systems for commercial and defense platforms.
Germany
Premium automotive OEMs qualify carbon fiber composites for electric vehicle battery enclosures to offset battery mass. REACH and EU Green Deal regulations tighten volatile organic compound limits on resin formulations. Hamburg and Munich industrial corridors host prepreg qualification programs with tier-one aerostructures suppliers.
Japan
Toray Industries dominates upstream carbon fiber supply through captive precursor capacity across domestic chemical complexes. METI industrial policy supports advanced materials R&D through designated technology clusters. Nagoya and Tokyo metropolitan areas concentrate fiber production and aerospace tier relationships.
China
Wind turbine OEMs scale pre-impregnated fabric consumption for 100-meter-plus blade spar caps requiring drapability. MIIT standards and dual carbon goals accelerate domestic carbon fiber capacity expansion. Yangtze River Delta manufacturing bases integrate filament winding for hydrogen pressure vessel applications.
France
Airbus programs in Toulouse drive thermoset prepreg qualification for A350 wing boxes and fuselage sections. EASA certification reciprocity with FAA governs material substitution timelines. The Occitanie aerospace cluster maintains long-term offtake agreements with qualified tape suppliers for primary load-bearing structures.
Carbon Prepreg Market Key Industry Players
Global majors compete with regional champions across precursor supply, resin formulation, and qualification depth. Japanese chemical conglomerates control upstream fiber capacity while European and American firms anchor downstream prepreg conversion and aerospace certification. Three archetypes dominate: integrated fiber-to-prepreg suppliers, specialized resin formulators, and automotive-focused converters. Competitive moves concentrate on capacity expansion in low-emission production methods and strategic partnerships for hydrogen pressure vessel applications.
Among integrated suppliers, Toray Industries, Inc. exemplifies upstream-to-downstream control through captive precursor operations. Hexcel Corporation and SGL Carbon SE occupy distinct positioning vectors—Hexcel anchoring North American defense and space qualification, SGL specializing in automotive-grade systems through German premium OEM relationships. These three represent the structural poles around which mid-cap specialists and regional converters organize their market participation.
| Leading Market Players |
|---|
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Toray Industries, Inc. |
| Axiom Materials |
| Gurit Holding AG |
| Hexcel Corporation |
| Solvay |
| Park Electrochemical Corporation |
| SGL Carbon SE |
| Others |
Cost & Logistics Intelligence
EU Green Deal emissions thresholds gate both qualified supply and premium-tier pricing access for carbon prepreg producers, as REACH-compliant resin formulations command material cost premiums while excluding uncertified converters from aerospace procurement channels. German and French formulators capture pricing power through bio-based epoxy development that satisfies ECHA substance windows, while non-compliant suppliers face margin compression from exclusion.
Pricing Analysis
Acrylonitrile cost pass-through from petrochemical feedstock markets governs carbon fiber precursor pricing, compressing margin predictability for prepreg converters. Three-tier pricing structure across aerospace-qualified, industrial-standard, and automotive-economy levels separates tape grades with FAA certification from fabric formats for wind energy. Pricing pressure stems from thermoplastic substitution threats in non-structural applications. Automotive OEMs exhibit highest price sensitivity due to battery mass offset calculations, while aerospace primes accept premiums for B-basis design allowables.
Supply Chain Analysis
Carbon fiber supply rests on Japanese chemical complexes in Nagoya and Tokyo metropolitan areas, with precursor capacity concentrated domestically. Acrylonitrile feedstock, epoxy resin formulations, and automated fiber placement equipment constitute critical input dependencies. Single-source vulnerability from Toray Industries' upstream dominance creates geographic concentration risk. Distribution runs through direct mill-to-aerostructures contracting for qualified aerospace grades, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon prepreg markets offer margin expansion through out-of-autoclave curing adoption that compresses capital intensity for tier-two suppliers, alongside premium-tier shifts toward hydrogen pressure vessel applications.
For Market Incumbents: Cement qualification depth as the primary defensive moat by accelerating bio-based epoxy R&D ahead of REACH authorization sunsets. Expand captive precursor capacity through backward integration into acrylonitrile supply to offset Japanese concentration risk. Lock in long-term offtake agreements with Hamburg and Toulouse aerostructures clusters before distributor displacement accelerates. For New Entrants and Emerging Players: Capture filament winding demand for Type IV hydrogen pressure vessels in China's Yangtze River Delta manufacturing bases, where domestic carbon fiber capacity expansion outpaces qualification expertise. Target automotive battery enclosure applications with compression-molding compatible prepreg formats that bypass aerospace certification barriers. Partner with Indian tier-one suppliers under offset agreements for regional aircraft programs. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap resin formulators because ECHA substance authorization windows are aging out grandfathered material systems, creating forced seller dynamics among non-compliant European converters. Focus acquisition screening on German and French specialists with bio-based epoxy pipelines and existing aerospace tier relationships. Watch for acrylonitrile price volatility spikes as inflection indicators for vertical integration premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive acrylonitrile capacity insulates margin from petrochemical volatility at Japanese chemical complexes. |
| Bio-based Epoxy Formulation Investment | REACH-compliant resin chemistry maintains aerospace qualification while meeting ECHA substance thresholds in Germany. |
| Long-term Supply Agreement with Aerostructures | Direct mill-to-tier contracting with Toulouse and Hamburg clusters locks in qualified tape volume commitments. |
| Filament Winding Capacity for Pressure Vessels | Type IV composite tank demand from fuel cell vehicle programs in China creates high-volume growth vector. |
| Out-of-Autoclave Curing Protocol Adoption | Bombardier and Gulfstream OOA specifications for control surfaces reduce capital barriers for tier-two suppliers. |
Research Approach
Multiple input streams — primary interviews with aerospace procurement directors, automotive platform engineers, and wind blade manufacturing heads, alongside secondary validation through ECHA substance databases, FAA material qualification filings, and customs trade data — were reconciled through bottom-up and top-down triangulation. Conversations with resin formulators in Germany and France, carbon fiber producers in Japan, and tier-one aerostructures suppliers in the United States and Europe informed supply chain concentration assessments. Secondary sources included SEC 10-K disclosures from listed composites firms, REACH authorization registers, and MIIT domestic capacity announcements from China.
Data-stream reconciliation across product type, end-use industry, manufacturing process, and regional production hub dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs incorporated automated fiber placement equipment installation rates, electric vehicle platform composite content trajectories, and wind turbine blade length scaling curves.
Acrylonitrile price volatility, REACH substance authorization timeline shifts, and thermoplastic substitution acceleration are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect modeling assumptions that remain contingent on regulatory enforcement consistency and certification reciprocity between FAA and EASA. A small set of named triggers — precursor supply disruptions, emissions threshold tightening, and hydrogen infrastructure deployment rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Europe Graphene Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Global Synthetic Diamond Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Advanced Composite Materials Market