
 Oilfield Air Drilling Market | 2026-2036
Oilfield Air Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Air Drilling Market Analysis
Aftermarket service revenue from compressor maintenance and downhole hammer refurbishment is reshaping margin distribution across the oilfield air drilling value chain. Baker Hughes leverages its integrated equipment-service model to capture recurring revenue streams in harsh-environment deployments. Halliburton anchors its position through proprietary air hammer designs optimized for hard-rock formations in the Middle East. Schlumberger differentiates via digital diagnostics that predict downhole tool failure before costly interruptions occur.
Oilfield air drilling injects compressed air or nitrogen into the wellbore to reduce hydrostatic pressure, enabling faster penetration rates in hard formations while minimizing formation damage from invasive drilling fluids; typical surface pressures range from 350 to 1,500 psi depending on hole depth and formation characteristics. Horizontal wellbores now dominate North American air drilling activity as lateral lengths extend past 3,000 meters in unconventional reservoirs. Smart drilling systems represent the fastest-expanding technology category, combining real-time downhole telemetry with automated air injection controls. Onshore applications retain the largest share of deployed air drilling rigs, though offshore managed-pressure air systems are gaining traction in shallow-water gas developments.
The US EPA enforces methane monitoring requirements that shape air drilling equipment specifications, while OSHA mandates respiratory protection standards for crews exposed to silica dust during dry drilling operations. API Specification 7-1 governs downhole tool dimensional tolerances and material grades, creating compliance barriers for non-certified suppliers. Stakeholders must weigh capital allocation between conventional rotary air hammer fleets and emerging pulsed-air technologies that promise lower nitrogen consumption in pressure-depleted reservoirs.
Market Dynamics
Compressed nitrogen injection systems are displacing conventional air drilling in pressure-depleted shale formations, forcing equipment manufacturers to redesign compressor fleets around lower-density gas specifications and closed-loop recovery architectures.
Growth Catalysts
- EPA Methane Regulations:Fugitive emission mandates in the United States accelerate closed-loop air system retrofits across Permian Basin operations.
- Extended lateral drilling:Horizontal wellbores exceeding 3,000 meters in West Texas unconventional reservoirs drive demand for high-pressure air hammer durability.
- Silica dust exposure protocols:OSHA respiratory protection standards expand automated dust suppression system installations at onshore drilling sites.
Market Restraints
- Specialized steel alloys:Downhole hammer manufacturing concentrates among API 7-1 certified forgers in Germany and Japan, creating supply bottlenecks during demand spikes.
- Substitute fluid systems:Managed-pressure drilling with synthetic-based muds captures share in deep gas formations where air drilling faces pressure control limitations.
- Capital intensity:Mobile nitrogen generation units require compressor packages exceeding 1,500 psi ratings, freezing out mid-tier contractors from closed-loop service bids.
Strategic Opportunities
- Digital diagnostics convergence:Real-time telemetry paired with predictive maintenance algorithms opens recurring revenue streams for tool fleet operators.
- Middle East hard-rock expansion:Carbonate formation drilling in Saudi Arabia and the UAE creates demand for percussion-optimized air hammer designs.
- Shallow-water gas developments:Offshore managed-pressure air systems gain traction in Southeast Asian marginal field projects.
Industry Challenges
- Downhole telemetry integration:Legacy rotary rigs require control system overhauls to accommodate smart drilling automation, extending deployment timelines.
- API 7-1 certification backlog:Material grade verification delays for non-standard hammer geometries stretch procurement cycles for custom tool orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Air Drilling Market |
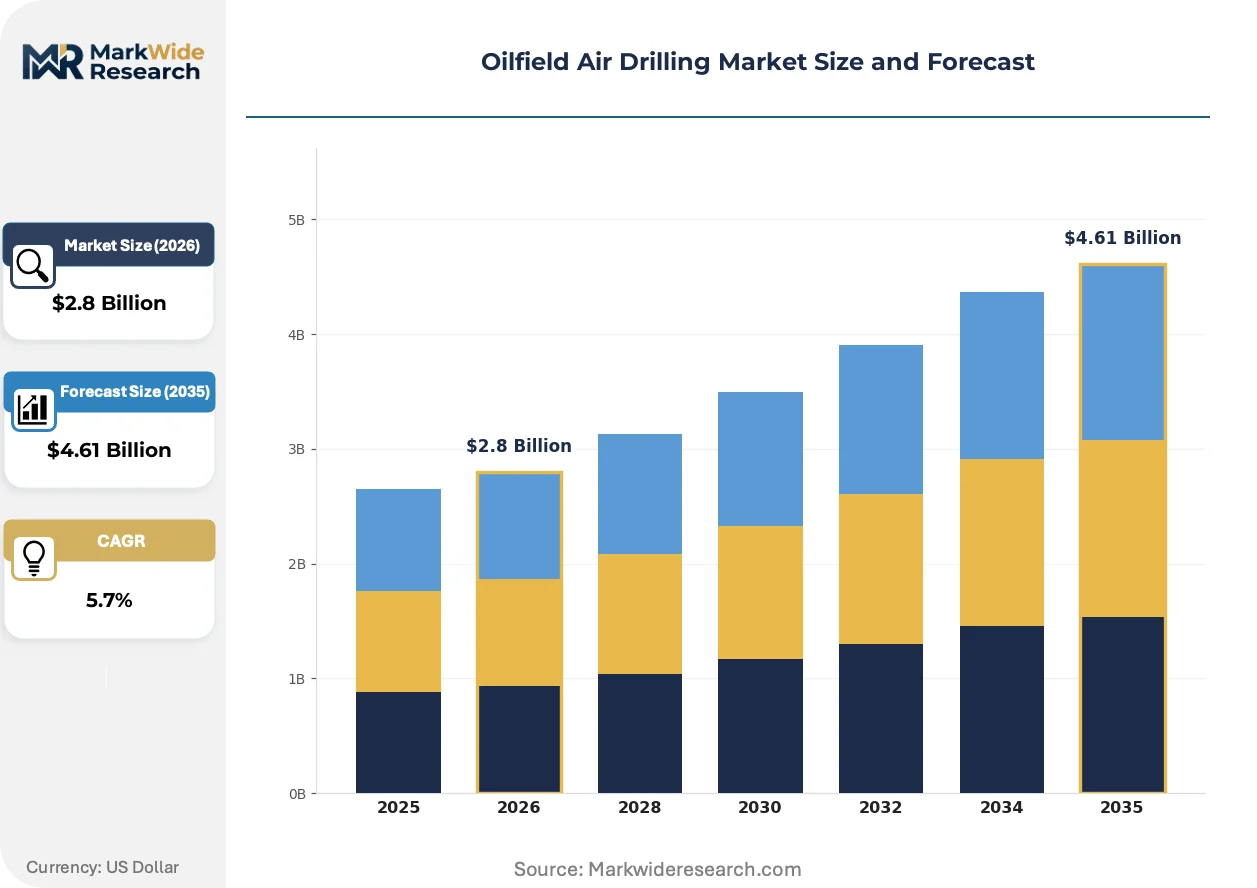
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vertical, Horizontal, Directional, Multilateral Application: Onshore, Offshore, Research, Exploration Technology: Smart Drilling, Rotary, Managed Pressure, Pulsed Air End User: Oil Companies, Independent Producers, Service Providers, Contractors |
| Companies Covered | NOV Inc., Aker Solutions, Baker Hughes, Tenaris, TechnipFMC, Halliburton, Weatherford, China Oilfield Services Limited, Schlumberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Air Drilling Market Emerging Trajectories
Equipment-service bundling is compressing vendor margins while elevating technical support expectations, reshaping how air drilling contractors structure long-term field agreements.
Pulsed-air drilling technology is hybridizing conventional continuous-flow methods with intermittent pressure waves to reduce nitrogen consumption in depleted reservoirs. Unconventional shale operators in the Permian Basin are piloting these systems on extended-reach laterals. The technology is hybridizing cost structures by cutting consumables expenditure while demanding upgraded compressor control architectures.
EPA methane monitoring rules now mandate optical gas imaging surveys at drilling sites, forcing air system designers to eliminate venting points in surface equipment. Equipment specifications now require sealed bearing assemblies and closed-loop pressure relief circuits. North American onshore contractors face the steepest compliance retrofit costs as state-level rules in Texas and New Mexico layer onto federal baselines.
Service contract unbundling is fragmenting traditional full-scope agreements into discrete equipment rental, maintenance, and nitrogen supply arrangements. Independent nitrogen providers in the Permian Basin are capturing volume previously held by integrated oilfield services. This restructuring is most pronounced among private equity-backed operators seeking line-item cost transparency for investor reporting.
Oilfield Air Drilling Market Segmentation
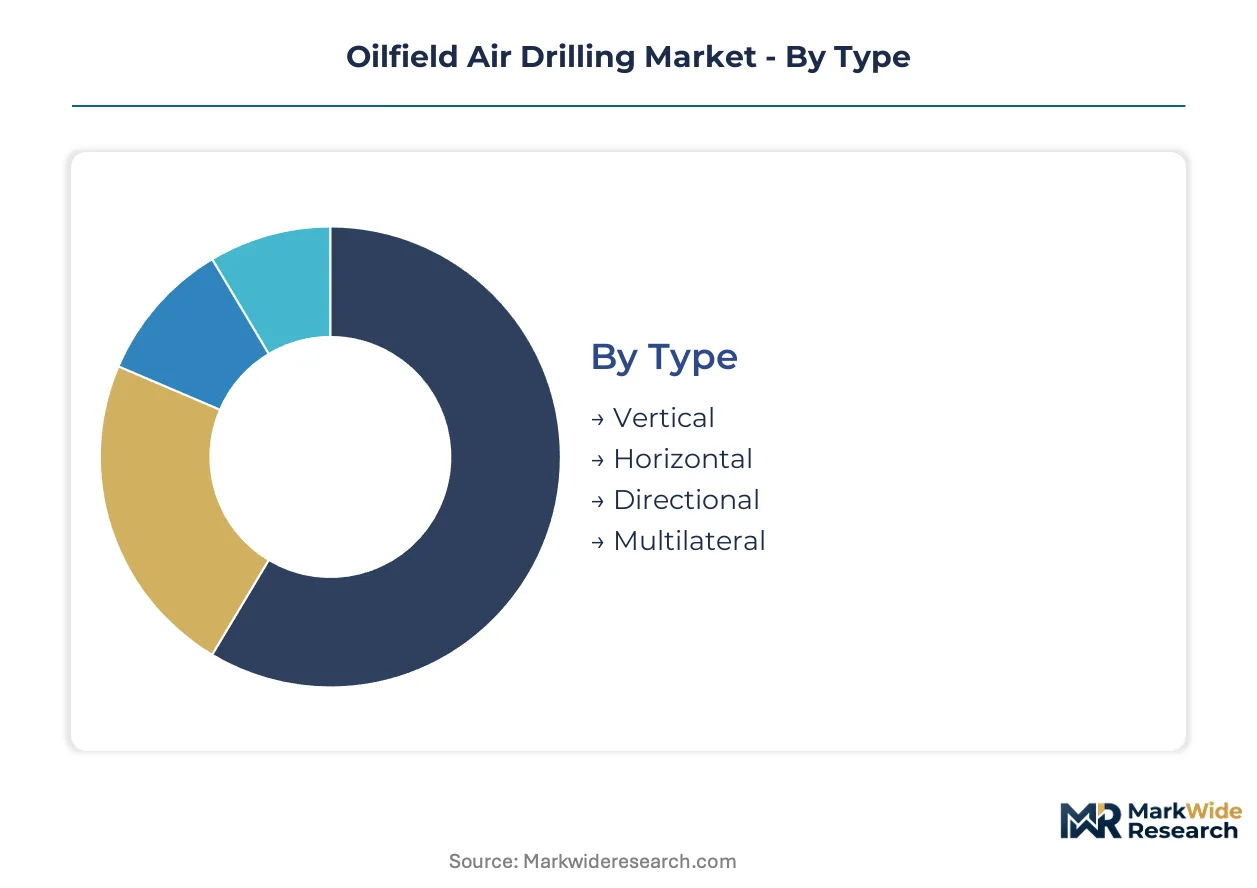
Segmentation in oilfield air drilling reveals how technology choice, well geometry, and operator type determine equipment specifications and service pricing. Understanding these divisions exposes where capital concentrates and which configurations face substitution pressure from alternative drilling methods.
Type:
Mature vertical configurations coexist with emerging multilateral architectures as operators balance simplicity against reservoir contact optimization.
- Vertical:Straight-hole drilling maintains dominance in conventional sandstone targets and shallow gas fields where deviation control costs outweigh production benefits. Demand persists in West Texas conventional zones and Saudi Arabian carbonate developments where reservoir thickness reduces horizontal necessity.
- Horizontal:Lateral sections exceeding 3,000 meters now dominate Permian Basin unconventional activity, driving demand for high-pressure air hammer durability and continuous nitrogen injection. Extended-reach designs strain compressor fleet specifications and elevate downhole tool failure rates in hard-rock interbeds.
- Directional:Controlled deviation drilling serves salt-dome flank developments and fault-block targeting where precise wellbore placement matters more than lateral length. Applications concentrate in mature US Gulf Coast fields and Middle East carbonate rim developments.
- Multilateral:Branch-well architectures from single motherbores remain technically challenging for air drilling due to junction pressure integrity requirements. Pilot deployments focus on compartmentalized North Sea gas reservoirs and Australian coalbed methane fields.
Horizontal configurations retain volume leadership; multilateral designs hold the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive offshore deployments from price-sensitive onshore contract economics.
- Onshore:Land-based operations account for the majority of deployed air drilling rigs, with West Texas and southeastern New Mexico forming the densest activity clusters. EPA methane regulations and OSHA silica protocols shape equipment specifications and crew protection investments.
- Offshore:Shallow-water gas developments in Southeast Asian marginal fields adopt managed-pressure air systems to avoid formation damage in pressure-depleted zones. Higher day rates justify closed-loop nitrogen recovery architectures unavailable to onshore contractors.
- Research:Experimental drilling programs test pulsed-air and geothermal applications outside commercial production economics. Funding flows from national laboratories in the United States and consortium-backed geothermal demonstration projects.
- Exploration:Wildcat drilling in frontier basins employs air methods for rapid penetration through hard caprock where fluid invasion risks obscure formation evaluation. Activity concentrates in Argentine Vaca Muerta extensions and Moroccan offshore reconnaissance.
Onshore applications dominate capital deployment; offshore gas developments are climbing fastest as marginal field economics improve.
Technology:
Supply concentration among API-certified forgers limits availability of advanced hammer designs while digital capabilities differentiate service tiers.
- Smart Drilling:Real-time telemetry paired with automated air injection controls enables predictive failure detection and rate-of-penetration optimization. Integration demands control system overhauls on legacy rotary rigs, extending deployment timelines.
- Rotary:Conventional continuous-flow methods retain cost advantages in competent formations without pressure depletion complications. Equipment availability and technician familiarity sustain share in Middle Eastern carbonate drilling.
- Managed Pressure:Precision annular pressure control bridges air drilling and conventional mud systems in narrow-margin formations. Offshore shallow-water gas projects in Southeast Asia drive specification evolution.
- Pulsed Air:Intermittent pressure wave technology cuts nitrogen consumption in depleted reservoirs but demands upgraded compressor control architectures. Permian Basin operators pilot these systems on extended-reach laterals to reduce consumables expenditure.
Rotary systems maintain the widest installed base; pulsed-air configurations are gaining share fastest among pressure-depleted shale operators.
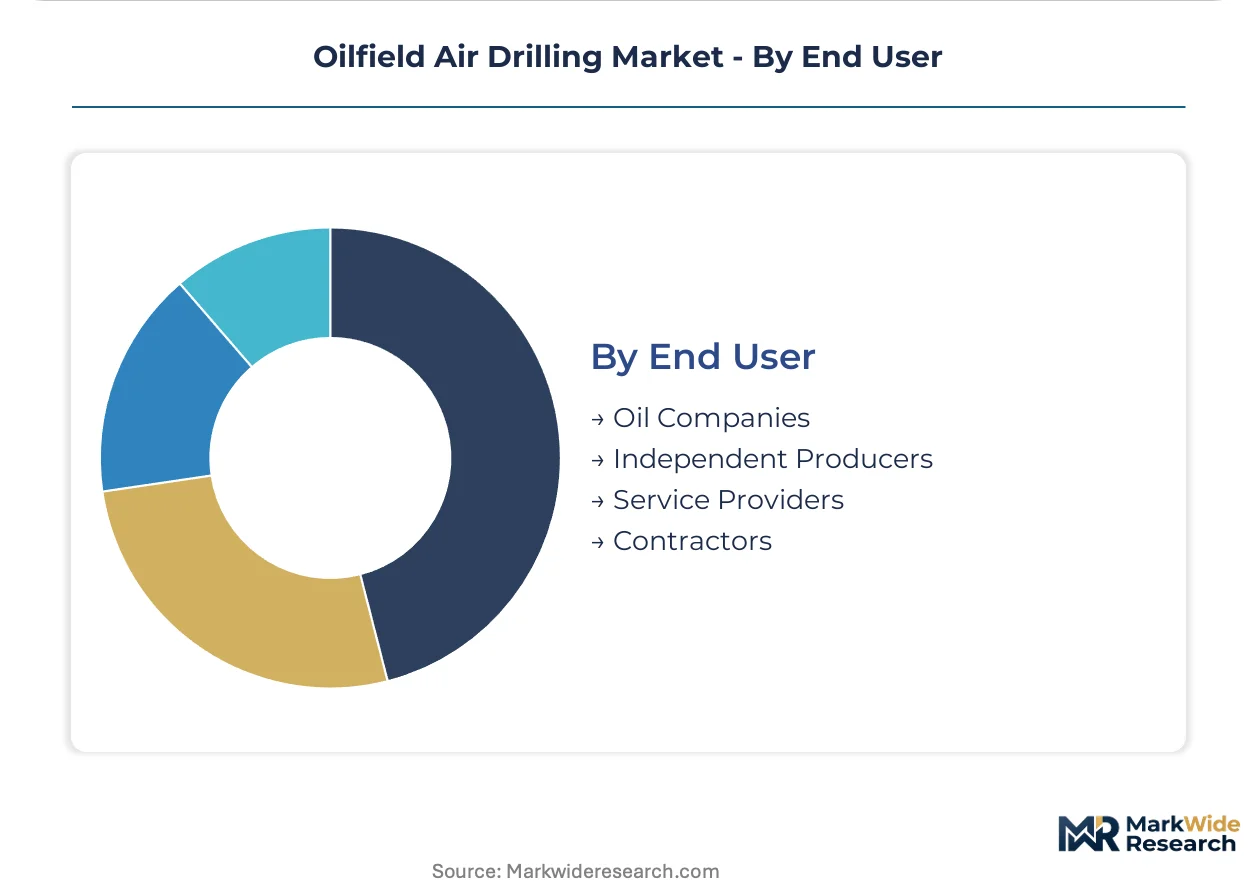
End User:
Customer type determines procurement structure, with integrated oil companies favoring bundled service contracts and independents pursuing unbundled line-item transparency.
- Oil Companies:Majors and national oil companies deploy captive air drilling fleets or long-term integrated service agreements covering equipment, nitrogen supply, and maintenance. Capital discipline favors vendors with global logistics networks and API-certified tool inventories.
- Independent Producers:Private equity-backed operators in North American shale plays drive contract unbundling, separating equipment rental, maintenance, and nitrogen supply for investor reporting clarity. Price sensitivity elevates competition among regional nitrogen providers.
- Service Providers:Integrated oilfield services firms capture recurring revenue through aftermarket compressor maintenance and downhole hammer refurbishment. Technical support expectations compress vendor margins while extending contract durations.
- Contractors:Mid-tier drilling contractors face exclusion from closed-loop service bids due to capital intensity of mobile nitrogen generation units exceeding 1,500 psi ratings. Market access depends on equipment leasing partnerships with nitrogen specialists.
Oil companies command the largest contract values; independent producers are expanding their share of technology pilot programs and alternative procurement structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air drilling compressor manufacturing clusters in Germany and Japan supply API 7-1 certified forgings to operators worldwide. Demand geography follows unconventional shale basins and hard-rock carbonate developments across four distinct national markets.
United States
Permian Basin operators in West Texas and southeastern New Mexico deploy the densest concentration of horizontal air drilling rigs for extended-reach laterals exceeding 3,000 meters. EPA methane monitoring rules mandate optical gas imaging surveys and sealed bearing assemblies on surface equipment. Midland-Odessa anchors aftermarket service demand for compressor maintenance and downhole hammer refurbishment.
Saudi Arabia
Carbonate formation drilling in the Ghawar and Khurais fields drives demand for percussion-optimized air hammer designs in hard-rock intervals. The national oil company enforces closed-loop nitrogen recovery specifications for pressure-depleted reservoirs. Dhahran-based engineering centers coordinate Middle East technical support for high-temperature downhole tools.
China
Sichuan Basin shale gas operators pilot pulsed-air systems to reduce nitrogen consumption in pressure-depleted formations. MIIT standards govern compressor safety certifications for mobile nitrogen generation units. Chongqing manufacturing clusters produce lower-cost rotary air hammer assemblies for domestic unconventional drilling campaigns.
United Arab Emirates
Offshore shallow-water gas developments in the Lower Zakum field adopt managed-pressure air systems to minimize formation damage. MOHAP regulations align equipment specifications with international pressure-control standards. Abu Dhabi contracting hubs integrate nitrogen supply logistics for marginal field redevelopment projects.
Canada
Montney and Duvernay shale operators in Alberta and British Columbia utilize air drilling for rapid caprock penetration in winter drilling windows. Health Canada respiratory protection standards govern silica dust exposure protocols at remote onshore sites. Calgary service centers coordinate cross-border nitrogen logistics with Permian Basin supply chains.
Oilfield Air Drilling Market Vendor Landscape
Integrated energy technology conglomerates and specialized oilfield service providers split the market along equipment-manufacturing versus service-delivery lines. The vendor structure concentrates among firms with captive forging relationships and global nitrogen logistics networks. Three archetypes dominate: full-scope integrated services, equipment-specialist manufacturers, and regional nitrogen supply contractors. Competitive positioning hinges on API certification maintenance and aftermarket service contract duration.
Among Houston-based integrated service providers, Baker Hughes, Halliburton, and Schlumberger exemplify the bundled equipment-service model. These firms anchor recurring revenue streams through compressor fleet ownership and predictive maintenance algorithms. NOV Inc. and Weatherford occupy positions within the equipment-specialist tier, emphasizing downhole tool durability and control system integration. China Oilfield Services Limited represents state-affiliated scale advantages in Asia-Pacific contracting.
| Leading Market Players |
|---|
| NOV Inc. |
| Aker Solutions |
| Baker Hughes |
| Tenaris |
| TechnipFMC |
| Halliburton |
| Weatherford |
| China Oilfield Services Limited |
| Schlumberger |
| Others |
Supply Flow & Price Mechanics
Houston-Dubai nitrogen logistics corridors absorb premium freight costs that compress margins for onshore contractors while enabling API-certified suppliers to command tiered pricing premiums based on certification grade and compressor specification tiers.
Pricing Analysis
API Specification 7-1 dictates the pricing tier structure across the oilfield air drilling market, separating premium-mid-economy pricing differentiation based on material grade verification and closed-loop system architecture. Price differentiation stems from certification backlog delays and nitrogen consumption efficiency ratings. Pricing pressure stems from unbundled service contracts as independent producers demand line-item transparency. Mid-tier contractors exhibit highest price sensitivity due to capital intensity barriers exceeding 1,500 psi compressor ratings, while national oil companies show lowest sensitivity through captive fleet ownership.
Supply Chain Analysis
Tariff exposure between Germany and Japan dominates supply chain risk profiles for API 7-1 certified forging supply. Manufacturing gravity centers on German and Japanese precision forgers for specialized steel alloys, with Chinese Chongqing clusters producing lower-cost rotary assemblies. Raw material dependencies include high-grade chromium-molybdenum steel, tungsten carbide inserts, and precision bearing assemblies. Single-source vulnerability concentrates in non-standard hammer geometry certification. Distribution runs through integrated oilfield service hubs in Houston, Dhahran, and Calgary coordinating nitrogen logistics with aftermarket refurbishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
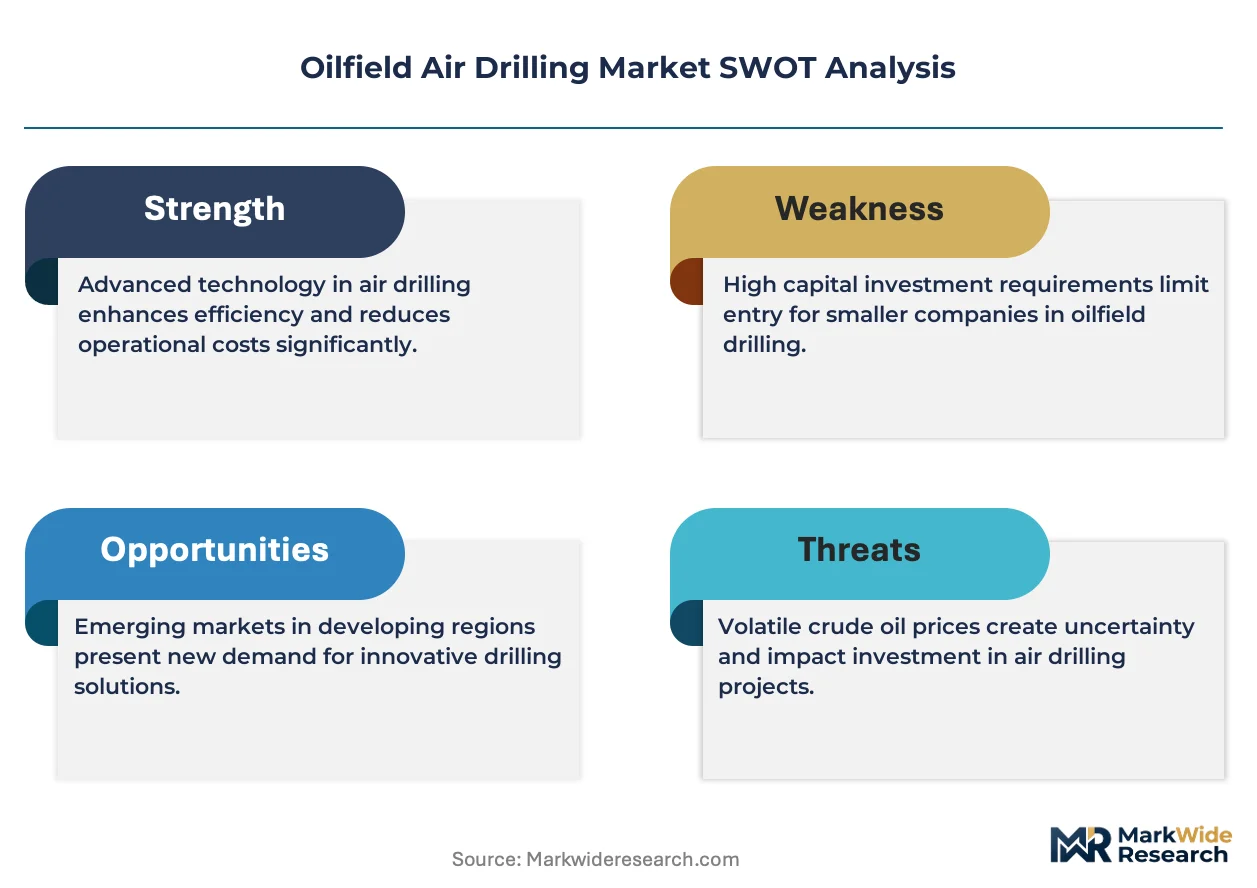
Managed-pressure drilling with synthetic-based muds threatens substitution in deep gas formations, forcing air drilling incumbents to defend positioning through technology differentiation and service bundling lock-in.
For Market Incumbents: Entrench market position through backward integration into captive nitrogen generation capacity and predictive maintenance algorithm deployment. Baker Hughes and Halliburton demonstrate model efficacy via integrated equipment-service contracts. Compressor fleet ownership creates switching costs that synthetic mud substitutes cannot replicate. API certification maintenance investments defend against regional nitrogen provider encroachment. For New Entrants and Emerging Players: Southeast Asian shallow-water gas developments offer underpenetrated white-space for managed-pressure air system deployment. Pulsed-air technology pilots in Permian Basin extended-reach laterals present second entry vector through consumables reduction value proposition. Partner with established nitrogen logistics networks rather than building compressor fleets from origin. For Investors and Strategic Acquirers: Regional nitrogen supply contractors with closed-loop recovery architectures represent priority acquisition archetypes for portfolio exposure to EPA compliance-driven retrofit cycles. Long-term viability hinges on methane regulation stringency trajectory across North American shale basins. Monitor state-level rule layering in Texas and New Mexico as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Nitrogen Recovery Deployment | EPA methane rules in the Permian Basin mandate sealed bearing assemblies and pressure relief circuit retrofits. |
| Pulsed-Air Technology Licensing | Intermittent pressure wave systems cut nitrogen consumption for pressure-depleted shale operators in West Texas. |
| API 7-1 Certification Investment | Material grade verification capabilities unlock custom hammer geometry orders from Saudi Aramco carbonate drilling programs. |
| Digital Diagnostics Platform Integration | Real-time telemetry paired with predictive algorithms extends contract duration for Schlumberger-style service models. |
| Regional Nitrogen Logistics Partnership | Cross-border supply chains between Calgary and Midland-Odessa capture unbundled contract volume from private equity-backed operators. |
Methodological Framework
Desk research of trade customs data, API certification registries, and EPA enforcement disclosures preceded structured interviews with drilling contractors, compressor fleet managers, nitrogen supply specialists, and aftermarket service heads. Primary fieldwork across Permian Basin operations and Dhahran engineering centers validated equipment specification trends. Secondary triangulation incorporated SEC filings from integrated service providers, OSHA silica exposure enforcement records, and state-level methane rule dockets. Bottom-up rig count modeling converged with top-down value chain revenue estimates.
Fixed assumptions held EPA methane monitoring rules and OSHA respiratory protection standards constant across the modeling period, while varying nitrogen price volatility and lateral length extension rates. Segmentation dimensions included well geometry type, application setting, technology category, and end-user procurement structure. CAGRs derived from equipment deployment trajectories and consumables expenditure patterns. Forecast inputs incorporated compressor fleet age profiles and pressure-depletion curves in unconventional shale basins.
The forecast holds incumbent behavior within observed patterns; aggressive moves by independent nitrogen providers or pulsed-air technology specialists would shift outcomes through accelerated unbundling or substitution dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Copper Mining Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Algeria Oil and Gas Upstream Market