
 Soft Capsules Drugs Market | 2026-2036
Soft Capsules Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Capsules Drugs Market Insights
Specialty nutraceutical buyers are unwinding share from traditional OTC purchasers as preventive health spending accelerates. Lonza leverages its integrated gelatin-to-finished-dose capability across Swiss and North American sites. Catalent Inc. anchors high-volume pharmaceutical softgel production for prescription antidepressant and antihistamine programs. Sirio Pharma Co. Ltd. dominates Asia-Pacific contract manufacturing with dedicated softgel capacity in China.
Soft capsules drugs are oral dosage forms comprising active pharmaceutical or nutraceutical ingredients dissolved or suspended in liquid or semi-solid fill, enclosed within a gelatin or plant-based shell that dissolves in gastric fluid to release contents. The shell typically contains gelatin, plasticizers such as glycerin or sorbitol, and optional colorants, with fill formulations ranging from oils to self-emulsifying drug delivery systems designed to enhance bioavailability of poorly water-soluble compounds. Vitamins and omega-3 fatty acid segments lead volume as consumers self-direct preventive supplementation, while curcumin and coenzyme Q10 active ingredients command premium positioning due to complex stability requirements and limited qualified suppliers. Direct sales and e-commerce distribution channels are expanding fastest as brand owners bypass wholesale markups, though hospital and pharmacy end users retain leverage in regulated prescription categories.
FDA cGMP regulations and EMA's ICH Q3D elemental impurity guidelines shape softgel manufacturing standards, with USP dissolution testing protocols further defining product release criteria. India's CDSCO and BIS standards govern import quality for multinational softgel entrants targeting domestic pharmacy chains. Stakeholders must monitor plant-based shell substitution timelines as consumer preference shifts and gelatin supply volatility intersect with regulatory acceptance pathways.
Market Dynamics
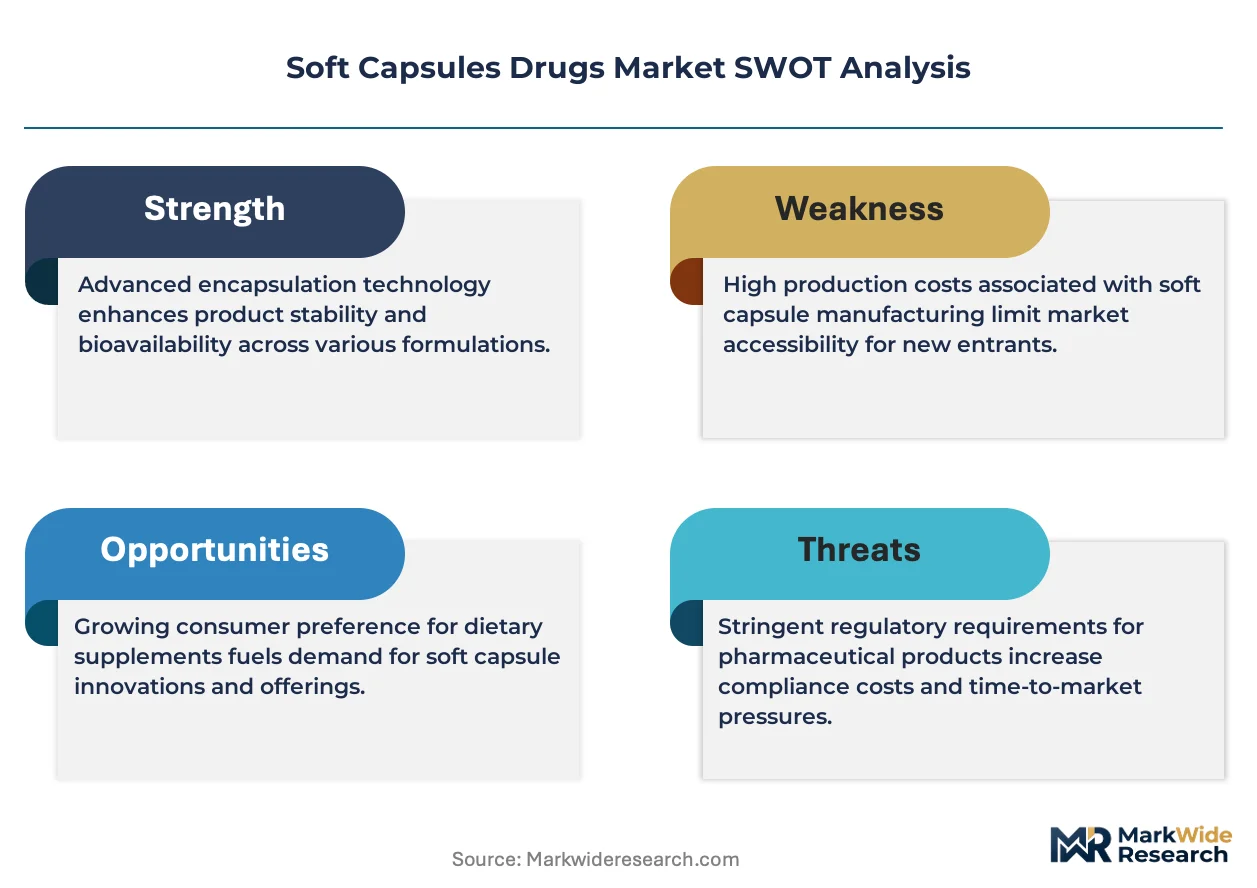
Plant-based shell substitution is fragmenting gelatin supply chains as nutraceutical brands accelerate vegan capsule launches ahead of regulatory acceptance curves, forcing contract manufacturers to dual-qualify gelatin and hydroxypropyl methylcellulose (HPMC) production lines.
Growth Catalysts
- FDA cGMP enforcement escalation:Elevated inspection frequency for dietary supplement manufacturers is consolidating demand toward large-scale contract development and manufacturing organizations with validated quality systems.
- Omega-3 cardiovascular protocols:Cardiology clinics in Germany and Japan are prescribing high-concentration EPA/DHA softgels as adjunctive therapy, expanding prescription-grade volume beyond traditional OTC channels.
- Self-emulsifying drug delivery systems (SEDDS):Formulation advances are enabling bioavailability enhancement for poorly soluble APIs, opening softgel applications to oncology and immunology pipelines previously restricted to parenteral delivery.
Market Restraints
- Gelatin price volatility:Bovine and porcine raw material costs fluctuate with livestock feed grain markets and religious slaughter certification availability, compressing margin predictability for high-volume vitamin producers.
- Shell substitution technical barriers:HPMC and pullulan alternatives exhibit slower dissolution profiles and higher oxygen permeability than gelatin, limiting their deployment for oxidation-sensitive actives like astaxanthin and certain probiotic oils.
- EMA ICH Q3D compliance costs:Elemental impurity testing requirements for cadmium, lead, and arsenic are extending batch release timelines and requiring capital investment in inductively coupled plasma mass spectrometry instrumentation.
Strategic Opportunities
- India pharmacy chain consolidation:Organized retail expansion by Apollo Pharmacy and MedPlus is creating demand for branded softgel generics with consistent supply security that fragmented local manufacturers cannot match.
- Swissmedic fast-track pathways:Switzerland's abbreviated approval routes for well-characterized nutraceutical ingredients are attracting softgel innovators seeking earlier European market entry than centralized EMA procedures permit.
- Direct-to-consumer subscription models:Personalized vitamin platforms using algorithmic dosing recommendations are bypassing wholesale distribution, capturing recurring revenue with higher lifetime value than retail replenishment cycles.
Industry Challenges
- Formulation scientist scarcity:Expertise in lipid-based drug delivery systems and shell-plasticizer compatibility matrices is concentrated among retiring cohorts, constraining R&D throughput for complex softgel programs.
- Cross-contamination validation:Multi-product softgel facilities face extended cleaning validation protocols when switching between allergen-containing and allergen-free fills, reducing effective line utilization rates.
- Legacy ERP integration:Paper-based batch records and isolated manufacturing execution systems impede real-time release testing automation, delaying adoption of continuous manufacturing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Capsules Drugs Market |
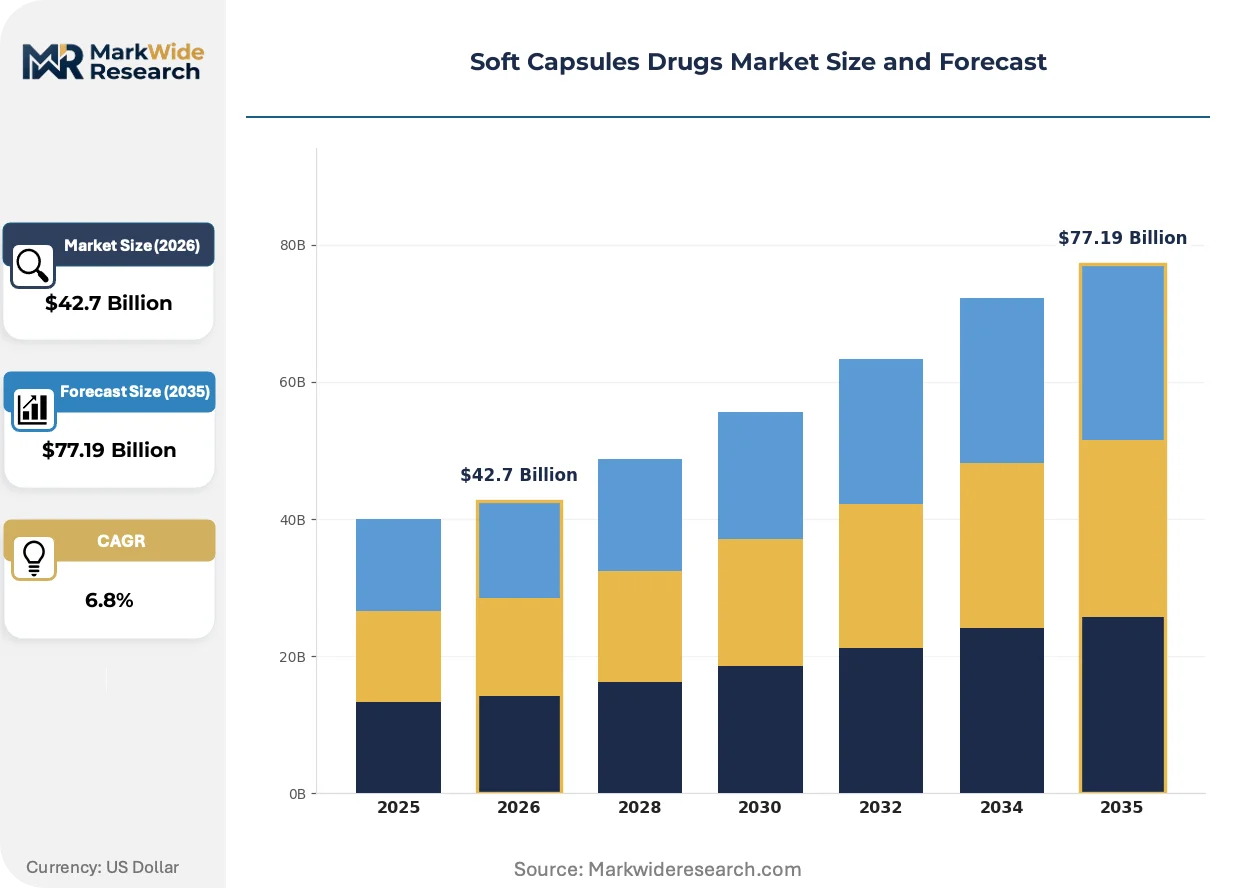
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Antidepressants, Antihistamines, NSAIDs Active Ingredient: Omega-3 Fatty Acids, Curcumin, Coenzyme Q10, Melatonin End User: Pharmacies, Hospitals, Clinics, Online Retailers Distribution Channel: Direct Sales, E-commerce, Wholesalers, Retail Stores |
| Companies Covered | Catalent Inc., Lonza, Sirio Pharma Co. Ltd., Aenova Group, Captek Softgel International Inc., Fuji Capsule Co. Ltd., EuroCaps Ltd., Soft Gel Technologies Inc., Hunan Er Kang Pharmaceutical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Capsules Drugs Market Trends and Innovations
Softgel manufacturing is pivoting from batch-oriented processing toward continuous production architectures, with digital twin deployment and real-time release testing compressing cycle times while regulatory frameworks scramble to accommodate post-approval change management for novel shell polymers.
Enteric-coated softgel technologies are fragmenting the traditional immediate-release dominance in prescription categories. Pumps and coating systems enabling targeted intestinal release are attracting investment from pain management and psychiatric drug developers seeking to bypass gastric degradation or reduce nausea side effects. European CDMOs are retrofitting existing gelatin lines with aqueous coating capabilities, while Asian manufacturers pursue integrated enteric solutions from greenfield sites.
REACH restrictions on certain phthalate plasticizers are accelerating migration toward citrate esters and triacetin alternatives in European manufacturing. The substitution cascade is forcing reformulation of legacy products with decades of stability data, creating temporary supply interruptions as suppliers revalidate dissolution profiles. German and Swiss contract manufacturers are leading this transition, leveraging proximity to EMA scientific advice pathways for rapid regulatory alignment.
Specialty pharmacy channels are displacing traditional hospital procurement for high-value softgel prescriptions. Payers in the United States are steering oral oncology and immunology therapies toward limited-distribution networks with enhanced patient adherence monitoring. This channel compression is elevating requirements for cold-chain distribution integrity and tamper-evident packaging, particularly for temperature-sensitive lipid nanoparticle fills targeting lymphatic absorption pathways.
Soft Capsules Drugs Market Segmentation
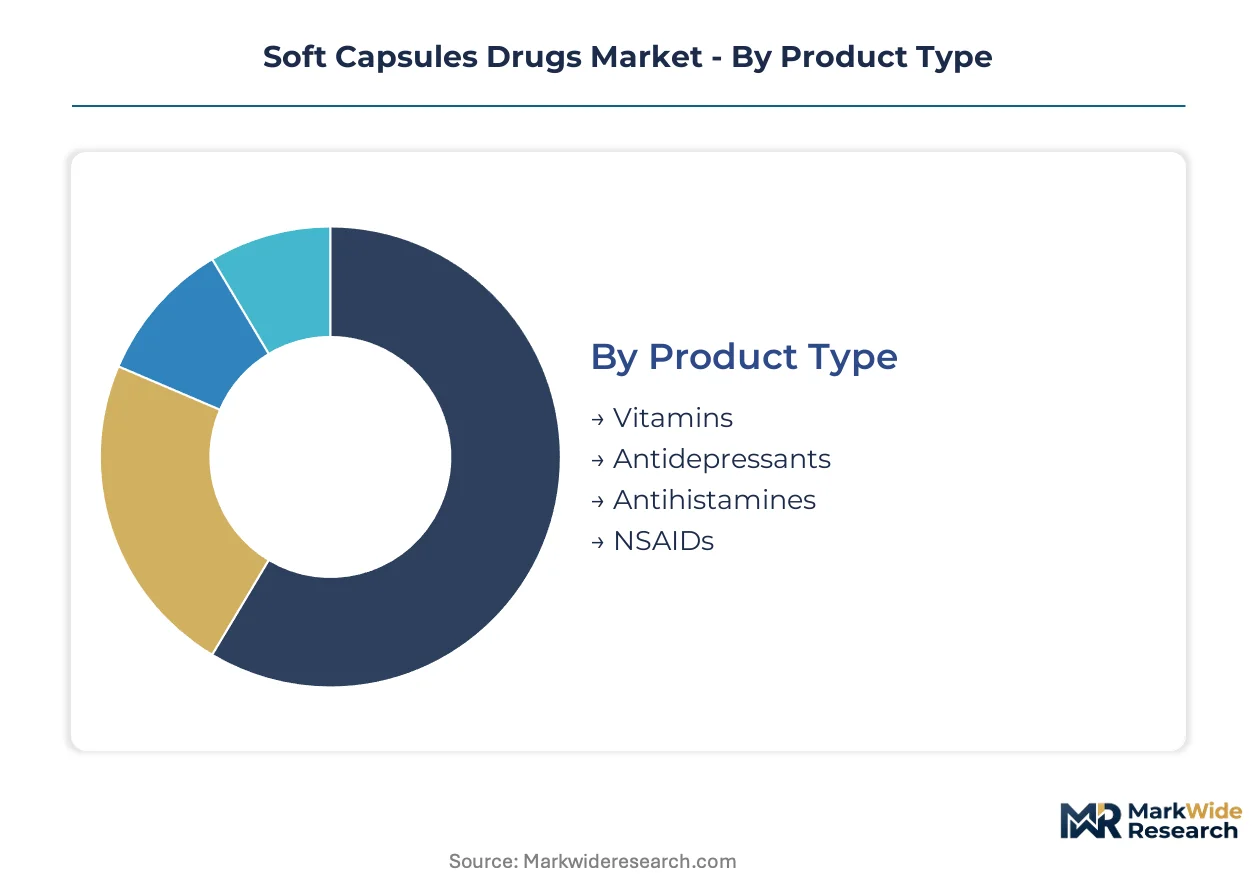
Soft capsule segmentation reveals divergent margin structures across nutraceutical and pharmaceutical applications, with formulation complexity and regulatory intensity determining profitability tiers. Manufacturers prioritize segments where lipid-based delivery systems command premium pricing over commodity vitamin fills.
Product Type:
Highest margins concentrate in prescription antidepressant and antihistamine softgels where formulation stability requirements and regulatory validation create supplier stickiness, while vitamin softgels compete on scale economies with thinner unit economics.
- Vitamins:Multivitamin and single-nutrient softgels dominate volume through preventive health self-prescribing, with demand clustering in United States direct-to-consumer channels as subscription platforms displace retail replenishment cycles.
- Antidepressants:Prescription SSRI and SNRI softgel formulations leverage SEDDS technology for bioavailability enhancement, with German and Japanese psychiatrists prescribing these as first-line oral options where gastric tolerability concerns arise.
- Antihistamines:Second-generation H1 antagonist softgels serve pediatric and geriatric populations requiring swallowing ease, with hospital formularies in Switzerland and Austria driving adoption for perioperative allergy management.
- NSAIDs:Ibuprofen and diclofenac softgel variants target rapid onset pain relief segments, with limited prescription penetration due to established tablet dominance in acute care settings.
The dominant share belongs to Vitamins, while Antidepressants is closing the gap fastest.
Active Ingredient:
Ingredient selection determines technical barriers to entry, with oxidation-sensitive actives requiring specialized shell formulations and nitrogen-blanketed manufacturing that filters out undercapitalized competitors.
- Omega-3 Fatty Acids:EPA and DHA concentrates from marine and algal sources constitute the largest volume category, with cardiovascular wellness protocols in German cardiology clinics expanding prescription-grade demand beyond traditional OTC positioning.
- Curcumin:Lipid-encapsulated turmeric extracts command premium positioning due to limited qualified suppliers and complex stability requirements, with United States functional medicine practitioners driving clinical-grade adoption.
- Coenzyme Q10:Ubiquinone and ubiquinol softgels serve statin-associated myopathy and heart failure adjuvant therapy niches, with Japanese manufacturers holding formulation expertise advantages.
- Melatonin:Extended-release and immediate-release variants target sleep disorder segments, with regulatory classification as dietary supplement in United States versus prescription drug in other markets creating channel fragmentation.
Omega-3 Fatty Acids retains volume leadership, though Curcumin exhibits the steepest expansion trajectory as clinical validation accumulates.
End User:
Channel power dynamics shift procurement leverage, with consolidated pharmacy chains extracting supply security commitments while hospital systems prioritize formulary standardization over price minimization.
- Pharmacies:Retail and specialty pharmacy networks handle the majority of prescription softgel dispensing, with United States limited-distribution networks for oncology softgels elevating cold-chain and adherence monitoring requirements.
- Hospitals:Inpatient and outpatient departments source through group purchasing organizations, with formulary committees in Japan and Germany evaluating SEDDS-enabled softgels for bioavailability-critical therapies.
- Clinics:Cardiology and psychiatric practices prescribe high-concentration omega-3 and antidepressant softgels directly, bypassing retail pharmacy markups in integrated delivery systems.
- Online Retailers:Direct-to-consumer platforms and marketplace sellers capture preventive supplementation demand, with algorithmic personalization engines capturing recurring revenue at lifetime values exceeding retail replenishment cycles.
Pharmacies maintains institutional dominance, yet Online Retailers is gaining share fastest as brand owners bypass wholesale distribution layers.
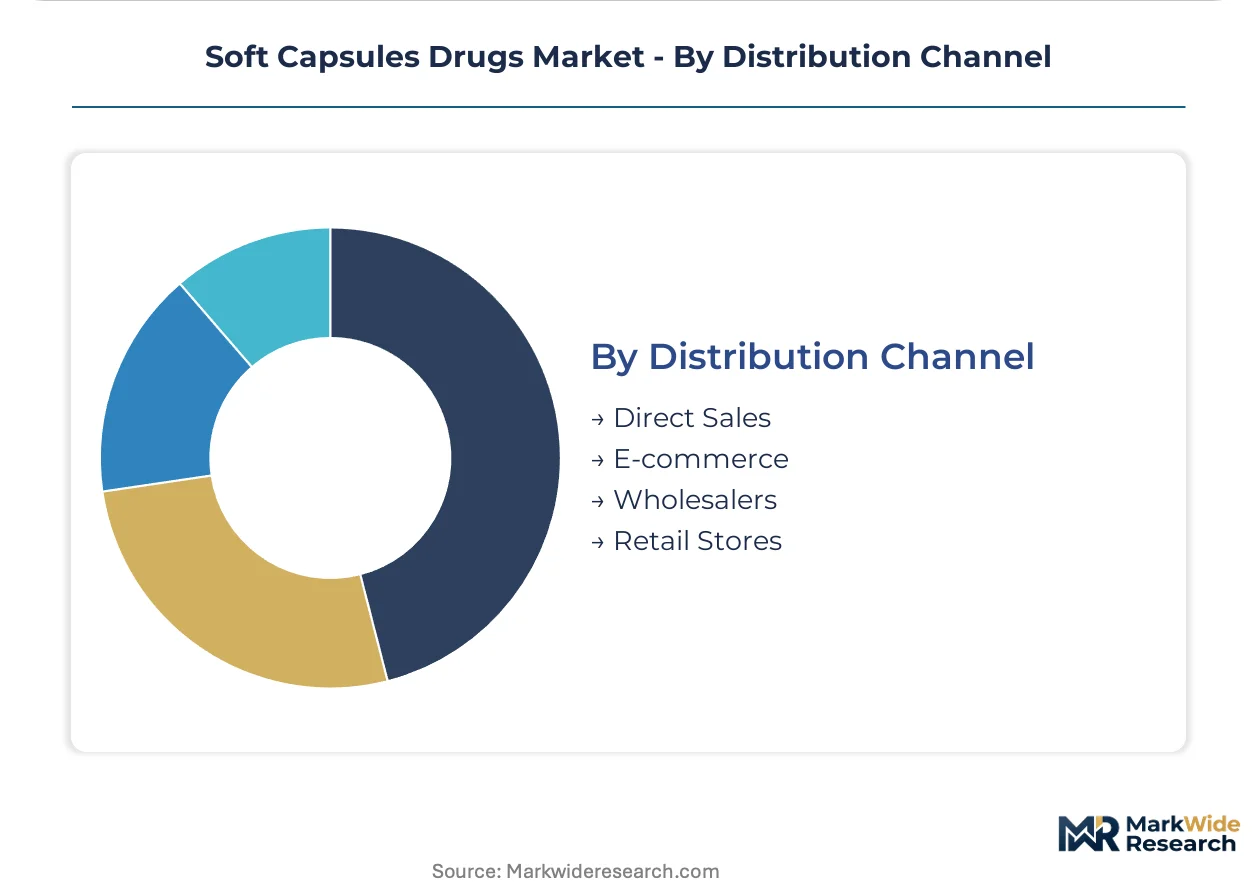
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with direct engagement enabling subscription economics while wholesale relationships provide geographic reach at margin sacrifice.
- Direct Sales:Manufacturer-to-consumer relationships through owned digital properties enable algorithmic dosing personalization and recurring revenue models, with United States nutraceutical brands investing in retention analytics infrastructure.
- E-commerce:Third-party marketplace and platform sales expand reach without inventory ownership, though price transparency intensifies competitive pressure on legacy brands.
- Wholesalers:Regional and national distributors retain relevance for hospital and pharmacy procurement, with consolidated buying power in Germany and Japan compressing supplier margins.
- Retail Stores:Mass merchandisers and health food chains provide impulse purchase visibility for vitamin softgels, with shelf space allocation favoring private label and national brand blockbusters over niche entrants.
Direct Sales commands the highest margin per unit, while E-commerce is expanding most quickly as digital-native brands capture preventive health spending acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preventive health buyers concentrate in high-income economies with established nutraceutical retail infrastructure and reimbursement pathways for prescription lipid-based therapies. Cardiology clinics and direct-to-consumer subscription platforms are pulling volume toward specific metropolitan clusters.
United States
Direct-to-consumer vitamin subscriptions and specialty pharmacy networks for oncology softgels drive demand concentration. FDA cGMP enforcement escalation favors large-scale contract manufacturers with validated quality systems. Boston and Research Triangle Park host formulation development clusters serving SEDDS-enabled antidepressant programs.
Germany
Cardiology clinics prescribe high-concentration EPA/DHA softgels as adjunctive cardiovascular therapy. EMA ICH Q3D elemental impurity guidelines extend batch release timelines for domestic manufacturers. Bavaria anchors pharmaceutical softgel production with integrated gelatin-to-finished-dose capabilities.
Japan
Geriatric populations requiring swallowing-ease dosage forms sustain antihistamine and CoQ10 softgel demand. PMDA maintains stringent stability requirements for oxidation-sensitive lipid fills. Osaka and Tokyo metropolitan areas concentrate formulation expertise for ubiquinol and omega-3 concentrates.
China
Domestic pharmacy chain consolidation by organized retailers creates demand for branded softgel generics with supply security. NMPA oversees import quality standards for multinational entrants targeting hospital formularies. Zhejiang and Jiangsu provinces host dedicated softgel contract manufacturing capacity.
Switzerland
Swissmedic fast-track pathways attract nutraceutical innovators seeking earlier European market entry. REACH restrictions on phthalate plasticizers accelerate citrate ester migration in regional manufacturing. Basel and Zurich clusters leverage proximity to EMA scientific advice for rapid regulatory alignment.
Soft Capsules Drugs Market Competitive Landscape
Player mix skews toward integrated contract development and manufacturing organizations with captive gelatin supply and validated pharmaceutical quality systems. Tiered competitive structure separates premium prescription-grade specialists from high-volume nutraceutical commodity producers. Strategic archetypes include integrated gelatin-to-finished-dose operators, pure-play softgel contract manufacturers, and diversified pharmaceutical CDMOs with softgel divisions. Dominant competitive moves encompass dual-qualification of gelatin and HPMC production lines, plus geographic expansion into Swissmedic and PMDA regulatory jurisdictions.
Within the integrated CDMO tier, Catalent Inc. and Lonza exemplify scale-driven operators with North American and European manufacturing footprints. Sirio Pharma Co. Ltd. occupies a position among Asia-Pacific contract manufacturers with dedicated regional capacity. These three entities represent contrasting strategic archetypes: pharmaceutical prescription-grade validation, nutraceutical gelatin integration, and Asia-Pacific volume manufacturing respectively.
| Leading Market Players |
|---|
| Catalent Inc. |
| Lonza |
| Sirio Pharma Co. Ltd. |
| Aenova Group |
| Captek Softgel International Inc. |
| Fuji Capsule Co. Ltd. |
| EuroCaps Ltd. |
| Soft Gel Technologies Inc. |
| Hunan Er Kang Pharmaceutical Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at large-scale softgel contract manufacturing organizations shapes both supply concentration and price floors, as FDA cGMP enforcement escalation filters out sub-scale competitors and consolidates volume toward validated quality systems in the United States and Germany.
Pricing Analysis
Cost-plus contracts with gelatin raw material indexation dominate procurement between vitamin brand owners and contract manufacturers, insulating suppliers from bovine and porcine feed grain volatility while passing base cost movements through to buyers. Three-tier pricing structure across prescription-grade, clinical nutraceutical, and commodity vitamin levels separates SEDDS-enabled antidepressant formulations from standard omega-3 fills. Pricing pressure stems from consolidated pharmacy chain buying power in Germany and Japan extracting supply security commitments at margin compression. Direct-to-consumer subscription platforms exhibit lowest price sensitivity due to algorithmic personalization stickiness, while mass-market retail vitamin buyers drive hardest bargain.
Supply Chain Analysis
Strategic stockpiling of gelatin and plasticizer inventories prevails over just-in-time approaches, as livestock feed grain volatility and religious slaughter certification availability create raw material uncertainty that manufacturers buffer through forward purchasing. Supply concentrates in China, India, and Switzerland, with Zhejiang and Jiangsu provinces hosting dedicated softgel capacity, Bavaria anchoring integrated gelatin-to-finished-dose operations, and Swiss sites leveraging EMA proximity. Production draws from bovine-derived gelatin, hydroxypropyl methylcellulose alternatives, and citrate ester plasticizers migrating from restricted phthalates. Single-source vulnerability in qualified SEDDS formulation scientists constrains R&D throughput. Distribution runs through direct-to-consumer platforms, specialty pharmacy networks, and consolidated wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmacy chains and direct-to-consumer platforms, as Apollo Pharmacy and MedPlus in India plus algorithmic vitamin subscriptions in the United States fragment procurement leverage away from fragmented traditional retailers.
For Market Incumbents: Fortify quality system validation investments to capture FDA cGMP enforcement consolidation, while securing captive gelatin supply through backward integration into bovine raw material sourcing or long-term offtake agreements with certified slaughterhouses. Plant-based shell substitution by nutraceutical brands threatens traditional gelatin-dependent revenue streams; dual-qualification of HPMC production lines preserves optionality. Capacity addition in Swissmedic jurisdictions captures fast-track regulatory pathway premiums. For New Entrants and Emerging Players: Lead with SEDDS formulation capabilities targeting oncology and immunology pipelines previously restricted to parenteral delivery, where lipid-based bioavailability enhancement commands specialist premiums. Swiss nutraceutical innovators seeking abbreviated approval routes represent the most penetrable client segment. Go-to-market positioning as regulatory navigation partners rather than commodity manufacturers differentiates against established CDMOs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated operators with captive gelatin supply and validated pharmaceutical quality systems over pure-play nutraceutical commodity producers. Five-to-ten year viability hinges on successful plant-based shell substitution timelines intersecting with regulatory acceptance curves. Acquisition target archetype: mid-scale CDMOs with SEDDS expertise and Swiss or Japanese regulatory footholds. Signal to watch: FDA publication of HPMC shell dissolution equivalence guidance as inflection indicator for substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Qualification of HPMC Production Lines | Preserves revenue optionality as nutraceutical brands accelerate vegan capsule launches ahead of regulatory curves. |
| SEDDS Formulation Capability Investment | Opens softgel applications to oncology pipelines previously restricted to parenteral delivery routes. |
| Swissmedic Fast-Track Regulatory Positioning | Captures abbreviated approval premiums for well-characterized nutraceutical ingredients entering European markets. |
| Direct-to-Consumer Subscription Infrastructure | Bypasses wholesale markups while capturing recurring revenue at lifetime values exceeding retail cycles. |
| Citrate Ester Plasticizer Migration | Aligns European manufacturing with REACH restrictions while maintaining dissolution profile equivalence. |
Research Methodology
A spread of perspectives from softgel formulation scientists, contract manufacturing executives, pharmacy procurement directors, and regulatory affairs specialists converged on the working assumptions underlying demand projections. Primary interviews with these stakeholders combined with secondary validation against FDA cGMP inspection records, EMA scientific advice pathways, Swissmedic approval databases, and NMPA import quality standards. Bottom-up capacity and utilization estimates triangulated against top-down preventive health spending trends.
Segmentation dimensions modeled span product type, active ingredient stability requirements, end-user channel power dynamics, and distribution format across the analysis window. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory enforcement intensity and substitution technology adoption curves. Forecast inputs incorporated cardiology clinic prescribing patterns for EPA/DHA protocols, direct-to-consumer subscription platform growth rates, and plant-based shell polymer regulatory acceptance timelines.
Forecasts assume regulatory continuity in FDA cGMP enforcement, EMA ICH Q3D elemental impurity guidelines, and Swissmedic fast-track pathways; material policy shifts would require re-modeling. Specific risks include gelatin supply disruption from livestock disease outbreaks, HPMC dissolution profile non-equivalence determinations, and SEDDS formulation scientist scarcity constraining R&D throughput. Revision becomes warranted when plant-based shell regulatory acceptance crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Vaginitis Therapeutics Market