
 Engineered Stone Market | 2026-2036
Engineered Stone Market Size, Share, and Industry Trends Forecast 2026-2036
Engineered Stone Market Intelligence
NSF/ANSI 51 certification for food equipment materials is reorganizing competitive tiers among engineered stone producers. Cosentino S.A. leverages integrated quartz manufacturing across Spain and the United States to sustain premium positioning. Caesarstone Ltd. anchors its position through Israeli production bases with strong North American distribution. Cambria competes as a fully domestic American manufacturer with captive supply chains and color innovation pipelines.
Engineered stone comprises crushed natural stone aggregates bound with polymer resins under vacuum and vibration, yielding slabs with controlled porosity below 0.5 percent and flexural strength exceeding 25 MPa. The material serves architects and fabricators seeking consistent aesthetics with reduced maintenance versus natural stone. Quartz dominates product type volumes due to superior hardness and stain resistance for countertop applications. Residential end users generate the deepest margin pools, while hospitality projects drive specification-grade volume for flooring and wall cladding segments. Direct sales and showroom channels capture the highest-value transactions through fabricator relationships.
The U.S. Occupational Safety and Health Administration enforces permissible exposure limits on respirable crystalline silica that directly shape wet-cutting mandates and fabrication shop compliance investments. The EU REACH regulation and associated ECHA guidance classify certain silica fractions as substances of very high concern, forcing reformulation toward lower-silica engineered stone compositions. China's GB standards for building materials and the Ministry of Ecology and Environment's emission controls govern domestic manufacturing scale. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate product line restructuring and regional sourcing reconfigurations.
Market Dynamics
The engineered stone sector faces a structural pivot as crystalline silica regulations force reformulation investments while residential renovation demand concentrates in China's tier-one cities and US metropolitan corridors.
Growth Catalysts
- REACH SVHC classification:The EU's designation of respirable silica as a substance of very high concern is accelerating manufacturer investment in low-silica resin formulations and wet-processing infrastructure.
- Residential kitchen renovation cycles:North American homeowners are prioritizing countertop replacement over full kitchen remodels, directing volume toward quartz surfacing with NSF/ANSI 51 certification.
- Polymer resin bonding advances:Vacuum vibration compression technology is achieving sub-0.5% porosity thresholds that satisfy hospitality specification standards for flooring and wall cladding.
Market Restraints
- Petrochemical resin cost volatility:Polyester and epoxy resin feedstock prices fluctuate with crude oil derivatives, compressing margin predictability for slab producers.
- Fabrication shop concentration:Wet-cutting compliance investments are consolidating independent fabricators in the United States, creating distribution bottlenecks for regional slab distributors.
- Porcelain slab substitution:Sintered stone alternatives with zero silica content are capturing specification-grade projects where LEED points and indoor air quality certifications drive material selection.
Strategic Opportunities
- India urban residential construction:Metro rail corridor expansion in Mumbai, Delhi, and Bangalore is generating mid-rise housing stock with standardized kitchen specifications receptive to engineered stone.
- GB standard alignment:China's Ministry of Ecology and Environment emission controls are creating first-mover advantage for domestic producers achieving dual compliance with export-market silica thresholds.
- Direct-to-fabricator digital platforms:Slab selection and templating software is compressing the specification cycle for residential contractors bypassing traditional showroom intermediaries.
Industry Challenges
- Respirable silica monitoring expertise:Fabrication shops lack industrial hygienists capable of implementing OSHA-compliant exposure assessment protocols and engineering control validation.
- Multi-jurisdiction certification timelines:NSF/ANSI 51, CE marking, and GB standard testing sequences extend product launch windows by 8-14 months for global portfolio consistency.
- Legacy natural stone fabricator conversion:Granite and marble shops face capital barriers in retrofitting wet-cutting infrastructure and dust collection systems for engineered stone compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineered Stone Market |
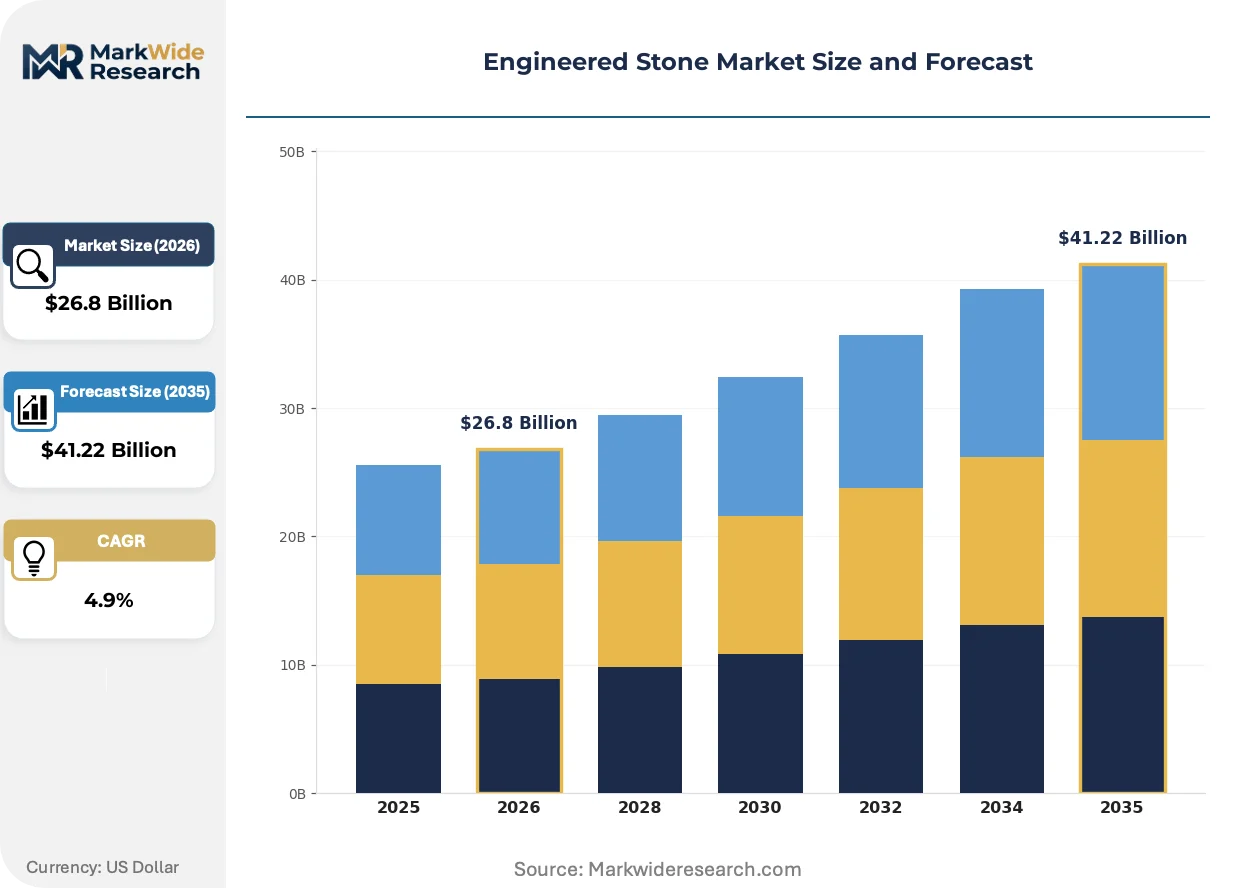
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $41.22 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz, Marble, Granite, Onyx End User: Residential, Commercial, Industrial, Hospitality Application: Countertops, Flooring, Wall Cladding, Sinks Distribution Channel: Direct Sales, Online Retail, Distributors, Showrooms |
| Companies Covered | Cosentino S.A., Caesarstone Ltd., LX Hausys, Technistone A.S., VICOSTONE, Cambria, Johnson Marble & Quartz, Quarella Group Ltd., Belenco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineered Stone Market Strategic Shifts & Innovations
Silica-free formulation chemistry and digital templating workflows are restructuring competitive advantage across the engineered stone value chain, separating compliance-ready producers from legacy operators.
Bio-based resin binders derived from agricultural waste streams are decomposing the petroleum dependency of conventional polyester formulations. European kitchen manufacturers are piloting these materials for CE-marked surfacing. This transition is compressing the cost premium between sustainable and conventional engineered stone to under 15% at slab scale.
REACH authorization requirements for crystalline silica are mandating closed-loop water recycling in fabrication facilities. The European Chemicals Agency guidance documents are forcing capital redeployment toward wet-processing infrastructure. Italian and Spanish producers with integrated fabrication networks are absorbing compliance costs more efficiently than import-dependent distributors.
Homeowner specification behavior is fragmenting across generational lines. Millennial buyers prioritize NSF-certified antimicrobial surfaces through direct online research, compressing the influence of kitchen showrooms and contractor recommendations. This pattern concentrates in US coastal metropolitan markets where renovation spending exceeds new construction volumes.
Engineered Stone Market Segmentation
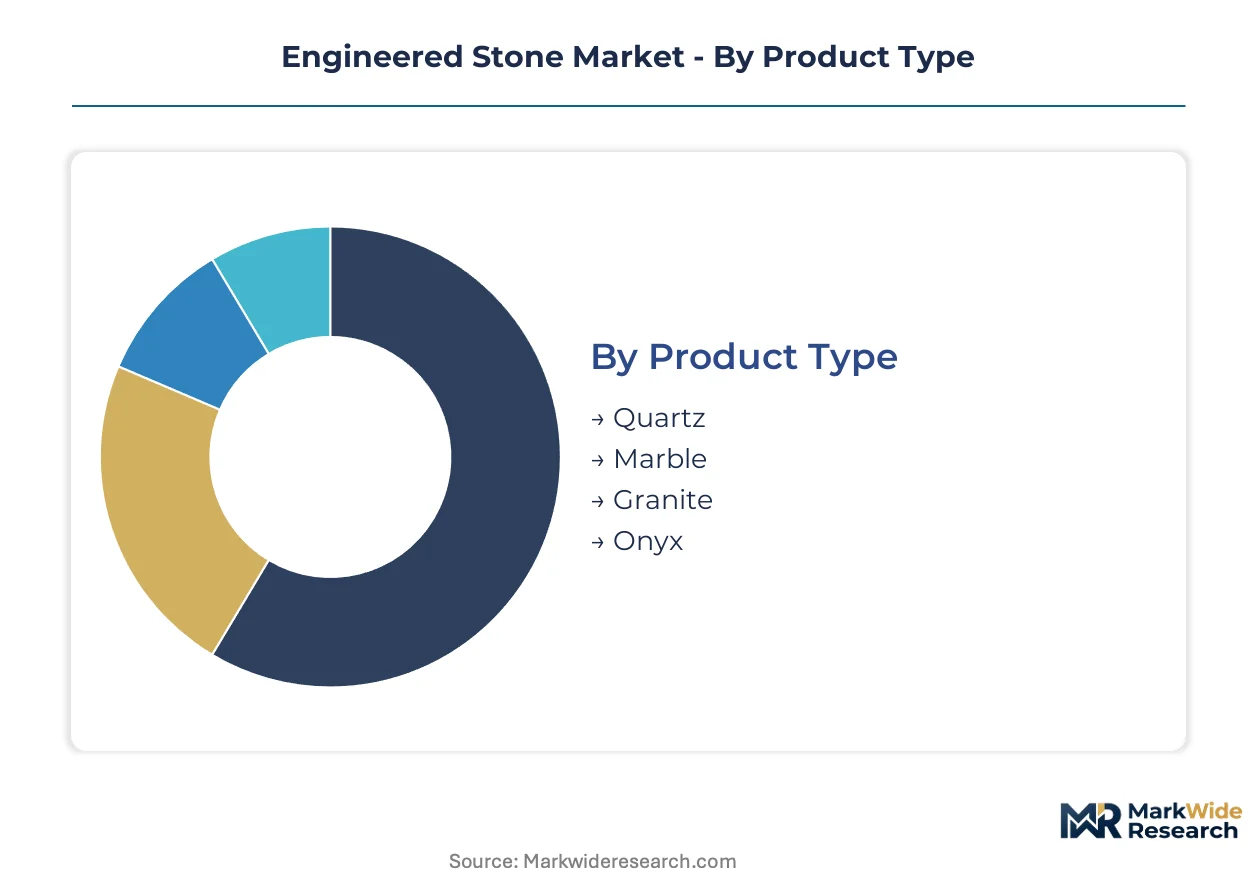
Engineered stone segmentation determines margin capture through channel specialization and specification-grade certification requirements. Product type and application pairings dictate whether volume flows through fabricator networks or direct-to-contractor platforms.
Product Type:
Quartz and marble variants route through showroom and direct sales channels for residential kitchen specification, while granite and onyx grades concentrate in distributor networks serving commercial projects.
- Quartz:Crushed quartz aggregates bound with polyester resin achieve Mohs hardness of 7 and sub-0.5% porosity. Residential renovation spending in China's tier-one cities and US metropolitan corridors drives specification for NSF/ANSI 51-certified kitchen countertops. REACH SVHC classification on respirable silica is accelerating wet-processing compliance investments among quartz slab producers.
- Marble:Engineered marble combines calcium carbonate fillers with resin binders to replicate veining aesthetics with superior flexural strength exceeding 25 MPa. Hospitality flooring and wall cladding projects in India's metro rail corridor cities specify marble-look engineered stone for consistent batch coloring versus natural stone variation. ECHA guidance on crystalline silica exposure is forcing reformulation toward lower-calcite compositions.
- Granite:Granite-aggregate engineered stone serves commercial countertop applications through distributor channels with standard color palettes.
- Onyx:Translucent resin formulations with backlit installation capability target premium residential vanity and feature wall segments.
Quartz dominates installed base. Marble is where expansion concentrates for hospitality specification.
End User:
Cost tier stratification separates premium residential specification from volume commercial procurement, with hospitality representing a distinct margin pool for LEED-certified projects.
- Residential:Homeowners generate the deepest margin pools through showroom-direct specification of certified antimicrobial surfaces. Millennial buyers in US coastal metropolitan markets compress the contractor influence cycle through online research and digital templating platforms. OSHA-compliant wet-cutting mandates shape fabricator network consolidation for residential installation.
- Commercial:Office and retail fit-out projects standardize on mid-tier quartz grades through distributor procurement with volume pricing. China's GB standards for building materials govern domestic commercial specification, while export-oriented producers dual-certify for CE marking. MEE emission controls create compliance barriers for non-integrated producers.
- Industrial:Laboratory and food-service surfaces require NSF/ANSI 51 certification with chemical resistance specifications.
- Hospitality:Hotel and resort projects drive specification-grade volume for flooring and wall cladding with batch consistency requirements.
Residential commands margin premiums. Commercial delivers volume scale.
Application:
Application type determines fabrication complexity and channel margin structure, with vertical surfaces requiring templating precision versus horizontal surface standardization.
- Countertops:Horizontal surface applications dominate engineered stone consumption with standardized slab dimensions and edge profiling. US metropolitan renovation cycles prioritize countertop replacement over full kitchen remodels, directing volume toward quartz surfacing with rapid templating turnaround. Porcelain slab substitution threatens specification-grade countertop projects where zero-silica content drives LEED point accumulation.
- Flooring:Large-format slab installation requires specification-grade flexural strength and slip resistance certification. Hospitality projects in India's urban residential construction corridors specify engineered stone flooring for durability versus natural marble maintenance requirements. Vacuum vibration compression technology achieves the sub-0.5% porosity thresholds that satisfy flooring specification standards.
- Wall Cladding:Vertical surface applications emphasize lightweight substrate compatibility and adhesive bonding performance.
- Sinks:Integrated basin fabrication demands thermoforming capability and seamless joint finishing.
Countertops anchor volume demand. Flooring is climbing the fastest for hospitality specification.
Distribution Channel:
Channel selection reflects customer specification behavior fragmentation, with digital platforms compressing traditional showroom intermediaries in coastal metropolitan markets.
- Direct Sales:Fabricator relationships and contractor networks capture highest-value transactions with templating and installation bundling. Italian and Spanish producers with integrated fabrication networks absorb REACH compliance costs more efficiently than import-dependent distributors serving direct sales channels. Millennial specification behavior through online research is compressing the influence of traditional showroom intermediaries.
- Online Retail:Slab selection and templating software platforms enable residential contractors to bypass showroom intermediaries. Direct-to-fabricator digital platforms compress the specification cycle for standardized kitchen configurations in China's tier-one cities. Bio-based resin binder pilots for CE-marked surfacing are decomposing petroleum dependency through online sustainability positioning.
- Distributors:Regional slab distributors face consolidation pressure from wet-cutting compliance investments and independent fabricator concentration.
- Showrooms:Physical display channels retain influence in generational segments prioritizing tactile material evaluation.
Direct Sales commands premium positioning. Online Retail is gaining share fastest among millennial specification segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH SVHC classification on respirable silica is forcing reformulation investments across manufacturing jurisdictions. Regulatory divergence between the EU, United States, and China is reshaping regional sourcing strategies. Fabrication compliance costs are concentrating production among integrated producers with captive wet-processing infrastructure.
United States
Metropolitan renovation corridors in New York, Los Angeles, and Chicago are driving quartz countertop specification through NSF/ANSI 51-certified fabricator networks. OSHA enforces permissible exposure limits on respirable crystalline silica that mandate wet-cutting infrastructure investments. Cambria anchors domestic manufacturing with captive Minnesota production serving premium residential segments.
China
Tier-one cities including Shanghai, Beijing, and Shenzhen are concentrating urban residential construction demand for engineered stone kitchen surfaces. MEE emission controls and GB standards for building materials govern domestic manufacturing scale. Yangtze River Delta producers are achieving dual compliance with export-market silica thresholds for European and North American shipment.
Germany
Commercial fit-out projects in Berlin, Munich, and Hamburg standardize on mid-tier quartz grades through distributor procurement networks. ECHA guidance documents under REACH are mandating closed-loop water recycling in fabrication facilities. North Rhine-Westphalia integrated producers are absorbing compliance costs more efficiently than import-dependent distributors.
India
Metro rail corridor expansion in Mumbai, Delhi, and Bangalore is generating mid-rise housing stock with standardized kitchen specifications. BIS standards for building materials create compliance frameworks for domestic engineered stone consumption. Maharashtra and Karnataka fabrication clusters are scaling wet-processing capacity to serve hospitality flooring and wall cladding projects.
Italy
Hospitality specification-grade volume for flooring concentrates in Rome, Milan, and Florence renovation cycles. CE marking requirements and REACH authorization for crystalline silica are forcing capital redeployment toward wet-processing infrastructure. Emilia-Romagna producers with integrated fabrication networks are capturing specification margin through batch consistency guarantees.
Engineered Stone Market Key Industry Players
Player mix skews toward vertically integrated specialists with captive resin formulation and slab production capacity. Market structure concentrates among three to five dominant producers controlling premium certification tiers and direct fabricator relationships. Strategic archetypes separate domestic-captive manufacturers from export-oriented integrated producers and regional distributor-dependent importers. Competitive moves center on low-silica formulation R&D partnerships and wet-processing infrastructure acquisitions to preempt regulatory compliance barriers.
Among premium-tier integrated producers, Cosentino S.A. and Cambria exemplify the domestic-captive archetype with in-house manufacturing and color innovation pipelines. Caesarstone Ltd. occupies a position representing export-oriented production with strong North American distribution architecture. These three companies anchor the competitive structure by demonstrating how regulatory compliance investments and certification maintenance create sustainable positioning against import-dependent distributors facing consolidation pressure from fabrication shop concentration.
| Leading Market Players |
|---|
| Cosentino S.A. |
| Caesarstone Ltd. |
| LX Hausys |
| Technistone A.S. |
| VICOSTONE |
| Cambria |
| Johnson Marble & Quartz |
| Quarella Group Ltd. |
| Belenco |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day resin inventory cycles at European slab producers concentrate pricing power among integrated manufacturers with captive polyester formulation, while independent distributors absorb margin compression from petrochemical feedstock volatility. This lead-time band separates REACH-compliant wet-processing investments from legacy operators facing fabrication shop consolidation.
Pricing Analysis
Certification level (NSF/ANSI 51, CE marking, GB standard) creates the primary spread between premium quartz slabs and commodity-grade engineered stone. Three-tier pricing structure across premium certified, standard export-grade, and economy domestic tiers stratifies margin capture, with REACH SVHC compliance investments intensifying cost compression in the mid-tier segment. Residential contractors through direct sales channels exhibit lowest price sensitivity due to templating bundling, while commercial distributors face acute margin pressure from porcelain slab substitution in LEED-driven specifications.
Supply Chain Analysis
Strategic stockpiling of quartz aggregate and resin binders dominates inventory strategy among Yangtze River Delta producers preparing for dual GB standard and REACH compliance audits. Manufacturing concentrates in China, Spain, and the United States, with raw material dependencies centering on crushed silica aggregates, polyester resins, and vacuum vibration compression equipment. Single-source vulnerability in petrochemical resin feedstocks from crude oil derivatives threatens margin predictability. Distribution runs through fabricator networks and direct-to-contractor digital platforms, with showroom intermediaries losing share to templating software adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among millennial homeowners in US coastal metropolitan markets who compress specification cycles through online research and digital platform adoption, fragmenting traditional showroom influence.
For Market Incumbents: Shield premium positioning by accelerating low-silica formulation R&D partnerships and acquiring wet-processing fabrication capacity in North Rhine-Westphalia or Minnesota to preempt OSHA and REACH compliance barriers. Backward integration into bio-based resin binders decomposes petroleum dependency exposure while capturing sustainability premiums from European kitchen manufacturers.
For New Entrants and Emerging Players: Differentiate on zero-silica sintered stone positioning to capture specification-grade hospitality projects where LEED points and indoor air quality certifications drive material selection. Target India's metro rail corridor cities for mid-rise housing stock with standardized kitchen specifications, leveraging direct-to-fabricator digital platforms to bypass consolidated showroom intermediaries.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance consolidation play because REACH authorization requirements and OSHA wet-cutting mandates are structurally advantaging integrated producers with captive fabrication networks over import-dependent distributors. Acquisition targets cluster among Italian and Spanish producers with batch consistency guarantees and CE-marked surfacing portfolios. Watch for ECHA guidance document revisions on crystalline silica exposure thresholds as the inflection signal for accelerated reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Silica Formulation R&D Partnership | REACH SVHC compliance accelerates wet-processing infrastructure investments among European producers. |
| Wet-Processing Fabrication Acquisition | OSHA exposure limits consolidate independent fabricators, creating captive distribution advantages. |
| Bio-Based Resin Binder Pilot Scale-Up | European kitchen manufacturers drive CE-marked surfacing demand for agricultural waste stream binders. |
| Direct-to-Fabricator Digital Platform Launch | Millennial specification behavior compresses showroom intermediary influence in coastal US markets. |
| Dual GB Standard and REACH Compliance Investment | Yangtze River Delta producers capture first-mover advantage for export-market silica thresholds. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed surfacing producers, ECHA guidance documents, and GB standard technical specifications to validate market sizing and competitive positioning assessments. Interviews with plant managers at integrated slab manufacturers, procurement leads at hospitality developers, distribution channel partners, and technical R&D directors informed supply chain and reformulation investment trajectories. Bottom-up volume modeling across product type and application segments triangulates against top-down macro construction spending indicators.
Segmentation dimensions modeled include product type (quartz, marble, granite, onyx), end user (residential, commercial, hospitality, industrial), application (countertops, flooring, wall cladding, sinks), and distribution channel (direct sales, online retail, distributors, showrooms) across the analysis window. CAGRs derive from regression analysis against urban residential construction permits, renovation spending indices, and regulatory compliance cost curves. Industry-specific forecast inputs incorporate OSHA enforcement intensity scores and REACH authorization timeline probabilities.
The analysis sits within stated boundaries; outcomes outside sustained residential renovation spending in China's tier-one cities and US metropolitan corridors, or absent ECHA crystalline silica reclassification, would require recalibration. Forecasts reflect assumptions on petrochemical resin price stability and fabrication shop consolidation rates. Revision becomes warranted when porcelain slab substitution rates in LEED-certified projects cross thresholds that structurally displace engineered stone specification share.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Dutch Brick Market
Building Materials
China Cement Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
GRC Cladding Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Italy Architectural Coatings Market
Building Materials
India Concrete Admixtures Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Qatar Cement Market
Building Materials
Construction Stone Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
North America Cement Market