
 Europe Medical Devices Market | 2026-2036
Europe Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Devices Market Foresight
German orthopedic implant production is decoupling from legacy stainless steel supply chains as domestic forgers shift to titanium alloy billet. Siemens Healthineers anchors its imaging portfolio through in-house superconducting magnet production. Smith & Nephew leverages advanced wound care polymers to sustain premium positioning across European hospital networks.
Europe medical devices encompass instruments, apparatus, and software intended for diagnosis, prevention, monitoring, or treatment of disease, typically manufactured under ISO 13485 quality systems with biocompatibility testing per ISO 10993. These products serve clinical settings ranging from acute intervention to chronic disease management. Diagnostic devices lead volume shipment across the region, while telemedicine platforms capture the fastest expansion as reimbursement frameworks adapt to remote care protocols. Surgical instruments retain mature margin pools where single-use disposables displace reprocessed metal tools in German and French operating theaters.
The EU Medical Device Regulation and In Vitro Diagnostic Regulation now govern market access, with notified bodies in Germany and the Netherlands experiencing backlog that delays product certification for smaller manufacturers. EMA coordination with national competent authorities shapes pharmacovigilance expectations for combination devices. Stakeholders must monitor notified body capacity constraints and evolving guidance on software-as-a-medical-device to time market entry effectively.
Market Dynamics
The EU Medical Device Regulation is compressing certification timelines while notified bodies in Germany and the Netherlands operate at capacity limits, creating a structural bottleneck that favors manufacturers with established quality systems and capital reserves for regulatory compliance.
Growth Catalysts
- MDR Conformity Pathways:The EU Medical Device Regulation's stricter clinical evidence requirements are consolidating procurement toward CE-marked devices with robust technical documentation, elevating standards across French and German hospital networks.
- Home-Based Care Expansion:French healthcare budgets are reallocating toward ambulatory dialysis and remote cardiac monitoring, pulling device innovation toward portable form factors with cloud connectivity.
- Titanium Alloy Adoption:German orthopedic forgers are transitioning billet supply from stainless steel to titanium alloys, enabling lighter implant designs that reduce surgical revision rates.
Market Restraints
- Notified Body Bottlenecks:German and Dutch notified bodies face application backlogs exceeding eighteen months, freezing market entry for smaller manufacturers lacking parallel regulatory strategies.
- Superconducting Magnet Supply Concentration:In-house production of niobium-titanium magnets at Siemens Healthineers and select competitors limits third-party access to high-field MRI core components.
- Single-Use Disposable Cost Premium:French and German operating theaters face 40-60% per-procedure cost increases as polymer disposables displace reprocessed metal instruments under infection control protocols.
Strategic Opportunities
- Polish and Romanian Hospital Modernization:EU cohesion funds are financing diagnostic imaging upgrades in Eastern European markets where equipment age averages exceed twelve years.
- Software-as-a-Medical-Device:The MDR's evolving guidance on SaMD classification creates first-mover advantage for AI-enabled diagnostic algorithms with validated clinical performance data.
- Wound Care Polymer Innovation:Advanced hydrocolloid and hydrogel formulations command premium positioning in European hospital networks seeking reduced healing times for chronic diabetic ulcers.
Industry Challenges
- Biocompatibility Testing Capacity:ISO 10993 cytotoxicity and sensitization studies face laboratory queue times of four to six months, delaying product launch schedules.
- EMA-National Authority Coordination:Combination device manufacturers must navigate divergent pharmacovigilance reporting expectations between European Medicines Agency guidance and national competent authority interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Devices Market |
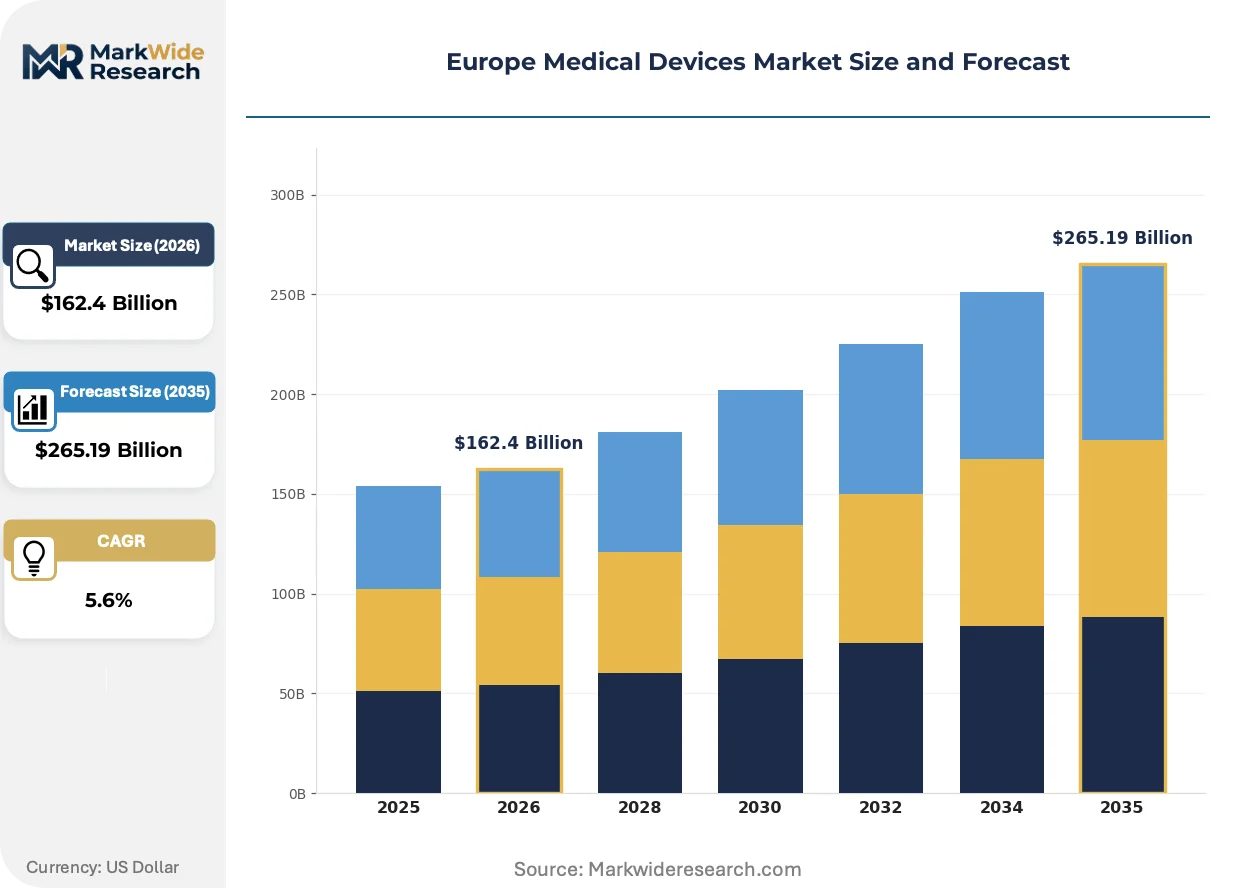
| Market Size in 2026 | $162.4 Billion |
| Market Size in 2035 | $265.19 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Surgical Instruments, Dental Equipment, Prosthetics Application: Cardiology, Orthopedics, Neurology, Endoscopy End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Wearable Devices, Imaging Systems, Minimally Invasive, Telemedicine |
| Companies Covered | Smith & Nephew, Sartorius Stedim Biotech, Medtronic plc, Becton Dickinson, Straumann Holding, Siemens Healthineers, Fresenius Medical Care, EssilorLuxottica, Philips Healthcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Devices Market Shifts & Advancements
Digital health integration is collapsing traditional boundaries between diagnostic hardware and clinical decision support, while regulatory frameworks scramble to keep pace with algorithmic functionality.
Continuous glucose monitoring systems paired with automated insulin delivery are unifying glucose sensing and therapeutic response into closed-loop platforms. Pediatric endocrinology departments in Germany and the Netherlands are piloting these systems at scale. The technology is unifying previously separate device categories into single reimbursement codes that compress pricing flexibility for component suppliers.
The EU AI Act's risk classification system for medical device software is mandating conformity assessments for machine learning algorithms deployed in diagnostic workflows. Manufacturers must now document training data provenance and algorithmic bias testing alongside traditional safety and performance files. Radiology AI tools for mammography screening face the steepest compliance burden, with notified bodies developing specialized audit protocols for black-box neural networks.
Hospital procurement consortia in France and Belgium are consolidating purchasing power through regional tendering platforms that displace distributor relationships. These platforms aggregate demand across multiple facilities to extract volume discounts on imaging equipment and surgical consumables. German university hospitals have pioneered this model, with Austrian and Swiss systems now replicating the structure.
Europe Medical Devices Market Segmentation
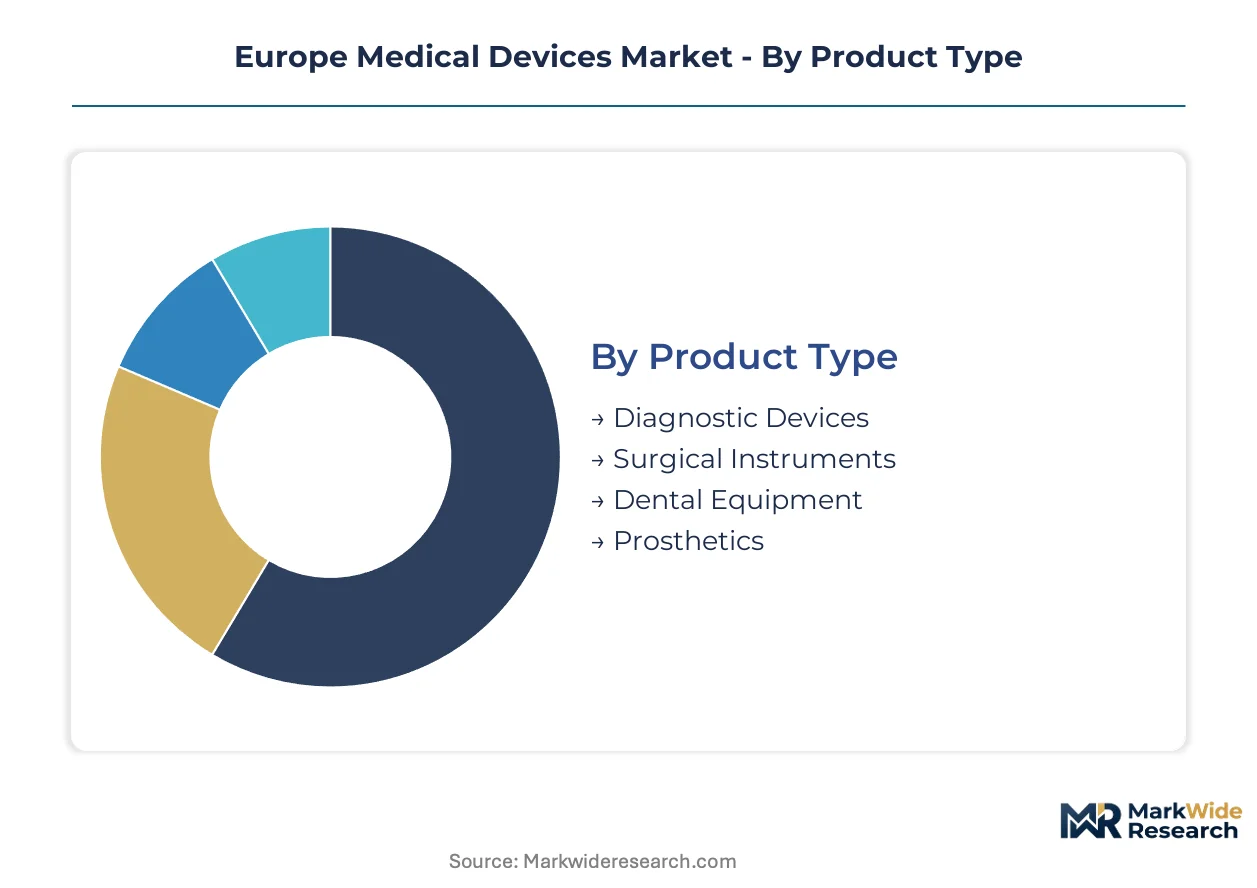
Device taxonomy in European healthcare procurement determines reimbursement codes, regulatory pathways, and distribution economics. Segment boundaries are blurring as diagnostic hardware merges with software platforms and hospital-based treatments migrate toward ambulatory settings.
Product Type:
Standalone instruments dominate acute intervention workflows, while embedded sensor systems increasingly penetrate chronic disease management protocols across German and French healthcare networks.
- Diagnostic Devices:ISO 13485-certified instruments ranging from handheld ultrasound probes to automated immunoassay analyzers. Demand concentrates in Polish and Romanian hospital networks upgrading imaging infrastructure with EU cohesion financing.
- Surgical Instruments:Reprocessed metal tools face displacement by single-use polymer disposables under MDR-mandated infection control protocols. German university hospitals drive procurement volume despite 40-60% per-procedure cost premiums.
- Dental Equipment:CAD-CAM milling systems and intraoral scanners.
- Prosthetics:Titanium alloy implants with 3D-printed patient-specific geometries.
Diagnostic devices lead volumes today; surgical instruments are gaining share fastest as disposable conversion accelerates.
Application:
Clinical specialization shapes device procurement through procedure volume thresholds and reimbursement tiering that favor high-utilization categories.
- Cardiology:Wearable cardiac monitors and interventional catheters. German hospitals are expanding remote monitoring procurement as ambulatory reimbursement frameworks mature.
- Orthopedics:Joint replacement implants and arthroscopy systems. French surgical networks prioritize titanium alloy designs that reduce revision rates.
- Neurology:Deep brain stimulation hardware and EEG monitoring platforms.
- Endoscopy:Single-use bronchoscopes and colonoscopes displacing reprocessed flexible scopes.
Orthopedics captures the largest revenue pool; cardiology is expanding most quickly through remote monitoring adoption.
End User:
Care setting determines device form factor, connectivity requirements, and regulatory classification intensity under MDR software-as-a-medical-device guidance.
- Hospitals:High-acuity settings requiring CE-marked devices with full technical documentation. German university hospital consortia aggregate procurement through regional tendering platforms.
- Clinics:Outpatient facilities favoring portable diagnostic hardware with cloud connectivity.
- Home Care:Dialysis equipment and glucose monitoring systems. French healthcare budgets are reallocating toward ambulatory dialysis, pulling device innovation toward portable form factors.
- Rehabilitation Centers:Mobility aids and continuous passive motion devices.
Hospitals dominate installed base; home care is climbing the fastest as chronic disease management decentralizes.
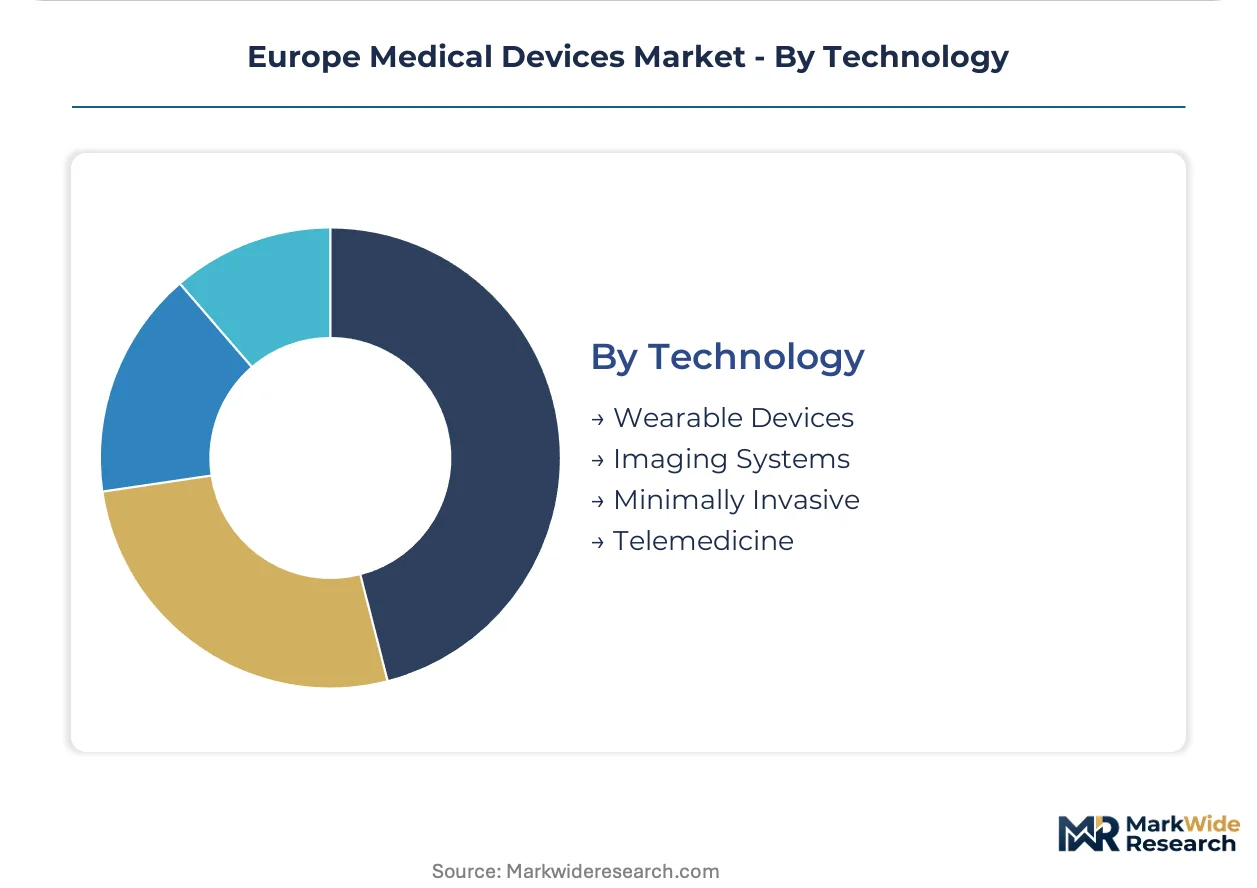
Technology:
Platform architecture determines whether devices operate as isolated instruments or integrated nodes within hospital information systems and remote care networks.
- Wearable Devices:Continuous glucose monitors and cardiac event recorders with Bluetooth telemetry. Pediatric endocrinology departments in Germany and the Netherlands pilot closed-loop insulin delivery at scale.
- Imaging Systems:MRI and CT platforms requiring superconducting magnet supply chains. Siemens Healthineers anchors European supply through in-house niobium-titanium magnet production.
- Minimally Invasive:Laparoscopic and robotic-assisted surgical platforms.
- Telemedicine:AI-enabled diagnostic algorithms facing EU AI Act conformity assessments for black-box neural networks.
Imaging systems command the highest unit economics; telemedicine shows the steepest expansion trajectory as reimbursement frameworks adapt to remote protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with streamlined MDR conformity pathways and notified body availability, compressing time-to-market for CE-marked devices.
Germany
German hospitals are expanding procurement of wearable cardiac monitors and remote monitoring platforms as ambulatory reimbursement frameworks mature. The country's national pharmaceutical regulator coordinates with EMA on pharmacovigilance expectations for combination devices. The Baden-Württemberg industrial corridor hosts orthopedic forgers transitioning billet supply from stainless steel to titanium alloys.
France
French healthcare budgets are reallocating toward home-based dialysis equipment and portable renal care systems. ANSM oversees medical device vigilance and software-as-a-medical-device classifications under evolving MDR guidance. The Île-de-France region concentrates hospital procurement consortia that aggregate demand across multiple facilities through regional tendering platforms.
Netherlands
Pediatric endocrinology departments in Dutch hospital networks are piloting closed-loop insulin delivery systems at scale. The country's national health technology assessment body evaluates reimbursement eligibility for AI-enabled diagnostic algorithms. The Eindhoven-Utrecht corridor anchors diagnostic imaging component manufacturing serving broader European supply chains.
Switzerland
Swiss hospital networks prioritize premium wound care polymers and advanced hydrocolloid formulations for chronic diabetic ulcer management. Swissmedic maintains bilateral recognition agreements with EU notified bodies that streamline market access for CE-marked devices. The Basel-Zurich corridor concentrates precision instrument manufacturing with captive supply chains for surgical consumables.
Poland
Polish hospital networks are upgrading diagnostic imaging infrastructure with EU cohesion fund financing as equipment age averages exceed twelve years. The country's national medical device regulator aligns conformity assessment procedures with EU MDR requirements. The Warsaw-Kraków corridor is emerging as a distribution hub for refurbished imaging equipment serving Eastern European markets.
Europe Medical Devices Market Competitive Landscape
German producers anchor the premium-tier imaging and surgical instrument segments; Swiss and Dutch specialists hold positions in precision diagnostics and biotechnology equipment. The vendor base stratifies across three tiers: diversified conglomerates with in-house magnet and sensor production, mid-cap device specialists with ISO 13485-certified quality systems, and niche component suppliers serving contract manufacturing relationships. Dominant competitive moves include backward integration into superconducting magnet supply and strategic partnerships with hospital procurement consortia to secure multi-year tender awards.
Within the diversified conglomerate tier, Siemens Healthineers and Philips Healthcare exemplify players with captive production of core imaging components. Among orthopedic and wound care specialists, Smith & Nephew occupies a position representing premium polymer innovation for European hospital networks. These archetypes illustrate how regulatory compliance capacity and manufacturing scale determine competitive positioning under MDR certification timelines.
| Leading Market Players |
|---|
| Smith & Nephew |
| Sartorius Stedim Biotech |
| Medtronic plc |
| Becton Dickinson |
| Straumann Holding |
| Siemens Healthineers |
| Fresenius Medical Care |
| EssilorLuxottica |
| Philips Healthcare |
| Others |
Supply & Pricing Matrix
Niobium-titanium billet price indices cascade through European MRI manufacturing into tiered equipment pricing, compressing margins for third-party assemblers lacking captive magnet production while elevating premium positioning for vertically integrated imaging suppliers serving German and French hospital procurement consortia.
Pricing Analysis
Distributor markups on single-use surgical disposables absorb 25-35% of landed cost in French and German operating theaters. Three-tier pricing structure across premium CE-marked devices, standard ISO 13485-certified instruments, and economy refurbished equipment separates procurement budgets by clinical acuity tier. Pricing pressure stems from hospital consortia aggregating demand through regional tendering platforms that extract volume discounts. Price-sensitive buyers concentrate in Polish and Romanian networks upgrading aged infrastructure with EU cohesion financing, while Swiss university hospitals exhibit lowest sensitivity to premium wound care polymer pricing.
Supply Chain Analysis
Single-source vulnerability sits with German niobium-titanium magnet foundries supplying Siemens Healthineers and select imaging competitors. Component sourcing draws from Netherlands-based sensor packaging facilities, Swiss precision instrument forgers, and Italian polymer compounders serving wound care applications. Raw material dependencies include titanium alloy billet, medical-grade silicone, and superconducting wire. Tariff exposure on Chinese-sourced rare earth elements for MRI magnet production presents structural risk. Distribution runs through hospital procurement consortia in France and Germany that displace traditional distributor relationships with direct manufacturer contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Medical Devices Market functions as a stable compounder anchored by MDR-mandated replacement cycles that force systematic equipment refresh across hospital networks regardless of macroeconomic conditions.
For Market Incumbents: Extend regulatory compliance capacity through notified body pre-submission pathways in Germany and the Netherlands to compress certification timelines for software-as-a-medical-device launches. Deepen backward integration into titanium alloy billet supply as orthopedic implant demand shifts from stainless steel. Defend against emerging Polish and Romanian refurbished imaging distributors by anchoring service contracts to CE-marked original equipment. For New Entrants and Emerging Players: Launch via software-as-a-medical-device pathways targeting AI-enabled diagnostic algorithms with validated clinical performance data ahead of EU AI Act conformity assessment specialization. White-space opportunity concentrates in ambulatory dialysis equipment for French home-care reimbursement expansion and closed-loop insulin delivery systems for German pediatric endocrinology networks. Go-to-market angle should prioritize hospital procurement consortia partnerships over traditional distributor channel builds. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap device specialists possessing ISO 13485-certified quality systems and established notified body relationships but lacking capital for MDR clinical evidence generation. Five-to-ten year viability favors acquisition targets with software-enabled hardware platforms where recurring revenue streams emerge from remote monitoring connectivity. Signal to watch is notified body capacity expansion announcements in Germany and the Netherlands as inflection indicator for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation investment secures market access ahead of notified body bottlenecks. |
| Hospital System Partnership | Multi-year tender awards with German university hospital consortia lock in imaging equipment replacement cycles. |
| Software Companion Development | AI-enabled diagnostic algorithms attract EU AI Act risk-classification premium under evolving guidance. |
| Backward Integration into Magnets | In-house niobium-titanium production shields MRI manufacturers from rare earth supply volatility. |
| Reimbursement Strategy | Remote monitoring coding alignment with French ambulatory dialysis budgets accelerates home-care device adoption. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down imaging equipment shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at notified bodies combined with secondary validation against EMA guidance documents, EU MDR implementing acts, hospital procurement databases, and GPO contract award disclosures. Triangulation between demand-side procedure volume assumptions and supply-side manufacturing capacity data ensures cross-verified output integrity.
Input-output matrices map procedure volume forecasts by clinical specialty against device utilization rates per intervention, with segmentation dimensions spanning diagnostic versus therapeutic application, acute versus ambulatory care setting, and CE-marked versus legacy device regulatory status. CAGRs derive from logistic diffusion curves fitted to reimbursement framework adoption timelines and hospital capital expenditure cycle analysis. Industry-specific forecast inputs include notified body certification queue projections and EU cohesion fund disbursement schedules for Eastern European infrastructure modernization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged notified body backlogs or accelerated EU AI Act enforcement timelines. Forecasts reflect documented assumptions regarding MDR transition completion rates and hospital procurement consortium penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Acne Treatment Devices Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Global Hip Implant Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Australia Medtech Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Artificial Eye Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Radiofrequency (RF) Ablation System Market