
 Europe Nurse Call Systems Market | 2026-2036
Europe Nurse Call Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nurse Call Systems Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access across the Europe nurse call systems landscape. Ascom Holding AG leverages its Swiss engineering heritage to sustain premium positioning in acute care connectivity. Siemens anchors large-scale hospital infrastructure projects through its building technology division, while SCHRACK SECONET specializes in Austrian-manufactured alarm systems for Central European healthcare networks.
Nurse call systems encompass patient-triggered communication infrastructure that relays alerts to nursing stations via hardwired or wireless signaling pathways, typically integrating with building management and clinical workflow platforms. These installations reduce response latency to bedside emergencies and streamline staff deployment across multi-wing facilities. Wireless systems capture expanding retrofit demand as legacy wired infrastructure reaches replacement cycles in aging European hospital stock. IP-Based technology segments attract capital as facilities prioritize interoperability with electronic health records and real-time location services. Workflow Management applications deepen penetration in nursing homes seeking labor optimization amid continent-wide staffing shortages.
The EU Medical Device Regulation and EMA guidance on connected medical devices tighten software validation and cybersecurity requirements for new nurse call deployments. Germany's KBA-equivalent federal institute for drugs and medical devices enforces post-market surveillance protocols that extend vendor accountability timelines. France's ANSM coordinates vigilance reporting for alarm system malfunctions, reinforcing documentation burdens on manufacturers. Stakeholders must weigh backward integration into cloud-native platform development against partnership strategies with established healthcare IT vendors as regulatory complexity escalates.
Market Dynamics
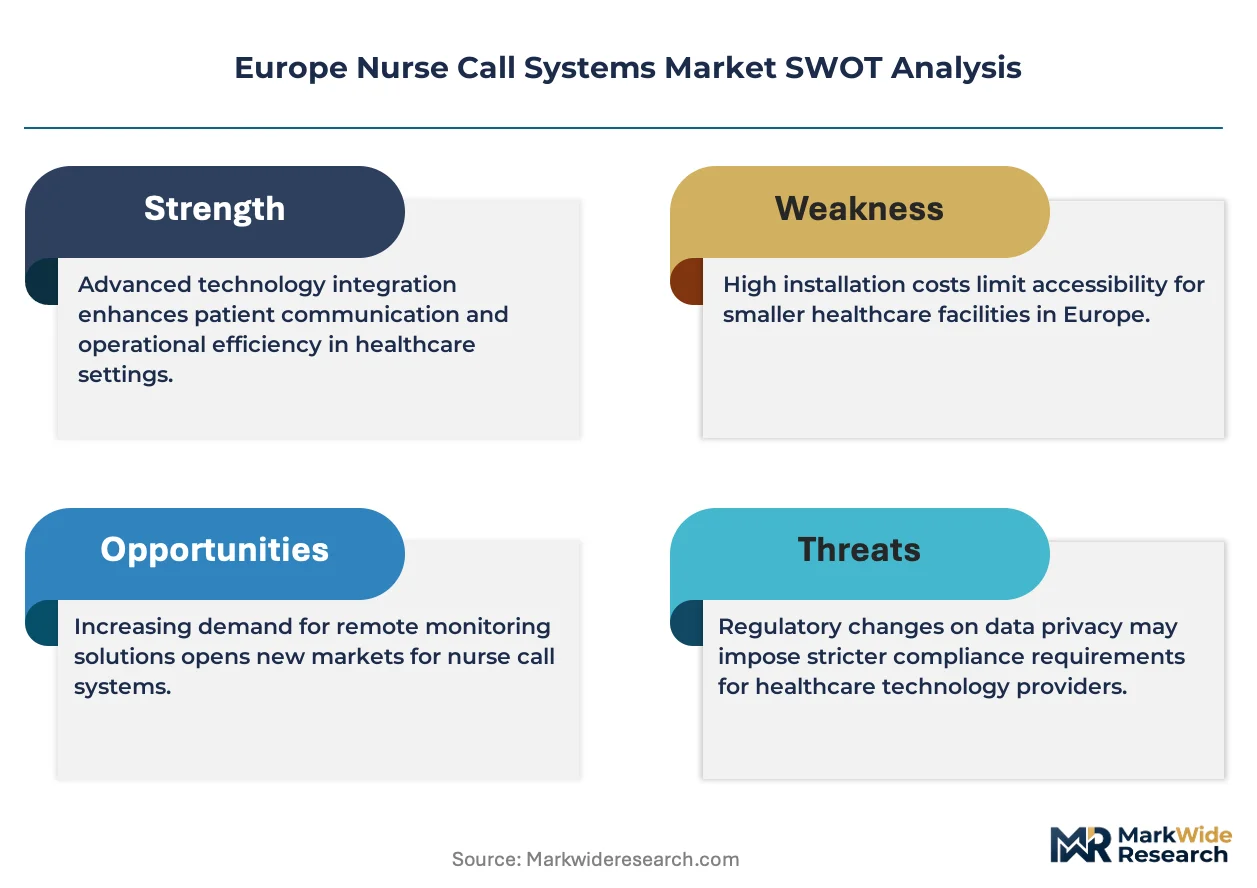
Wireless IP infrastructure is displacing legacy copper-wire installations across European acute care facilities, with retrofit demand intensifying as aging hospital estates face connectivity obsolescence. The EU Medical Device Regulation's software validation mandates are compressing vendor development timelines while elevating compliance costs.
Growth Catalysts
- EU MDR software classification:Stricter cybersecurity protocols for connected medical devices are compelling hospitals to replace non-compliant legacy systems with validated alternatives.
- Real-time location services convergence:Nurse call platforms integrating staff-tracking capabilities are capturing capital allocation in multi-wing facilities seeking workflow optimization.
- German hospital infrastructure renewal:Federal procurement programs targeting digital health modernization are accelerating replacement cycles in Europe's largest acute care market.
Market Restraints
- Copper and semiconductor input volatility:Fluctuating raw material costs for wireless chipset and cabling components are compressing hardware margins.
- CE marking timeline extension:Extended conformity assessment procedures under notified body capacity constraints are delaying product launches.
- Building management system substitution:Integrated facility platforms with native alerting capabilities are capturing share in greenfield construction projects.
Strategic Opportunities
- Polish healthcare infrastructure gap:Underpenetrated acute care digitization in Central European markets offers first-mover positioning for IP-native vendors.
- GDPR-compliant cloud architecture:Sovereign data residency requirements are creating demand for EU-hosted platform deployments.
- Workflow management software unbundling:Modular SaaS offerings are opening channel access to nursing home operators previously priced out of integrated systems.
Industry Challenges
- Embedded systems cybersecurity expertise:Scarce talent pools for medical device penetration testing are extending development cycles.
- Legacy analog integration complexity:Hybrid deployments requiring protocol bridging between copper-wire and IP infrastructure are elevating implementation risk.
- Post-market surveillance documentation:EUDAMED reporting obligations are expanding quality assurance headcount requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nurse Call Systems Market |
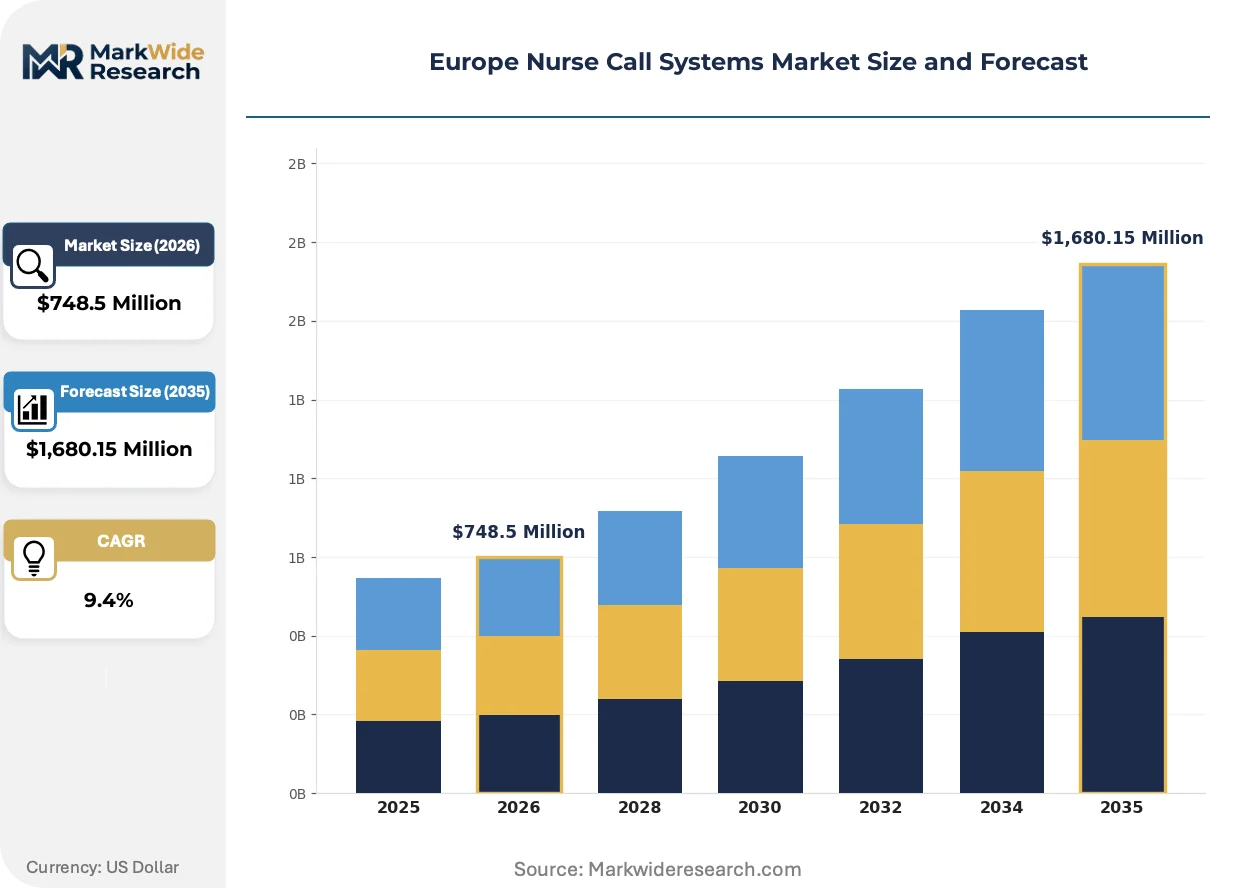
| Market Size in 2026 | $748.5 Million |
| Market Size in 2035 | $1,680.15 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Systems, Wired Systems, Integration Solutions, Alarm Systems Technology: Analog, Digital, IP-Based, Hybrid End User: Hospitals, Nursing Homes, Assisted Living Facilities, Rehabilitation Centers Application: Patient Monitoring, Emergency Communication, Staff Alerting, Workflow Management |
| Companies Covered | Ascom Holding AG, Honeywell International Inc, Baxter (Hillrom), AMETEK (Rauland), Siemens, SCHRACK SECONET, Tunstall Group, Austco Healthcare, Legrand, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nurse Call Systems Market Shifts & Advancements
Interoperability mandates and cloud-native architecture are restructuring how patient-staff communication infrastructure is procured, deployed, and monetized across European healthcare networks.
IP-based nurse call infrastructure is bifurcating competitive positioning between premium interoperability providers and cost-optimized standalone vendors. Acute care hospitals in France and Germany are prioritizing platforms with native electronic health record integration, compressing demand for closed-system alternatives. This technology shift is enabling real-time data exchange with clinical workflow platforms while marginalizing proprietary protocol ecosystems.
REACH substance restrictions on electronics manufacturing are tightening material compliance requirements for circuit board assemblies. Manufacturers must now document full chemical composition across supply chains, elevating documentation burdens for Asian-sourced components. German medical device producers are responding by regionalizing printed circuit board procurement to reduce regulatory exposure.
Hospital procurement departments are consolidating vendor relationships through framework agreements covering multiple facility sites. National health service purchasing consortia in the United Kingdom are displacing individual hospital tender processes, concentrating contract awards with platforms demonstrating multi-site manageability. This concentration is most visible in National Health Service trusts seeking unified incident response protocols.
Europe Nurse Call Systems Market Segmentation
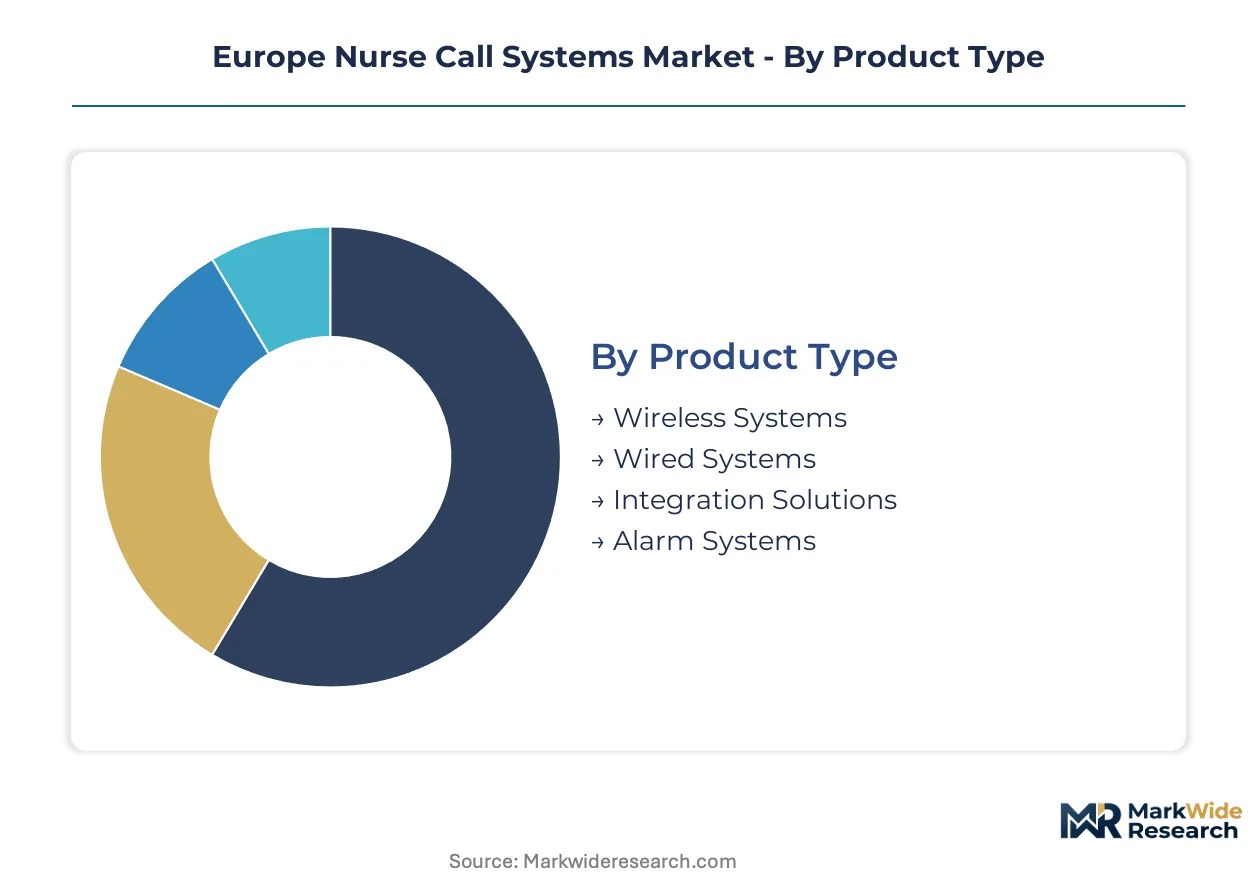
Segmentation in Europe's nurse call systems market reveals distinct procurement patterns across infrastructure types, technology generations, and care settings. Each dimension carries different margin profiles and regulatory exposure under the EU Medical Device Regulation.
Product Type:
Margin pools concentrate in wireless retrofit installations where copper replacement cycles coincide with cybersecurity upgrade mandates.
- Wireless Systems:Radio-frequency and Wi-Fi enabled infrastructure eliminates copper cabling while enabling real-time location services integration. German acute care hospitals are prioritizing these deployments as KBA-equivalent surveillance protocols tighten accountability for alarm latency failures.
- Integration Solutions:Middleware platforms bridging nurse call infrastructure with electronic health records, building management, and clinical workflow systems command premium pricing. French hospital consortia under ANSM oversight are consolidating procurement around vendors offering native interoperability with existing IT estates.
- Wired Systems:Legacy copper-wire installations retain share in greenfield construction where electromagnetic interference concerns persist.
- Alarm Systems:Standalone audible and visual alert hardware serves budget-constrained nursing home operators in Central European markets.
Wireless Systems holds installed capacity. Integration Solutions is rotating up the share rankings.
Technology:
Technology selection maps directly to regulatory compliance burden and total cost of ownership across replacement cycles.
- IP-Based:Native internet protocol architecture enables cloud connectivity, remote diagnostics, and seamless EHR integration while satisfying GDPR data residency requirements. United Kingdom NHS trusts are mandating IP-native platforms for new procurements to enable centralized multi-site management.
- Digital:Packet-switched signaling over dedicated networks offers intermediate upgrade paths for facilities with partial legacy infrastructure. Austrian healthcare networks under SCHRACK SECONET influence favor these systems for Central European alarm reliability standards.
- Analog:Voltage-loop signaling retains residual demand in rural facilities with limited IT infrastructure.
- Hybrid:Protocol-bridging configurations connect copper-wire endpoints to IP backbones during phased migrations.
Digital maintains the largest installed base. IP-Based is climbing the fastest as MDR software validation requirements harden.
End User:
End user segmentation reflects divergent staffing pressures and capital availability across European care settings.
- Hospitals:Acute care facilities with 24-hour nursing stations require enterprise-grade redundancy and sub-second alarm routing. Germany's federal hospital infrastructure programs are accelerating replacement of non-compliant legacy systems in this segment.
- Nursing Homes:Long-term care operators face continent-wide workforce shortages driving demand for workflow optimization software. French nursing home chains are unbundling SaaS modules from integrated platforms to access previously cost-prohibitive functionality.
- Assisted Living Facilities:Semi-independent resident populations need simplified pendant interfaces with fall detection integration.
- Rehabilitation Centers:Transitional care settings prioritize mobility tracking and therapy scheduling integration.
Hospitals retain procurement volume leadership. Nursing Homes is expanding most quickly as labor scarcity intensifies.
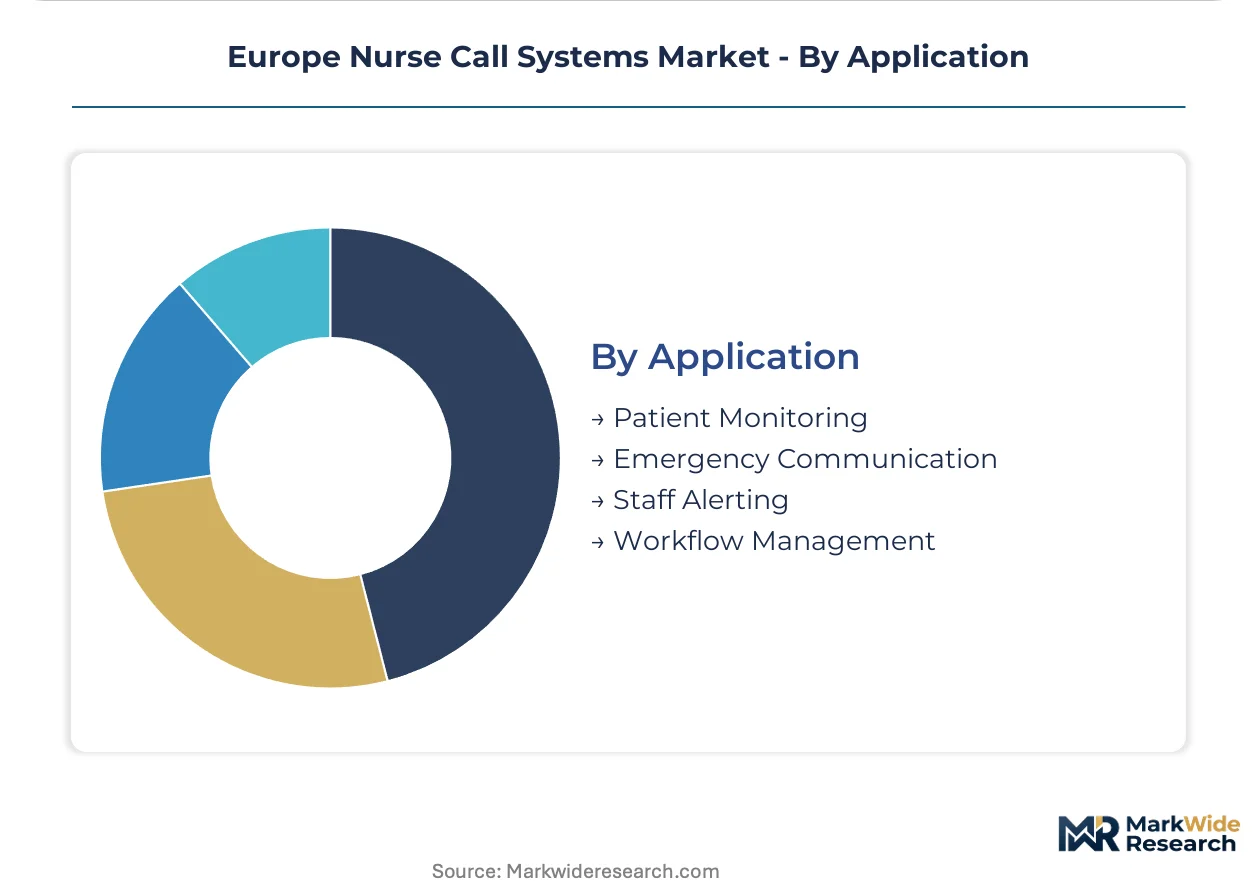
Application:
Application segmentation tracks the shift from reactive alerting toward predictive workflow orchestration.
- Workflow Management:Staff deployment optimization algorithms reduce response variance and overtime costs through predictive load balancing. United Kingdom NHS purchasing consortia are weighting tender evaluations toward platforms demonstrating measurable nursing hour savings.
- Patient Monitoring:Continuous vital sign integration with nurse call escalation protocols supports early warning score automation. German university hospitals are piloting these configurations under BfArM post-market surveillance frameworks.
- Emergency Communication:Code blue and rapid response team activation remains mandatory functionality in all acute care settings.
- Staff Alerting:Individual nurse paging and location-aware routing addresses basic connectivity requirements.
Patient Monitoring dominates current installations. Workflow Management is gaining share fastest as labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal digital health infrastructure programs across the continent are accelerating hospital modernization timelines. CE marking requirements under EU MDR are compressing vendor certification windows while elevating compliance costs for new installations. Procurement concentration in Germany, France, and the United Kingdom is reshaping competitive access patterns.
Germany
Acute care digitization initiatives and hospital infrastructure renewal programs are driving replacement of legacy copper-wire systems. BfArM post-market surveillance protocols extend vendor accountability timelines for alarm latency failures. University hospital clusters in Berlin and Munich are piloting IP-native platforms with EHR integration.
France
ANSM-coordinated vigilance reporting for alarm malfunctions reinforces documentation burdens on manufacturers. National health service purchasing consortia are consolidating procurement around multi-site manageable platforms. Hospital networks in Île-de-France are weighting tender evaluations toward workflow optimization capabilities.
United Kingdom
NHS trusts are mandating IP-native platforms to enable centralized multi-site management and unified incident response protocols. Framework agreements covering multiple facility sites are displacing individual hospital tender processes. Procurement concentration in London and the Southeast is accelerating vendor consolidation.
Poland
Underpenetrated acute care digitization creates first-mover positioning opportunities for IP-native vendors. EU structural funds targeting healthcare infrastructure modernization are unlocking capital for wireless retrofit installations. Hospital networks in Warsaw and Kraków are initiating phased connectivity upgrades.
Switzerland
Swissmedic oversight of connected medical devices aligns with EU MDR software validation requirements. Premium acute care connectivity demand leverages Swiss engineering heritage for alarm reliability standards. Healthcare clusters in Zurich and Geneva prioritize interoperability with cross-border clinical workflow platforms.
Europe Nurse Call Systems Market Competitive Landscape
Player mix skews toward diversified healthcare technology conglomerates and specialized alarm system manufacturers. Market structure exhibits moderate consolidation with tiered positioning between premium interoperability providers and cost-optimized standalone vendors. Two dominant strategic archetypes emerge: engineering-driven specialists with regional manufacturing footprints, and diversified conglomerates leveraging building technology portfolios. Competitive moves center on M&A for workflow software capabilities and partnership strategies with healthcare IT vendors.
Within the engineering-specialist tier, Ascom Holding AG and SCHRACK SECONET exemplify regional manufacturing anchoring. Siemens occupies a position representing building technology conglomerate diversification into healthcare infrastructure. Among diversified healthcare technology providers, Honeywell International Inc and Baxter (Hillrom) sit within portfolios spanning acute care connectivity and clinical workflow platforms. These named entities represent archetype positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Ascom Holding AG |
| Honeywell International Inc |
| Baxter (Hillrom) |
| AMETEK (Rauland) |
| Siemens |
| SCHRACK SECONET |
| Tunstall Group |
| Austco Healthcare |
| Legrand |
| Others |
Supply & Pricing Matrix
EU Medical Device Regulation software classification gates both vendor qualification and price differentiation simultaneously, compressing development timelines for premium-tier platforms while elevating compliance costs that propagate through contract structures. Hospital procurement consortia in France and Germany exploit this bifurcation to consolidate purchasing power around validated interoperability providers.
Pricing Analysis
Certification level creates the primary spread across the European nurse call systems landscape, with CE-marked MDR-compliant platforms commanding substantial premiums over legacy installations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation in EHR integration depth, cybersecurity validation, and real-time location services bundling. Cost compression in mid-tier wireless retrofit segments intensifies as Asian chipset vendors enter component supply. Nursing home operators in Central Europe exhibit highest price sensitivity, while German university hospital clusters prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Taiwan semiconductor foundry capacity constraints propagate through wireless chipset lead times, tethering European nurse call system production to Asia-Pacific electronics manufacturing cycles. Printed circuit board assemblies draw from German and Austrian regional suppliers seeking REACH substance compliance, while copper cabling components source from Polish and Romanian wire mills. Single-source vulnerability in Wi-Fi module procurement elevates inventory carrying requirements for IP-native platform vendors. Distribution runs through hospital group purchasing organizations and national health service framework agreements rather than direct manufacturer-to-facility contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across European healthcare procurement as NHS trusts and French hospital consortia displace individual facility tender processes, fragmenting vendor access for standalone system providers.
For Market Incumbents: Secure backward integration into cloud-native platform development to defend margin position against building management system substitution threatening greenfield construction share. Anchor capacity expansion in German manufacturing clusters to satisfy BfArM post-market surveillance proximity requirements. Prioritize certification investment in MDR software validation to maintain access to acute care procurement channels as notified body capacity constraints extend rival launch timelines. For New Entrants and Emerging Players: Lead with modular SaaS workflow management unbundling to capture nursing home operators previously priced out of integrated system procurement. Polish acute care digitization gaps offer the most penetrable geography for IP-native first-mover positioning. Pursue hospital system partnership strategies with established healthcare IT vendors rather than direct competitive confrontation with engineering heritage incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IP-native platform development as cybersecurity expertise scarcity extends engineering headcount requirements. Five-to-ten year viability favors acquisition targets with sovereign EU cloud architecture capabilities and GDPR-compliant data residency infrastructure. Watch EUDAMED reporting obligation enforcement intensity as the inflection signal for quality assurance cost structure normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR software validation accelerates competitive exclusion of non-compliant legacy vendors. |
| Hospital System Partnership | NHS framework agreements concentrate contract awards with multi-site manageable platforms. |
| Software Companion Development | EHR integration modules capture premium pricing in French university hospital networks. |
| Backward Integration | Regional PCB procurement reduces REACH substance compliance exposure from Asian suppliers. |
| Reimbursement Strategy | German federal infrastructure programs unlock capital for validated alarm system replacement cycles. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with hospital procurement committees, biomedical engineers, GPO contracts managers, and nurse call system integration specialists; and secondary validation against EUDAMED device registrations, NHS procurement databases, BfArM vigilance reports, and EU structural fund disbursement records. Bottom-up installation tracking across German, French, and United Kingdom acute care facilities triangulated against top-down vendor revenue segmentation.
Across the projection horizon, the analytical framework modeled technology generation transitions, end-user capital availability divergences, and application workflow depth as core segmentation dimensions. CAGRs derived from replacement cycle velocity analysis incorporating legacy copper-wire infrastructure age profiles and MDR compliance deadline proximity. Forecast inputs included semiconductor lead time volatility indices and notified body certification queue length estimates.
The analysis sits within stated boundaries; outcomes outside sustained EU healthcare infrastructure funding levels or accelerated MDR enforcement timelines would require recalibration. Practitioners should keep alternative scenarios live as EUDAMED reporting obligation implementation intensity and REACH substance restriction scope evolution reshape vendor cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Immunoadsorption Columns Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Self-Injections Market
Medical Devices
Meniscal Rasps Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market