
 Aircraft Seats Market | 2026-2036
Aircraft Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Seats Market Insights
EU AI Act is recalibrating the cost-of-entry calculus for smart seat manufacturers integrating passenger monitoring systems. Safran leverages its vertical integration from composites to final assembly to sustain margin control across European airline programs. RECARO Aircraft Seating anchors its position through R&D intensity in lightweight thermoplastic designs that compete on fuel-burn reduction metrics.
Aircraft seats are structural cabin components engineered to withstand dynamic loads, typically incorporating aluminum frames, fire-blocking cushions, and polyester or leather upholstery, with primary functions encompassing occupant restraint during turbulence and crash events while optimizing passenger density per cabin floor area. Economy class configurations dominate volume shipments across commercial airlines, while lie-flat technology commands the deepest margin pools on long-haul routes. Modular platforms represent the fastest-growing technology segment as carriers seek reconfigurable cabins that adapt to seasonal demand shifts without full interior overhauls.
FAA regulations govern flammability and structural integrity standards for seats installed on US-registered aircraft, while EASA enforces parallel certification requirements across European operators, and TSO-C127b establishes minimum performance benchmarks that shape manufacturer design priorities. Airlines and seat vendors must monitor evolving crashworthiness mandates that extend testing protocols to higher deceleration pulses. Stakeholders should weigh certification timeline risks against the revenue upside of platforms that ship across multiple regulatory jurisdictions.
Market Dynamics
Fleet renewal cycles across narrow-body commercial aviation are compressing replacement timelines, forcing seat manufacturers to accelerate development pipelines while absorbing stricter FAA and EASA crashworthiness testing protocols that extend certification durations.
Growth Catalysts
- FAA Crashworthiness Amendments:Updated TSO-C127b testing standards mandate higher deceleration pulse survivability, compelling airlines to replace legacy seat structures and expanding addressable market volume for certified suppliers.
- Lightweight Thermoplastic Adoption:Carbon fiber-reinforced thermoplastic frames reduce per-seat weight by substantial margins, delivering fuel-burn savings that justify premium pricing on retrofit programs across LCC and full-service carriers.
- India:The country's PLI scheme for aerospace components is attracting seat subsystem manufacturers to establish local assembly capacity, reducing import dependency for domestic airline fleet expansion.
Market Restraints
- Titanium and Aluminum Price Volatility:Frame material cost swings compress margin predictability for manufacturers locked into long-term airline supply contracts with fixed pricing clauses.
- Supply Concentration in Western Europe:Premium seat final assembly clusters in Germany and France, creating geographic risk exposure for programs requiring just-in-time delivery to Asian MRO facilities.
- Fire-Blocking Foam Substitution Limits:No commercially viable alternative to polyurethane-based fire-blocking layers has achieved FAA flammability certification, constraining material cost reduction pathways.
Strategic Opportunities
- Brazil:ANVISA alignment with FAA certification standards is streamlining dual-approval pathways, enabling seat vendors to access LATAM carrier retrofit demand with reduced regulatory friction.
- Modular Reconfiguration Platforms:Quick-release track systems and plug-and-play IFE integration allow carriers to shift density between 180 and 220 seats on identical airframes within 48-hour turnaround windows.
- EU AI Act Compliance Services:Smart seat manufacturers integrating passenger biometrics can monetize regulatory consulting as a revenue stream, converting compliance burden into recurring advisory income.
Industry Challenges
- Structural Engineer Talent Scarcity:Specialized expertise in dynamic load simulation and crash kinematics concentrates among aging workforces in Toulouse and Wichita, constraining R&D scaling.
- Certification Timeline Compression:EASA's expanded dynamic testing requirements add 8-14 months to type certification, misaligning product availability with airline fleet delivery schedules.
- Legacy Fleet Integration Complexity:New lightweight seat designs require floor fitting modifications on pre-2010 Boeing 737NG and Airbus A320ceo airframes, inflating retrofit engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Seats Market |
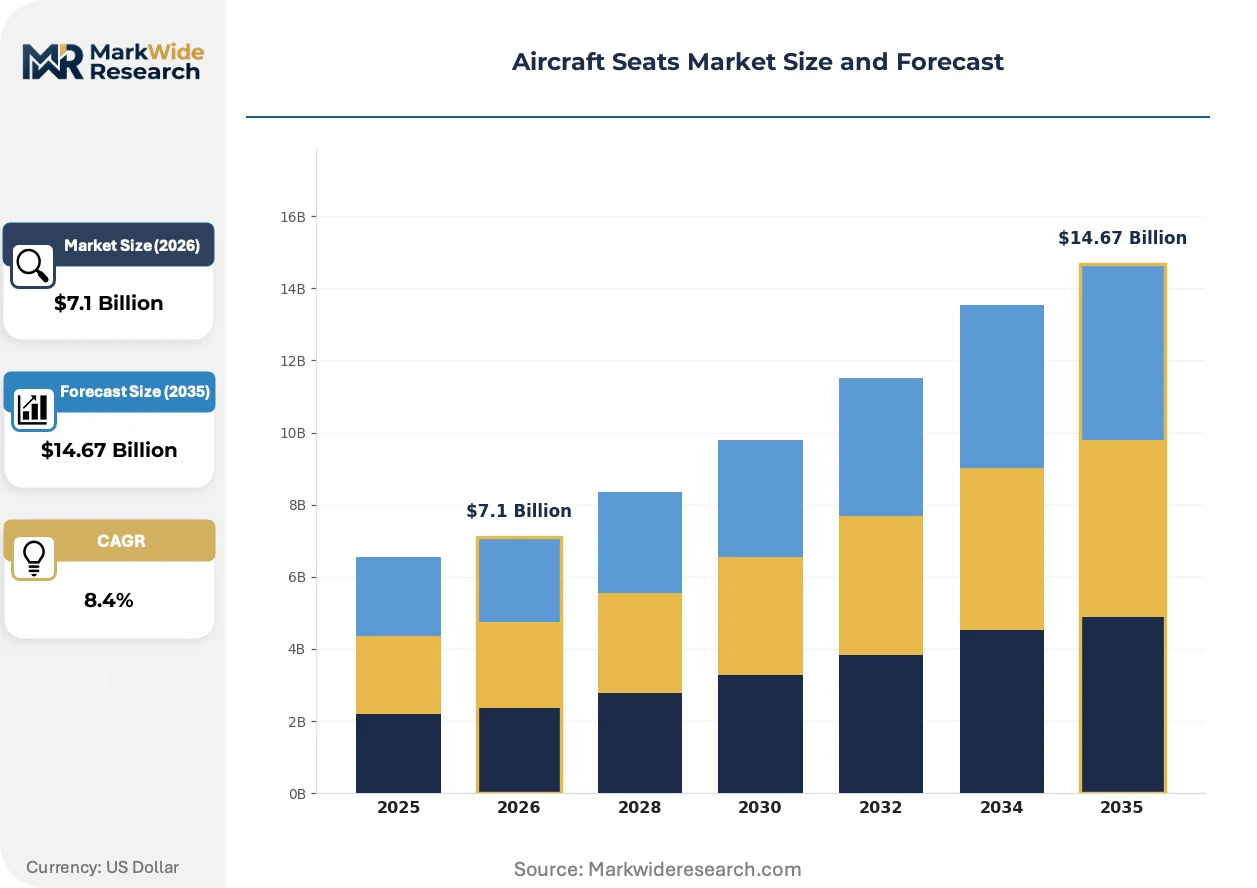
| Market Size in 2026 | $7.1 Billion |
| Market Size in 2035 | $14.67 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Economy Class, Business Class, First Class, Premium Economy Technology: Recliner, Sleeper, Lie-flat, Modular Application: Commercial Airlines, Private Jets, Military Aircraft, Cargo Planes End User: Airlines, Charter Services, Government Operators, Aircraft Manufacturers |
| Companies Covered | Safran, Raytheon Technologies Corporation, RECARO Aircraft Seating, STELIA Aerospace, Collins Aerospace, Geven S.p.A., Jamco Corporation, Thompson Aero Seating, ZIM Aircraft Seating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Seats Market Trends and Innovations
Digital thread technologies are collapsing the design-to-certification pipeline, enabling real-time structural validation that accelerates iteration cycles while embedding regulatory compliance from initial concept phases.
Shape-memory alloy actuators are integrating into adjustable headrest and lumbar support mechanisms, delivering electromechanical precision without hydraulic complexity. Full-service carriers deploying these systems on long-haul premium cabins report reduced maintenance intervals compared to pneumatic alternatives. The technology is integrating passenger comfort customization with weight reduction targets that were previously mutually exclusive.
EASA's expanded CS-25 cabin safety amendments now require 16g dynamic testing for all newly certified seat models, elevating engineering standards that filter down to regional airline procurement specifications. Manufacturers serving European operators have reallocated R&D budgets toward finite element modeling capabilities that predict structural failure modes under multi-axis loading. This regulatory tightening is compressing the competitive set to suppliers with captive crash-test facilities in France, Germany, and the United Kingdom.
Airline technical procurement teams are consolidating vendor relationships around platform providers capable of delivering integrated seat-IFE-power solutions under single-source accountability frameworks. This bundling displaces the historical model of discrete subsystem contracting, favoring manufacturers with in-house electronics integration capabilities. The shift is most visible among Gulf carriers modernizing wide-body fleets, where specification complexity and delivery coordination costs now exceed hardware price differentials in sourcing decisions.
Aircraft Seats Market Segmentation
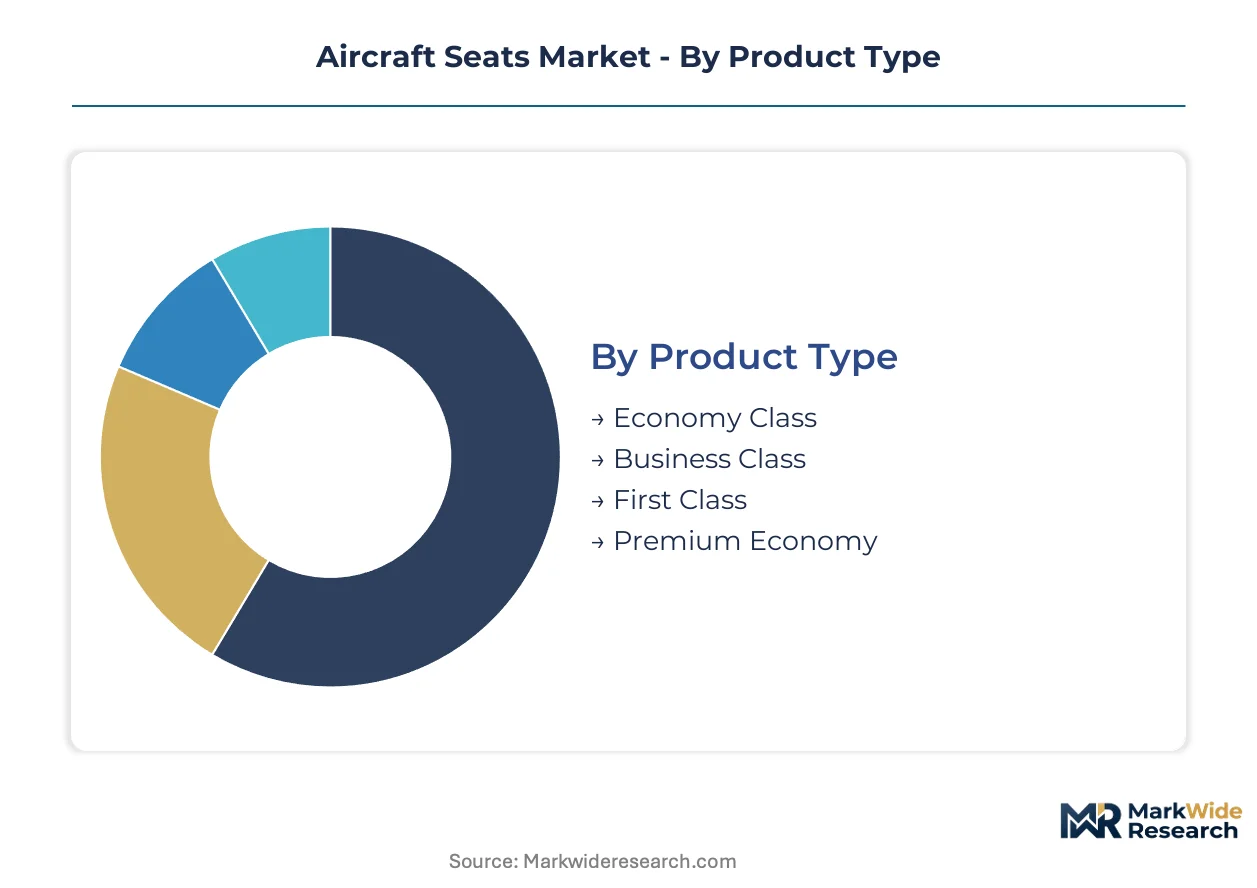
Seat segmentation in commercial aviation tracks directly with cabin reconfiguration cycles and regulatory recertification timelines. Airlines prioritize segments that minimize floor modification costs during retrofit programs while maximizing passenger yield per square meter.
Product Type:
Upgrade urgency varies sharply across cabin tiers as carriers balance amortization schedules against fuel-burn savings from lighter platforms.
- Economy Class:High-density configurations utilize aluminum-composite hybrid frames with fire-blocking polyurethane cushions. Narrow-body fleet renewal across United States domestic carriers drives volume demand, though margin compression limits supplier pricing power on bulk orders.
- Business Class:Lie-flat mechanisms with carbon fiber-reinforced shells command substantial retrofit investment from full-service carriers on transatlantic and transpacific routes. FAA TSO-C127b amendments now mandate 16g dynamic testing for all new business seat certifications, extending development timelines.
- First Class:Ultra-premium enclosed suites with integrated IFE and personal storage occupy minimal fleet penetration.
- Premium Economy:Recliner platforms with increased pitch and width target yield optimization on long-haul leisure routes.
Economy Class sits at the top of the volume ranking, with Premium Economy climbing the fastest.
Technology:
Platform selection hinges on reconfiguration flexibility and maintenance interval predictability rather than upfront hardware cost alone.
- Modular:Quick-release track systems enable density shifts between configurations within 48-hour turnaround windows. Gulf carriers consolidating wide-body fleet specifications around single-source accountability frameworks favor these platforms for seasonal demand adaptation.
- Lie-flat:Electromechanical actuation with shape-memory alloy precision delivers zero-gravity positioning without hydraulic fluid maintenance. Long-haul premium cabin deployments concentrate among Asia-Pacific full-service carriers competing on sleep quality metrics.
- Recliner:Pneumatic or mechanical tilt mechanisms dominate narrow-body short-haul applications.
- Sleeper:Angled flat-bed designs occupy a narrowing market niche between recliner and full lie-flat functionality.
Modular platforms lead procurement discussions for new fleet deliveries, while Lie-flat technology captures the steepest margin expansion trajectory.
Application:
Installation base fragmentation creates divergent certification pathways and aftermarket service requirements.
- Commercial Airlines:Scheduled carriers operating narrow-body and wide-body fleets generate the dominant addressable market. Fleet renewal programs across United States majors and European legacy operators compress replacement timelines amid stricter EASA crashworthiness protocols.
- Private Jets:Custom interiors with bespoke upholstery and personalized IFE integration serve ultra-high-net-worth owner-operators. Completion centers in Wichita and Toulouse concentrate final assembly for this segment.
- Military Aircraft:Troop transport and VIP configurations require specialized restraint systems and ballistic protection compatibility.
- Cargo Planes:Quick-change combi configurations and supernumerary crew seating represent a thin volume layer.
Commercial Airlines anchor absolute shipment volumes, with Private Jets expanding most quickly on post-pandemic personal aviation demand.
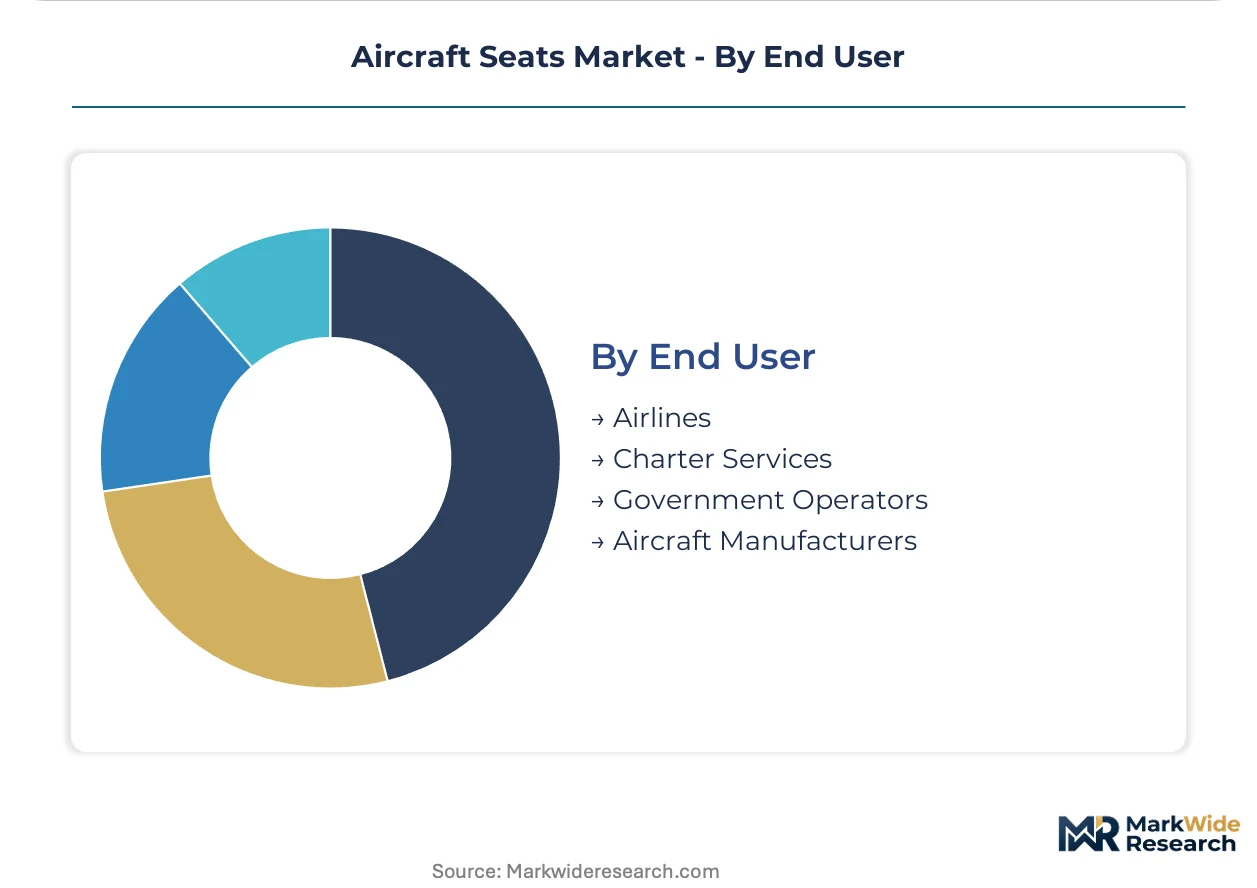
End User:
Procurement authority distribution shapes vendor relationship structures and contract duration preferences.
- Airlines:Technical procurement teams at United States majors and European flag carriers consolidate vendor relationships around integrated seat-IFE-power bundles. Single-source accountability frameworks now displace discrete subsystem contracting.
- Aircraft Manufacturers:Boeing and Airbus line-fit programs at final assembly lines in Washington State and Toulouse provide specification influence without direct procurement ownership.
- Charter Services:Fractional ownership operators and on-demand charter fleets prioritize rapid reconfiguration capability over customization depth.
- Government Operators:Presidential and ministerial transport programs impose security-cleared supply chain requirements.
Airlines dominate direct procurement spend, with Aircraft Manufacturers gaining specification influence through line-fit partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized structural engineers in dynamic load simulation and crash kinematics cluster in Toulouse, Wichita, and Hamburg, anchoring design capabilities that concentrate procurement influence among carriers operating from these regions.
United States
Domestic fleet renewal at major carriers compresses retrofit timelines for narrow-body platforms. FAA TSO-C127b amendments mandate 16g dynamic testing that extends certification durations. Wichita hosts completion centers serving private jet operators with bespoke interior integration.
Germany
Full-service carriers on transatlantic routes drive lie-flat mechanism demand from Frankfurt and Munich hubs. EASA CS-25 cabin safety amendments elevate engineering standards that filter to regional procurement specifications. Hamburg anchors premium seat final assembly capacity with captive crash-test facilities.
France
Toulouse concentrates aerospace engineering talent for finite element modeling and multi-axis loading prediction. EASA expanded dynamic testing requirements now add 8-14 months to type certification timelines. The city's supplier ecosystem serves both Airbus line-fit programs and airline direct procurement.
United Kingdom
Gulf carrier wide-body fleet modernization creates specification complexity that favors integrated seat-IFE-power bundling. CAA alignment with EASA standards streamlines dual-approval pathways. Thompson Aero Seating exemplifies specialists occupying the premium-tier reconfiguration segment.
India
Domestic airline fleet expansion attracts seat subsystem manufacturers under the PLI scheme for aerospace components. DGFT import dependency reduction targets accelerate local assembly capacity establishment. Maharashtra and Karnataka host emerging MRO clusters serving narrow-body retrofit demand.
Aircraft Seats Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base separates into three strategic archetypes: vertically integrated platform providers, component-specialist subsystem vendors, and regional assembly contractors. Consolidation pressures favor manufacturers with captive crash-test facilities and in-house electronics integration. Geographic expansion and strategic partnerships constitute the dominant competitive moves as vendors seek to bypass Western European supply concentration.
Among France-based diversified aerospace conglomerates, Safran anchors the integrated platform tier through backward integration from composites to final assembly. RECARO Aircraft Seating GmbH exemplifies the specialist archetype with concentrated R&D intensity in lightweight thermoplastic applications. Raytheon Technologies Corporation represents the diversified conglomerate model with cross-divisional technology transfer capabilities. These three occupy positions that reflect the market's structural tension between scale-driven bundling and focused technical specialization.
| Leading Market Players |
|---|
| Safran |
| Raytheon Technologies Corporation |
| RECARO Aircraft Seating |
| STELIA Aerospace |
| Collins Aerospace |
| Geven S.p.A. |
| Jamco Corporation |
| Thompson Aero Seating |
| ZIM Aircraft Seating |
| Others |
Pricing and Supply Chain Analysis
Airline technical procurement teams at United States majors and European flag carriers concentrate buying power around integrated seat-IFE-power bundles, forcing a contract-based long-term offtake model with price differentiation anchored in certification tier and after-sales service depth.
Pricing Analysis
Seat-IFE-power bundling versus discrete subsystem contracting splits the market into two pricing paradigms. Three-tier pricing structure across premium lie-flat, standard recliner, and economy levels tracks certification grade and volume scale. Cost compression in economy aluminum-composite hybrids is intensifying because bulk orders from narrow-body fleet renewals compress supplier pricing power. Charter services and fractional ownership operators exhibit highest price sensitivity, while Gulf carriers on wide-body programs prioritize single-source accountability over hardware price differentials.
Supply Chain Analysis
India's PLI scheme for aerospace components and Brazil's ANVISA alignment with FAA standards are reshaping sourcing patterns away from Western European concentration. Premium seat final assembly draws from Germany, France, and the United Kingdom, with carbon fiber-reinforced thermoplastic frames and fire-blocking polyurethane foam as critical inputs. Single-source vulnerability runs through Hamburg and Toulouse captive crash-test facilities. Distribution feeds from final assembly lines through airline direct procurement and Boeing-Airbus line-fit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI incentives and lower engineering labor costs versus Germany's EASA-aligned certification infrastructure create divergent cost structures for equivalent seat platforms.
For Market Incumbents: Extend captive crash-test facility utilization across multiple regulatory jurisdictions to compress EASA timeline extensions. Deepen backward integration into carbon fiber-reinforced thermoplastic production to defend margin position against raw material volatility. Lock long-term supply contracts with indexed pricing clauses to buffer titanium and aluminum cost swings. For New Entrants and Emerging Players: Launch via subsystem specialization in quick-release track systems or shape-memory alloy actuators rather than full-platform competition. India's emerging MRO clusters in Maharashtra and Karnataka offer the most penetrable geography for narrow-body retrofit programs. Target ANVISA-FAA dual-approval consulting as a service layer to reduce regulatory friction for LATAM carrier access. For Investors and Strategic Acquirers: Tier 1 aerospace conglomerates seeking cabin integration capabilities are the most active acquirer in this space. The five-to-ten year viability window favors specialists with in-house finite element modeling and multi-axis loading prediction. Acquisition target archetype: pure-play seat manufacturers with EASA CS-25 certification momentum but constrained capital for IFE integration. Watch EASA dynamic testing backlog as inflection signal for certification timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Crash-Test Facility Expansion | EASA CS-25 amendments elevate barriers to suppliers without in-house dynamic testing in France or Germany. |
| Carbon Fiber Thermoplastic Integration | Safran's backward integration into composites sustains margin control across European airline programs. |
| Seat-IFE-Power Bundling | Gulf carrier procurement consolidation favors manufacturers with electronics integration under single-source accountability. |
| PLI-Aligned Local Assembly | India's component manufacturing incentives attract subsystem vendors to Maharashtra and Karnataka MRO clusters. |
| ANVISA-FAA Dual-Approval Pathway | Brazilian regulatory alignment streamlines LATAM retrofit access for seat vendors with existing FAA certification. |
Research Methodology
Multiple input streams — primary technical interviews, regulatory filing analysis, and production database cross-referencing — were reconciled to construct market estimates. Conversations with airline procurement directors, aircraft interior program managers, EASA certification engineers, and MRO operations heads informed demand-side validation. Secondary sources included FAA TSO-C127b amendment records, EASA CS-25 cabin safety documentation, airline fleet renewal announcements, and customs trade data for aerospace components. Bottom-up seat shipment modeling and top-down fleet projection alignment provided triangulation checks.
Historical delivery patterns were cross-referenced against expert panel inputs on fleet renewal timing and retrofit program acceleration. Segmentation modeling spanned cabin class, platform technology, and carrier type across the projection horizon. CAGRs emerged from fitted curves on narrow-body and wide-body delivery schedules, weighted by seat count per airframe and replacement cycle compression. Fuel-burn reduction metrics and crashworthiness testing timeline extensions served as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FAA-EASA regulatory divergence or sustained titanium-aluminum price volatility. Estimates reflect documented assumptions on fleet renewal pace and certification timeline standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market