
 Heel Incision Devices Market | 2026-2036
Heel Incision Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Heel Incision Devices Market Analysis
Hospital procurement consortiums is rewriting how heel incision devices reach end users, consolidating purchasing power across multi-facility networks. BD leverages its broad anesthesia and critical care portfolio to bundle heel incision tools into larger neonatal supply contracts. Owen Mumford Limited anchors its position through specialized lancet engineering and OEM partnerships with diagnostic instrument manufacturers.
Heel incision devices are precision surgical instruments designed to create controlled capillary blood draws from neonatal heels, typically employing spring-loaded or electrosurgical mechanisms with blade depths calibrated to 0.85–2.0 millimeters for safe infant tissue penetration. Stainless steel instruments dominate hospital procurement due to established sterilization protocols and durability under autoclave cycling, while polymer-based disposable variants gain traction in outpatient clinics prioritizing infection control and reduced reprocessing overhead. Electrosurgical devices command premium positioning in surgical centers where integration with cautery systems streamlines workflow, though traditional scalpel formats persist in cost-sensitive diagnostic settings.
The US FDA 510(k) framework governs device safety and substantial equivalence for market entry, while the EU MDR imposes stricter clinical evidence requirements on manufacturers seeking CE marking for European distribution. Japan's PMDA maintains distinct quality management system audits that extend approval timelines but reinforce product reliability standards. Stakeholders must monitor evolving harmonization efforts between FDA and MDR clinical data expectations, as divergence in predicate device acceptability could fragment development roadmaps and force parallel regulatory investments.
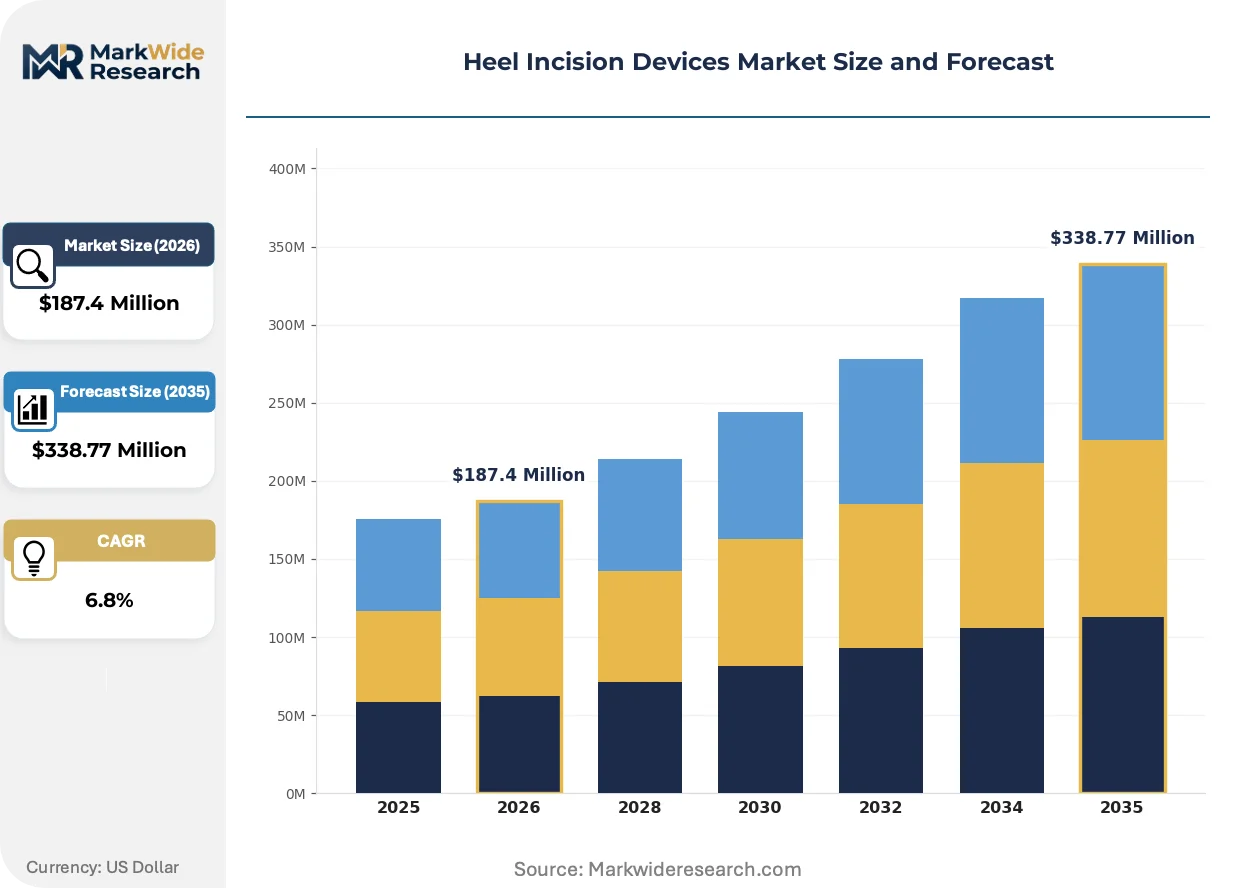
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across multi-facility networks, forcing manufacturers to restructure pricing and bundling strategies around neonatal supply contracts rather than standalone device sales.
Growth Catalysts
- Newborn screening mandates:The United States, Germany, and Japan enforce stringent heel-stick blood collection protocols for metabolic disorder detection, creating baseline demand for automated incision tools.
- Spring-loaded mechanism refinement:Calibrated blade depths between 0.85–2.0 millimeters now enable safer infant tissue penetration, reducing iatrogenic injury rates and driving NICU adoption.
- Diagnostic instrument integration:OEM partnerships between lancet engineers and laboratory automation manufacturers embed heel incision devices into closed-loop screening workflows.
Market Restraints
- Stainless steel sterilization overhead:Autoclave cycling requirements impose recurring operational costs on hospitals maintaining reusable instrument inventories.
- EU MDR clinical evidence burden:Stricter predicate device acceptability standards extend CE marking timelines and force parallel regulatory investments for European market entry.
- Polymer-based disposables cost premium:Single-use variants command higher per-procedure pricing than reprocessable alternatives, limiting penetration in cost-sensitive outpatient settings.
Strategic Opportunities
- Outpatient clinic channel expansion:Polymer-based disposable formats align with infection control priorities in non-hospital diagnostic settings, creating white space beyond NICU concentration.
- Electrosurgical-cautery convergence:Integration with existing surgical energy systems positions premium devices in ambulatory surgical centers seeking workflow streamlining.
- Japan PMDA quality premium:Extended approval timelines reinforce reliability standards that manufacturers can leverage for differentiated positioning in high-integrity Asian markets.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 material safety evaluations for polymer blade substrates extend product development cycles before regulatory submission.
- Legacy sterilization protocol incompatibility:Electrosurgical device electronics require specialized reprocessing workflows that conflict with established hospital central sterile supply department capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heel Incision Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Scalpel, Surgical Knife, Electrosurgical Device, Biopsy Punch Usage: Minimally Invasive Surgery, Traditional Surgery, Outpatient Procedures, Diagnostic Procedures Material: Stainless Steel, Carbon Steel, Polymer, Coated Metal End User: Hospitals, Surgical Centers, Clinics, Research Facilities |
| Companies Covered | BD, Cardinal Health, Owen Mumford Limited, Smiths Medical, Clinical Innovations, MEDIcore Co., LTD., Vitrex Medical A/S, NSP Tech Pte Ltd., Torvan Medical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heel Incision Devices Market Emerging Trajectories
Device architecture is pivoting from mechanical spring systems toward electrosurgical integration, while regulatory data requirements harden across major jurisdictions and procurement centralization restructures commercial access.
Micro-electrode cautery tips are virtualizing the traditional mechanical lancet function by replacing physical blade penetration with controlled thermal tissue disruption. Ambulatory surgical centers in Germany and Japan are piloting these systems at accelerated evaluation paces. This convergence is virtualizing the standalone heel incision device category into broader electrosurgical platform ecosystems, compressing addressable market boundaries for pure-play mechanical manufacturers.
EU MDR predicate device acceptability rules are tightening clinical evidence standards for Class II surgical instruments seeking CE marking renewal. Manufacturers must now generate original clinical data rather than relying on historical equivalence demonstrations. European distribution strategies face 12–18 month timeline extensions, prompting some suppliers to deprioritize continental European markets in favor of FDA 510(k) pathway efficiency.
Consortium purchasing agreements are consolidating formerly fragmented hospital buying decisions into multi-year, multi-facility supply contracts with standardized device specifications. Group purchasing organizations now dictate blade depth calibration and sterilization compatibility requirements that individual manufacturers must accommodate. This concentration is most visible in United States health systems where three major purchasing alliances control NICU supply access for over forty percent of annual births.
Heel Incision Devices Market Segmentation
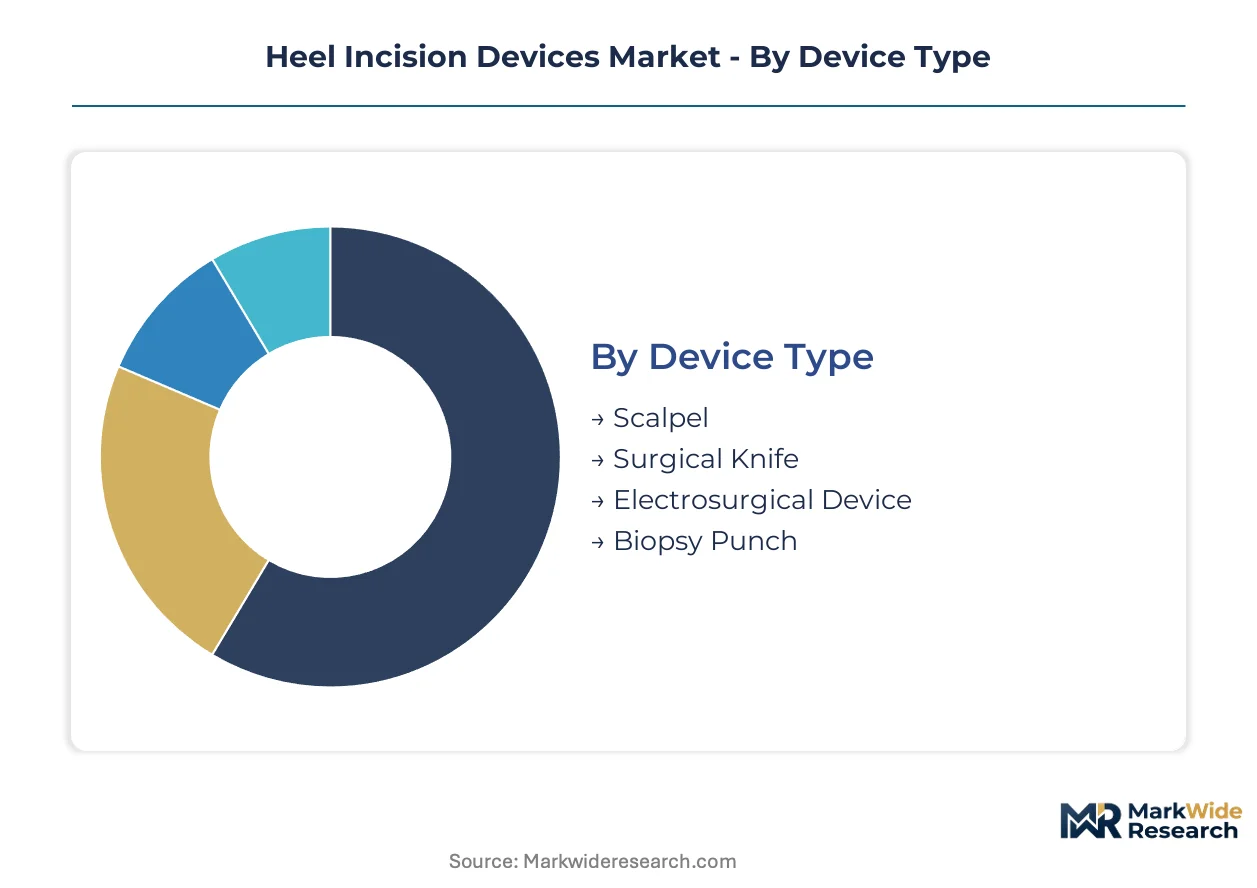
Heel incision devices fragment across four distinct taxonomies that reshape procurement priorities and regulatory pathways. Device architecture, clinical setting, material substrate, and facility type each impose incompatible technical specifications and commercial access routes.
Device Type:
Mature mechanical formats coexist with emerging energy-based alternatives across the maturity spectrum.
- Scalpel:Traditional handheld blades with fixed or retractable edges deliver precise linear incisions at minimal unit cost. Demand concentrates in United States outpatient clinics where cost containment overrides automation preferences.
- Surgical Knife:Refined blade geometries with ergonomic handles improve operator control during repetitive neonatal procedures. German hospital systems specify these instruments for standardized heel-stick protocols under national newborn screening mandates.
- Electrosurgical Device:Thermal tissue disruption via micro-electrode tips.
- Biopsy Punch:Circular cutting heads for targeted tissue sampling.
Scalpel formats retain volume leadership; electrosurgical devices hold the steepest expansion curve.
Usage:
Procedure invasiveness stratifies device selection from controlled capillary draws to operative interventions.
- Minimally Invasive Surgery:Small-portal techniques demand compact instrument profiles with reduced tissue trauma. Japanese NICUs favor these approaches for preterm infant blood collection where tissue preservation is paramount.
- Traditional Surgery:Open procedural access permits larger instrument formats with established sterilization protocols. United States hospital consortiums standardize on these devices across multi-facility networks for supply chain simplicity.
- Outpatient Procedures:Rapid-turnover diagnostic settings.
- Diagnostic Procedures:Laboratory-integrated screening workflows.
Traditional surgery commands installed base dominance; minimally invasive applications are gaining share fastest.
Material:
Substrate selection trades durability against reprocessing economics and biocompatibility certification burden.
- Stainless Steel:Austenitic grades withstand repeated autoclave cycling above 121°C without dimensional degradation. United States central sterile supply departments specify these alloys for reusable instrument inventories under AAMI sterilization standards.
- Carbon Steel:Higher hardness edges maintain sharpness through extended use cycles. Cost-sensitive clinics in Germany deploy these instruments where blade replacement economics favor disposability over reprocessing investment.
- Polymer:Single-use thermoplastic substrates.
- Coated Metal:Surface-modified alloys for friction reduction.
Stainless steel retains procurement volume leadership; polymer substrates climb the fastest as infection control priorities harden.
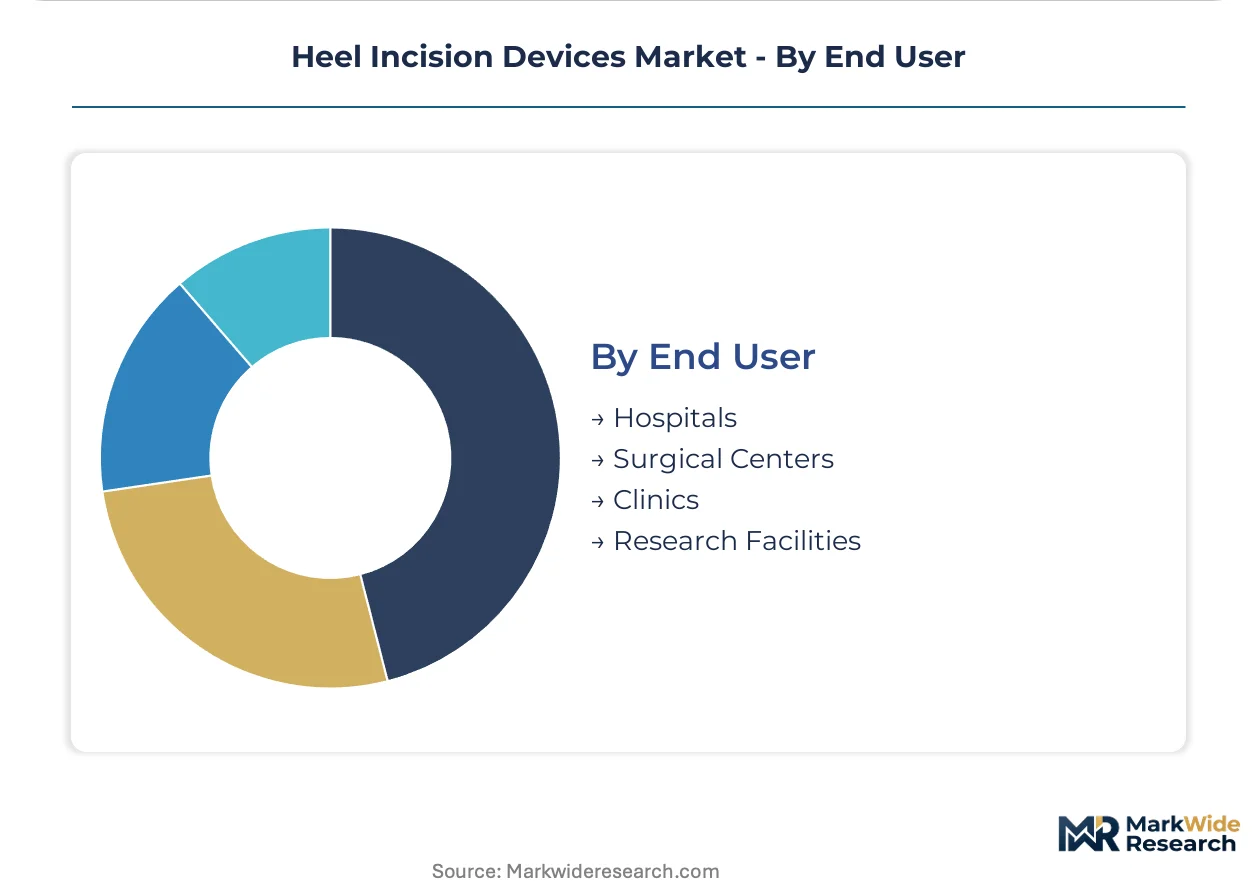
End User:
Facility scale and clinical mission dictate purchasing authority and technical specification complexity.
- Hospitals:Integrated health systems with neonatal intensive care units drive automated heel incision adoption. United States group purchasing organizations consolidate multi-year supply contracts specifying blade depth calibration and sterilization compatibility across birth centers handling over forty percent of annual deliveries.
- Surgical Centers:Ambulatory facilities prioritize workflow integration with existing energy platforms. German and Japanese pilot programs evaluate electrosurgical-cautery convergence for procedural efficiency gains.
- Clinics:Distributed diagnostic access points.
- Research Facilities:Protocol-driven blood collection for longitudinal studies.
Hospitals retain volume leadership; surgical centers show the steepest expansion trajectory as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA newborn screening mandates in the United States generate the dominant procurement volume for automated heel incision systems, while regulatory stringency in Germany and Japan sustains premium-tier demand for precision-engineered instruments.
United States
Group purchasing organizations consolidate NICU supply contracts across multi-facility networks handling over forty percent of annual births. FDA 510(k) clearance pathways enable rapid product iteration for Class II surgical instruments. Boston and Philadelphia medical device clusters host development operations for spring-loaded mechanism refinement.
Germany
National newborn screening mandates enforce standardized heel-stick protocols across hospital systems. EU MDR clinical evidence requirements extend CE marking timelines but reinforce predicate device standards for blade depth calibration. Baden-Württemberg surgical instrument manufacturers supply precision-engineered lancets to European diagnostic networks.
Japan
PMDA quality management system audits extend approval timelines while reinforcing reliability benchmarks for neonatal intensive care applications. METI industrial standards guide domestic manufacturing of minimally invasive surgical instruments. Osaka and Nagoya medical device corridors pilot electrosurgical-cautery convergence programs.
United Kingdom
NHS procurement frameworks standardize heel incision device specifications across maternity and pediatric services. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR safety standards while streamlining domestic market entry. London and Cambridge medtech clusters develop polymer-based disposable formats for outpatient diagnostic expansion.
India
CDSCO medical device rules classify heel incision instruments under regulated surgical tool categories, mandating quality system compliance for import and domestic manufacture. National newborn screening program expansion drives diagnostic infrastructure investment. Maharashtra and Karnataka medical device parks attract contract manufacturing for polymer substrate instruments.
Heel Incision Devices Market Vendor Landscape
Diversified medical technology conglomerates and specialized surgical instrument fabricators split the market into distinct capability tiers. Hospital procurement consortiums favor suppliers with broad anesthesia and critical care portfolios that enable bundled neonatal supply contracting. Two strategic archetypes dominate: integrated health system vendors leveraging cross-category scale, and precision engineering specialists anchoring OEM partnerships with diagnostic automation manufacturers. Competitive maneuvering concentrates on portfolio bundling into multi-year group purchasing agreements and regulatory pathway efficiency across FDA, EU MDR, and PMDA jurisdictions.
Within the diversified conglomerate tier, BD and Cardinal Health occupy positions shaped by cross-category hospital supply relationships. Owen Mumford Limited exemplifies the specialized engineering archetype, with its limited company structure indicating focused operational scope on precision lancet development. These three anchors illustrate how market access increasingly depends on either procurement consortium integration or technical specialization in blade depth calibration and sterilization compatibility.
| Leading Market Players |
|---|
| BD |
| Cardinal Health |
| Owen Mumford Limited |
| Smiths Medical |
| Clinical Innovations |
| MEDIcore Co., LTD. |
| Vitrex Medical A/S |
| NSP Tech Pte Ltd. |
| Torvan Medical Inc |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's precision surgical instrument cluster anchors European manufacturing capacity for heel incision devices, with its specialized lancet engineering expertise translating into downstream pricing power for premium-tier electrosurgical formats. This geographic concentration enables manufacturers serving German hospital systems to command blade-depth calibration premiums that resist cost compression in automated neonatal screening workflows.
Pricing Analysis
Price spreads between United States and German procurement markets exceed those seen in other Class II surgical instrument categories, reflecting divergent sterilization protocol economics and regulatory compliance burdens. Three-tier pricing structure across premium electrosurgical, standard spring-loaded, and economy scalpel levels stratifies by certification tier and after-sales service bundling. Pricing pressure stems from polymer-based disposable cost premiums limiting outpatient clinic penetration. Hospital group purchasing organizations demonstrate lowest price sensitivity due to multi-year contract security, while independent diagnostic laboratories face acute margin constraints.
Supply Chain Analysis
Tariff exposure between United States and Chinese polymer substrate suppliers dominates supply chain risk calculations for disposable format manufacturers. Component sourcing draws from German stainless steel processors, Japanese precision spring manufacturers, and United States thermoplastic resin suppliers. Single-source vulnerability concentrates in micro-electrode cautery tip fabrication, where Japanese metallurgical expertise limits qualified vendor pools. Distribution runs through hospital procurement consortiums and diagnostic instrument OEM partnerships rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as electrosurgical-cautery convergence virtualizes standalone heel incision devices into broader energy system ecosystems, rewarding suppliers with existing surgical platform installed bases.
For Market Incumbents: Entrench position through backward integration into precision blade substrate manufacturing, capturing margin currently flowing to Japanese and German metallurgical suppliers. Deepen vertical control over sterilization-compatible coating technologies to neutralize polymer disposable substitution threats. Prioritize FDA 510(k) pathway efficiency over EU MDR clinical evidence investments given timeline divergence risks. For New Entrants and Emerging Players: India's diagnostic infrastructure expansion presents the most penetrable geographic entry point, with CDSCO regulatory compliance costs below FDA or PMDA barriers and national newborn screening program growth creating demand tailwinds. Target polymer-based disposable formats for outpatient clinic channels where infection control priorities override cost sensitivity. Pursue OEM partnerships with laboratory automation manufacturers to embed devices into closed-loop screening workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core neonatal instrument portfolios. Five-to-ten-year viability hinges on electrosurgical platform integration capabilities rather than mechanical lancet manufacturing scale. Monitor PMDA approval timeline compression as signal that Japanese quality premium positioning is eroding, potentially reallocating investment toward FDA-efficient suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | EU MDR clinical evidence requirements force 12–18 month timeline extensions that reshape European market prioritization. |
| Hospital System Partnership | Group purchasing organization consolidation across United States birth centers mandates multi-facility contract negotiation capabilities. |
| Diagnostic Instrument Integration | OEM partnerships with laboratory automation manufacturers embed heel incision devices into closed-loop newborn screening workflows. |
| Polymer Substrate Development | ISO 10993 biocompatibility certification for single-use thermoplastic formats opens outpatient clinic channel expansion. |
| Reimbursement Strategy | Newborn screening mandate coverage under national health programs in Germany and Japan ensures procedure volume stability. |
Methodological Framework
Cross-validation between primary interviews with neonatal intensive care unit directors, hospital procurement committee members, biomedical engineers specializing in surgical instrument sterilization, and group purchasing organization contract managers anchors the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, EU MDR notified body submission records, PMDA quality management system audit reports, and hospital supply chain procurement databases. Bottom-up demand modeling from individual facility adoption rates triangulates against top-down market sizing from regulatory filing volumes and trade flow analysis.
Calibration against historical adoption curves for comparable Class II surgical instruments informs the projection framework across the analysis window. Segmentation dimensions include device architecture, clinical setting invasiveness level, material substrate composition, and end-user facility type. CAGRs derive from installed base growth rates adjusted for replacement cycle compression and technology substitution effects. Forecast inputs incorporate newborn screening mandate expansion timelines and regulatory pathway efficiency differentials between FDA, EU MDR, and PMDA jurisdictions.
Practitioners should monitor EU MDR predicate device acceptability rule evolution and polymer substrate biocompatibility testing timeline extensions for early signals of forecast revision needs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Blood Lancet Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Gastric Bands Market
Medical Devices
Electrophysiology Market
Medical Devices
Global Dermatome Device Market