
 Crack-Bridging Flexible Polymer Additives for Repair Mortars Market | 2026-2036
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market Size, Share, and Industry Trends Forecast 2026-2036
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market Insights
Qualified polymer chemists and formulation engineers is collapsing across Western Europe, constraining R&D throughput for next-generation crack-bridging systems. Sika leverages its integrated supply chain from monomer synthesis to packaged additive to sustain rapid customer response times. Master Builders Solutions anchors its competitive stance through deep specialization in cement-compatible redispersible polymer powders. Wacker Chemie dominates the silicone-modified acrylic segment for exterior wall repair applications requiring UV-stable flexibility.
Crack-bridging flexible polymer additives comprise elastomeric compounds—typically styrene-butadiene rubber latices, acrylic copolymer dispersions, or carboxylated vinyl polymers—dispersed within cementitious matrices to impart tensile strain capacity exceeding 3% at mortar interfaces. These additives functionally transform brittle repair mortars into compliant overlays capable of accommodating substrate movement, thermal cycling, and drying shrinkage without delamination. Acrylic copolymers command the premium tier in floor restoration owing to superior alkali resistance and adhesion to damp concrete, while ethylene vinyl acetate emulsions occupy the volume-driven pavement rehabilitation segment where cost efficiency outweighs extreme performance requirements. Powder-form redispersible polymers are accelerating fastest as pre-packaged dry-mix mortars displace site-blended liquid systems across European construction contractors.
REACH registration requirements and the EU Green Deal's chemical sustainability thresholds are restricting phthalate-plasticized formulations while accelerating bio-based acrylic development. Germany's KBA and federal building codes mandate minimum crack-bridging class ratings for concrete bridge deck overlays, directly conditioning product specification lists. ECHA's evolving restrictions on styrene monomer residuals are forcing reformulation investments across SBR latex producers. Stakeholders must monitor polymer feedstock volatility and pre-emptively certify additive portfolios against impending EU Construction Products Regulation amendments on durability testing protocols.
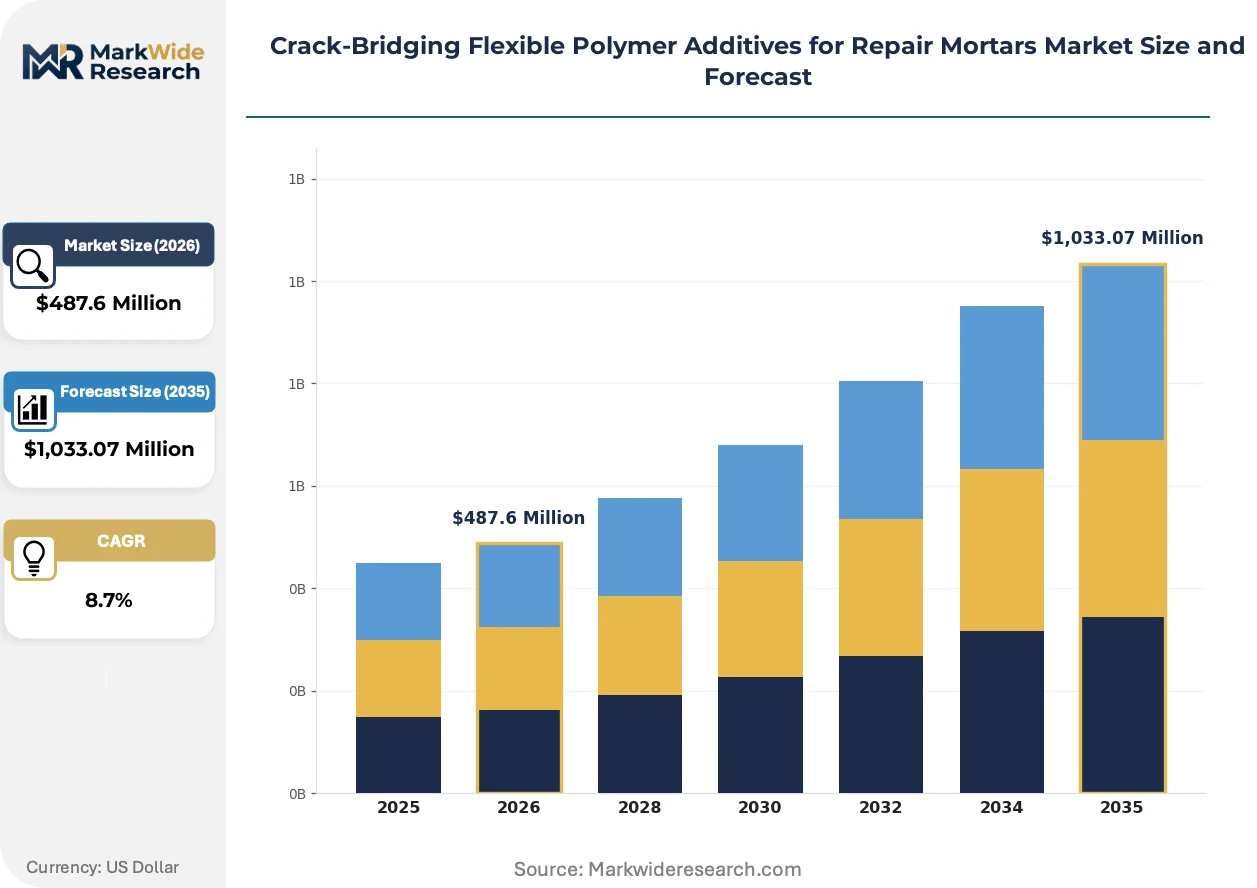
Market Dynamics
Germany's federal infrastructure renewal programs are concentrating demand for crack-bridging repair systems, while REACH and F-Gas Regulation compliance costs are restructuring formulation portfolios across European additive producers.
Growth Catalysts
- Aging concrete infrastructure:Bridge deck maintenance and pavement rehabilitation across Germany, France, and Italy are expanding procurement volumes for compliant polymer-modified mortars.
- EU Green Deal chemical sustainability thresholds:Bio-based acrylic development is accelerating as phthalate-plasticized formulations face registration restrictions under evolving ECHA frameworks.
- Redispersible polymer powders:Pre-packaged dry-mix mortars are displacing site-blended liquid systems among European construction contractors seeking quality consistency and reduced waste.
Market Restraints
- Styrene monomer residual restrictions:ECHA's evolving limits on SBR latex formulations are forcing costly reformulation investments without immediate performance parity guarantees.
- Qualified polymer chemist scarcity:Western Europe's collapsing pool of formulation engineers is constraining R&D throughput for next-generation crack-bridging systems.
- Acrylic copolymer feedstock volatility:Petrochemical price swings are compressing margins for premium-tier floor restoration additives where alkali resistance commands specification.
Strategic Opportunities
- Silicone-modified acrylic exterior applications:UV-stable flexibility requirements for wall repair systems in Mediterranean climates are opening premium positioning for specialized additive portfolios.
- Pre-packaged dry-mix channel expansion:Building material distributors are consolidating shelf space for certified repair mortars, displacing commodity cement blends in professional contractor segments.
- Federal building code alignment:Germany's KBA minimum crack-bridging class ratings for bridge deck overlays are conditioning specification lists that favor certified additive suppliers.
Industry Challenges
- Certification timeline compression:EU Construction Products Regulation amendments on durability testing protocols are requiring pre-emptive portfolio recertification before enforcement dates.
- Legacy liquid system integration:Site-blended additive workflows among established contractor networks resist conversion to powder-form dry-mix protocols despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crack-Bridging Flexible Polymer Additives for Repair Mortars Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene-Butadiene Rubber, Acrylic Copolymers, Ethylene Vinyl Acetate, Polyurethane, Carboxylated Vinyl Polymer Form: Liquid, Powder, Emulsion, Dispersion, Solvent-based Application: Exterior Wall Repair, Floor Restoration, Concrete Roofing Fix, Bridge Deck Maintenance, Pavement Rehabilitation End User Industry: Construction Contractors, Building Maintenance Firms, Civil Engineering Firms, Infrastructure Management Companies, Specialty Repair Services |
| Companies Covered | Sika, Master Builders Solutions, Mapei, Wacker Chemie, Dow, Arkema, Synthomer, Celanese, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market Trends and Innovations
Formulation chemistry is pivoting toward bio-based feedstocks and powder-dispersion technologies, while regulatory pressure on residual monomers and solvent content is compressing acceptable formulation windows.
Redispersible polymer powder technology is bifurcating the repair mortar supply chain. Cement-compatible acrylic and vinyl acetate-ethylene copolymers in spray-dried form enable extended shelf stability and precise dosing control. Major German civil engineering contractors are specifying powder-only systems for federal bridge deck contracts. This shift is bifurcating procurement patterns between integrated dry-mix suppliers and traditional liquid latex distributors.
REACH registration requirements and the EU F-Gas Regulation are tightening solvent-based formulation specifications. ECHA's progressive restrictions on styrene residuals in SBR latices are eliminating cost-competitive options for pavement rehabilitation segments. Producers are responding with carboxylated vinyl polymer alternatives and bio-acrylic development programs, though performance benchmarking against legacy systems remains incomplete.
Specification-driven procurement is consolidating buyer decision authority around certified additive portfolios. German federal infrastructure tenders now mandate third-party crack-bridging class verification, compressing vendor qualification lists. Building material distributors are capturing specification influence through exclusive dry-mix partnerships. Southern European facade restoration contractors are demonstrating strongest uptake of silicone-modified acrylic systems for UV-exposed applications.
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market Segmentation
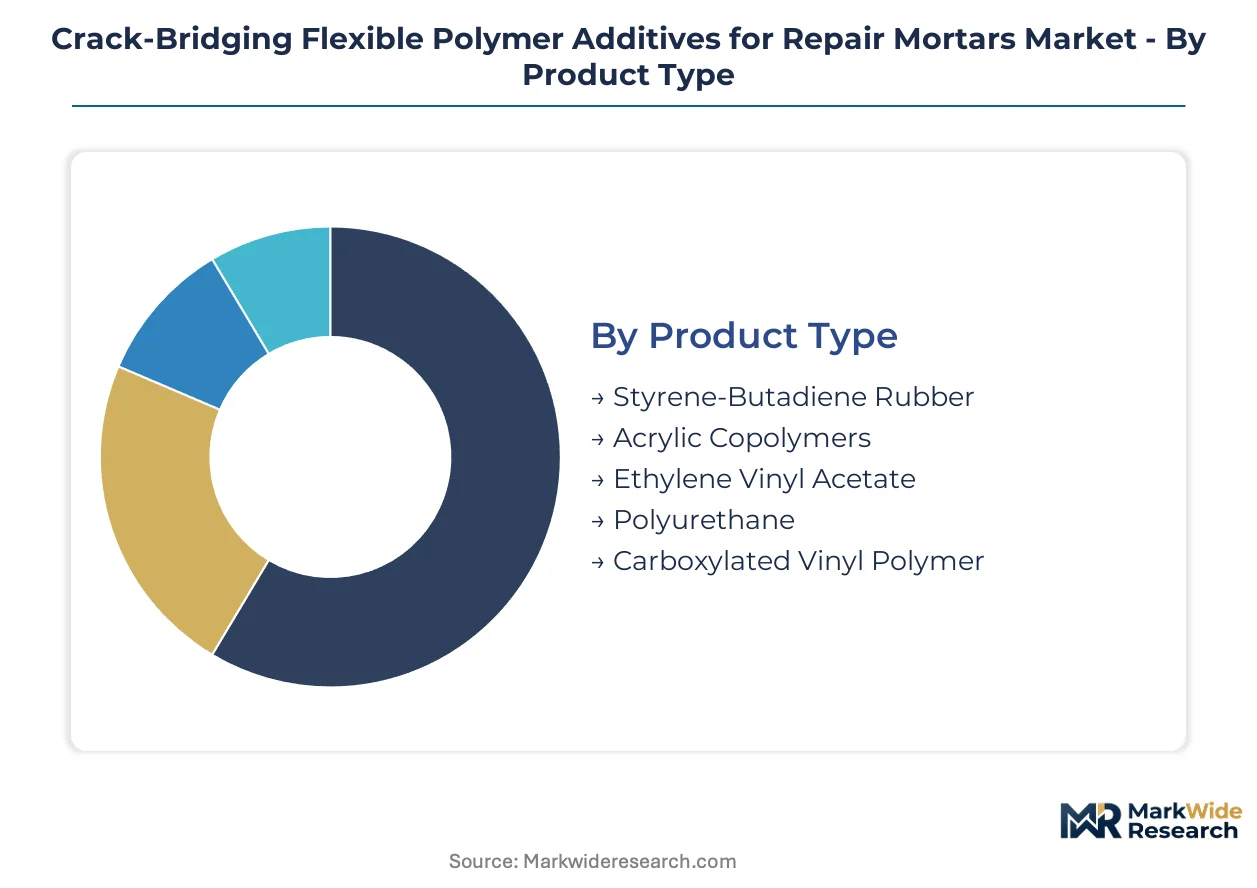
Polymer additive segmentation reveals distinct margin architectures across chemistry types, with premium acrylics commanding specification-driven pricing while commodity SBR latices compete on volume. Form factor choices increasingly determine supply chain economics as powder technologies displace liquid systems.
Product Type:
Margin pools concentrate in alkali-resistant acrylic formulations and UV-stable silicone-modified variants, while commodity styrenic systems face compression from regulatory compliance costs.
- Acrylic Copolymers:These carboxylated polymer dispersions deliver superior adhesion to damp concrete substrates and exceptional alkali resistance for floor restoration applications. German federal bridge deck specifications increasingly mandate acrylic-based systems for their crack-bridging class ratings. REACH compliance costs are accelerating bio-based acrylic development programs.
- Styrene-Butadiene Rubber:SBR latices historically dominated pavement rehabilitation volumes through cost-efficient styrenic backbone chemistry. ECHA's tightening residual monomer restrictions are forcing costly reformulation investments across European producers. Southern European contractors still specify SBR for non-structural highway overlays where extreme flexibility demands are moderate.
- Ethylene Vinyl Acetate:EVA emulsions balance cost efficiency with adequate performance for volume-driven infrastructure repair segments.
- Polyurethane:Two-component polyurethane systems target premium structural bonding applications requiring extreme tensile strain capacity.
- Carboxylated Vinyl Polymer:Vinyl acetate-based alternatives are gaining specification share as direct replacements for restricted SBR formulations in pavement maintenance.
The dominant share belongs to Styrene-Butadiene Rubber, while Acrylic Copolymers is closing the gap fastest.
Form:
Supply chain configuration favors powder technologies enabling extended shelf stability and precise dosing control at construction sites.
- Powder:Redispersible polymer powders in spray-dried acrylic and vinyl acetate-ethylene copolymer forms are displacing liquid systems across German civil engineering contractors. Federal bridge deck contracts now specify powder-only protocols for quality consistency. Building material distributors are consolidating shelf space around certified dry-mix additive portfolios.
- Liquid:Traditional latex emulsions retain entrenched contractor workflows despite powder conversion trends, particularly among established site-blending operations resisting protocol changes.
- Emulsion:Water-based polymer emulsions serve intermediate applications where immediate re-dispersibility is valued over extended storage.
- Dispersion:High-solids dispersions target specialized repair mortars requiring concentrated polymer loading.
- Solvent-based:F-Gas Regulation compliance costs are eliminating solvent-carrier formulations from European specification lists.
Powder holds the installed base advantage, though Emulsion retains pockets of contractor loyalty.
Application:
Specification intensity varies sharply by exposure conditions, with exterior vertical surfaces and trafficked horizontal decks demanding certified performance tiers.
- Bridge Deck Maintenance:German KBA-mandated crack-bridging class ratings condition vendor qualification lists for federal infrastructure tenders. Polymer-modified overlays must accommodate thermal cycling, de-icing salt exposure, and dynamic load deflection without delamination. Third-party certification requirements compress acceptable additive portfolios to pre-qualified suppliers.
- Exterior Wall Repair:Mediterranean climate facade restoration contractors demonstrate strongest uptake of silicone-modified acrylic systems for UV-stable flexibility. Southern European building codes are progressively aligning with German durability testing protocols.
- Floor Restoration:Acrylic copolymers dominate premium-tier specifications where alkali resistance and damp substrate adhesion are non-negotiable.
- Concrete Roofing Fix:Elastomeric polymer selection prioritizes ponding water resistance and thermal shock accommodation.
- Pavement Rehabilitation:Cost efficiency drives specification toward EVA and reformulated vinyl polymer alternatives in highway maintenance segments.
Bridge Deck Maintenance commands the specification premium, while Exterior Wall Repair is expanding most quickly on climate adaptation investment.
End User Industry:
Procurement authority concentrates in civil engineering firms managing federal infrastructure contracts, with building maintenance firms representing fragmented volume opportunity.
- Civil Engineering Firms:These entities control specification lists for Germany's federal bridge deck and highway renewal programs, mandating certified crack-bridging class ratings. Their procurement volumes are expanding fastest under infrastructure stimulus allocations. Technical qualification requirements exclude commodity additive suppliers from tender participation.
- Construction Contractors:General contractors face bifurcating procurement patterns between integrated dry-mix suppliers and traditional liquid latex distributors. Federal project mandates are accelerating powder system conversion despite established site-blending workflows.
- Building Maintenance Firms:Facility maintenance operators prioritize pre-packaged repair mortars for reduced waste and quality consistency in commercial property portfolios.
- Infrastructure Management Companies:Asset owners are consolidating vendor relationships around certified additive portfolios with documented durability performance.
- Specialty Repair Services:Niche restoration contractors command premium positioning for heritage concrete conservation and aesthetic repair applications.
Civil Engineering Firms anchor volume concentration, while Infrastructure Management Companies are gaining procurement influence fastest through asset-life-cycle contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA mandates minimum crack-bridging class ratings for bridge deck overlays, concentrating European procurement authority within its federal infrastructure renewal programs. REACH and F-Gas Regulation compliance costs are restructuring formulation portfolios across additive producers, while powder-form redispersible polymers displace liquid systems among major contractors.
Germany
Federal bridge deck maintenance contracts and KBA-mandated crack-bridging specifications drive specification authority toward certified additive portfolios. The EU Green Deal's chemical sustainability thresholds restrict phthalate-plasticized formulations while accelerating bio-based acrylic development. Bavaria and North Rhine-Westphalia host concentrated civil engineering contractor networks specifying powder-only dry-mix protocols for quality consistency.
France
Pavement rehabilitation volumes expand under national infrastructure stimulus allocations targeting aging highway networks. ECHA's evolving styrene monomer residual restrictions force reformulation investments across SBR latex suppliers serving the market. The Auvergne-Rhône-Alpes industrial corridor anchors formulation R&D activity for cement-compatible polymer systems.
Italy
Southern European facade restoration contractors demonstrate strongest uptake of silicone-modified acrylic systems for UV-exposed exterior wall applications. ANSM and national building codes progressively align durability testing protocols with German federal standards. Lombardy-based building material distributors consolidate shelf space around certified pre-packaged repair mortar portfolios.
Spain
Mediterranean climate adaptation investment accelerates specification of UV-stable flexible polymer additives for exterior vertical surfaces. The country's national construction regulator tightens solvent-based formulation specifications under EU F-Gas Regulation alignment. Catalonia and Madrid metropolitan contractors lead conversion from site-blended liquid systems to powder-form dry-mix protocols.
United Kingdom
Post-Brexit regulatory divergence creates parallel certification requirements for crack-bridging additive portfolios serving UK infrastructure contracts. The Health and Safety Executive and national building codes maintain distinct durability testing standards for bridge deck overlays. London and Southeast England civil engineering firms prioritize pre-qualified supplier relationships for federal-equivalent project specifications.
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with supply chain control and formulation expertise determining competitive positioning. The market structure rewards backward integration from monomer synthesis through packaged additive production, while specialist tiers concentrate on chemistry-specific applications. Three archetypes dominate: integrated chemical conglomerates with captive polymer supply, construction chemical specialists with deep cement compatibility knowledge, and regional formulators serving localized contractor networks. Competitive moves center on dry-mix channel consolidation through distributor partnerships and pre-emptive portfolio recertification against impending EU Construction Products Regulation amendments.
Among Swiss- and German-anchored integrated leaders, Sika, Master Builders Solutions, and Wacker Chemie occupy positions exemplifying distinct strategic vectors. Sika represents the vertically integrated archetype controlling supply chain stages from raw monomer to field-deployed additive. Master Builders Solutions exemplifies deep specialization in cement-compatible redispersible polymer powders. Wacker Chemie anchors the silicone-modified chemistry segment for exterior applications requiring UV-stable flexibility performance.
| Leading Market Players |
|---|
| Sika |
| Master Builders Solutions |
| Mapei |
| Wacker Chemie |
| Dow |
| Arkema |
| Synthomer |
| Celanese |
| Ashland |
| Others |
Pricing and Supply Chain Analysis
Germany's KBA crack-bridging class certification gates both supplier qualification and price tiering simultaneously, compressing vendor lists while amplifying premium capture for certified portfolios. This regulatory filter stratifies the market into pre-qualified premium suppliers and excluded commodity players.
Pricing Analysis
Acrylic copolymers command 15-25% price premiums over SBR latices in German federal bridge deck contracts, with certification grade and alkali resistance performance as the primary differentiation drivers. Cost compression in styrenic formulations is intensifying because ECHA's residual monomer restrictions force reformulation investments without immediate performance parity. Civil engineering firms demonstrate lowest price sensitivity due to specification mandates, while general construction contractors exhibit highest sensitivity as they absorb powder-system conversion costs.
Supply Chain Analysis
Ethylene feedstock availability through Rotterdam-Antwerp chemical corridors anchors European polymer additive production, with formulation concentration in Germany, Switzerland, and the Netherlands. Redispersible powder production draws from acrylic monomer supplies and spray-drying capacity concentrated in the Rhine-Ruhr industrial cluster. Single-source vulnerability in qualified polymer chemist talent constrains R&D throughput expansion. Distribution runs through building material distributors consolidating exclusive dry-mix partnerships with certified additive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's federal infrastructure renewal programs and ECHA's tightening chemical restrictions create a high-growth disruption window, with powder-form redispersible polymers displacing liquid systems as the decisive technological inflection.
For Market Incumbents: Shield certified portfolio positions by accelerating bio-based acrylic development ahead of EU Green Deal sustainability thresholds, while securing backward integration into monomer synthesis to offset petrochemical feedstock volatility. Deepen distributor exclusivity arrangements in Bavaria and North Rhine-Westphalia to preempt dry-mix channel consolidation by competitors. For New Entrants and Emerging Players: Germany's KBA certification fast-track offers the most penetrable entry vector for specialized silicone-modified acrylic formulations targeting Mediterranean climate exterior wall applications. Southern European facade restoration contractors represent underserved demand with less entrenched supplier relationships. Pursue white-label partnerships with Lombardy-based building material distributors to bypass direct specification battles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across powder-form redispersible polymer production as spray-drying capacity scales, improving returns for mid-scale specialists. Acquisition targets should prioritize formulators with captive cement-compatibility testing capabilities and existing REACH registration portfolios. Watch ECHA's Construction Products Regulation amendment timeline as the critical signal for recertification investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Sika's captive supply of acrylic monomers insulates margin compression from petrochemical volatility. |
| Redispersible Powder Capacity Expansion | Master Builders Solutions' spray-drying investments capture German federal bridge deck contract specifications. |
| Bio-Based Acrylic Development Program | Wacker Chemie's renewable feedstock pivot aligns additive portfolios with EU Green Deal chemical thresholds. |
| Exclusive Distributor Partnership Consolidation | Building material distributors in Catalonia and Madrid capture specification influence through dry-mix shelf space control. |
| Pre-Emptive REACH Portfolio Recertification | Proactive ECHA compliance investments ahead of Construction Products Regulation amendments compress competitor qualification timelines. |
Research Methodology
Operator-level perspectives from polymer chemists, formulation engineers, civil engineering procurement directors, and building material distributor category managers anchored the qualitative base for this study. Primary interview findings combined with secondary validation from ECHA regulatory filings, KBA certification databases, Cefic chemical industry reports, and German federal infrastructure tender records. Bottom-up additive demand modeling and top-down construction chemical market sizing provided cross-referenced triangulation.
Sensitivity analysis tested volume and value outputs across polymer chemistry type, form factor, application exposure class, and end-user procurement authority segmentation throughout the forecast period. CAGRs derived from historical infrastructure spending patterns, regulatory compliance cost trajectories, and technology substitution curves for powder versus liquid systems. Modeled inputs incorporated ECHA restriction timelines and German federal bridge deck maintenance program allocations.
Decision-makers should treat outputs as directional under base assumptions of sustained infrastructure stimulus and progressive chemical regulation tightening; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA styrene residual limits and EU Construction Products Regulation durability testing protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
South Africa Acidulants Market
Additives
North America Pectin Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Isobutyl Acetate Market
Additives
Coating Additives Market
Additives
Foundry Additives Market
Additives
Pearlizers Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Alginic Acid Market
Additives
Europe Citric Acid Market
Additives
Lubricant Additives Market
Additives
Stabilizers Market
Additives
China Citric Acid Market
Additives
Cetane Improver Additives Market
Additives
Citrate Ester Market