
 Stabilizers Market | 2026-2036
Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Stabilizers Market Analysis
EU REACH chemical registration is pivoting formulation requirements across the stabilizers value chain. Baerlocher GmbH leverages its integrated calcium-zinc heat stabilizer production across European compounding hubs. SONGWON Industrial Co., Ltd. anchors Asian supply through antioxidant specialization for polyolefin processors. BASF SE differentiates via phosphite and phenolic antioxidant technology leadership in high-performance polymer systems.
Stabilizers are chemical additives that inhibit thermal oxidation, UV degradation, or hydrolysis in polymers, typically dosed at 0.1–3.0 wt% depending on resin sensitivity and processing temperature. They function by scavenging free radicals, absorbing ultraviolet radiation, or neutralizing acid byproducts to extend product service life in demanding environments. Heat stabilizers dominate value generation due to PVC's inherent thermal lability during extrusion and injection molding. Light stabilizers represent the fastest-expanding category as agricultural films and automotive exterior plastics face intensified UV exposure requirements. Powder formulations retain margin advantages in bulk thermoplastic compounding while liquid grades capture specialized coating and adhesive applications.
EPA regulates heavy-metal content in PVC stabilizers through TSCA Section 6 restrictions, while ECHA enforces REACH authorization for cadmium and lead-based additives across European polymer converters. China's MEE implements GB standards limiting organotin stabilizers in food-contact plastics, redirecting formulation investment toward calcium-zinc and organic alternatives. India's BIS certification mandates for construction PVC pipes are elevating stabilizer quality specifications in building material supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging metal-free mandates and emerging bio-based stabilizer efficacy benchmarks.
Market Dynamics
REACH authorization protocols and China's GB standards on heavy-metal additives are forcing formulators to abandon legacy lead and cadmium stabilizer chemistries, redirecting R&D investment toward calcium-zinc and organic alternatives that meet tightening purity thresholds across automotive and construction supply chains.
Growth Catalysts
- Automotive VOC mandates:OEMs in Germany and the United States are enforcing stricter interior air quality protocols, compelling polymer processors to source low-emission heat stabilizers for dashboard and seating applications.
- India's construction surge:BIS certification requirements for PVC pipes in residential and infrastructure projects are elevating stabilizer quality specifications and procurement volumes in the building materials sector.
- Calcium-zinc chemistry maturation:Advances in thermal stability performance of metal-free alternatives are unlocking substitution in rigid PVC extrusion previously dependent on organotin systems.
Market Restraints
- Feedstock volatility:Epoxidized soybean oil and calcium carbonate prices fluctuate with agricultural commodity cycles, compressing margin predictability for stabilizer compounders.
- Asian supply concentration:Antioxidant intermediate production clusters in eastern China create geographic risk exposure for European and North American formulators dependent on just-in-time additive delivery.
- Technical performance gaps:Organic stabilizers still exhibit inferior long-term thermal stability versus traditional heavy-metal systems in high-temperature wire and cable jacketing applications.
Strategic Opportunities
- Bio-based stabilizer development:EFSA and FDA approval pathways for plant-derived antioxidant systems open premium positioning in food-contact and medical device polymers.
- Agricultural film specialization:UV stabilizer demand for greenhouse and mulch films is accelerating in Spain, Italy, and the Netherlands as climate adaptation intensifies protected cultivation.
- Recycling-compatible formulations:Stabilizer systems engineered for multi-pass reprocessing address the technical requirements of post-consumer PVC recovery mandates under EU Green Deal circular economy frameworks.
Industry Challenges
- Formulation complexity escalation:Replacing single-component heavy-metal stabilizers with multi-additive calcium-zinc or organic packages demands expanded technical service capabilities and extended customer qualification timelines.
- Regulatory testing burden:ECHA substance evaluation and state-level TSCA Section 6 enforcement require dedicated compliance staffing and third-party analytical verification that strain mid-tier stabilizer suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stabilizers Market |
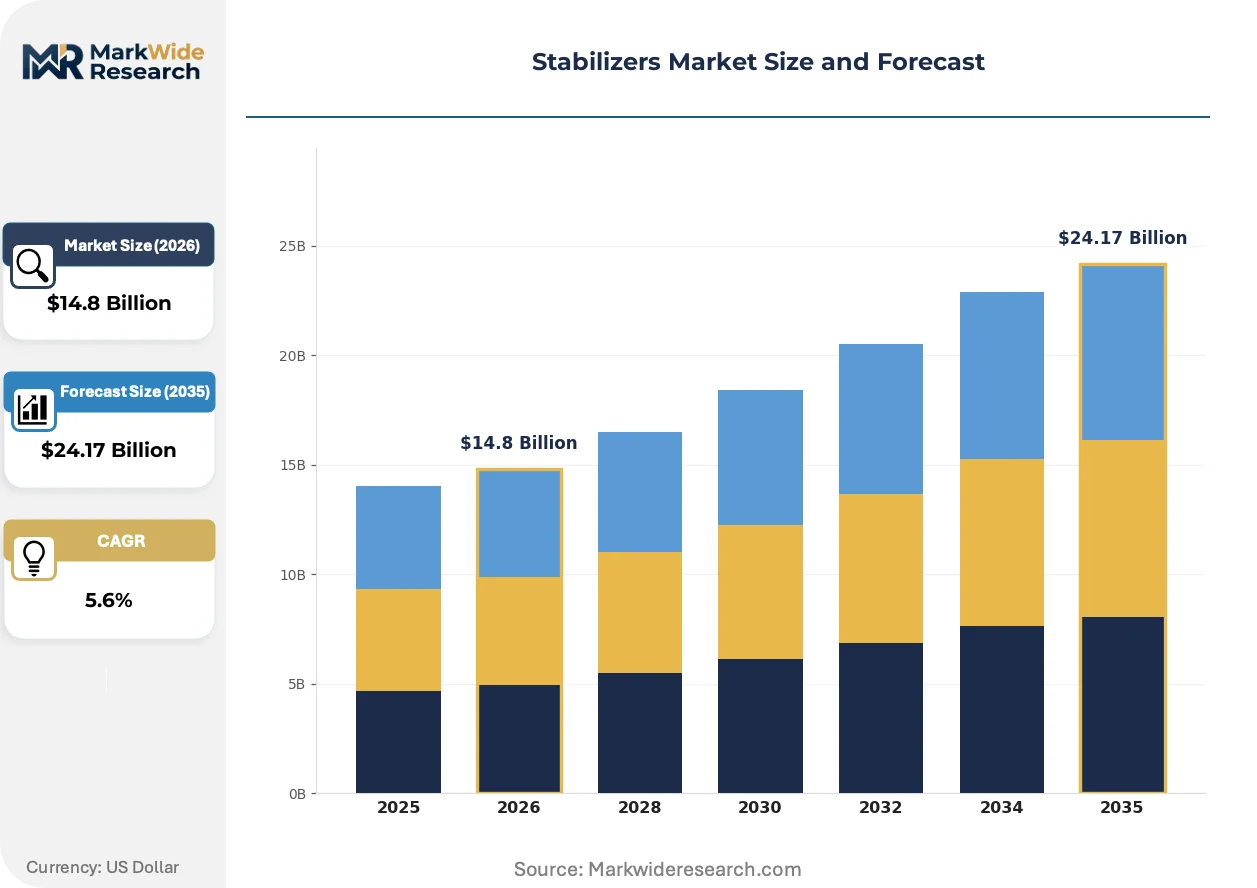
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Plasticizers, Antioxidants, Heat Stabilizers, Light Stabilizers Application: Packaging, Automotive, Construction, Agriculture End User: Manufacturers, Distributors, Retailers, Exporters Form: Granules, Liquid, Powder, Pellets |
| Companies Covered | Adeka Corporation, Baerlocher GmbH, SONGWON Industrial Co., Ltd., Arkema, Valtris Specialty Chemicals, BASF SE, Clariant, Avient Corporation, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stabilizers Market Emerging Trajectories
Formulation science is pivoting toward molecular architectures that satisfy simultaneous demands for metal-free composition, processing efficiency, and end-of-life recyclability, compressing development cycles and reshaping competitive differentiation criteria.
Hybrid calcium-zinc stabilizer systems incorporating co-stabilizing organic components are consolidating technical credibility in rigid PVC pipe and profile extrusion. German and Austrian compounders have accelerated qualification of these packages for potable water and construction applications. The technology is consolidating market share in segments where organotin substitution was previously stalled by performance concerns.
ECHA's 2023-2025 rolling action plan for REACH substance evaluation is tightening data requirements for tin-containing stabilizers used in rigid PVC. The industrial consequence is accelerated reformulation investment among European converters serving building products and packaging sectors. Wire and cable manufacturers in France and Poland are most affected, with several major processors completing transitions to calcium-zinc systems ahead of regulatory deadlines.
Specification-driven purchasing in automotive supply chains is shortening stabilizer qualification cycles and elevating technical documentation requirements. Tier-1 interior suppliers now demand full material disclosure and lifecycle assessment data that previously sufficed at OEM level only. This behavioral shift is most visible in Germany and the United States, where Volkswagen Group and Ford have implemented harmonized supplier sustainability scorecards capturing additive composition transparency.
Stabilizers Market Segmentation
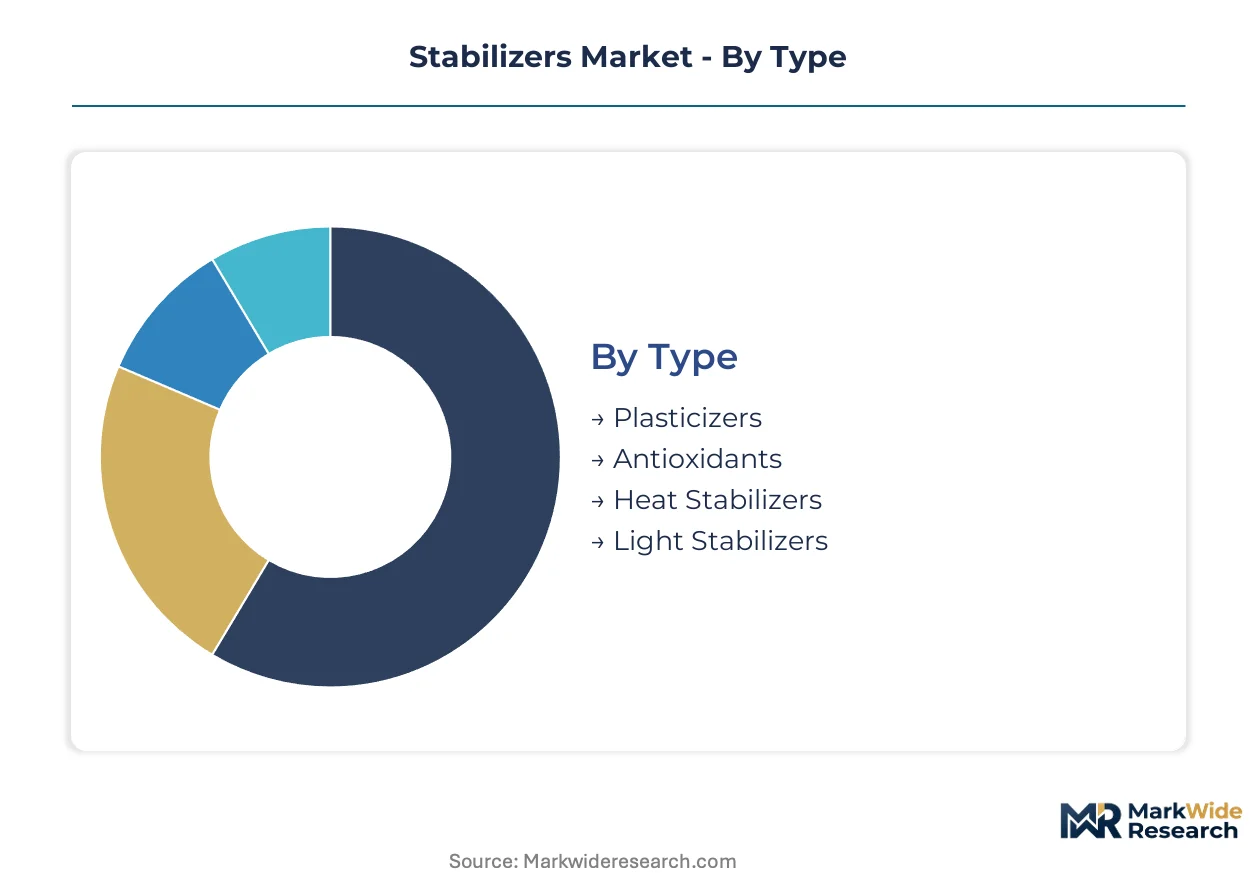
Stabilizer formulation diversity reflects divergent capital requirements across polymer processing infrastructure. Segmentation reveals where technical service intensity and regulatory compliance costs concentrate value capture.
Type:
Capital intensity peaks in heat stabilizer manufacturing due to multi-stage synthesis and hazardous material handling infrastructure. Antioxidant production demands continuous oxidation reactor systems with higher automation investment.
- Heat Stabilizers:Calcium-zinc and organotin systems require dedicated metal salt precipitation and filtration equipment. German and Austrian compounders are redirecting procurement toward calcium-zinc packages as ECHA REACH authorization deadlines approach for tin-containing alternatives in rigid PVC extrusion.
- Antioxidants:Phosphite and phenolic systems involve high-pressure hydrogenation and crystallization trains. Asian supply concentration in eastern China creates geographic risk for European formulators dependent on hindered phenol intermediates for polyolefin stabilization.
- Plasticizers:Epoxidized soybean oil and phthalate alternative production ties to agricultural commodity processing.
- Light Stabilizers:HALS and UV absorber synthesis demands specialized photoreactor containment.
Most installed capacity flows through heat stabilizers. Expansion is steepest in antioxidants.
Application:
Application segmentation tracks divergent qualification timelines and specification stringency across end-use sectors. Construction and automotive represent opposing poles of volume versus value concentration.
- Construction:PVC pipe and profile extrusion consumes bulk heat stabilizer volumes with standardized BIS certification requirements in India driving quality upgrades. Residential infrastructure investment in Indian states is accelerating procurement of calcium-zinc systems for potable water applications.
- Automotive:Interior polymer stabilization demands low-VOC heat stabilizers with full material disclosure documentation. Volkswagen Group and Ford supplier scorecards in Germany and the United States now mandate additive composition transparency previously required only at OEM tier.
- Packaging:Food-contact applications require EFSA and FDA pathway navigation for bio-based antioxidant approval.
- Agriculture:Greenhouse and mulch film UV stabilization is climbing fastest in Spain, Italy, and the Netherlands as climate adaptation intensifies protected cultivation.
Construction absorbs the highest stabilizer tonnage. Automotive commands the steepest premium expansion trajectory.
End User:
End user segmentation distinguishes between formulation control points and value-added service requirements. Manufacturers retain technical specification authority while distributors intermediate for smaller compounders.
- Manufacturers:Polymer compounders and resin producers purchase stabilizers in bulk with customized technical service agreements. Tier-1 automotive interior suppliers in Germany now demand lifecycle assessment data and full material disclosure that previously satisfied only at OEM level.
- Distributors:Regional chemical distributors aggregate smaller PVC processor orders with inventory financing and formulation guidance.
- Retailers:Limited direct engagement; primarily specialty chemical trade channels for adhesive and coating formulators.
- Exporters:Trading houses bridge regulatory divergence between European REACH compliance and Indian BIS certification requirements.
Manufacturers dominate volume procurement. Distributors are gaining share fastest in mid-tier construction segments.
Form:
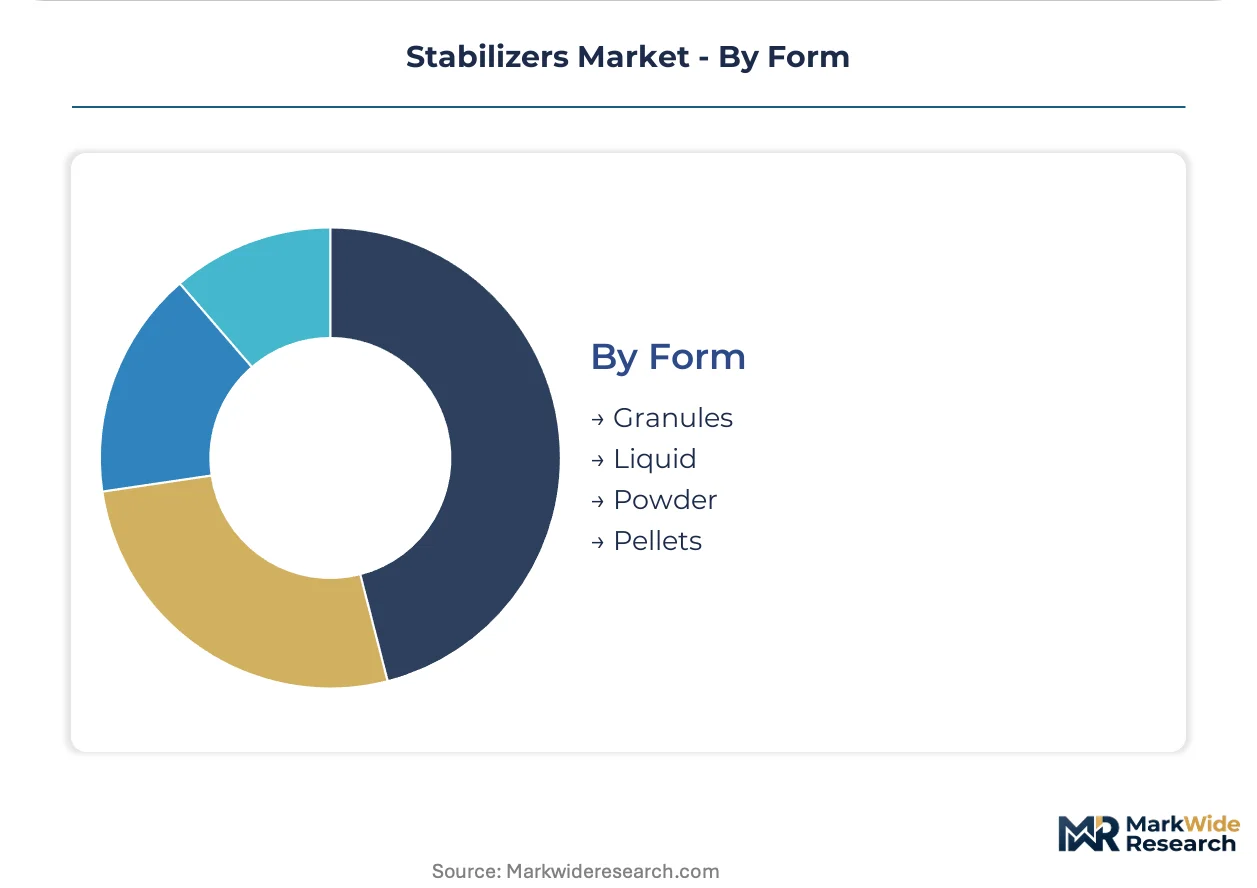
Physical form selection reflects processing equipment compatibility and dust exposure regulations. Powder retains cost advantage while liquid captures specialized coating applications.
- Powder:Dominates bulk thermoplastic compounding with lower packaging and transport costs. PVC pipe extruders in India prefer powder calcium-zinc systems for direct high-speed mixing integration.
- Liquid:Preferred in coating, adhesive, and flexible PVC plastisol applications where dust-free handling is mandatory.
- Granules:Intermediate dust control with metering precision for automated compounding lines.
- Pellets:Lowest dust exposure; premium positioning for medical device and food-contact polymer systems.
Powder commands the largest installed processing base. Liquid is expanding most quickly in automotive interior coating applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical conglomerates pioneered organotin and calcium-zinc stabilizer synthesis during the post-war plastics expansion, establishing technical standards that still govern global formulation protocols today.
United States
Automotive interior polymer demand from Detroit and Tennessee manufacturing corridors is accelerating low-VOC heat stabilizer procurement. EPA TSCA Section 6 enforcement restricts heavy-metal content in PVC additives, compelling formulators toward calcium-zinc alternatives. Gulf Coast petrochemical clusters in Texas and Louisiana host integrated stabilizer compounding operations serving construction and packaging converters.
Germany
Volkswagen Group and BMW supplier scorecards now mandate full material disclosure for dashboard and seating polymers previously required only at OEM tier. ECHA REACH authorization deadlines for tin-containing stabilizers are driving accelerated reformulation among Bavarian and North Rhine-Westphalian pipe extruders. BASF SE and Baerlocher GmbH anchor production in Ludwigshafen and Munich metropolitan zones.
China
Construction-grade PVC consumption in Jiangsu and Zhejiang provinces is elevating calcium-zinc stabilizer procurement for residential infrastructure. MEE GB standards limit organotin stabilizers in food-contact plastics, redirecting investment toward organic alternatives. Yangtze River Delta chemical parks concentrate antioxidant intermediate production for polyolefin processors.
India
BIS certification mandates for PVC pipes in Maharashtra and Gujarat are driving quality upgrades in residential and commercial building materials. Central government infrastructure spending is accelerating construction-grade polymer consumption across Delhi-NCR and Bangalore metropolitan regions. Domestic compounders are expanding calcium-zinc system capacity for potable water applications.
Netherlands
Greenhouse film UV stabilizer demand is climbing in Westland and Noord-Brabant agricultural zones as climate adaptation intensifies protected cultivation. EU Green Deal circular economy frameworks mandate recycling-compatible stabilizer formulations for post-consumer PVC recovery. Rotterdam-Antwerp chemical corridor hosts specialty additive distribution hubs serving Benelux polymer converters.
Stabilizers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technical service intensity and regulatory compliance documentation capabilities. The vendor base organizes into three tiers: integrated chemical conglomerates with captive raw material positions, mid-scale compounders with regional formulation expertise, and specialty distributors aggregating smaller processor demand. Competitive moves concentrate on backward integration into antioxidant intermediates and strategic partnerships with automotive tier-1 suppliers for qualification acceleration.
Among German-based integrated producers, Baerlocher GmbH exemplifies the calcium-zinc specialization archetype with European compounding hub integration. BASF SE anchors the phosphite and phenolic antioxidant technology tier for high-performance polymer systems. SONGWON Industrial Co., Ltd. represents Asian supply concentration through antioxidant specialization for polyolefin processors.
| Leading Market Players |
|---|
| Adeka Corporation |
| Baerlocher GmbH |
| SONGWON Industrial Co., Ltd. |
| Arkema |
| Valtris Specialty Chemicals |
| BASF SE |
| Clariant |
| Avient Corporation |
| Cargill, Incorporated |
| Others |
Supply Flow & Price Mechanics
Family-owned German and Austrian compounders anchor premium pricing discipline through captive calcium-zinc formulation expertise, while private-equity-rolled-up Asian antioxidant specialists compete on volume scale. This ownership bifurcation concentrates margin capture in REACH-compliant metal-free systems while compressing returns on legacy heavy-metal chemistries facing regulatory obsolescence.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the stabilizer market by certification grade and technical service intensity. Premium tiers command 40-60% markups for EFSA and FDA pathway-compliant bio-based antioxidants, while economy tiers serve bulk PVC pipe extruders in India with powder calcium-zinc systems. Cost compression in standard-grade heat stabilizers is intensifying because epoxidized soybean oil feedstock fluctuates with agricultural commodity cycles. Tier-1 automotive interior suppliers exhibit lowest price sensitivity due to VOC mandate compliance costs, whereas mid-tier construction compounders in India remain highly price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements from European automotive OEMs now mandate qualified backup suppliers for calcium-zinc heat stabilizers, reshaping procurement patterns. Geographic supply concentrates in Germany, China, and India, with antioxidant intermediate production clustering in eastern China. Raw material dependencies center on calcium carbonate, epoxidized soybean oil, and hindered phenol intermediates. Single-source vulnerability persists for phosphite antioxidant precursors synthesized through high-pressure hydrogenation trains. Distribution runs through integrated chemical conglomerates serving bulk compounders, with regional distributors aggregating smaller PVC processor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European REACH compliance costs and Indian BIS certification-driven quality upgrades, with formulation investment migrating toward jurisdictions with tightening metal-free mandates.
For Market Incumbents: Hedge regulatory fragmentation by maintaining parallel production lines for REACH-authorized calcium-zinc systems and GB-compliant organic alternatives. Prioritize backward integration into antioxidant intermediates to reduce exposure to eastern China supply concentration. Defend margin position through technical service capabilities that accelerate customer qualification timelines for multi-additive packages replacing legacy single-component stabilizers. For New Entrants and Emerging Players: Launch via specialty distribution partnerships targeting mid-tier Indian construction compounders seeking BIS-certified calcium-zinc systems for potable water applications. Focus white-space capture on agricultural film UV stabilizers in Spain, Italy, and the Netherlands where climate adaptation intensifies protected cultivation demand. Prioritize bio-based antioxidant development for food-contact and medical device polymers with EFSA and FDA approval pathways. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European compounders with stranded organotin capacity facing ECHA authorization deadlines. Long-term viability over the next decade hinges on successful transition to metal-free formulations and recycling-compatible systems for EU Green Deal circular economy frameworks. Monitor ECHA substance evaluation timelines as the critical inflection signal for forced substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Antioxidant Intermediates | Captive supply of hindered phenol precursors reduces exposure to eastern China concentration risk. |
| Calcium-Zinc Capacity Expansion in India | Domestic production for BIS-certified potable water pipe applications captures infrastructure spending upside. |
| Bio-Based Stabilizer Regulatory Pathway Investment | EFSA and FDA approvals unlock premium positioning in food-contact and medical device polymer segments. |
| Recycling-Compatible Formulation Development | Multi-pass reprocessing stability addresses EU Green Deal post-consumer PVC recovery mandates. |
| Automotive Tier-1 Technical Partnership | Volkswagen Group and Ford supplier scorecard qualification accelerates low-VOC heat stabilizer adoption. |
Methodological Framework
Direct dialogue with polymer compounders, automotive Tier-1 procurement officers, construction materials distributors, and ECHA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from SEC 10-K filings of listed chemical producers, Cefic industry statistics, customs trade data for stabilizer intermediate flows, and REACH authorization databases. Bottom-up and top-down triangulation cross-checked volume estimates across application segments and regional production clusters.
Bottom-up modeling aggregated end-use demand from construction PVC extrusion, automotive interior polymer stabilization, agricultural film UV protection, and packaging food-contact applications. Top-down verification referenced chemical industry capacity disclosures and regional production hub analysis. Segmentation dimensions included stabilizer type, physical form, end-use industry, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical consumption patterns and regulatory-driven substitution curves.
Several conditions sit outside the modeled scope, including abrupt shifts in agricultural commodity pricing for epoxidized soybean oil feedstock and unanticipated ECHA authorization timeline accelerations. Forecasts reflect assumptions about calcium-zinc thermal stability performance maturation and Indian infrastructure execution rates. Deviation in REACH enforcement intensity or Chinese GB standard expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Ultraviolet Light Stabilizer Market
Additives
Marine Fuel Additives Market
Additives
Biofuel Additives Market
Additives
Antimicrobial Additives Market
Additives
United States Betaine Market
Additives
Antimicrobial Ingredients Market
Additives
Iso-Butyric Acid Market
Additives
Plasticizer Alcohols Market
Additives
Gluconic Acid and Derivatives Market
Additives
Sodium Potassium Tartrate Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Tricalcium Citrate Market
Additives
Global Formulation Additives Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Refinery Fuel Additives Market
Additives
Lauroyl Methyl Glucamide Market