
 Citrate Ester Market | 2026-2036
Citrate Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Citrate Ester Market Analytics
Specialty chemical distribution is rewriting procurement patterns for citrate esters as buyers consolidate vendor relationships around technical service capabilities. Jungbunzlauer Suisse AG leverages its Swiss manufacturing base to sustain premium positioning in pharmaceutical-grade tributyl citrate. Cargill, Incorporated anchors North American supply through backward integration into citric acid feedstocks. Vertellus Holdings LLC specializes in custom esterification for personal care formulators seeking rapid regulatory compliance documentation.
Citrate esters comprise citric acid-derived compounds—triethyl citrate, tributyl citrate, acetyl tributyl citrate, and diethyl citrate—manufactured through esterification with corresponding alcohols and typically specified at purity levels exceeding 99% for food and pharmaceutical applications. These compounds function primarily as non-phthalate plasticizers, solvents, and film-forming agents across food packaging, drug delivery systems, and cosmetic formulations. Tributyl citrate and acetyl tributyl citrate dominate volume consumption due to their compatibility with polyvinyl chloride and cellulosic polymers in high-clarity packaging films. The personal care application segment registers the fastest structural expansion as clean beauty standards in Europe and North America displace traditional phthalate plasticizers from fragrance fixatives and nail care products. Food additive grades command the deepest margin pools owing to stringent pharmacopeial certification requirements and limited qualified supply base.
EMA pharmaceutical guidelines and EU REACH Annex XVII restrictions on phthalate plasticizers directly expand citrate ester qualification programs across European formulation houses. FDA food contact notifications and EPA Safer Choice criteria shape U.S. market access thresholds, particularly for indirect food additive applications in packaging films and processing equipment. Stakeholders must monitor evolving substance evaluations under ECHA's SVHC candidate list processes, as any citric acid derivative reclassification would trigger reformulation timelines across multiple downstream sectors.
Market Dynamics
REACH Annex XVII phthalate restrictions and FDA food-contact notifications are compressing formulation windows across European and North American packaging sectors, forcing rapid citrate ester qualification cycles that favor pre-certified suppliers with backward-integrated citric acid supply.
Growth Catalysts
- EU REACH RoHS convergence:Tightening phthalate bans in food-contact materials and electronics housings are accelerating substitution mandates across German and French packaging supply chains.
- Clean-label food processing:Processed and packaged food manufacturers are reformulating around non-phthalate plasticizers to meet retailer sustainability scorecards and consumer transparency demands.
- Pharmaceutical film-forming:Drug delivery system designers specify high-purity tributyl citrate for enteric coatings and controlled-release matrices, expanding qualified supplier rosters.
Market Restraints
- Citric acid feedstock volatility:Fermentation-grade citric acid prices fluctuate with Brazilian and Chinese agricultural input costs, compressing esterification margins during harvest disruptions.
- Swiss-German supply concentration:Pharmaceutical-grade production clusters around Basel and Ludwigshafen, creating geographic vulnerability to single-site regulatory actions or logistics interruptions.
- Acetyl tributyl citrate performance ceiling:Compatibility gaps with high-temperature PVC processing above 180°C limit substitution rates in industrial cable and automotive interior applications.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO and Indian Pharmacopoeia harmonization efforts are opening formulation trials for citrate esters in generic drug exports to regulated markets.
- Biodegradable agricultural film:Cellulosic mulch and greenhouse film developers are testing citrate ester plasticizers to meet soil-contact biodegradability certifications.
- Direct-to-formulator digital channels:Specialty chemical platforms are bypassing traditional distributor markups for mid-volume personal care compounders seeking rapid regulatory documentation.
Industry Challenges
- Pharmacopeial certification timelines:USP-NF and EP monograph compliance for food and pharmaceutical grades requires 18-24 month validation cycles that strain working capital.
- Esterification reactor retrofit costs:Continuous processing upgrades for acetylation capacity demand capital deployment that mid-scale producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrate Ester Market |
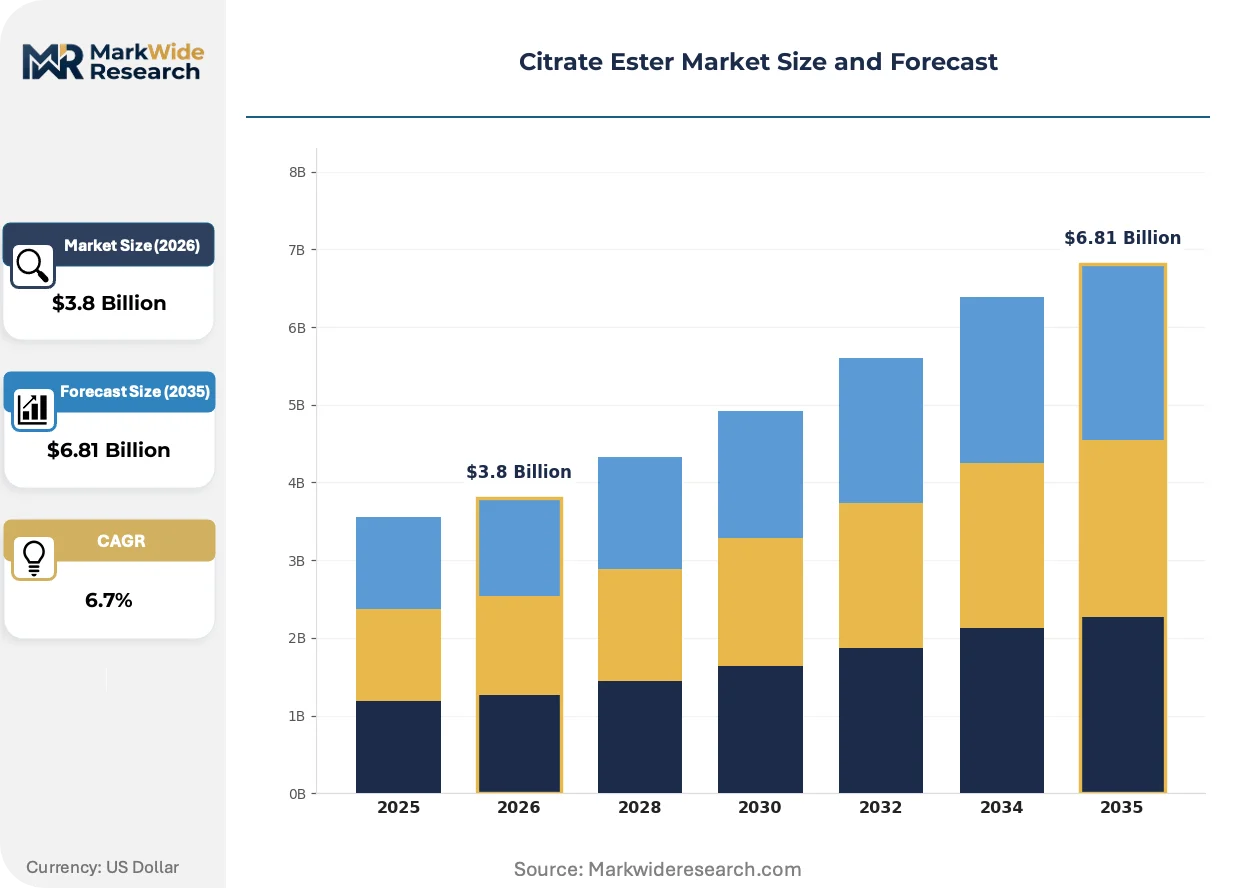
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triethyl Citrate, Tributyl Citrate, Acetyl Tributyl Citrate, Diethyl Citrate Application: Food Additives, Pharmaceuticals, Personal Care, Plastics End User: Food Industry, Healthcare Sector, Cosmetics Industry, Manufacturing Distribution Channel: Online Sales, Direct Sales, Retail Stores, Distributors |
| Companies Covered | Jungbunzlauer Suisse AG, Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Corbion N.V., Vertellus Holdings LLC, Fine Organics, Austrade Inc., Avril Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrate Ester Market Evolving Landscape
Digital formulation platforms and predictive regulatory compliance tools are compressing product development cycles, while sustainability verification requirements reshape specification priorities across packaging and personal care value chains.
Continuous esterification reactor technology is virtualizing batch-based production economics. Swiss and German specialty chemical producers are retrofitting plug-flow systems to reduce solvent recovery overhead and improve acetyl tributyl citrate yield consistency. This virtualization is collapsing minimum efficient scale thresholds and enabling regional production footprints that previously required centralized bulk manufacturing.
EU F-Gas Regulation phase-down schedules and ECHA SVHC candidate list expansions are tightening substance evaluation timelines for plasticizer alternatives. Formulation houses must pre-qualify citrate ester grades against evolving hazard classifications before customer specification lock-in. Personal care and food packaging segments in France and Italy are accelerating supplier audits to secure multi-year compliance coverage.
Specification-driven consolidation is compressing vendor rosters for mid-tier compounders. Personal care formulators in Germany and the Netherlands are consolidating procurement around technical service providers who bundle regulatory documentation, formulation support, and inventory management. This consolidation is most visible in fragrance fixative and nail care applications where clean beauty certification requirements demand integrated compliance packages rather than commodity supply relationships.
Citrate Ester Market Segmentation
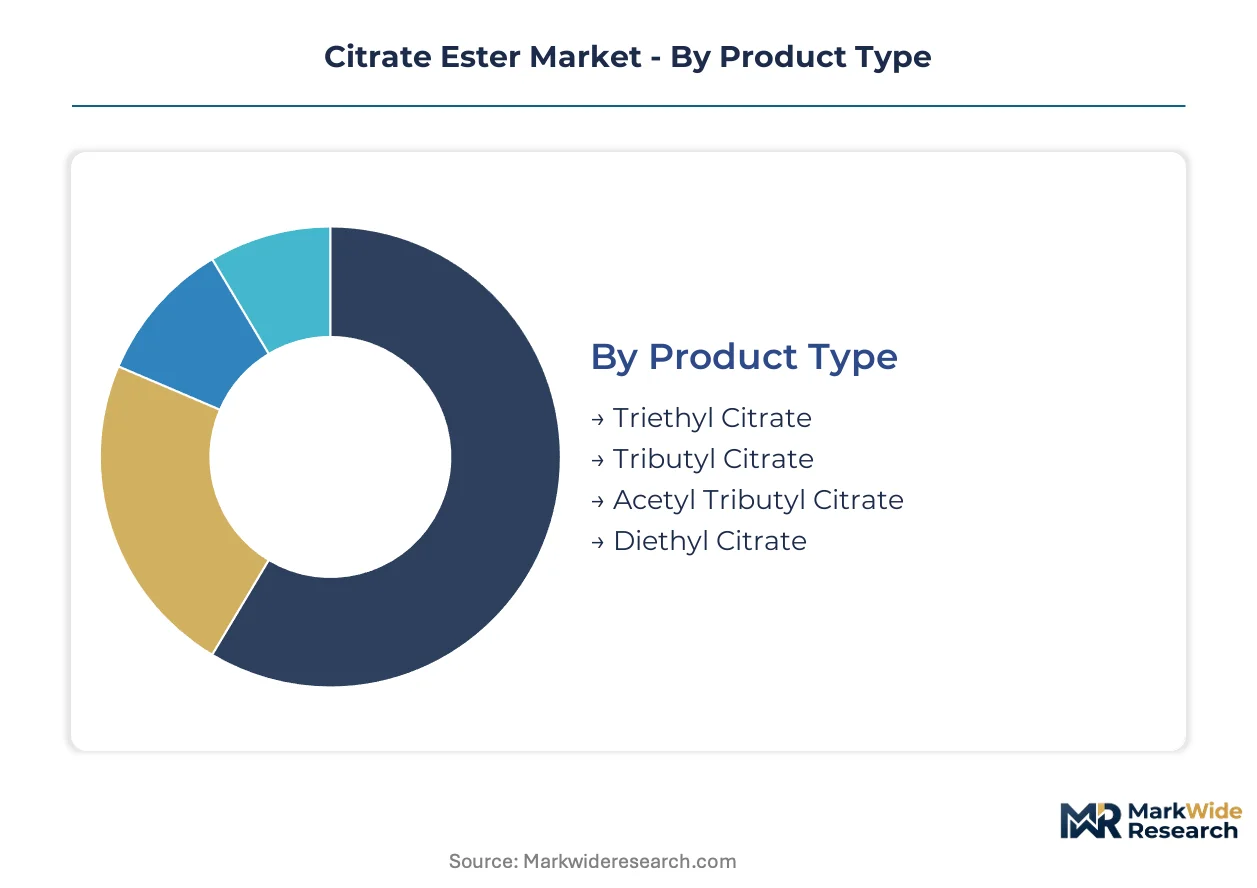
Citrate ester procurement patterns diverge sharply across purity grades and regulatory certification tiers, forcing suppliers to maintain parallel production streams. Formulation houses select segments based on end-use compliance requirements rather than commodity pricing, fragmenting competitive dynamics across each dimension.
Product Type:
Cost tier differentiation separates pharmaceutical-grade specifications from industrial plasticizer alternatives, with acetylation chemistry adding margin capture for high-performance applications.
- Tributyl Citrate:Manufactured through esterification of citric acid with n-butanol, this compound delivers primary plasticization for PVC and cellulosic films in food-contact packaging. Demand concentrates in German and French flexible packaging supply chains where REACH Annex XVII phthalate bans force rapid substitution. ECHA SVHC screening protocols extend qualification timelines for new supply sources.
- Acetyl Tributyl Citrate:Post-esterification acetylation elevates compatibility with polar polymers and improves hydrolytic stability in high-humidity environments. Personal care formulators in the Netherlands specify this grade for fragrance fixatives and nail care products facing clean beauty audit requirements. Performance ceilings above 180°C processing temperatures constrain penetration into automotive cable applications.
- Triethyl Citrate:Lower molecular weight ester functions as solvent and film-forming agent in pharmaceutical coatings.
- Diethyl Citrate:Specialty solvent grade serves niche flavor and fragrance extraction processes.
Tributyl Citrate commands the established base. The steepest expansion runs through Acetyl Tributyl Citrate.
Application:
Application segmentation tracks regulatory intensity, with food-contact and pharmaceutical grades demanding pharmacopeial certification that industrial plasticizer volumes bypass.
- Food Additives:Citrate esters function as acidulants, emulsifiers, and non-phthalate plasticizers for indirect food contact materials. Processed and packaged food manufacturers in Germany reformulate around clean-label alternatives to meet retailer sustainability scorecards. USP-NF and EP monograph compliance requirements limit qualified supply sources and sustain premium pricing tiers.
- Personal Care:Clean beauty standards in Europe and North America displace traditional phthalate plasticizers from fragrance fixatives, nail care, and cosmetic film-formers. French and Italian formulators accelerate supplier audits to secure multi-year compliance coverage against evolving ECHA hazard classifications. This segment climbs the fastest as certification requirements reshape procurement priorities.
- Pharmaceuticals:High-purity tributyl citrate serves enteric coatings and controlled-release drug delivery matrices.
- Plastics:PVC and cellulosic polymer plasticization for packaging films and processing equipment.
Food Additives anchors volume consumption. Personal Care gains share fastest.
End User:
Customer type determines technical service intensity, with pharmaceutical and food sectors demanding bundled regulatory documentation that manufacturing buyers rarely require.
- Healthcare Sector:Drug delivery system designers specify pharmacopeial-grade citrate esters for enteric coatings, transdermal patches, and controlled-release formulations. CDSCO harmonization efforts in India are opening qualification trials for generic drug exports to regulated markets. FDA drug master file documentation requirements favor pre-certified suppliers with established compliance histories.
- Cosmetics Industry:Clean beauty formulators consolidate procurement around technical service providers who bundle regulatory documentation, formulation support, and inventory management. German and Dutch personal care compounders increasingly bypass traditional distributors for digital channels offering rapid compliance documentation. This customer type is expanding most quickly as certification complexity rises.
- Food Industry:Processed and packaged food manufacturers seeking clean-label plasticizer alternatives.
- Manufacturing:Industrial plasticizer consumers in packaging and processing equipment.
Food Industry represents the incumbent demand base. Cosmetics Industry shows the steepest growth trajectory.
Distribution Channel:
Channel selection reflects order scale and documentation requirements, with large compounders favoring direct relationships while mid-tier buyers accept distributor markups for technical support.
- Direct Sales:Large-volume pharmaceutical and food packaging manufacturers negotiate directly with producers for multi-year supply agreements with locked pharmacopeial certification. Swiss and German specialty chemical producers leverage technical service capabilities to defend margin positions against distributor competition. Direct relationships compress lead times for custom esterification requests.
- Distributors:Specialty chemical distributors serve mid-volume personal care and cosmetics compounders requiring rapid regulatory documentation and formulation support. German and Netherlands-based distributors are consolidating vendor relationships around pre-qualified citrate ester grades with bundled compliance packages. This channel is climbing fastest as specification-driven consolidation reshapes procurement patterns.
- Online Sales:Digital platforms targeting small-scale formulators and research quantities.
- Retail Stores:Limited presence for laboratory and small-batch chemical supply.
Direct Sales captures the premium tier. Distributors post the fastest expansion rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and German pharmaceutical-grade supply chains, while Asian fermentation-based feedstock regions compete on volume cost positions. This asymmetry shapes procurement strategies across food-contact and personal care formulation networks.
Germany
REACH Annex XVII phthalate bans drive food packaging reformulation in Ludwigshafen and Leverkusen chemical clusters. The country's Federal Institute for Risk Assessment enforces strict food-contact material evaluations. BASF and Lanxess legacy infrastructure in North Rhine-Westphalia now pivots toward citrate ester toll manufacturing for mid-scale compounders.
Switzerland
Swissmedic pharmaceutical guidelines and Basel's life sciences concentration sustain premium-grade tributyl citrate demand. Jungbunzlauer leverages its Swiss manufacturing base to defend margin positions against commodity competitors. The Basel-Land canton hosts specialized esterification capacity serving EU drug delivery system designers.
United States
FDA food contact notifications and EPA Safer Choice criteria compress qualification timelines for packaging film suppliers. Cargill's backward integration into citric acid feedstocks anchors North American supply security. Midwest fermentation facilities in Iowa and Illinois buffer against Brazilian agricultural input volatility.
France
ANSM cosmetic safety assessments and clean beauty retailer scorecards accelerate phthalate displacement in fragrance and nail care. The Lyon chemical corridor specializes in personal care-grade acetylation capacity. French formulators consolidate vendor relationships around bundled regulatory documentation packages.
India
CDSCO pharmaceutical excipient harmonization efforts open qualification trials for generic drug exports to regulated markets. FSSAI food additive safety evaluations expand citrate ester adoption in processed food packaging. Maharashtra and Gujarat chemical zones develop esterification capacity targeting mid-volume personal care compounders.
Citrate Ester Market Competitive Landscape
Swiss-German pharmaceutical specialists and North American agribusiness-integrated producers split the market into premium-certified and volume-commodity tiers. Consolidation pressures concentrate around pharmacopeial documentation capabilities rather than manufacturing scale. Three archetypes dominate: fermentation-integrated feedstock controllers, custom esterification service providers, and regional toll manufacturers competing on regulatory response speed. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines stretch working capital requirements.
Within the premium-tier vector, Jungbunzlauer Suisse AG exemplifies Swiss-based pharmaceutical-grade positioning through its Basel manufacturing concentration. Cargill, Incorporated anchors North American supply through its captive citric acid production infrastructure. Vertellus Holdings LLC occupies a specialist position serving personal care formulators requiring rapid compliance documentation turnaround.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Corbion N.V. |
| Vertellus Holdings LLC |
| Fine Organics |
| Austrade Inc. |
| Avril Group |
| Others |
Value Network & Pricing Analysis
Undercapacity in Swiss pharmaceutical-grade esterification capacity is tightening supplier discipline and amplifying premium capture for pre-certified tributyl citrate grades. German food packaging compounders now face extended lead times that force acceptance of configured-to-order pricing premiums over standard catalog offerings.
Pricing Analysis
The customization-premium spread between pharmacopeial-grade tributyl citrate and industrial plasticizer alternatives now exceeds three-to-one. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity, with USP-NF and EP monograph compliance commanding the top tier. Cost compression in fermentation-grade citric acid feedstocks is intensifying because Brazilian harvest volatility feeds through to esterification margins. Small-scale personal care formulators exhibit the highest price sensitivity, while pharmaceutical drug delivery designers accept premium positioning without volume negotiation.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for citric acid feedstock procurement. Manufacturing concentrates in Switzerland, Germany, and the United States, with Basel and Ludwigshafen hosting specialized esterification capacity. Raw material flows draw from Brazilian fermentation facilities, Chinese citric acid refineries, and North American corn-derived feedstock streams. Single-source vulnerability in pharmaceutical-grade acetylation reactors creates geographic concentration risk. Distribution runs through specialty chemical distributors who bundle regulatory documentation with inventory management for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The citrate ester market functions as a regulatory entrenchment story, where pharmacopeial certification timelines create switching costs that lock formulation houses into pre-qualified supplier relationships.
For Market Incumbents: Build regulatory documentation moats by pre-qualifying acetyl tributyl citrate grades against evolving ECHA SVHC candidate list expansions before customer specification lock-in. Expand captive citric acid production in Iowa and Illinois to buffer against Brazilian agricultural input volatility. Continuous esterification reactor retrofits in Basel-Land canton defend yield consistency against batch-based competitors. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical excipient qualification by targeting CDSCO harmonization trials for generic drug exports to regulated markets. Direct-to-formulator digital channels bypass traditional distributor markups for mid-volume personal care compounders seeking rapid compliance documentation. White space concentrates in biodegradable agricultural film applications testing citrate ester plasticizers for soil-contact certifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous esterification capacity as plug-flow reactor retrofits demand capital deployment that mid-scale producers struggle to finance. Acquisition targets with bundled regulatory documentation capabilities and established FDA drug master file histories offer the strongest five-to-ten year viability. Monitor ECHA substance evaluation timelines as the critical inflection signal for reformulation-driven demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citric Acid Feedstocks | Cargill's Iowa fermentation facilities anchor North American supply security against Brazilian harvest disruption. |
| Continuous Esterification Reactor Retrofit | Swiss plug-flow systems reduce solvent recovery overhead and improve acetyl tributyl citrate yield consistency. |
| Pharmacopeial Certification Investment | USP-NF and EP monograph compliance requires eighteen-to-twenty-four month validation cycles that strain working capital. |
| Direct-to-Formulator Digital Channel Launch | Specialty chemical platforms bypass traditional distributor markups for mid-volume personal care compounders. |
| Long-term Supply Agreement with Food Packaging Manufacturers | German flexible packaging compounders lock multi-year pharmacopeial certification coverage against REACH Annex XVII substitution mandates. |
Research Methodology
A spread of perspectives from plant managers at esterification facilities, procurement leads at downstream food packaging OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary interviews combined with secondary validation against customs and trade data, Cefic sector reports, SEC filings, and FDA food contact notification databases. Bottom-up volume modeling triangulated against top-down value estimates across grade tier, end-use industry, and regional production hub segmentation.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product type, application, end user, and distribution channel. CAGRs were derived from growth rate convergence across projection scenarios. Forecast inputs incorporated fermentation-grade citric acid price volatility and ECHA SVHC candidate list expansion timelines.
Stress conditions across Brazilian agricultural input costs, ECHA substance evaluation outcomes, and continuous reactor retrofit financing availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions that may require revision if regulatory reclassification or feedstock disruption materializes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antimicrobial Ingredients Market
Additives
Lactic Acid Ester Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
United States Betaine Market
Additives
Crosslinking Agents Market
Additives
Sodium Citrate Dihydrate Market
Additives
Driveline Additives Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Tragacanth Market
Additives
Global Pearlizing Agent Market
Additives
Encapsulated Citric Acid Market
Additives
Global Scale Inhibitors Market
Additives
Canada Anti-Caking Market
Additives
Global Feed Acidulants Market
Additives
Global Sodium Acetate Market
Additives
China Sodium Reduction Ingredient Market