
 Make-Up Products Packaging Market | 2026-2036
Make-Up Products Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Make-Up Products Packaging Market Foresight
E-commerce fulfillment channels for cosmetic packaging is narrowing as direct-to-consumer brands demand smaller minimum order quantities and faster turnaround times. Albea SA leverages its European manufacturing footprint to sustain contract relationships with heritage makeup houses. Quadpack Industries anchors its position through specialized decoration capabilities for premium lip and eye products. HCP Packaging competes aggressively on pump-dispenser engineering for liquid foundation formats.
Make-Up Products Packaging encompasses primary and secondary enclosures designed to contain, protect, and dispense cosmetic formulations with specific functional requirements including airless sealing, UV opacity, and precision metering mechanisms. Glass and plastic dominate the Packaging Material landscape, with glass commanding margin pools in prestige fragrance-adjacent categories while plastic sustains volume leadership across mass-market face products. Pump and dropper Closure Types are gaining structural share as serum-infused color cosmetics expand, though screw cap formats still occupy the largest installed base for solid and semi-solid applications. E-commerce End User requirements are reshaping structural specifications, with drop-testing protocols and transit-optimized dimensions now standard for online-exclusive beauty launches.
FDA cosmetic labeling requirements and the EU REACH framework govern material composition and chemical disclosure across the two largest demand jurisdictions, while China's GB standards and NMPA registration rules shape market access for imported packaging components. The EU Green Deal's packaging waste directives are forcing substrate transitions that will test converter flexibility across glass, metal, and certified paper alternatives. Stakeholders must monitor regulatory divergence between the EU's expanding extended producer responsibility schemes and the US state-level patchwork of packaging mandates to determine where to concentrate compliance investment and material qualification resources.
Market Dynamics
EU REACH chemical restrictions and the EU Green Deal's packaging waste directives are forcing substrate transitions across glass, metal, and certified paper alternatives, testing converter flexibility while professional salon channels accelerate sustainable packaging commitments.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes accelerate material transitions toward post-consumer recycled content and certified paper alternatives in France, Italy, and Germany.
- Serum-infused color cosmetics:Pump and dropper closure formats gain structural share as liquid foundation and hybrid skincare-makeup formulations expand airless sealing requirements.
- E-commerce structural specifications:Direct-to-consumer brands demand drop-testing protocols and transit-optimized dimensions, reshaping primary packaging engineering for online-exclusive beauty launches.
Market Restraints
- Virgin plastic input cost volatility:Polymer price swings compress margin pools for mass-market face product converters dependent on petroleum-derived substrates.
- Glass supply concentration:European furnace capacity constraints limit prestige fragrance-adjacent category expansion despite margin premiums.
- REACH chemical disclosure friction:Material composition documentation burdens slow qualification timelines for imported packaging components entering EU jurisdictions.
Strategic Opportunities
- Post-pandemic inventory rebuilding:European cosmetic houses in France and Italy are restocking premium lip and eye product lines, creating demand for specialized decoration capabilities.
- Airless pump engineering convergence:UV opacity requirements combine with precision metering mechanisms to open technical differentiation in liquid foundation formats.
- China GB standards alignment:NMPA registration rules for imported packaging components create compliance service revenue streams for converters with dual-jurisdiction expertise.
Industry Challenges
- Material science talent scarcity:Formulation chemists with biopolymer and certified paper substrate expertise command premium compensation, constraining R&D velocity.
- Dual-jurisdiction certification timelines:Simultaneous FDA cosmetic labeling and EU REACH qualification extends product launch windows by 8-14 months.
- Legacy screw cap integration complexity:Solid and semi-solid applications resist rapid format migration despite pump-dispenser performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Make-Up Products Packaging Market |
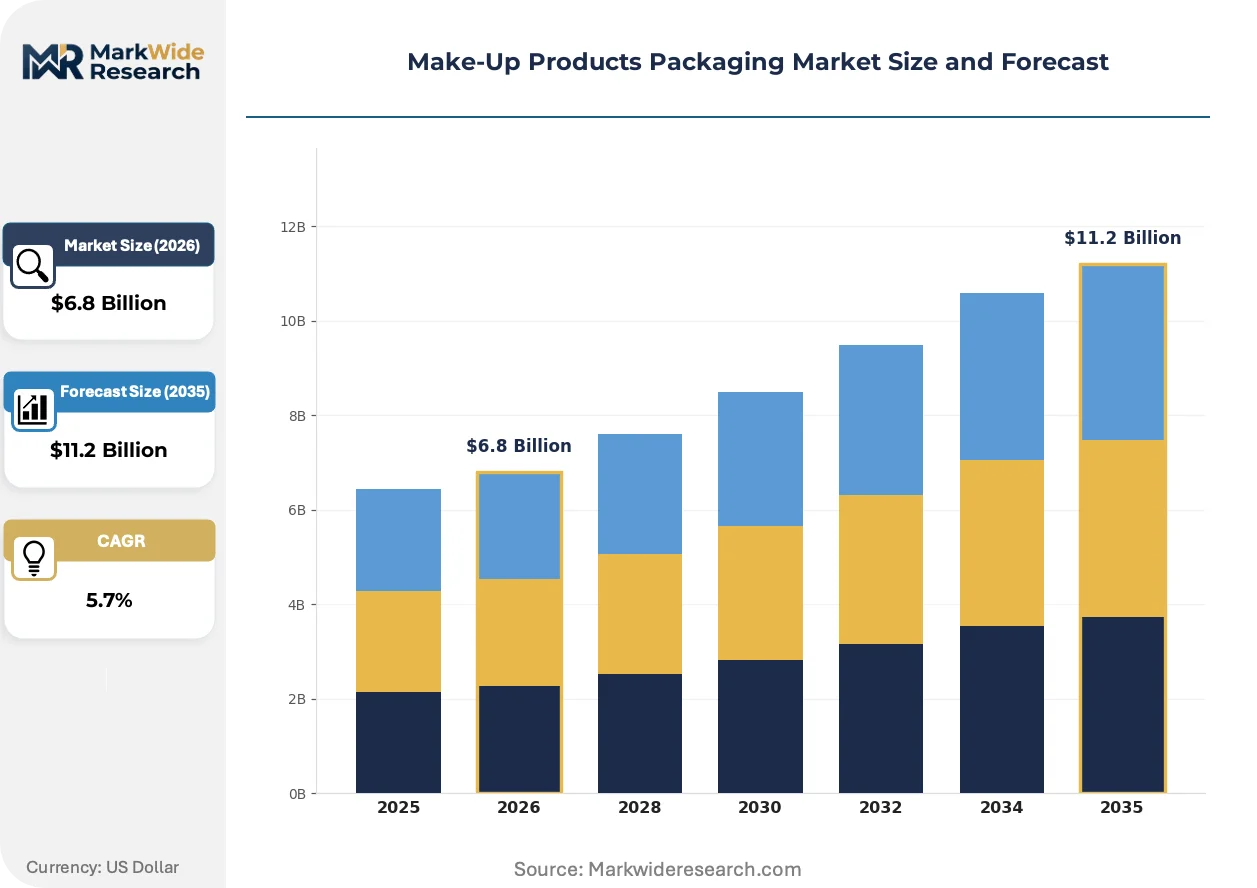
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Material: Glass, Plastic, Metal, Paper Closure Type: Screw Cap, Flip Top, Pump, Dropper Application Type: Lip Products, Face Products, Eye Makeup, Nail Products End User: Retail, Professional, E-commerce, Others |
| Companies Covered | Amcor plc, Albea SA, HCP Packaging, Berry Global, AptarGroup, Gerresheimer AG, DS Smith, Silgan Holdings, Quadpack Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Make-Up Products Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape enclosure engineering, with hybrid substrates and airless technologies displacing conventional formats across premium and mass-market tiers.
Biopolymer-barrier film laminates are hybridizing conventional petroleum-derived plastics with certified compostable layers, enabling brands to meet EU Green Deal targets without sacrificing shelf-life performance. Professional salon channels and heritage makeup houses adopt these substrates fastest, compressing the qualification window for virgin plastic alternatives. The structural consequence is a bifurcation in converter capabilities between those with in-house lamination expertise and commodity molders.
REACH chemical restrictions on microplastics and intentionally added substances are forcing reformulation of decorative coatings and UV stabilizers used in prestige packaging. The industrial consequence is accelerated qualification of mineral-based pigments and glass-derived opacity agents. Premium lip and eye product categories face the steepest compliance curves, with Italian and French cosmetic houses rebuilding supplier portfolios to maintain market access.
Direct-to-consumer fulfillment models are compressing minimum order quantities and turnaround expectations, with brands demanding sub-5,000 unit runs and 6-week production cycles. This pattern displaces traditional long-run contract manufacturing relationships in favor of agile converter networks. The shift is most visible in Germany's e-commerce beauty cluster, where online-exclusive launches now dictate structural specifications before retail formats.
Make-Up Products Packaging Market Segmentation
Segmentation in make-up packaging determines converter investment priorities, with material chemistry and closure engineering representing the largest capital allocation decisions. Each dimension carries distinct regulatory exposure and margin architecture that shapes supplier selection criteria.
Packaging Material:
Mature substrates dominate installed capacity while emerging alternatives force qualification timelines across European converter networks.
- Glass:Silica-based enclosures with UV opacity properties serve prestige fragrance-adjacent categories. Demand concentrates in France and Italy where heritage cosmetic houses rebuild post-pandemic inventory for premium lip and eye lines. Furnace capacity constraints limit expansion despite margin premiums.
- Plastic:Petroleum-derived polymers including PET, PP, and ABS sustain volume leadership across mass-market face products. E-commerce fulfillment channels in Germany drive specifications for drop-testing protocols and transit-optimized dimensions. Virgin plastic input cost volatility compresses converter margins.
- Metal:Aluminum and tinplate substrates offer barrier properties for pressed powder compacts. REACH chemical restrictions on intentionally added substances accelerate mineral-based pigment adoption.
- Paper:Certified fiber and molded pulp formats gain share under EU Green Deal mandates. Professional salon channels adopt fastest, compressing qualification windows for compostable barrier laminates.
Plastic handles the majority of throughput; paper is gaining share fastest among sustainability-mandated channels.
Closure Type:
Cost tier stratification separates commodity formats from precision-engineered dispensing systems with airless sealing requirements.
- Screw Cap:Threaded closures for solid and semi-solid applications occupy the largest installed base. Legacy integration complexity resists rapid migration despite pump-dispenser performance advantages in liquid formats.
- Flip Top:Hinged single-motion openings serve mass-market convenience requirements. Standardized tooling keeps per-unit costs lowest among plastic closure categories.
- Pump:Precision metering mechanisms with airless sealing properties expand with serum-infused color cosmetics. HCP Packaging competes aggressively on engineering for liquid foundation formats.
- Dropper:Glass or plastic pipette systems deliver controlled dosing for hybrid skincare-makeup formulations. UV opacity requirements open technical differentiation in premium tiers.
Screw cap maintains the largest installed base; pump and dropper formats climb the fastest on structural share as liquid formulations expand.
Application Type:
Volume concentration in face products contrasts with margin concentration in specialized color categories requiring decoration expertise.
- Face Products:Liquid foundation, concealer, and powder compacts represent the highest unit volumes. Pump-dispenser engineering and airless sealing requirements dominate technical specifications.
- Lip Products:Bullets, gloss tubes, and liquid lipstick formats command specialized decoration capabilities. Quadpack Industries anchors position through premium finishing for heritage European houses.
- Eye Makeup:Mascara, eyeshadow, and liner formats combine precision metering with aesthetic differentiation. REACH chemical restrictions on decorative coatings force supplier portfolio rebuilding in France and Italy.
- Nail Products:Brush-integrated caps for lacquer and treatment formulations require solvent-resistant substrates. Glass and metal sustain dominance over plastic alternatives.
Face products generate the highest unit volumes; eye makeup shows the steepest expansion trajectory for technical premiumization.
End User:
Customer type determines order quantity structures and turnaround expectations, with direct-to-consumer models compressing traditional manufacturing relationships.
- Retail:Brick-and-mortar distribution through department stores and specialty beauty chains sustains long-run contract manufacturing. Standardized dimensions optimize shelf-facing efficiency.
- Professional:Salon and backstage channels accelerate sustainable packaging commitments. Albea SA leverages European manufacturing footprint to sustain relationships with heritage makeup houses.
- E-commerce:Direct-to-consumer fulfillment demands sub-5,000 unit minimums and 6-week production cycles. Germany's online beauty cluster dictates structural specifications before retail formats.
- Others:Travel retail, subscription boxes, and promotional sampling programs require specialized logistics integration and variable batch sizing.
Retail retains the largest contract base; e-commerce is expanding most quickly on format specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European packaging material flows, while China's Ningbo-Zhoushan port complex anchors Asian substrate exports. These maritime gateways determine converter location decisions and qualification timelines across the three major demand jurisdictions.
France
Heritage cosmetic houses in Paris and Grasse drive premium glass demand for fragrance-adjacent makeup lines. ANSM enforces REACH chemical disclosure requirements on decorative coatings and UV stabilizers. The Île-de-France cluster concentrates specialized decoration capabilities for lip and eye product launches.
Germany
E-commerce beauty brands in Berlin and Hamburg compress minimum order quantities to sub-5,000 units with 6-week turnaround demands. KBA oversees packaging waste directives under EU Green Deal implementation. The Rhine-Ruhr industrial corridor hosts converter networks optimized for transit-optimized dimensional engineering.
Italy
Post-pandemic inventory rebuilding accelerates across Lombardy and Piedmont cosmetic manufacturing bases. ECHA chemical restrictions force supplier portfolio rebuilding for mineral-based pigment adoption. The Milan-Turin axis anchors specialized finishing capabilities for premium color cosmetic packaging.
United States
FDA cosmetic labeling requirements govern material composition disclosure for mass-market face product converters. The New Jersey-Philadelphia chemical corridor sustains petroleum-derived polymer supply chains for plastic substrate dominance. California's state-level packaging mandates create compliance complexity distinct from federal frameworks.
China
NMPA registration rules shape market access for imported packaging components entering domestic cosmetic supply chains. The Yangtze River Delta manufacturing belt concentrates pump-dispenser engineering capacity for liquid foundation formats. GB standards alignment creates dual-certification service opportunities for converters with EU-China expertise.
Make-Up Products Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material and closure engineering. The vendor base stratifies between consolidated multi-substrate converters and fragmented decoration boutiques. Three archetypes dominate: European heritage houses with furnace and lamination assets, Asian scale players on injection molding, and agile regional networks serving direct-to-consumer brands. Competitive moves concentrate on M&A for decoration capabilities and capacity expansion in post-consumer recycled content.
Among European heritage converters, Albea SA and Gerresheimer AG occupy positions spanning glass furnace operations and precision molding. Quadpack Industries exemplifies the specialized decoration archetype, anchoring premium finishing capabilities for lip and eye product lines. HCP Packaging represents the Asian engineering-focused tier, with its corporate naming convention indicating concentration on packaging hardware systems.
| Leading Market Players |
|---|
| Amcor plc |
| Albea SA |
| HCP Packaging |
| Berry Global |
| AptarGroup |
| Gerresheimer AG |
| DS Smith |
| Silgan Holdings |
| Quadpack Industries |
| Others |
Supply & Pricing Matrix
Virgin plastic input cost volatility functions as the central pricing risk vector, compressing converter margins in mass-market face products while simultaneously forcing supply chain restructuring toward post-consumer recycled content and certified paper alternatives. This petroleum-derived dependency creates divergent pricing power between commodity molders exposed to polymer price swings and integrated converters with captive lamination expertise.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs converter relationships, with heritage European houses paying decoration premiums for glass and specialized finishing while direct-to-consumer brands negotiate sub-5,000 unit minimums at compressed per-unit rates. Price differentiation rests on certification grade for EU Green Deal compliance and volume scale for e-commerce fulfillment channels. Cost compression in standard tiers is intensifying because virgin ABS and PP feedstock volatility erodes fixed-contract profitability. Mass-market face product buyers exhibit highest price sensitivity; prestige fragrance-adjacent categories show lowest.
Supply Chain Analysis
Contract-manufacturing concentration centers on Albea SA's European furnace network, HCP Packaging's Asian pump-dispenser engineering capacity, and Quadpack Industries' specialized decoration facilities in Spain and France. Raw material flows draw from German polymer processors for petroleum-derived substrates, Italian mineral pigment suppliers for REACH-compliant coatings, and Chinese injection molding clusters for precision closure components. Single-source vulnerability concentrates in European glass furnace capacity for prestige categories. Distribution runs through Rotterdam's container hub for inbound substrates and Rhine-Ruhr logistics corridors for outbound finished packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates and REACH chemical restrictions constitute a dual regulatory inflection, accelerating material transitions that will consolidate converter capabilities around compliant substrate expertise.
For Market Incumbents: Insulate margin pools by deepening backward integration into post-consumer recycled content processing and certified paper lamination capabilities. Albea SA's European manufacturing footprint provides defensive positioning against emerging agile networks, though furnace capacity constraints require selective capacity addition in France or Italy. REACH qualification timelines for decorative coatings represent the priority certification investment to maintain heritage house relationships. For New Entrants and Emerging Players: Germany's e-commerce beauty cluster presents the most penetrable geography, with Berlin and Hamburg direct-to-consumer brands demanding sub-5,000 unit runs that legacy converters struggle to fulfill. White-space targets include transit-optimized dimensional engineering for online-exclusive launches and 6-week turnaround production cycles. Go-to-market positioning should emphasize agile converter network partnerships over asset-heavy furnace investments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized decoration boutiques and dual-jurisdiction compliance service providers. Long-term viability across the analysis window hinges on converter flexibility across glass, metal, and certified paper alternatives. Acquisition target archetypes include Italian and French finishing specialists with established heritage house relationships. The signal to watch is NMPA registration rule harmonization between EU and Chinese jurisdictions, which would elevate converters with dual-certification expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycled Content Scale-Up | EU Green Deal mandates force substrate transitions that test converter lamination expertise. |
| Dual-Jurisdiction Certification Investment | REACH and NMPA alignment creates service revenue for converters with EU-China expertise. |
| Agile Manufacturing Network Partnership | E-commerce fulfillment demands sub-5,000 unit minimums that compress traditional contracts. |
| Specialized Decoration Capability Acquisition | Premium lip and eye lines in France and Italy require heritage finishing relationships. |
| Airless Pump Engineering Convergence | Serum-infused color cosmetics expand technical differentiation in liquid foundation formats. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating packaging procurement managers at heritage European cosmetic houses, converter plant managers in Germany and France, regulatory affairs specialists navigating REACH and NMPA frameworks, and e-commerce brand supply chain directors in Berlin and Hamburg. Secondary validation drew from ECHA chemical restriction databases, EU Green Deal directive documentation, ANSM and KBA regulatory filings, and customs records tracking substrate flows through Rotterdam. Bottom-up unit economics from converter operations were triangulated against top-down market sizing from packaging material trade associations.
Calibration against historical material transition timelines and regulatory implementation patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include packaging material chemistry, closure type engineering, application category, and end-user channel structure. CAGRs were derived from elasticity-adjusted demand projections incorporating e-commerce penetration rates and professional salon channel rebuilding patterns. Industry-specific forecast inputs encompassed furnace capacity utilization data and biopolymer-barrier film laminate qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian scale players or accelerated EU Green Deal enforcement would shift outcomes beyond modeled ranges. Quarterly review of NMPA registration rule harmonization progress and REACH chemical restriction amendment schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market