
 Europe Cosmetic Packaging Market | 2026-2036
Europe Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cosmetic Packaging Market Foresight
Glass is hardening its position against conventional petroleum-based plastics as brand owners face extended producer responsibility penalties under EU packaging rules. Albéa Group leverages its European tube manufacturing footprint to supply refillable formats for skincare houses in France and Germany. Gerresheimer AG anchors high-end fragrance bottle demand through its specialized molded glass facilities in the Czech Republic and Poland. Verescence SA competes on decorative finishing capabilities that command premium positioning in Paris-based luxury houses.
Europe cosmetic packaging encompasses primary and secondary containment systems engineered from glass, plastic, metal, or paper substrates, typically specified to barrier standards against oxygen ingress, UV degradation, and volatile compound loss while supporting brand differentiation through decoration and dispensing function. Plastic bottles and tubes still dominate unit volume across mass-market personal care, though glass jars and bottles capture disproportionate margin pools in prestige skincare and fragrance where weight and tactile perception signal quality. Pump and sprayer closure types are expanding fastest as airless dispensing technology migrates from professional channels into retail skincare, while screw caps and flip tops remain entrenched in body care and hair care segments where cost sensitivity limits converter investment.
REACH registration requirements and the EU Green Deal's packaging waste reduction targets are reshaping material specifications and supplier qualification timelines across the value chain. ECHA substance restrictions on microplastics and PFAS coatings are eliminating certain decorative finishes and lubricating additives that converters have relied upon for decades. France's AGEC anti-waste law and Germany's VerpackG extended producer responsibility framework add national compliance layers that multinational brand owners must reconcile. Stakeholders should monitor how the EU Packaging and Packaging Waste Regulation recalibrates recycled content mandates and reuse targets before committing to capacity investments in specific material platforms.
Market Dynamics
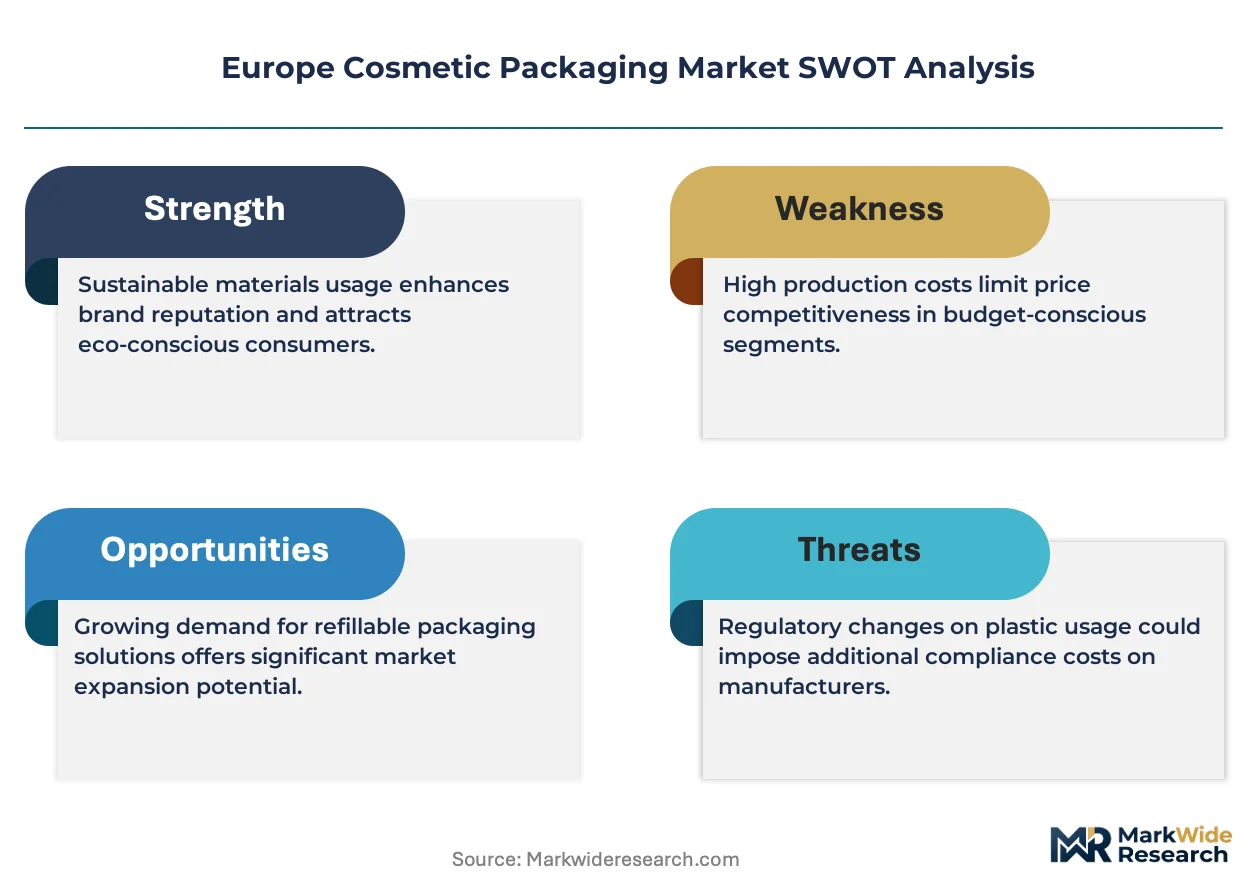
Extended producer responsibility frameworks under the EU Green Deal are forcing brand owners to internalize end-of-life packaging costs, accelerating converter investments in refillable formats and post-consumer recycled material streams across the Rhine-Ruhr and Île-de-France corridors.
Growth Catalysts
- REACH substance restrictions:ECHA microplastic bans are eliminating conventional decorative coatings, creating demand for compliant bio-based finishes in French and German skincare packaging.
- Glass jar adoption:Prestige fragrance houses in Paris and Milan are specifying heavier molded glass to signal quality and justify premium positioning against plastic alternatives.
- Rhine-Ruhr converter density:Germany's packaging cluster enables same-day prototyping for brand headquarters, compressing development cycles for seasonal cosmetic launches.
Market Restraints
- Post-consumer recycled plastic scarcity:Food-grade rPET supply concentrates with limited European recyclers, inflating input costs for mass-market tube converters.
- Decorative finishing limitations:PFAS lubricant bans under REACH eliminate certain high-gloss metallization processes that luxury houses have specified for decades.
- Single-material mandate complexity:France's AGEC anti-waste law requires mono-material packaging by 2025, forcing redesign of multi-component pump assemblies.
Strategic Opportunities
- Poland and Czech Republic glass expansion:Underpenetrated molded fragrance bottle capacity in Central Europe offers cost-advantaged supply for German brand owners.
- Airless dispensing migration:Professional-channel airless pump technology is penetrating retail skincare, opening new specification windows for precision molders.
- EU Packaging and Packaging Waste Regulation:Pending recycled content mandates will create first-mover advantage for converters with verified mass-balance certification systems.
Industry Challenges
- Material provenance documentation:Full supply chain traceability requirements under EU Green Deal compliance timelines strain legacy ERP systems at mid-tier converters.
- Decorative chemist scarcity:PFAS and microplastic restrictions have eliminated core formulation expertise, forcing rapid retraining of finishing line technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cosmetic Packaging Market |
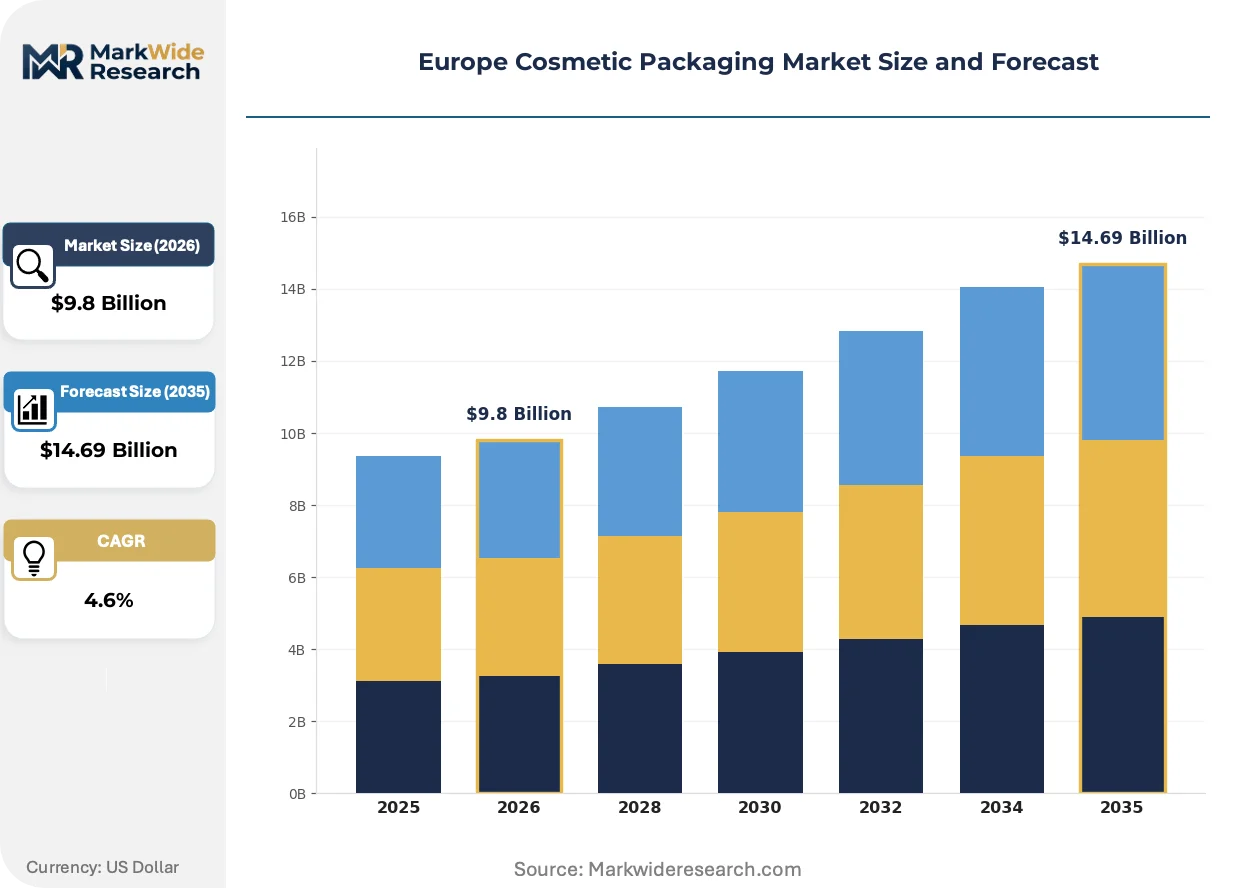
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tubes, Jars, Bottles, Pallets Material: Plastic, Glass, Metal, Paper Closure Type: Screw Caps, Pumps, Sprayers, Flip Tops End User: Personal Care, Makeup, Skincare, Fragrance |
| Companies Covered | HCP Packaging Co., Ltd., Berry Global Inc., Amcor PLC, Verescence SA, Quadpack Industries SA, Albéa Group, Gerresheimer AG, Mondi Group, AptarGroup Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cosmetic Packaging Market Shifts & Advancements
Refillable packaging architectures are displacing single-use formats as the default specification for European prestige skincare, with airless pump systems and modular glass components now standard in new product development briefs from Paris and Hamburg.
Airless dispensing technology is consolidating market share among premium skincare brands seeking to extend product shelf life and justify unit price premiums. German and French houses are specifying these systems for vitamin C and retinol formulations where oxidation sensitivity demands barrier performance. The technology is consolidating converter R&D budgets away from conventional screw-cap closures toward precision piston and bag-in-bottle engineering.
France's AGEC anti-waste law and Germany's VerpackG framework are imposing national compliance layers atop EU-wide extended producer responsibility rules. Brand owners must reconcile divergent reporting timelines and material definitions, forcing investment in multi-jurisdiction compliance management systems. Small and mid-sized converters in the Benelux region are most affected, lacking legal resources to navigate overlapping mandates.
Direct-to-consumer subscription models are reshaping order patterns for cosmetic packaging converters, replacing seasonal bulk procurement with continuous replenishment schedules. German indie skincare brands are leading this shift, specifying smaller minimum order quantities and faster turnaround times. The Rhine-Ruhr cluster has adapted most quickly, leveraging proximity to brand headquarters for just-in-time delivery contracts.
Europe Cosmetic Packaging Market Segmentation
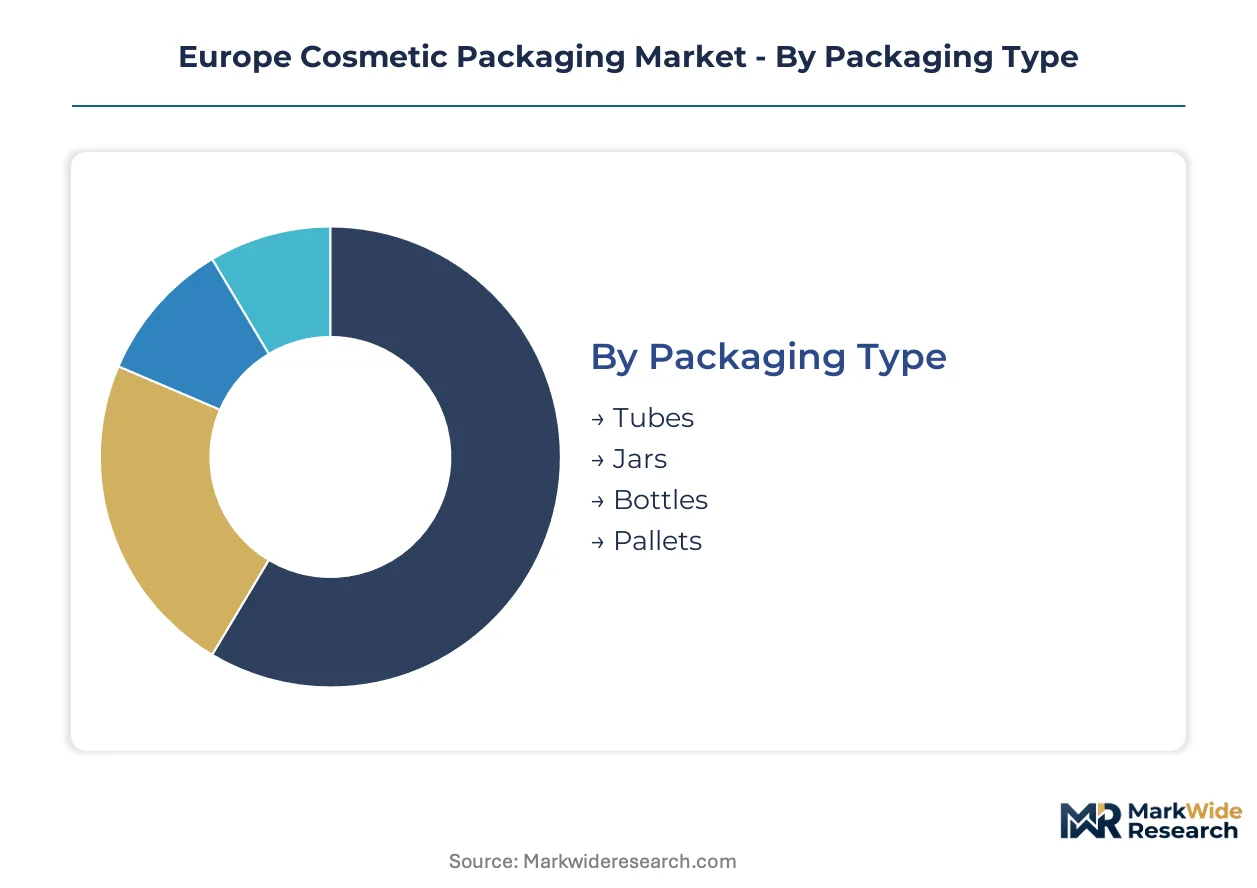
Segmentation in cosmetic packaging determines converter investment priorities and regulatory compliance pathways. Material and closure specifications cascade through supply chains differently across skincare versus fragrance end-uses, forcing brand owners to qualify multiple supplier bases.
Packaging Type:
Upgrade cycles vary by format durability and decoration complexity, with refillable architectures forcing redesign timelines shorter than traditional single-use formats.
- Bottles:Molded glass and PET formats dominate fragrance and skincare liquids, with heavier glass weights specified by Paris-based luxury houses for tactile quality signaling. German indie brands are driving demand for lightweight, post-consumer recycled PET in body care.
- Jars:Wide-mouth glass and thick-wall PP containers serve creams and balms where finger-access dispensing is preferred. French prestige skincare houses specify these for night cream and mask formulations, though refillable pod systems are displacing traditional single-wall designs.
- Tubes:Laminate and extruded plastic formats retain cost advantage in mass-market hair care and body lotion, with Albéa's European footprint supplying seasonal promotional volumes.
- Pallets:Secondary shipping containment for bulk cosmetic ingredient transfer and finished goods distribution, specified to ISPM-15 standards for intra-European logistics.
Bottles lead volumes today; jars are gaining share fastest through skincare premiumization.
Material:
Cost tiers separate mass-market converters from prestige suppliers, with certification requirements and input scarcity widening the gap between commodity and specialty grades.
- Plastic:PET, PP, and PE formats still dominate unit economics across personal care, though food-grade rPET scarcity is inflating costs for mass-market tube converters. REACH microplastic restrictions are eliminating certain decorative coatings that converters have relied upon.
- Glass:Molded soda-lime and borosilicate formats command disproportionate margin pools in fragrance and prestige skincare, with Verescence and Gerresheimer anchoring supply through Czech and Polish manufacturing.
- Metal:Aluminum tubes and aerosol cans serve deodorant and hair spray applications, with mono-material mandates under France's AGEC law forcing redesign of multi-component assemblies.
- Paper:Folding cartons and molded pulp formats are penetrating secondary packaging as brand owners eliminate plastic windows and laminates for EU Green Deal compliance documentation.
Plastic leads volumes today; glass is climbing the fastest on extended producer responsibility penalties.
Closure Type:
Application requirements determine specification, with airless dispensing technology migrating from professional channels into retail skincare and resetting performance expectations.
- Pumps:Precision piston and bag-in-bottle airless systems are consolidating R&D budgets as German and French houses specify these for oxidation-sensitive vitamin C and retinol formulations. The technology extends shelf life and justifies unit price premiums.
- Sprayers:Fine-mist and continuous-spray mechanisms serve fragrance and hair care, with mechanical durability requirements stricter than pump formats due to actuation cycle counts.
- Screw Caps:Threaded closures remain entrenched in body care and hair care segments where cost sensitivity limits converter investment, though tamper-evident bands are becoming standard.
- Flip Tops:Hinged PP closures dominate shower gel and shampoo formats, with single-material mandates forcing elimination of silicone gasket inserts.
Screw caps lead volumes today; pumps are expanding most quickly through skincare premiumization.
End User:
Customer type determines margin structure and regulatory exposure, with prestige skincare and fragrance converters capturing value pools unavailable to mass-market personal care suppliers.
- Skincare:Serum, cream, and mask formats drive the most demanding barrier specifications, with airless dispensing and UV-opaque glass now standard for anti-aging and brightening lines. German dermocosmetic brands are leading refillable format adoption.
- Fragrance:Parfum and eau de toilette presentations prioritize decorative finishing and bottle heft, with Czech and Polish glass capacity offering cost-advantaged supply for German brand owners seeking to defend margin positions.
- Makeup:Compact, lipstick, and mascara formats require precision molding for mechanism integration, with smaller production runs and faster turnaround times than skincare.
- Personal Care:Shampoo, conditioner, and body wash formats remain most price-sensitive, with converters competing on minimum order quantities and Rhine-Ruhr proximity for just-in-time delivery.
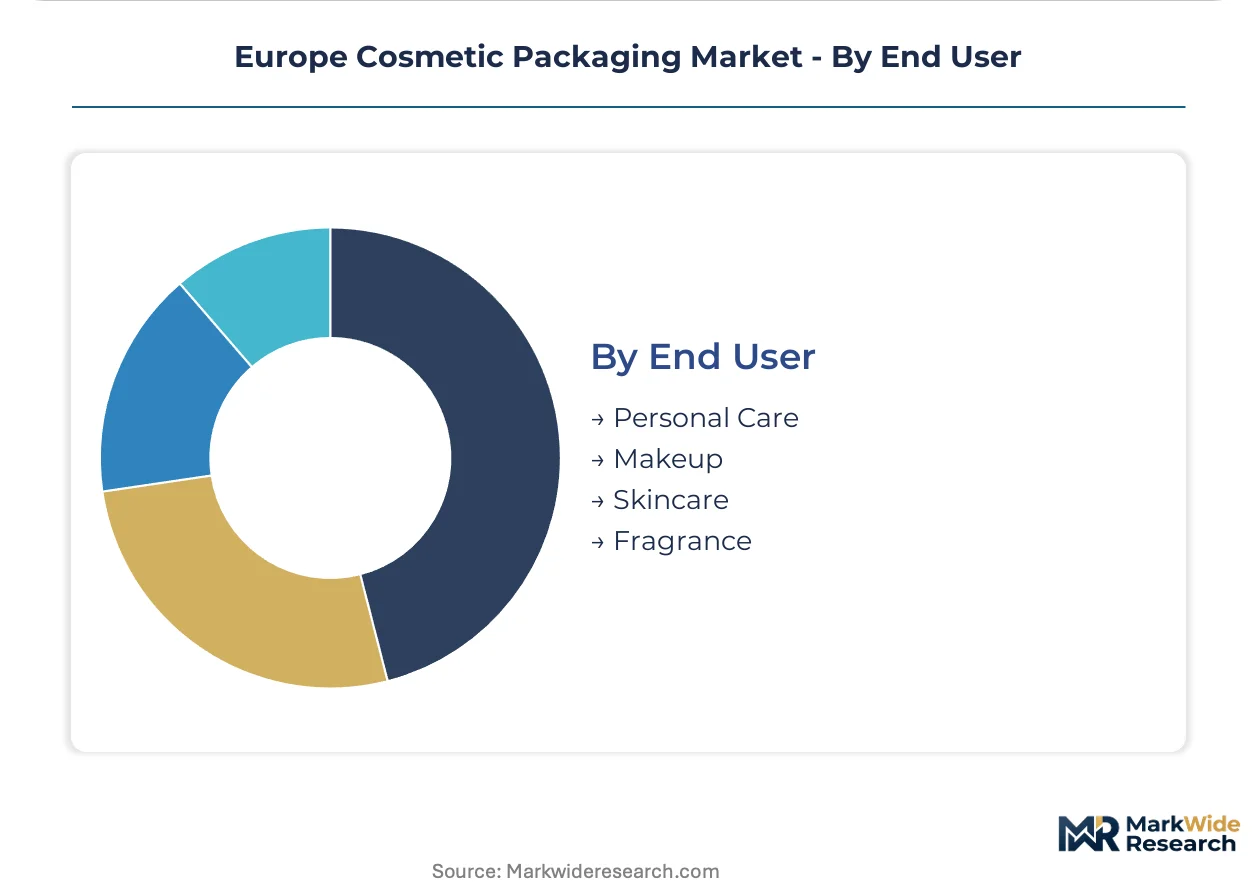
Personal care leads volumes today; skincare shows the steepest expansion trajectory on premiumization and refillable format conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr packaging cluster anchors European cosmetic packaging demand through its dense converter network and same-day prototyping capabilities for brand headquarters in Düsseldorf and Cologne.
Germany
Dermocosmetic brands in Hamburg and Berlin are accelerating refillable glass jar specifications for anti-aging lines. The country's VerpackG extended producer responsibility framework forces converters to document end-of-life cost internalization. North Rhine-Westphalia hosts Albéa Group tube manufacturing and Gerresheimer AG glass operations serving Paris-based luxury houses.
France
Prestige fragrance houses in Paris and Grasse specify heavier molded glass bottles to signal quality against plastic alternatives. The AGEC anti-waste law mandates mono-material packaging by 2025, eliminating multi-component pump assemblies. Île-de-France's cosmetics corridor concentrates Verescence SA decorative finishing and brand headquarters within 50 kilometers.
Italy
Milan-based luxury skincare houses are adopting airless dispensing systems for vitamin C formulations sensitive to oxidation. REACH microplastic restrictions eliminate conventional decorative coatings, forcing converters to source bio-based finishes. Lombardy's precision molding cluster supplies compact and lipstick mechanisms with faster turnaround than Asian competitors.
Poland
German brand owners are qualifying Czech and Polish glass capacity for cost-advantaged fragrance bottle supply. ECHA substance restrictions on PFAS lubricants complicate metallization processes that luxury houses have specified for decades. Lower Silesia's emerging converter base offers 15-20 percent cost savings versus Western European molding operations.
United Kingdom
Indie skincare brands in London are driving direct-to-consumer subscription packaging with smaller minimum order quantities and compressed development cycles. The country's post-Brexit regulatory divergence from REACH creates compliance friction for converters serving EU and UK markets simultaneously. Southeast England's logistics hubs enable just-in-time delivery contracts for German brand owners defending margin positions.
Europe Cosmetic Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters invest in Central European glass molding and airless pump assembly lines ahead of EU Packaging and Packaging Waste Regulation mandates. The vendor base stratifies across three tiers: multinational diversified packaging conglomerates, mid-cap European specialists with regional converter density, and niche decorative finishers serving Paris-based luxury houses. Two strategic archetypes are consolidating share: glass specialists with Czech and Polish manufacturing footprints, and tube converters leveraging laminate extrusion expertise for seasonal promotional volumes. M&A activity and geographic expansion into underpenetrated Central European markets represent the dominant competitive moves.
Within the glass specialist tier, Verescence SA and Gerresheimer AG exemplify converters capturing disproportionate margin pools in prestige fragrance and skincare through decorative finishing capabilities and specialized molded soda-lime facilities. Among diversified packaging conglomerates, Berry Global Inc. and Amcor PLC occupy positions spanning multiple material platforms and end-use segments, enabling cross-selling to multinational brand owners seeking consolidated supplier relationships. Albéa Group represents the tube converter archetype, leveraging its European manufacturing footprint to supply refillable formats for German and French skincare houses.
| Leading Market Players |
|---|
| HCP Packaging Co., Ltd. |
| Berry Global Inc. |
| Amcor PLC |
| Verescence SA |
| Quadpack Industries SA |
| Albéa Group |
| Gerresheimer AG |
| Mondi Group |
| AptarGroup Inc. |
| Others |
Supply & Pricing Matrix
Prestige skincare brand procurement teams in Paris and Hamburg concentrate demand for certified refillable formats, locking in contract-based long-term offtake agreements that embed volume commitments against input cost volatility.
Pricing Analysis
Input-cost pass-through from food-grade rPET scarcity and borosilicate glass energy surcharges is compressing margins for mass-market tube converters while insulating premium glass specialists. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost. Price erosion runs through mass-market personal care as Rhine-Ruhr converters compete on minimum order quantities. Mass-market personal care buyers exhibit highest price sensitivity; Paris-based luxury houses show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German dermocosmetic brands mandate qualification of both Czech and Polish glass capacity alongside domestic Rhine-Ruhr converters. Supply concentrates in Germany, France, and Poland, with raw material dependencies spanning soda-lime glass batch, pharmaceutical-grade rPET resin, and PFAS-free decorative coatings. Single-source vulnerability in food-grade rPET recycling capacity creates structural risk. Distribution runs through brand headquarters clusters for just-in-time delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Central European glass capacity offers 15-20 percent cost savings versus Western European molding operations, creating geographic-arbitrage value for brand owners navigating France's AGEC compliance timelines against Germany's VerpackG reporting requirements.
For Market Incumbents: To counter PFAS and microplastic coating elimination under REACH, invest in bio-based decorative finish R&D partnerships and backward integration into Czech glass batch sourcing. Certify mass-balance systems ahead of EU Packaging and Packaging Waste Regulation mandates to capture first-mover recycled content premiums. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription packaging models targeting German indie skincare brands with compressed development cycles and smaller minimum order quantities. Poland's underpenetrated molded fragrance bottle capacity offers the most penetrable geography for cost-advantaged supply qualification. For Investors and Strategic Acquirers: Tube and glass converters with verified refillable format engineering capabilities are the most active acquirer targets in this space, reflecting long-term viability through the EU Green Deal implementation window. Monitor ECHA substance restriction expansion timelines as the inflection indicator for decorative finishing technology replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Central European Glass Molding | Polish and Czech facilities offer cost-advantaged supply for German fragrance brand owners. |
| Refillable Format Engineering Certification | Mass-balance verification creates competitive moat under pending EU recycled content mandates. |
| Backward Integration into rPET Sourcing | Food-grade recyclate scarcity forces converters to secure captive supply from limited European recyclers. |
| Bio-Based Decorative Finish Development | REACH microplastic bans eliminate conventional coatings, requiring rapid formulation replacement. |
| Direct-to-Consumer Packaging Service Launch | Subscription models reshape order patterns toward continuous replenishment schedules. |
Research Methodology
Multiple input streams — converter production data, brand owner procurement specifications, and regulatory filing documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews with packaging procurement managers, decorative finishing chemists, sustainability compliance officers, and Rhine-Ruhr cluster operations directors informed demand-side assumptions. Secondary validation drew from ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation draft texts, and national extended producer responsibility reporting disclosures.
Historical volume trajectories were cross-referenced against panel input from converter capacity planners to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include material platform, closure type, end-use application, and geographic production hub. CAGRs were derived from slope analysis of normalized shipment data and brand owner specification trend indices, with airless dispensing technology penetration and refillable format adoption rates serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA restriction timelines or rPET supply disruption scenarios. Deviation in EU Packaging and Packaging Waste Regulation final recycled content mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Cosmetic Vials Market