
 Europe Plastic Cosmetic Packaging Market | 2026-2036
Europe Plastic Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plastic Cosmetic Packaging Market Analysis
Refill subscription programs for cosmetic containers is rebalancing how value gets captured across the value chain. Albea Group leverages its decorative finishing capabilities to anchor premium makeup packaging relationships with French and Italian beauty houses. Aptar Group differentiates through airless pump technology leadership, sustaining R&D intensity in dosing precision for sensitive skincare formulations.
Europe plastic cosmetic packaging comprises engineered polymer vessels, closures, and dispensing systems designed to protect, portion, and present personal care products through barrier-controlled, shelf-stable construction. Primary fabrication employs injection molding, blow molding, and thermoforming of polyethylene, polypropylene, PET, and PVC resins to achieve chemical compatibility, opacity control, and dimensional stability across temperature ranges. Bottles and jars occupy mature volume positions in skincare and haircare, while pumps represent the fastest-expanding margin pool as brands convert to airless and precision-dosing formats for active-ingredient preservation. Sustainable packaging types are gaining structural weight as regulatory thresholds harden, though rigid formats still dominate absolute tonnage through established filling-line compatibility.
REACH chemicals regulation, the EU Green Deal packaging waste framework, and the F-Gas Regulation collectively constrain material choices and mandate recyclability pathways across member states. ECHA substance restrictions and national extended producer responsibility schemes shape how formulators specify polymer grades and how converters qualify new resin streams. Stakeholders must monitor evolving delegated acts under the Packaging and Packaging Waste Regulation to determine capital allocation between mechanical recycling integration and bio-based material pilot programs.
Market Dynamics
The EU Green Deal packaging waste framework is forcing converters to reengineer polymer specifications and recyclability pathways ahead of delegated acts under the Packaging and Packaging Waste Regulation. This regulatory compression is redistributing capital allocation across mechanical recycling integration, bio-based material pilots, and monomaterial format redesign.
Growth Catalysts
- REACH chemical compliance:ECHA substance restrictions on microplastics and restricted chemicals are accelerating demand for compliant polymer grades that maintain barrier properties in skincare formulations.
- Airless pump technology:Precision dosing systems for active-ingredient preservation are expanding addressable margins as clean-label skincare brands convert from jar formats.
- Extended producer responsibility schemes:National EPR frameworks in Germany, France, and Italy are creating direct financial incentives for refillable and recyclable packaging investments.
Market Restraints
- Recycled PET feedstock volatility:Bottle-to-bottle recycling competition and collection infrastructure gaps are constraining rPET availability for cosmetic-grade applications.
- F-Gas Regulation constraints:Blowing agent restrictions under EU F-Gas rules are limiting foam and insulated packaging options for temperature-sensitive formulations.
- Monomaterial technical limitations:Current barrier performance of single-polymer structures falls short of multilayer films for oxygen-sensitive actives, slowing full conversion.
Strategic Opportunities
- Poland and Romania manufacturing:Underdeveloped converter capacity in Central and Eastern Europe offers first-mover positioning for regional brands seeking reduced logistics costs.
- Refill subscription infrastructure:Direct-to-consumer channel integration enables durable primary packaging with recurring revenue from consumable refills.
- CSRD disclosure alignment:Corporate Sustainability Reporting Directive mandates are creating advisory and certification service demand for packaging carbon footprint verification.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with expertise in compatibilizers and degradation-resistant additives command premium compensation, constraining R&D scaling.
- Legacy filling-line retrofit costs:Airless pump and pouch format adoption requires capital expenditure on new capping and sealing equipment across established manufacturing footprints.
- Recyclability certification timelines:Interseroh and Citeo qualification processes for new material streams extend product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plastic Cosmetic Packaging Market |
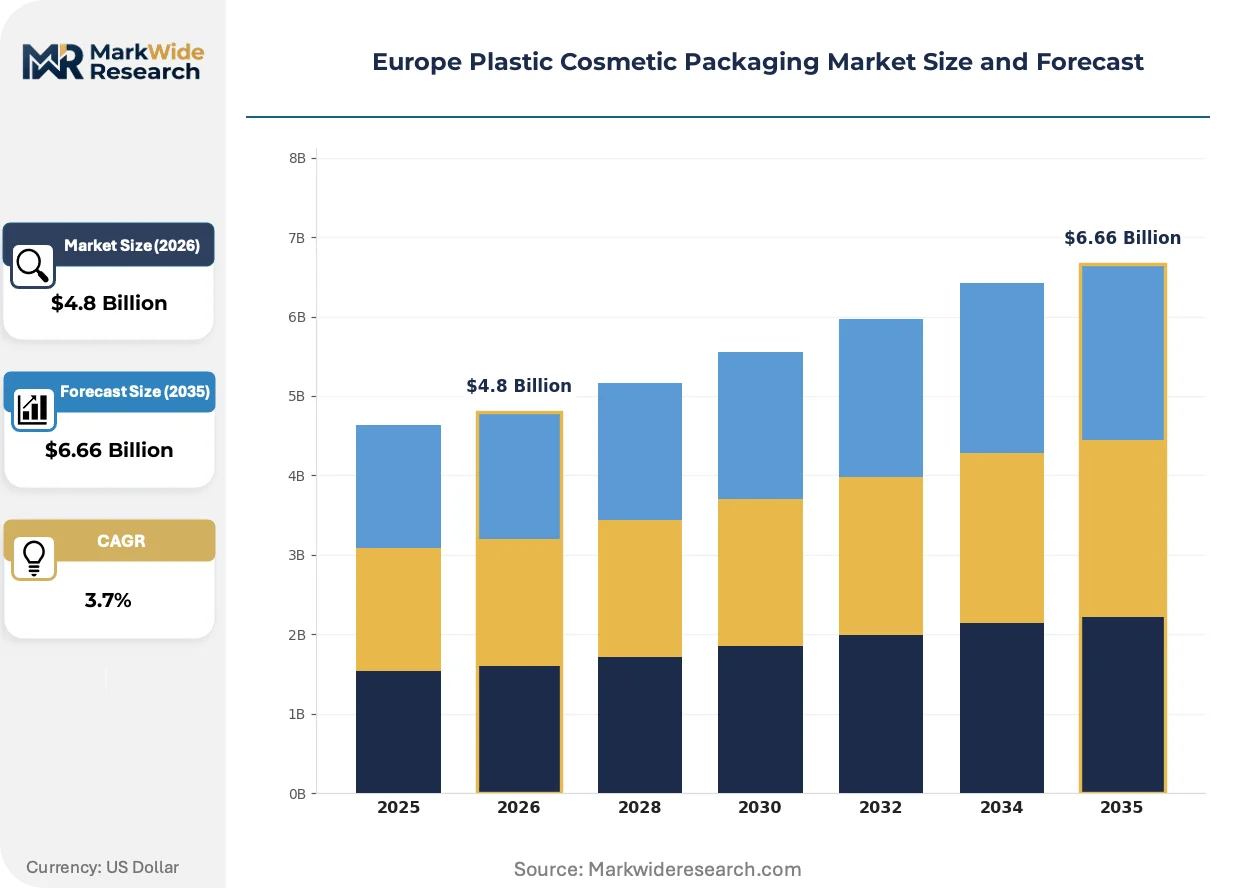
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tubes, Pumps Material: Polyethylene, Polypropylene, PET, PVC End User: Skincare, Haircare, Makeup, Fragrance Packaging Type: Rigid, Flexible, Sustainable, Customizable |
| Companies Covered | Amcor, Albea Group, Aptar Group, Berry Global, Huhtamaki Oyj, Gerresheimer, Sealed Air Corporation, Mondi Group, ALPLA Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plastic Cosmetic Packaging Market Emerging Trajectories
Monomaterial packaging architectures are consolidating technical and commercial attention as the dominant response to EU recyclability mandates. Three interconnected developments are reshaping how converters and brands specify, source, and scale next-generation formats.
Barrier-enhanced polyethylene structures are consolidating market share in premium skincare as L'Oréal and Beiersdorf accelerate conversion timelines. These single-polymer tubes and bottles replace multilayer laminates while maintaining oxygen and moisture protection for retinol and vitamin C formulations. German converters are consolidating production capacity around these grades, compressing legacy PVC and PS demand in the process.
The EU Packaging and Packaging Waste Regulation delegated acts are mandating minimum recycled content thresholds and harmonized Extended Producer Responsibility fee structures. This regulatory architecture is forcing brand owners to pre-qualify converters based on certified recycling stream access rather than unit cost alone. French and Italian beauty houses are responding by locking multi-year supply agreements with rPET-integrated molders ahead of 2030 compliance deadlines.
Direct refill models are compressing traditional retail shelf presence as brands bypass wholesale distribution for subscriber-locked container programs. German clean beauty startups and established Parisian houses are piloting durable primary vessels with mail-order concentrate replenishment, shifting value capture from volume manufacturing to recurring consumables. This channel disintermediation is most visible in premium facial care, where customer lifetime value calculations now favor higher upfront packaging investment.
Europe Plastic Cosmetic Packaging Market Segmentation
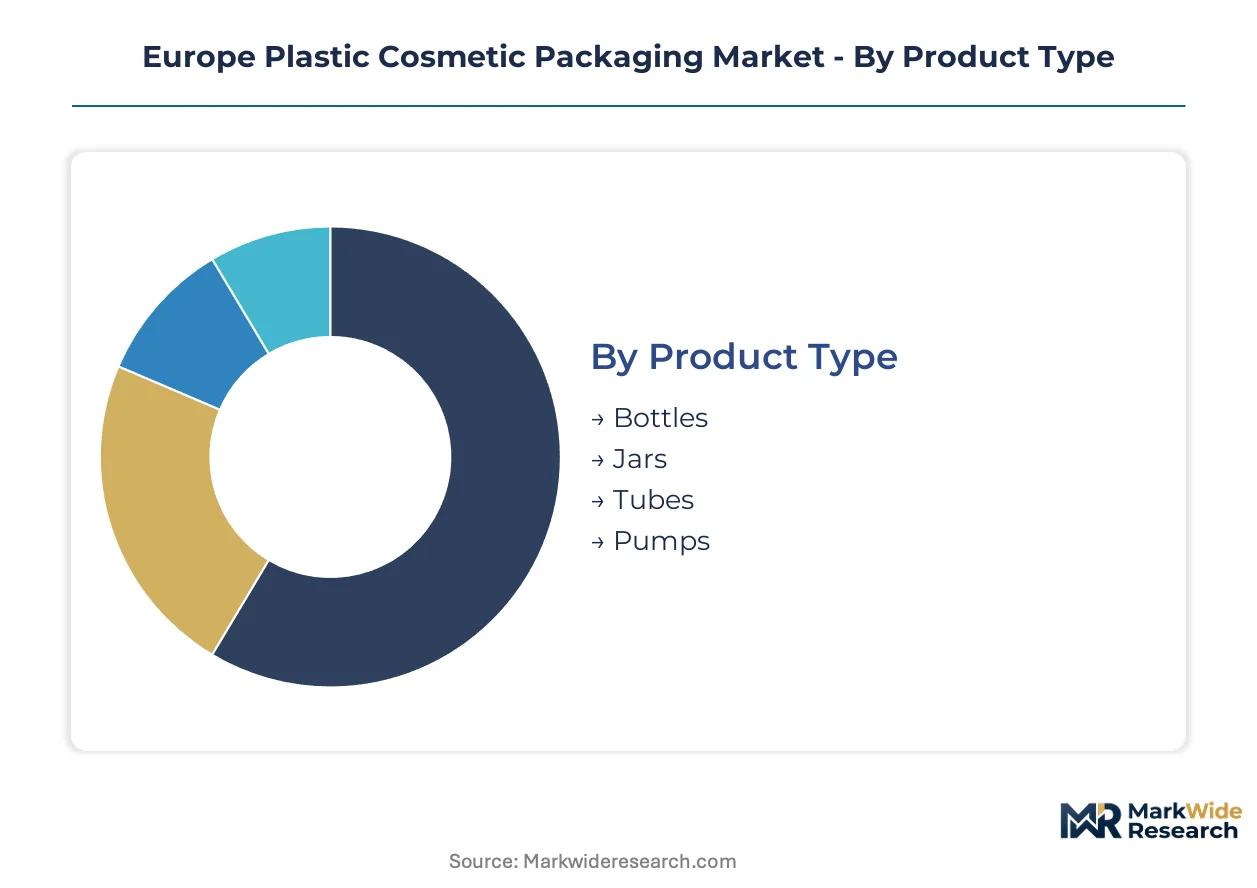
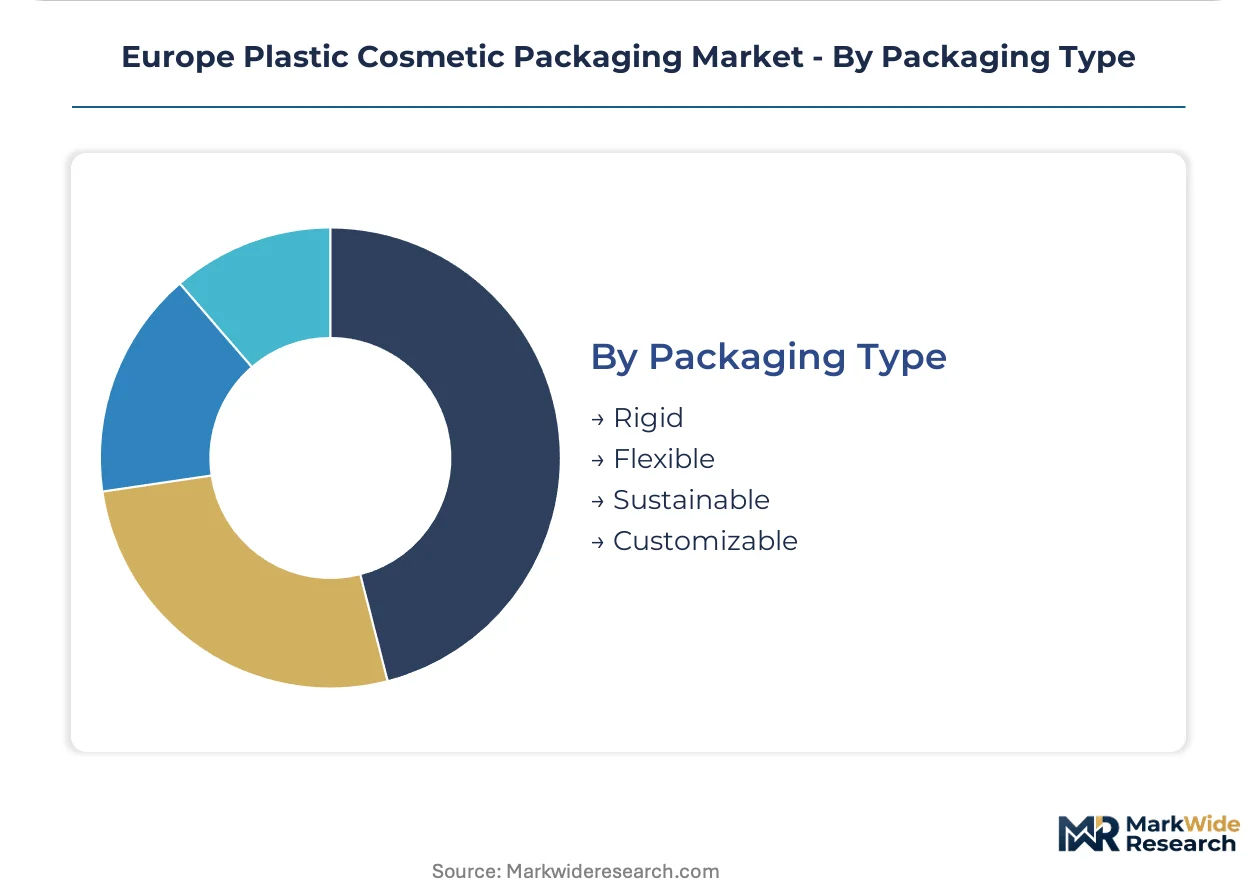
Packaging format decisions in European cosmetics hinge on formulation compatibility, shelf-life requirements, and filling-line economics. Brand owners specify product type and material combinations based on active-ingredient sensitivity, while end-use category and sustainability positioning determine final packaging architecture.
Product Type:
Purchase volumes concentrate where clean-label formulations demand precise dosing and contamination control.
- Pumps:Airless and precision-dosing systems employ piston or diaphragm mechanisms to isolate oxygen-sensitive actives from atmospheric exposure. German and French premium skincare brands are converting jar-based regimens to pump formats as retinol and vitamin C concentrations rise in mass-market lines.
- Bottles:Blow-molded PET and HDPE vessels dominate shampoo, conditioner, and body wash applications through established supply chains and recycling stream compatibility. Italian haircare manufacturers specify lightweight bottle formats to reduce EPR fees under national packaging waste frameworks.
- Jars:Wide-mouth containers serve thick emulsions and balms requiring direct finger or spatula access.
- Tubes:Collapsible polyethylene and laminate structures deliver controlled dispensing for creams and gels in travel and sample formats.
Bottles lead on scale; pumps lead on momentum.
Material:
Polymer selection tracks regulatory compliance timelines and recycling infrastructure maturity across member states.
- PET:Crystalline polyester delivers clarity, barrier performance, and established bottle-to-bottle recycling pathways. French and German converters are locking multi-year rPET supply agreements ahead of EU Green Deal recycled content mandates.
- Polypropylene:Semicrystalline polyolefin offers chemical resistance and monomaterial compatibility for tubes and closures. Italian packaging houses are expanding PP capacity as multilayer laminate demand contracts under recyclability pressure.
- Polyethylene:Flexible and rigid grades serve squeeze tubes, bottles, and caps through versatile processing windows.
- PVC:Chlorinated polymer retains niche position in fragrance overcaps and transparent boxes despite declining cosmetic-grade applications.
PET leads on scale; polypropylene leads on momentum.
End User:
Category growth rates diverge based on active-ingredient complexity and direct-to-consumer channel penetration.
- Skincare:Serums, moisturizers, and sun care formulations demand barrier-controlled packaging for photo- and oxidation-sensitive actives. German clean beauty startups are piloting refillable primary vessels with mail-order concentrate replenishment, compressing traditional retail shelf economics.
- Haircare:Shampoo and conditioner volumes sustain bottle format dominance through high-throughput filling lines and established rPET supply chains.
- Makeup:Color cosmetics require precision dispensing and aesthetic finishing for shelf differentiation.
- Fragrance:Premium positioning drives custom bottle shapes and decorative overcap investments with limited format standardization.
Skincare leads on scale; skincare also leads on momentum.
Packaging Type:
Capital allocation splits between legacy rigid infrastructure and emerging sustainable format qualification.
- Sustainable:Monomaterial architectures, post-consumer recycled content, and refillable systems attract compliance-driven investment. French beauty houses are pre-qualifying converters based on certified recycling stream access rather than unit cost alone.
- Rigid:Injection- and blow-molded bottles, jars, and caps retain volume dominance through filling-line compatibility and dimensional stability.
- Flexible:Pouches and sachets serve sample and travel formats with reduced material intensity.
- Customizable:Decorative finishing and shape differentiation support premium brand positioning in limited production runs.
Rigid leads on scale; sustainable leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher airless pump adoption rates than Italy, where refillable jar formats retain stronger heritage brand loyalty. Converter capacity concentrates in Western European manufacturing corridors, with Central and Eastern Europe emerging as cost-competitive alternatives for regional brand supply.
Germany
Clean beauty startups and established skincare houses drive precision-dosing pump demand for retinol and vitamin C formulations. The national EPR framework under Verpackungsgesetz imposes escalating fees on non-recyclable formats. Stuttgart and Hamburg host specialized molders scaling monomaterial polyethylene capacity for barrier-enhanced tubes.
France
Parisian luxury houses anchor premium decorative packaging demand for limited-edition fragrance and color cosmetic releases. REACH compliance timelines and delegated acts under the EU Packaging and Packaging Waste Regulation accelerate rPET supply contract lock-ins. The Île-de-France corridor concentrates converter relationships with certified recycling stream access ahead of 2030 mandates.
Italy
Heritage makeup brands sustain demand for ornate compact and lipstick case finishing with metallic overcap decoration. ECHA substance restrictions on microplastics in rinse-off products reshape polymer grade specifications. Lombardy-based packaging houses expand polypropylene tube capacity as multilayer laminate demand contracts under recyclability pressure.
Poland
Regional beauty brands and contract manufacturers seek reduced logistics costs through proximate converter relationships. The EU Green Deal packaging waste framework creates compliance-driven investment windows for first-mover molders. Warsaw and Łódź industrial zones attract blow-molding capacity for lightweight PET bottles serving Central European haircare markets.
United Kingdom
Independent skincare labels and direct-to-consumer brands pilot refill subscription models with durable primary vessels. Post-Brexit regulatory divergence from EU packaging waste rules creates transitional uncertainty for cross-border supply chains. Greater Manchester and West Midlands converters qualify recycled content streams for brands targeting dual-market compliance.
Europe Plastic Cosmetic Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium skincare favoring integrated design houses and mass haircare tilting toward scale molders. The vendor base organizes around three tiers: global diversified packaging conglomerates with cross-category polymer expertise, European-focused cosmetic specialists with decorative finishing capabilities, and regional molders competing on unit cost and logistics proximity. Consolidation pressure intensifies as brands reduce supplier counts to simplify EPR compliance and carbon footprint verification. Strategic moves concentrate on mechanical recycling integration partnerships and multi-year rPET supply agreements.
Among diversified packaging conglomerates, Amcor and Berry Global exemplify scale-driven archetypes with broad polymer processing capabilities across multiple end-use categories. Albea Group and Aptar Group occupy specialist positions, with the former representing decorative finishing expertise for premium color cosmetics and the latter exemplifying precision-dosing technology leadership for sensitive skincare formulations. These named entities anchor competitive dynamics without exhausting the participant landscape.
| Leading Market Players |
|---|
| Amcor |
| Albea Group |
| Aptar Group |
| Berry Global |
| Huhtamaki Oyj |
| Gerresheimer |
| Sealed Air Corporation |
| Mondi Group |
| ALPLA Group |
| Others |
Supply Flow & Price Mechanics
rPET resin price indices cascading from bottle-to-bottle recycling competition compress converter margins into three distinct pricing tiers across European cosmetic packaging supply chains. German and French brand procurement teams now pre-qualify molders based on certified recycling stream access rather than unit cost alone, rewiring traditional supplier selection economics.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for standard-grade PET bottles serving Central European haircare markets. Three-tier pricing structure across premium, standard, and economy levels stratifies around barrier performance certification and recycled content verification under EPR frameworks. Pricing pressure stems from rPET feedstock volatility as collection infrastructure gaps constrain cosmetic-grade availability. Mass-market shampoo brands exhibit highest price sensitivity, while French luxury houses absorb premium positioning costs for decorative finishing and monomaterial qualification.
Supply Chain Analysis
Interseroh and Citeo qualification timelines gate converter access to certified recycling streams, extending product development cycles and concentrating supply relationships among pre-qualified molders. Germany, France, and Italy anchor primary fabrication capacity, with Poland and Romania emerging as cost-competitive alternatives. The supply chain draws from virgin PET resin, post-consumer flake, and compatibilizer additives for barrier-enhanced monomaterial structures. Single-source vulnerability concentrates around German specialized molders scaling airless pump capacity. Distribution runs through brand-direct contracts, regional beauty distributors, and filling-line integrated supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European plastic cosmetic packaging rests on converter consolidation around mechanical recycling integration and premium-tier shift toward refill subscription economics. Brands capturing recurring consumable revenue offset higher upfront durable vessel investment through extended customer lifetime value.
For Market Incumbents: Lock in multi-year rPET supply agreements ahead of EU Packaging and Packaging Waste Regulation delegated acts mandating minimum recycled content thresholds. Deepen backward integration into post-consumer collection partnerships to secure feedstock certainty against bottle-to-bottle recycling competition. Pre-empt emerging Polish and Romanian molders by anchoring regional brand relationships through logistics proximity and EPR compliance bundling.
For New Entrants and Emerging Players: REACH chemical compliance and ECHA substance restrictions on microplastics in rinse-off products open a window for compatibilizer-specialized compounders serving Italian and German clean beauty startups. Target underdeveloped Central European converter capacity for regional brand supply with reduced logistics costs. Lead with mail-order concentrate replenishment infrastructure to capture refill subscription economics bypassing traditional wholesale distribution.
For Investors and Strategic Acquirers: Asymmetric upside sits with monomaterial-specialized molders holding Interseroh and Citeo pre-qualification for barrier-enhanced polyethylene tubes. Long-term viability over the coming decade hinges on mechanical recycling integration depth rather than bio-based material pilot scale. Watch for delegated act publication timing under the EU Packaging and Packaging Waste Regulation as inflection indicator for capital allocation toward compliance-ready assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Integration | Secures rPET feedstock access ahead of EU Green Deal recycled content mandates. |
| Monomaterial Format Qualification | Unlocks EPR fee reductions and Citeo certification for French beauty house supply. |
| Refill Subscription Infrastructure | Captures recurring revenue from consumable concentrates in German clean beauty channels. |
| Airless Pump Capacity Expansion | Serves retinol and vitamin C formulation conversion from jar formats in premium skincare. |
| Central European Manufacturing Footprint | Reduces logistics costs for Polish and Romanian regional brand procurement. |
Methodological Framework
Bottom-up skincare and haircare demand modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with brand packaging directors, converter plant managers, EPR scheme administrators, and polymer procurement leads at German and French beauty houses were cross-validated against secondary sources including ECHA substance restriction databases, national packaging waste framework filings, and customs records for PET resin trade flows. Triangulation between end-use consumption patterns and supply-side fabrication capacity yields volume and value estimates.
Input-output matrices map polymer grade specifications to formulation compatibility requirements across the projection horizon. Segmentation dimensions include packaging format, material resin, end-use category, and sustainability positioning tier. CAGRs were derived from regression analysis of historical conversion rates and regulatory compliance timelines. Forecast inputs incorporate airless pump adoption curves, refill subscription penetration assumptions, and rPET availability constraints under bottle-to-bottle recycling competition.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Packaging and Packaging Waste Regulation implementation or prolonged rPET feedstock shortage. Model outputs reflect assumptions on brand conversion timelines to monomaterial architectures and EPR fee structure harmonization across member states. A model refresh is warranted upon material change in delegated act publication schedules or mechanical recycling infrastructure investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Skin Care Packaging Market