
 Asia Pacific Personal Care Packaging Market | 2026-2036
Asia Pacific Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Personal Care Packaging Market Outlook
Skilled polymer engineering talent is unwinding capacity bottlenecks across Southeast Asian converting hubs. Amcor plc leverages its integrated film-to-bottle platform to serve multinational skincare brands from Thai manufacturing bases. HCP Packaging Co. Ltd anchors premium glass and acrylic jar supply for color cosmetics houses in Shanghai and Seoul. AptarGroup Inc. dominates dispensing closure technology for fragrance and serum applications, sustaining R&D intensity in precision molding.
Asia Pacific personal care packaging encompasses primary and secondary containment systems formulated from polyethylene terephthalate, polypropylene, borosilicate glass, and aluminum substrates, engineered to protect active cosmetic ingredients from oxidation, UV degradation, and microbial ingress while enabling controlled consumer dispensing. Bottles and tubes command the largest volume positions across haircare and body care lines, though sachets register the fastest structural expansion as single-use formats penetrate rural India and Indonesia through kirana store networks. Plastic retains material dominance but faces margin compression as brand owners mandate post-consumer recycled content thresholds, while glass captures premium positioning in skincare and fragrance segments where weight and tactile perception command shelf price realization.
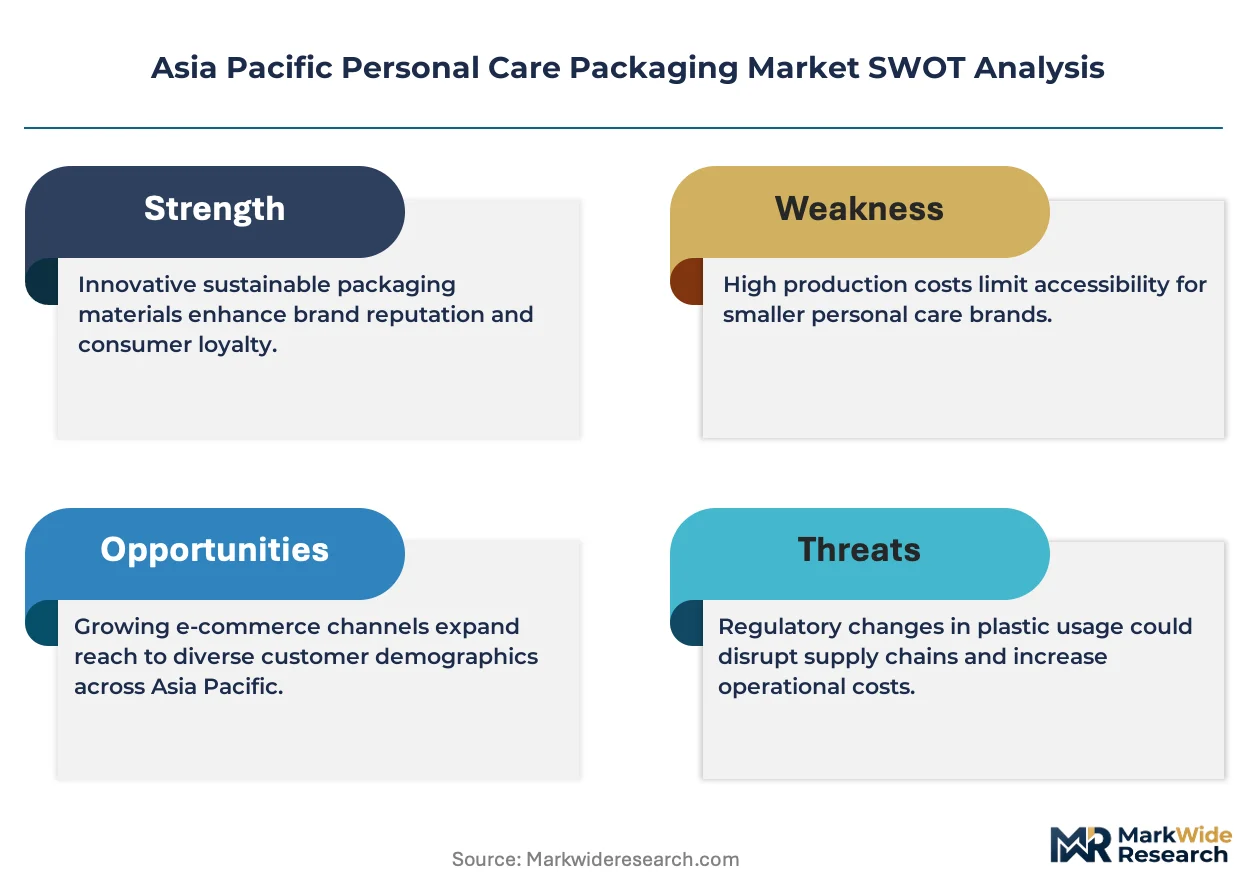
China's SAMR enforces GB standards governing cosmetic packaging recyclability and heavy metal limits, while India's BIS certification mandates material safety disclosures for imported primary packaging. The EU Green Deal's extraterritorial REACH compliance requirements shape export-oriented converter specifications across Malaysian and Indonesian plants. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and national labeling mandates to determine regional hub investments versus country-specific production footprints.
Market Dynamics
China's GB standards for cosmetic packaging recyclability are compressing material specifications across converter supply chains, forcing rapid substrate substitution and process retooling in polyethylene terephthalate and polypropylene extrusion lines.
Growth Catalysts
- Refillable format penetration:Skincare brands across Southeast Asia are expanding container demand as pump-refill systems and aluminum pod formats capture shelf space in organized retail channels.
- GB standards compliance:China's SAMR enforcement of heavy metal limits and recyclability mandates is accelerating technical upgrades in domestic converting capacity.
- Kirana network expansion:Single-use sachets are penetrating rural India and Indonesia through traditional grocery networks, driving volume demand for flexible laminate structures.
Market Restraints
- Post-consumer recycled resin shortage:Brand owner mandates for PCR content thresholds are squeezing converter margins as qualified rPET and rPP supply concentrates in Thai and Malaysian collection hubs.
- Glass weight penalty:Premium skincare and fragrance segments face logistics cost inflation as borosilicate and soda-lime glass jars retain tactile positioning despite freight density disadvantages.
- REACH extraterritoriality:EU Green Deal compliance requirements are fragmenting converter specifications across Malaysian and Indonesian export-oriented plants.
Strategic Opportunities
- Tier-two Indian cities:Organized retail penetration for beauty products is deepening beyond Mumbai, Delhi, and Bangalore, creating whitespace for secondary packaging localization.
- Dispensing closure convergence:Precision molding and airless pump technologies are merging in serum and fragrance applications, opening premium positioning for integrated solution providers.
- ASEAN harmonization lag:Divergence between regional labeling mandates and national requirements creates arbitrage potential for hub-and-spoke manufacturing footprints centered in Thailand.
Industry Challenges
- Polymer engineering talent scarcity:Southeast Asian converting hubs face capacity bottlenecks as skilled formulator and extrusion specialist pools fail to expand with equipment installation rates.
- Dual certification timelines:Simultaneous BIS disclosure mandates for India and GB standard testing for China are extending product launch cycles for multinational brand portfolios.
- Legacy equipment retrofit costs:Existing injection molding and blow molding lines require substantial capital reconfiguration to process post-consumer recycled streams without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Personal Care Packaging Market |
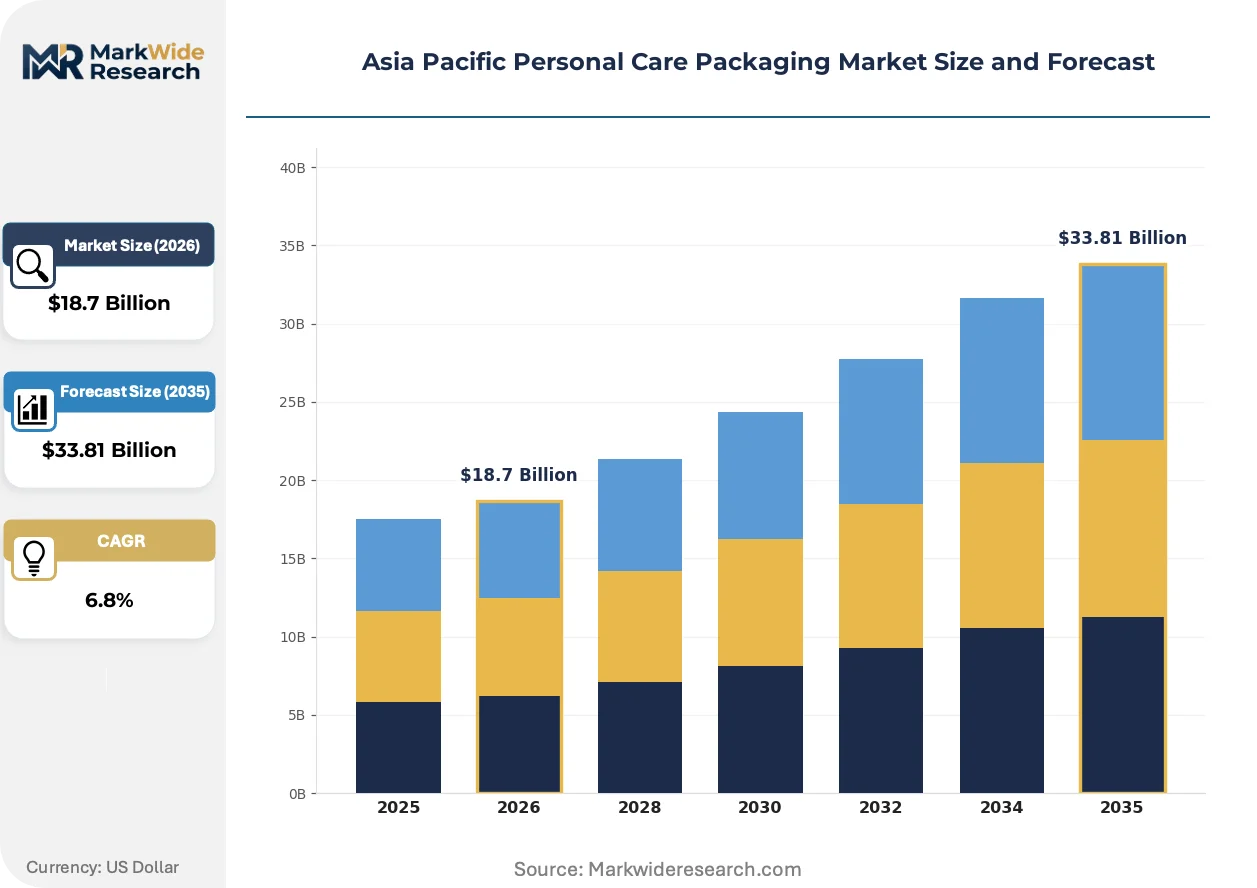
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Tubes, Jars, Sachets Material: Plastic, Glass, Metal, Paper End User: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Albea SA, HCP Packaging Co. Ltd, Berry Global Group, Silgan Holdings Inc., Bemis Company Inc., Amcor plc, AptarGroup Inc., Mondi plc, Crown Holdings, Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Personal Care Packaging Market Strategic Shifts
Active ingredient protection requirements and dispensing precision demands are reshaping substrate selection and closure engineering across skincare, haircare, and fragrance categories in Asia Pacific markets.
Airless pump technology is miniaturizing. This vacuum-dispensing system eliminates oxidation and microbial ingress for vitamin C and retinol formulations. Premium Korean and Japanese skincare houses are adopting sub-15ml micro-airless formats for travel retail and subscription sampling. The technology is miniaturizing unit economics and enabling dose-controlled premiumization in previously commoditized tube and jar segments.
China's SAMR is tightening GB/T enforcement for cosmetic packaging heavy metal limits and recyclability labeling. The industrial consequence is accelerated substitution of decorative metalized films and multi-layer laminates with mono-material polyethylene structures. Color cosmetics houses in Shanghai and Guangzhou are most affected, responding with accelerated supplier audits and material pre-certification programs to avoid customs detention.
Single-use sachet demand is rotating from urban convenience stores toward rural kirana networks in India and Indonesia. Traditional flexible packaging converters are disintermediated by integrated film-to-sachet players with direct brand relationships. This channel compression is most visible in mass-market shampoo and conditioner segments where unit price points below ten rupees dominate volume.
Asia Pacific Personal Care Packaging Market Segmentation
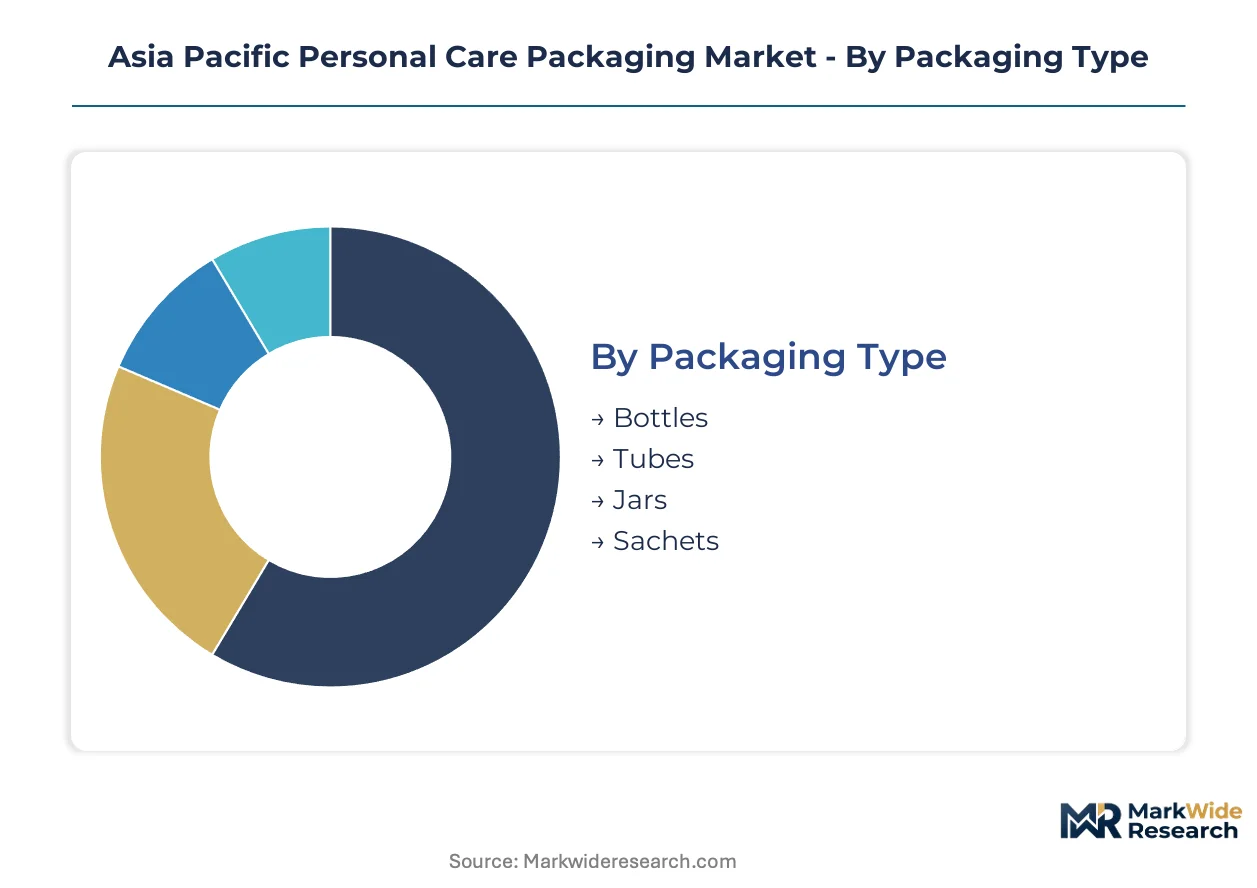
Packaging format and material selection in Asia Pacific personal care directly determine logistics cost structures and regulatory compliance burdens across diverse national standards. Substrate choices and containment geometries segment margin capture between mass-market converters and premium solution providers serving multinational beauty houses.
Packaging Type:
Margin pools concentrate in formats enabling controlled dispensing and premium shelf presence, with refill-compatible geometries commanding price premiums over single-use alternatives.
- Bottles:Polyethylene terephthalate and polypropylene extrusions dominate haircare and body wash applications across Thai and Malaysian converting hubs. Chinese skincare brands are driving demand for pump-integrated bottle systems in tier-one cities where organized retail penetration deepens.
- Tubes:Laminate and mono-material polyethylene structures serve toothpaste, hair colorant, and facial cleanser segments. Indian kirana networks absorb high volumes of small-format tubes as unit economics below twenty rupees penetrate rural Maharashtra and Uttar Pradesh.
- Jars:Borosilicate and soda-lime glass containers anchor premium skincare positioning in Seoul and Shanghai beauty clusters.
- Sachets:Flexible aluminum and plastic laminate pouches register the steepest expansion trajectory through Indonesia's traditional grocery channels.
The dominant share belongs to bottles, while sachets are gaining share fastest.
Material:
Cost tier stratification separates commodity resin converters from specialty substrate suppliers serving fragrance and luxury skincare houses.
- Plastic:Polyethylene terephthalate, polypropylene, and polyethylene retain volume leadership across haircare and body care lines. China's GB standards for cosmetic packaging recyclability are compressing specifications and forcing rapid substrate substitution in domestic extrusion lines.
- Glass:Borosilicate and soda-lime compositions capture premium positioning in skincare and fragrance segments where tactile weight commands shelf price realization despite freight density penalties.
- Metal:Aluminum aerosol cans and collapsible tubes serve deodorant and hair spray applications with barrier properties against oxidation.
- Paper:Molded pulp and folding carton secondary packaging expands in Korean and Japanese markets responding to EU Green Deal extraterritorial compliance requirements.
Plastic retains volume leadership, though glass is climbing fastest in premium tier repositioning.
End User:
Application-specific barrier requirements and dispensing precision demands create technology segmentation between mass-market converters and precision molding specialists.
- Skincare:Airless pump bottles and UV-protective glass jars protect vitamin C and retinol formulations from oxidation. Korean beauty houses are adopting sub-15ml micro-airless formats for travel retail and subscription sampling channels.
- Haircare:Large-format bottles and flexible tubes dominate shampoo and conditioner segments across Southeast Asian mass markets. Indian rural penetration drives sachet format expansion through kirana distribution networks.
- Makeup:Acrylic and glass jars combined with precision dispensing closures serve color cosmetics houses in Shanghai and Guangzhou facing tightened GB/T heavy metal enforcement.
- Fragrance:Premium glass bottles with precision spray pumps command highest unit margins in duty-free and department store channels.
Haircare absorbs the largest volume, while skincare is expanding most quickly in value terms.
Distribution Channel:
Customer type and purchase occasion segment packaging format requirements between impulse-driven single-use and planned replenishment systems.
- Online:E-commerce optimized geometries with damage-resistant secondary containment serve direct-to-consumer beauty brands. Subscription box formats favor compact, lightweight structures minimizing dimensional weight charges.
- Retail:Supermarket and department store channels demand shelf-ready secondary packaging with theft-deterrent closures. Organized retail penetration in India's tier-two cities creates whitespace for localized secondary packaging production.
- Direct Sales:Consultant-driven beauty brands require portable sampling formats and presentation-optimized primary containers.
- Wholesale:Bulk dispensing and professional salon formats favor large-capacity bottles and refill systems with cost-optimized closure engineering.
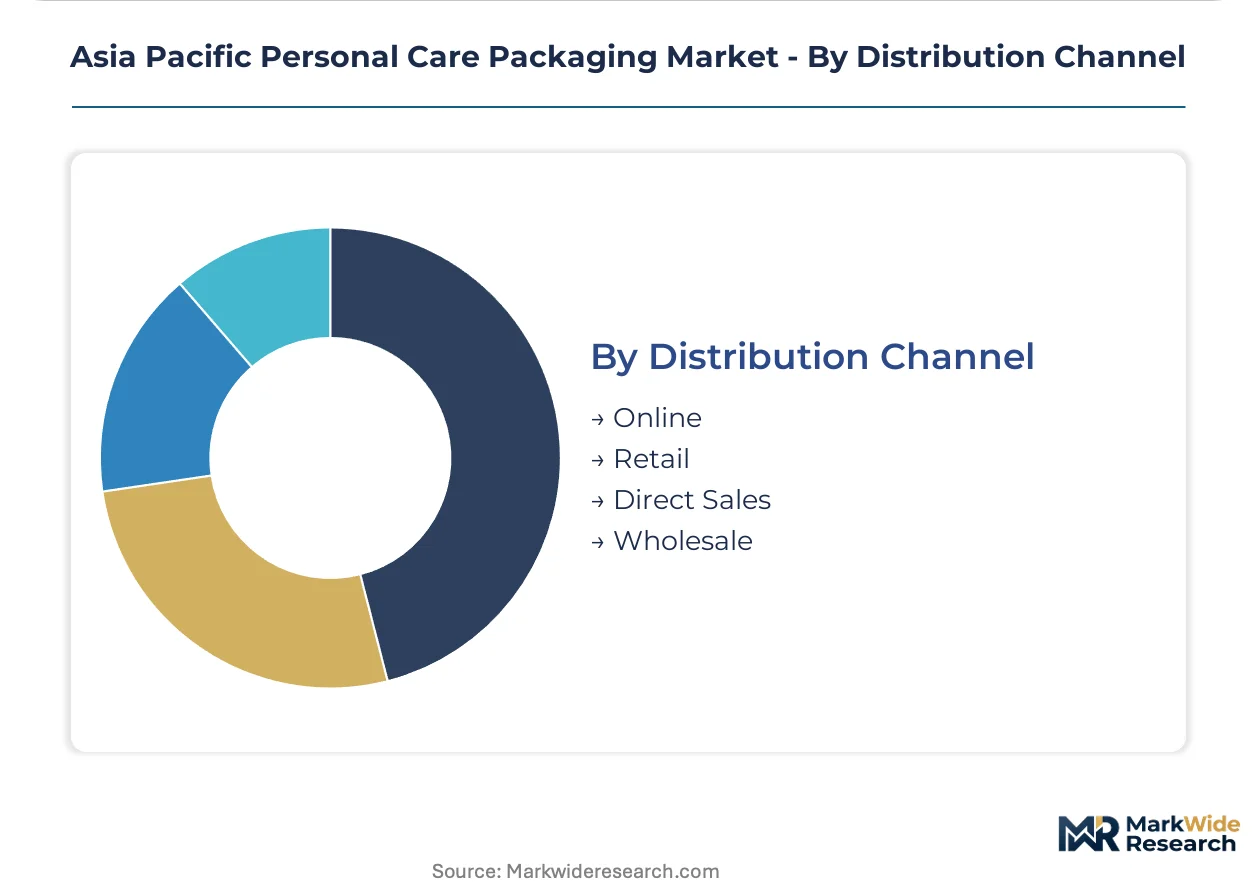
Retail maintains the largest share, while online is closing the gap fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia Pacific diverge sharply between China's precision-engineered skincare formats and India's sachet-driven rural penetration. Southeast Asian markets blend both models, with refillable systems gaining traction in urban centers while single-use formats dominate traditional trade channels.
China
Domestic skincare brands in Shanghai and Guangzhou are driving demand for mono-material polyethylene structures as SAMR enforces GB/T heavy metal limits. The country's national standards body is accelerating technical audits for decorative metalized films. Converter clusters in Jiangsu and Zhejiang provinces are retooling extrusion lines to process post-consumer recycled content.
India
Organized retail penetration for beauty products is deepening in Mumbai, Delhi, and Bangalore, while kirana networks absorb high volumes of flexible sachets below twenty rupees. BIS certification mandates material safety disclosures for imported primary packaging. Maharashtra-based converters are expanding film-to-sachet capacity to serve rural distribution channels.
Japan
Premium skincare houses in Tokyo and Osaka are adopting sub-15ml micro-airless formats for travel retail and subscription sampling. METI guidelines on packaging recyclability are shaping converter specifications for domestic and export-bound production. Chubu region molding specialists are investing in precision dispensing closure technology.
South Korea
K-beauty brands are miniaturizing airless pump systems for vitamin C and retinol formulations targeting duty-free channels. The country's national standards framework influences material selection for cosmetic packaging exports. Seoul metropolitan area converters are integrating UV-protective substrate engineering into glass and plastic jar production.
Thailand
Multinational brand owners are leveraging Thai manufacturing bases for integrated film-to-bottle platforms serving Southeast Asian markets. The country's central industrial estate zones are attracting polymer engineering talent to unwind capacity bottlenecks. Bangkok and surrounding provinces are emerging as hub-and-spoke manufacturing centers for ASEAN distribution.
Asia Pacific Personal Care Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former commanding end-to-end substrate-to-dispensing solutions and the latter dominating niche closure or premium glass segments. The structure rewards scale in polymer extrusion and precision molding while preserving margin pools for tactile substrate specialists. Three archetypes define the field: integrated multinational converters with regional hub strategies, precision dispensing technology specialists, and premium glass and acrylic fabricators serving color cosmetics houses. Competitive moves concentrate on backward integration into recycled resin streams and geographic expansion into India's tier-two cities.
Among the integrated multinational tier, Amcor plc exemplifies the film-to-bottle platform archetype with Thai manufacturing presence. HCP Packaging Co. Ltd occupies a position within the premium glass and acrylic specialist segment, serving color cosmetics clusters in Shanghai and Seoul. AptarGroup Inc. anchors the precision dispensing technology tier, with R&D intensity concentrated in molding capabilities for fragrance and serum applications. These three represent distinct competitive vectors: scale-driven substrate integration, tactile premium positioning, and dosing precision engineering.
| Leading Market Players |
|---|
| Albea SA |
| HCP Packaging Co. Ltd |
| Berry Global Group |
| Silgan Holdings Inc. |
| Bemis Company Inc. |
| Amcor plc |
| AptarGroup Inc. |
| Mondi plc |
| Crown Holdings, Inc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization disparities between Thai film-to-bottle hubs and Indian sachet converters create divergent margin floors across substrate tiers. Scale concentration in Southeast Asian extrusion clusters compresses unit economics for commodity polyethylene terephthalate, while fragmented flexible packaging in Maharashtra sustains price premiums through direct kirana channel relationships.
Pricing Analysis
Long-term offtake contracts dominate resin procurement for multinational brand owners, insulating Thai and Malaysian converters from spot polyethylene volatility. Three-tier pricing structure across premium, standard, and economy levels separates airless pump systems from basic tubes and sachets. Cost compression in standard-tier bottles intensifies as China's GB standards force substrate substitution without pass-through mechanisms. Mass-market sachet buyers exhibit highest price sensitivity, while premium skincare houses absorb glass weight premiums for tactile positioning.
Supply Chain Analysis
Malacca Strait transit underwrites raw material flows between Middle Eastern petrochemical feedstocks and Southeast Asian converting hubs. Thailand, Malaysia, and China anchor extrusion capacity for polyethylene and polypropylene structures. Converter operations draw from imported resin pellets, aluminum coil stock, and borosilicate glass cullet. Single-source vulnerability concentrates in Thai rPET collection infrastructure. Distribution runs through brand-owner consolidation centers serving organized retail channels across tier-one Indian cities and ASEAN urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refillable format disruption and China's GB standard acceleration create dual inflection points reshaping competitive viability. Incumbents and entrants face divergent pathway requirements across substrate substitution cycles.
For Market Incumbents: Consolidate backward integration into post-consumer recycled resin streams to defend margin position against PCR shortage squeezes. Lock Thai and Malaysian hub capacity through long-term offtake structures before polymer engineering talent scarcity deepens. Certification pre-investment for dual BIS and SAMR compliance accelerates product launch velocity versus fragmented competitors. For New Entrants and Emerging Players: Lead with precision dispensing closure specialization targeting Korean serum and Japanese fragrance applications where airless pump miniaturization commands premium positioning. India's tier-two cities present whitespace for secondary packaging localization as organized retail penetration deepens beyond Mumbai and Delhi. Direct brand relationships with kirana-integrated sachet converters bypass traditional distribution markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated film-to-bottle platforms with captive resin processing and regional hub footprints. Five-to-ten year viability hinges on converter consolidation around ASEAN harmonization arbitrage. Monitor SAMR enforcement intensity as signal for accelerated substrate substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Streams | Captive recycled resin supply insulates margins against Thai collection hub concentration. |
| Precision Dispensing R&D Intensity | Airless pump miniaturization captures Korean travel retail and subscription sampling premiums. |
| Dual Certification Pre-Investment | Simultaneous BIS and GB standard readiness compresses multinational launch cycles. |
| Tier-Two Indian Distribution Localization | Secondary packaging proximity to Bangalore and Hyderabad organized retail reduces logistics drag. |
| Mono-Material Structure Transition | Polyethylene substitution for metalized films satisfies China's SAMR heavy metal enforcement. |
Study Parameters
Operator-level perspectives from polymer extrusion plant managers, brand owner packaging procurement leads, regulatory affairs specialists at SAMR and BIS, and kirana channel distributors anchored the qualitative base. Secondary validation drew from customs trade data, SEC filings of listed converters, ASEAN harmonization directive texts, and retail audit databases. Bottom-up capacity modeling triangulated against top-down beauty product consumption forecasts.
Sensitivity analysis tested resin price volatility, regulatory enforcement intensity, and refillable adoption curve assumptions across the projection horizon. Segmentation dimensions included packaging format, material substrate, end-use application, and distribution channel. CAGRs derived from installed capacity expansion rates correlated with tiered city consumption penetration. Industry-specific inputs incorporated GB standard implementation timelines and kirana network expansion trajectories.
Forecasts assume regulatory continuity in China's SAMR enforcement and India's BIS certification regimes; material policy shifts would require re-modeling. PCR supply concentration and ASEAN harmonization lag present specific revision triggers. Practitioners should keep alternative scenarios live as polymer engineering talent availability and dual carbon goal acceleration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Skin Care Packaging Market