
 Lotion Tubes Market | 2026-2036
Lotion Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Lotion Tubes Market Foresight
Polyethylene terephthalate is broadening its addressable role in lotion tube construction as converters seek alternatives to conventional multi-layer plastics. Essel Propack Ltd leverages its laminate expertise to sustain high-volume contracts with multinational personal care brands. Albea S.A. anchors European supply through dedicated sustainable packaging facilities in France and Poland. Hoffmann Neopac AG differentiates via aluminum-barrier tubes that occupy the pharmaceutical and dermocosmetic premium tier.
Lotion tubes are cylindrical, collapsible containers manufactured from extruded plastic, laminated foil, or aluminum, typically ranging from 10ml to 200ml in fill volume, designed to dispense viscous personal care formulations through controlled orifice closures. Their primary commercial purpose centers on protecting product integrity from oxidation and contamination while enabling precise, hygienic dispensing in bathroom and travel environments. Plastic tubes dominate unit volume across mass-market skincare and sun protection lines, though eco-friendly materials represent the fastest-expanding margin pool as brand owners commit to recyclability pledges. Aluminum tubes retain structural importance in pharmaceutical and high-active dermocosmetic segments where barrier performance commands price premiums over standard polyethylene formats.
FDA regulations governing cosmetic packaging safety and labeling directly shape material selection and migration testing protocols for tubes distributed in the United States. REACH compliance within the European Union restricts certain plasticizers and additives, compelling reformulation of tube resins and laminate adhesives across the supplier base. China's GB standards and SAMR oversight impose additional substance restrictions and registration requirements for imported cosmetic packaging materials. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions to anticipate capital requirements for circular-design tube platforms.
Market Dynamics
Converters face mounting pressure to eliminate multi-layer barrier structures as the EU's Packaging and Packaging Waste Regulation mandates recyclability targets, forcing rapid material transitions across European supply chains.
Growth Catalysts
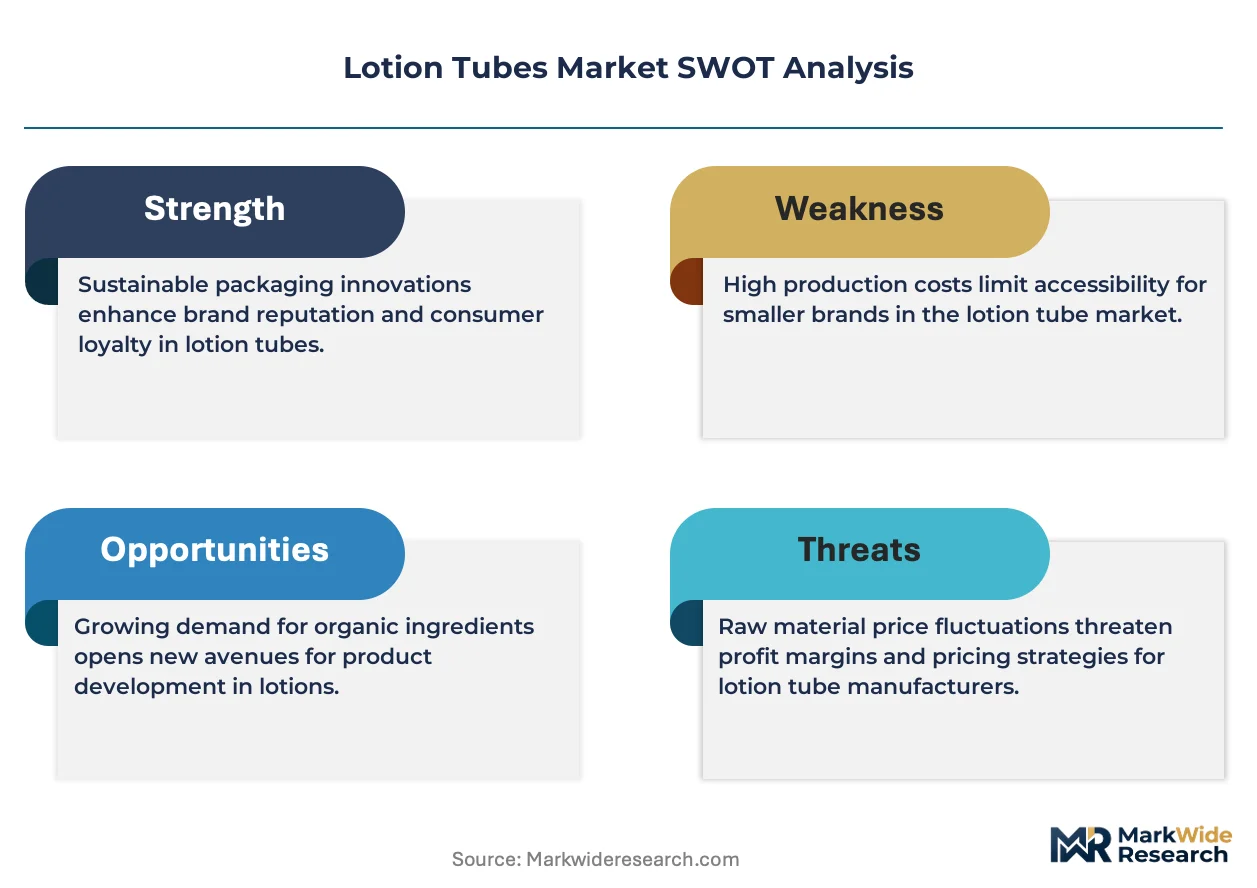
- REACH substance restrictions:European chemical regulations are phasing out legacy plasticizers, compelling tube manufacturers to qualify bio-based alternatives and capture premium positioning in dermocosmetic segments.
- Aluminum-barrier technology:High-barrier aluminum tubes are displacing conventional plastics in pharmaceutical applications where oxidation sensitivity demands superior protection.
- German premium cosmetic manufacturing:Concentrated demand from sustainable beauty brands in Germany is accelerating adoption of mono-material tube formats with post-consumer recycled content.
Market Restraints
- Resin cost volatility:Fluctuating polyethylene and polypropylene feedstock prices compress converter margins and destabilize long-term contract pricing with personal care brands.
- European supplier concentration:Laminate expertise clusters in France and Poland, creating geographic dependency risk for brands seeking qualified sustainable tube sources.
- Migration testing complexity:FDA safety protocols for cosmetic packaging require extended validation timelines that delay new material commercialization in the United States.
Strategic Opportunities
- Indian dermocosmetic expansion:CDSCO regulatory harmonization is opening pathways for barrier-grade tube imports into India's pharmaceutical skincare segment.
- Refill station distribution:Bulk dispensing retail formats are creating demand for large-format tubes and pouch-to-tube hybrid systems in European personal care retail.
- Extended producer responsibility frameworks:France's Citeo and Germany's Dual System Deutschland are incentivizing design-for-recycling investments through modulated eco-contribution fees.
Industry Challenges
- Adhesive reformulation expertise:Converters lack sufficient polymer chemists capable of engineering laminate bonds compatible with both recycling streams and aggressive cosmetic actives.
- Legacy equipment retrofitting:Extrusion lines designed for multi-layer structures require substantial capital expenditure to process mono-material alternatives at commercial throughput rates.
- Certification timeline compression:Brands demand simultaneous compliance with EU Green Deal circularity metrics and FDA migration limits, stretching quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lotion Tubes Market |
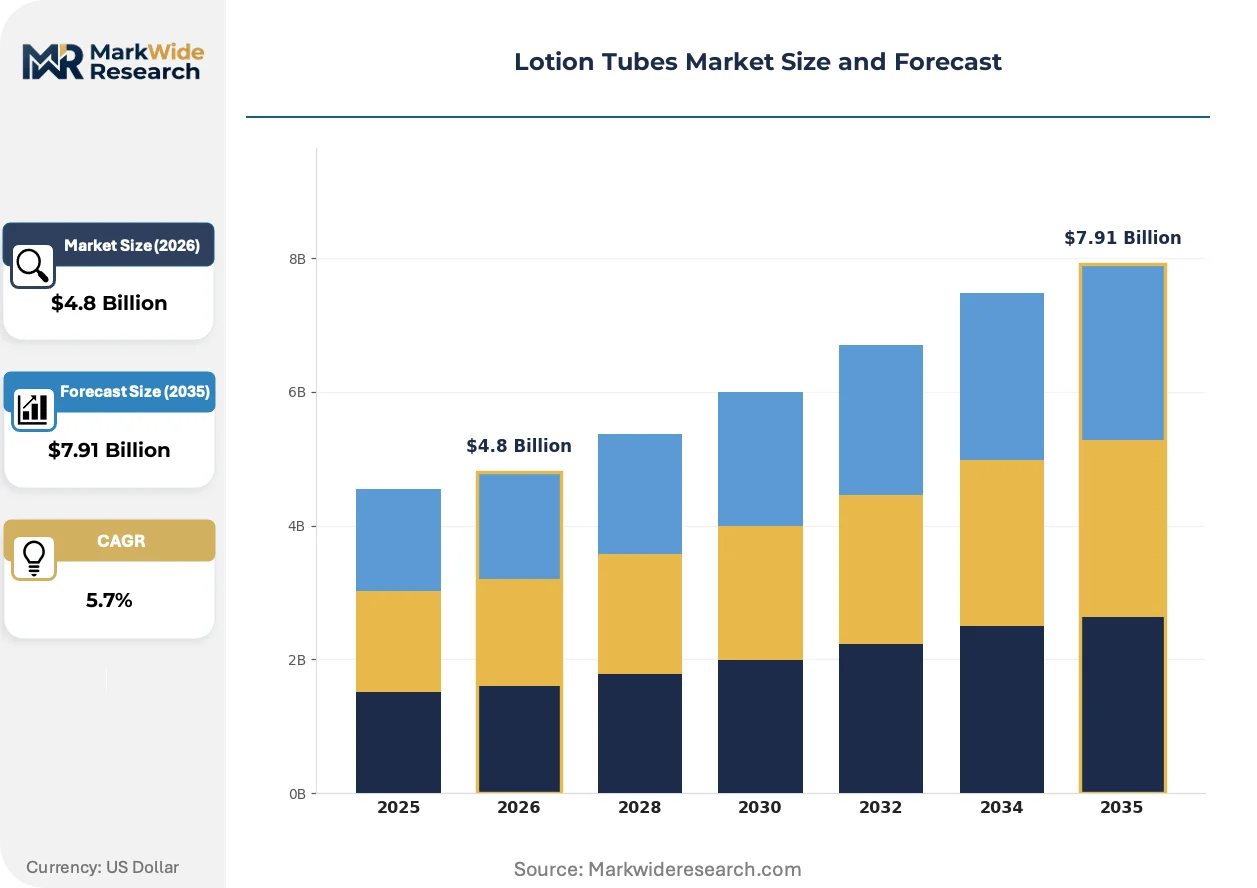
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Glass, Eco-friendly Materials Closure Type: Flip Top, Screw Cap, Pump, Disc Top Use Case: Skin Care, Sun Protection, Travel Size, Sample Packs Size: 10ml, 30ml, 50ml, 200ml |
| Companies Covered | Essel Propack Ltd, Albea S.A., Berry Global Group, Inc., CCL Industries Inc., Hoffmann Neopac AG, Montebello Packaging, Quadpack Company, Alltub SAS, ALPLA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lotion Tubes Market Shifts & Advancements
Material science breakthroughs are collapsing the performance gap between sustainable mono-material tubes and legacy multi-layer barriers, while regulatory mandates accelerate format standardization.
Polyethylene terephthalate is expanding into high-barrier lotion tube applications through advanced co-injection molding and surface metallization techniques. Premium skincare brands in Germany and France are adopting these formats for retinol and vitamin C formulations previously restricted to aluminum. This transition is expanding into pharmaceutical-adjacent dermocosmetic segments where barrier parity commands price premiums.
REACH authorization requirements are restricting phthalate plasticizers and certain epoxy-based adhesives in European tube laminates. Converters must reformulate entire material stacks to maintain compliance, with personal care multinationals accelerating supplier audits to preempt supply disruption. French packaging facilities are responding fastest, deploying bio-based sealant layers ahead of regulatory deadlines.
Beauty brands are consolidating tube specifications across product lines to simplify recycling streams and reduce packaging SKU complexity. Mass-market skincare manufacturers are eliminating decorative multi-component caps in favor of standard flip-top closures. This specification compression is most visible in German drugstore retail, where private-label brands lead format rationalization to meet retailer sustainability scorecards.
Lotion Tubes Market Segmentation
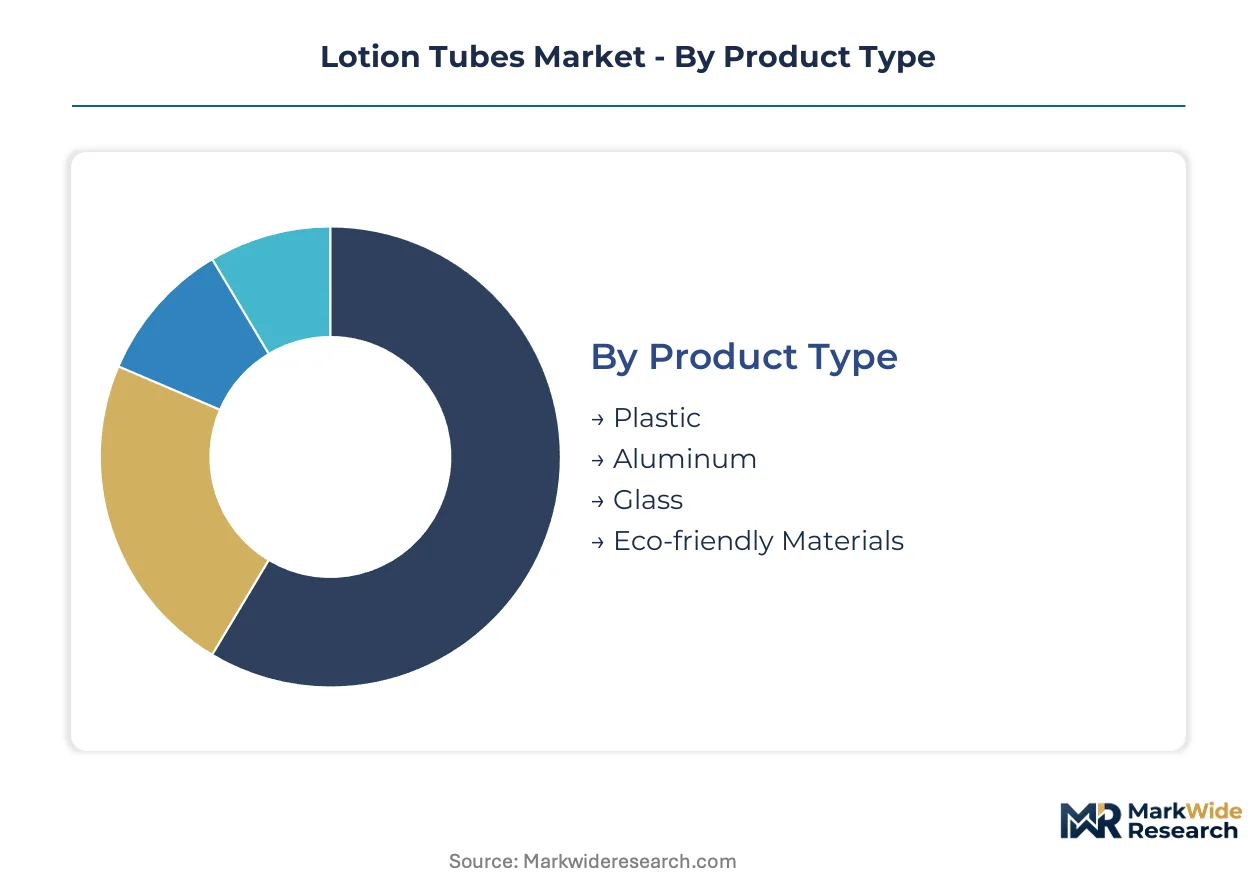
Lotion tube segmentation reveals how material science, dispensing mechanics, and consumption contexts fragment procurement priorities across personal care supply chains. Brand owners select formats based on barrier requirements, sustainability commitments, and retail channel specifications rather than unit cost alone.
Product Type:
Buyers differentiate primarily by barrier performance needs against recyclability mandates and price positioning.
- Plastic:Multi-layer polyethylene and polypropylene laminates dominate mass-market skincare and sun protection lines. German drugstore chains specify mono-material variants to meet retailer sustainability scorecards, though barrier limitations restrict use for oxidation-sensitive actives.
- Aluminum:Collapsible aluminum tubes with internal epoxy-phenolic lacquers provide impermeable barriers for pharmaceutical and dermocosmetic formulations. French and Swiss pharmaceutical brands specify these for retinoid and vitamin C products where oxidation protection commands premium pricing.
- Glass:Borosilicate and soda-lime glass tubes serve premium fragrance and facial oil segments requiring inert contact surfaces and aesthetic differentiation.
- Eco-friendly Materials:Bio-based polyethylene from sugarcane feedstock and post-consumer recycled content variants address EU Green Deal circularity requirements.
Volume sits with plastic; growth tilts toward eco-friendly materials.
Closure Type:
Dispensing precision requirements and manufacturing automation compatibility drive selection patterns across filling operations.
- Flip Top:Polypropylene snap-hinge closures dominate high-speed filling lines for body lotion and hand cream SKUs. German private-label manufacturers standardize on 24mm flip-top formats to reduce changeover downtime and simplify recycling stream sorting.
- Screw Cap:Threaded polypropylene or phenolic caps enable resealability for thick formulations and pharmaceutical ointments. Swiss dermocosmetic brands specify child-resistant screw closures for prescription-strength topical treatments.
- Pump:Airless pump systems with silicone valves dispense viscous creams without oxidation exposure.
- Disc Top:Press-to-open disc closures balance one-handed operation with leak resistance for travel retail formats.
Flip tops capture the highest unit volumes; disc tops are climbing the fastest amid travel-size SKU proliferation.
Use Case:
Formulation viscosity and retail channel placement determine structural specifications and decoration investments.
- Skin Care:Facial moisturizers and body lotions require compatibility with aqueous and emulsion bases across pH ranges. French pharmacy brands drive demand for aluminum-barrier tubes in anti-aging segments where active stability determines efficacy claims.
- Sun Protection:UV-filter formulations demand photostable packaging with minimal UV transmission. German beach and sports skincare manufacturers specify opaque plastic or aluminum tubes to prevent photodegradation of chemical filters.
- Travel Size:TSA-compliant sub-100ml formats for airline retail and hotel amenities.
- Sample Packs:Single-use or limited-use tubes for subscription boxes and counter sampling programs.
Skin care generates the most revenue per liter; travel sizes are expanding most quickly following post-pandemic mobility recovery.
Size:
Consumption occasion and distribution economics shape fill volume specifications across retail and professional channels.
- 10ml:Single-application sachet replacements and professional sampling formats. German cosmetic houses deploy 10ml aluminum tubes for physician-dispensed dermocosmetic trial programs where hygiene and shelf stability outweigh unit cost.
- 30ml:Standard travel retail and subscription box formats. French premium brands favor 30ml as the entry tier for skincare lines, enabling trial without inventory risk for specialty retailers.
- 50ml:Core retail SKU for daily-use body and hand care.
- 200ml:Family-size and professional salon formats for high-consumption categories.
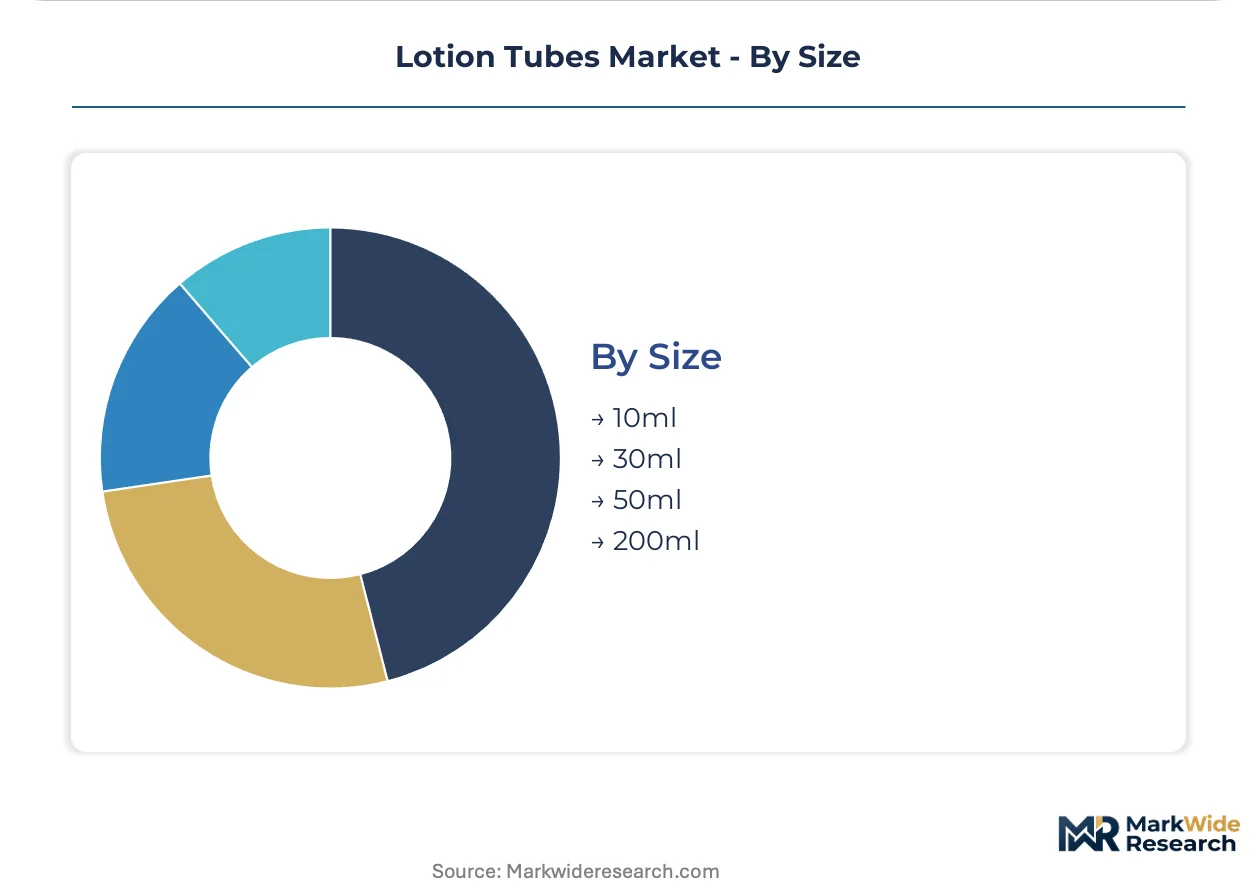
50ml holds the center of volume distribution; 30ml shows the steepest expansion trajectory in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium cosmetic manufacturers concentrate demand for sustainable tube formats, while regulatory pressure from Brussels reshapes supplier compliance costs across adjacent European markets.
Germany
Drugstore chains and pharmacy brands drive specification of mono-material tubes with post-consumer recycled content. The Packaging Act implements modulated fees through Dual System Deutschland, rewarding design-for-recycling investments. North Rhine-Westphalia hosts converter facilities supplying private-label manufacturers with standardized flip-top formats.
France
Pharmaceutical skincare brands specify aluminum-barrier tubes for oxidation-sensitive retinoid formulations. ANSM oversight of cosmetic packaging materials complements REACH substance restrictions on laminate adhesives. The Île-de-France region anchors European sustainable packaging R&D, with facilities deploying bio-based sealant layers ahead of regulatory deadlines.
United States
Mass-market skincare and sun protection lines sustain high-volume plastic tube procurement. FDA migration testing protocols for cosmetic packaging extend validation timelines for new material commercialization. New Jersey and Ohio host extrusion operations serving multinational personal care brands with multi-layer polyethylene formats.
India
Dermocosmetic expansion and pharmaceutical skincare growth create import pathways for barrier-grade tube technologies. CDSCO regulatory harmonization is streamlining registration requirements for cosmetic packaging materials. Maharashtra-based contract manufacturers are qualifying aluminum-barrier formats for physician-dispensed trial programs.
Switzerland
Premium dermocosmetic brands command price premiums for pharmaceutical-grade barrier performance. Swissmedic oversight of medical device packaging influences adjacent cosmetic tube specifications for high-active formulations. The Basel-Zürich corridor concentrates formulation expertise that dictates upstream packaging requirements.
Lotion Tubes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with laminate expertise clustering in European facilities and scale-driven extrusion dominating North American supply. The vendor base organizes around three strategic archetypes: integrated converters with captive resin operations, specialty barrier-tube fabricators serving pharmaceutical tiers, and regional contract manufacturers filling private-label specifications. Competitive moves center on M&A to secure laminate chemistry capabilities and capacity expansion to capture refill-station and direct-to-consumer format demand.
Among European-based fabricators, Albea S.A. and Hoffmann Neopac AG occupy positions within the specialty barrier and sustainable packaging tiers, while Essel Propack Ltd anchors high-volume contract manufacturing relationships with multinational personal care brands. These three exemplify how geographic concentration of laminate expertise in France, Poland, and India shapes competitive positioning across premium and mass-market segments.
| Leading Market Players |
|---|
| Essel Propack Ltd |
| Albea S.A. |
| Berry Global Group, Inc. |
| CCL Industries Inc. |
| Hoffmann Neopac AG |
| Montebello Packaging |
| Quadpack Company |
| Alltub SAS |
| ALPLA Group |
| Others |
Supply & Pricing Matrix
Polyethylene resin indices cascade through lotion tube supply chains into three distinct pricing tiers, with feedstock volatility compressing converter margins and forcing contract renegotiations across European and North American buyer networks.
Pricing Analysis
Volume sits with mass-market plastic tubes while margins concentrate in aluminum-barrier and mono-material sustainable formats. Price differentiation separates pharmaceutical-grade barrier tubes from standard polyethylene lines, with certification tier and customization level commanding premiums. Cost compression in multi-layer plastic segments is intensifying because REACH-driven adhesive reformulation raises input costs. Mass-market skincare brands exhibit highest price sensitivity; dermocosmetic and pharmaceutical buyers accept premium positioning for oxidation protection.
Supply Chain Analysis
Single-source vulnerability sits with laminate expertise clustering in France and Poland, where converter capacity constraints create geographic dependency for sustainable tube procurement. Raw material flows draw from Saudi Arabian and U.S. Gulf Coast polyethylene feedstock, German and Swiss aluminum rolling mills, and Brazilian sugarcane-derived bio-polyethylene. Regulatory restriction risk looms as EU Packaging and Packaging Waste Regulation deadlines approach. Distribution runs through personal care brand direct procurement teams, contract manufacturing intermediaries, and European private-label consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lotion tubes market sits in a material-transition phase as mono-material polyethylene displaces multi-layer laminates under regulatory pressure.
For Market Incumbents: Lock in laminate chemistry capabilities through targeted hiring of polymer scientists and captive adhesive development labs. Secure long-term supply contracts for post-consumer recycled resin streams before capacity constraints tighten. Vertical integration into bio-based sealant production insulates against REACH authorization disruptions. For New Entrants and Emerging Players: The mid-tier price gap between aluminum-barrier pharmaceutical tubes and commodity plastic formats offers white-space entry for hybrid barrier-mono-material solutions. Target Indian dermocosmetic contract manufacturers seeking qualified tube imports under CDSCO harmonization. Lead with sustainability certification and rapid FDA migration testing turnaround as differentiation. For Investors and Strategic Acquirers: Distressed-cycle entries favor European mid-cap converters with stranded multi-layer equipment and strong customer relationships in Germany and France. Assess long-term viability through exposure to refill-station retail formats and direct-to-consumer channel growth. Watch EU modulated eco-contribution fee schedules as inflection signals for design-for-recycling investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Migration | REACH compliance and Dual System Deutschland fees reward recyclability investments across German supply chains. |
| Adhesive Chemistry Acquisition | Bio-based sealant expertise addresses laminate reformulation bottlenecks before regulatory deadlines. |
| Indian Market Entry Partnership | CDSCO harmonization opens pharmaceutical skincare pathways for barrier-grade tube technologies. |
| Post-Consumer Recycled Resin Integration | Citeo and Green Deal circularity metrics incentivize recycled content specifications in French retail. |
| Refill Station Format Development | Bulk dispensing retail creates demand for large-format tubes and pouch-to-tube hybrid systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tube converter plant managers, personal care brand procurement leads, pharmaceutical packaging engineers, and European retail category buyers combined with secondary validation from ECHA substance restriction databases, FDA cosmetic packaging guidance documents, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up capacity modeling and top-down demand estimation were triangulated against trade flow data.
Data-stream reconciliation across production volume surveys, brand procurement pipeline tracking, and resin price indices shaped the analytical framework. Segmentation dimensions modeled include material type, barrier performance tier, closure mechanism, fill volume, and end-use application across the analysis window. CAGRs were derived from slope-log regression on normalized volume trajectories, with inputs from converter capacity expansion announcements and personal care brand sustainability pledge timelines.
Inputs from ECHA pre-registration databases and FDA cosmetic ingredient statement filings were available through the study window; gaps in real-time converter inventory levels and brand contract renewal schedules introduce uncertainty bands. Forecasts reflect assumptions about regulatory implementation timing and resin price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market