
 Cosmetic Tubes Market | 2026-2036
Cosmetic Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Tubes Market Analysis
Prestige skincare is recalibrating tube specifications toward airless pump tubes and mono-material polyethylene formats. Albéa leverages its European manufacturing footprint to anchor sustainable tube production for luxury cosmetic houses. Hoffmann Neopac specializes in small-diameter aluminum and plastic laminate tubes for pharmaceutical-cosmetic crossover brands. Essel Propack (EPL) dominates laminated tube supply across emerging Asian cosmetic markets through high-speed extrusion capacity.
Cosmetic tubes are cylindrical, collapsible containers extruded or molded from plastic laminates, aluminum, or biodegradable polymers, typically fitted with screw caps, flip tops, or pump closures to dispense viscous products in controlled volumes; they serve as primary packaging for creams, gels, and lotions across personal care categories. Plastic tubes sustain the largest volume share due to cost efficiency and decoration versatility, though biodegradable segments are capturing margin pools as brand sustainability commitments harden. Skincare applications lead value contribution given higher tube complexity and premium closure adoption, while oral care remains a mature, high-volume, lower-margin category.
The EU Green Deal and REACH framework restrict multi-layer barrier structures and mandate recyclability disclosures, compelling tube converters to redesign material stacks. FDA cosmetic labeling requirements in the United States govern ingredient disclosure and tamper-evident closure standards for imported tube packaging. China's SAMR enforces GB standards for cosmetic packaging safety and migration limits that foreign tube suppliers must certify against for market access. Stakeholders should monitor regulatory divergence between European recyclability mandates and American performance-based safety standards when allocating R&D and regional production capacity.
Market Dynamics
The EU Green Deal and REACH regulations are forcing tube converters to abandon multi-layer barrier structures in favor of mono-material polyethylene formats that satisfy recyclability mandates without sacrificing product protection.
Growth Catalysts
- REACH Recyclability Mandates:European cosmetic brands are redesigning packaging specifications to comply with ECHA disclosure requirements, creating immediate retrofit demand for compliant tube structures.
- Airless Pump Technology:Prestige skincare houses are specifying high-barrier pump tubes for serum formulations, extending shelf stability and commanding premium placement in retail channels.
- Germany Manufacturing Clusters:Concentrated cosmetic production around Hamburg and Frankfurt is generating localized procurement pull for regional tube converters with rapid turnaround capabilities.
Market Restraints
- Aluminum Price Volatility:Laminated tube producers face margin compression when London Metal Exchange aluminum prices spike, particularly affecting pharmaceutical-cosmetic crossover applications.
- Barrier Performance Trade-offs:Mono-material polyethylene tubes struggle to match the oxygen and moisture resistance of legacy aluminum-plastic laminates for oxidation-sensitive actives.
- Recycling Infrastructure Gaps:Collection and sorting systems in Southern and Eastern Europe lag behind Northern European capabilities, undermining the practical recyclability of compliant packaging.
Strategic Opportunities
- Biodegradable Polymer Scale-Up:PLA and PHA tube formats present white-space positioning for brands targeting zero-waste retail channels and refill-loop subscription models.
- Pharmaceutical-Cosmetic Convergence:Dermocosmetic brands require pharmaceutical-grade tube cleanliness standards with cosmetic decoration versatility, a specification gap few converters fill.
- Digital Printing Personalization:Short-run variable decoration enables mass-customization campaigns and limited-edition releases without plate-changeover downtime.
Industry Challenges
- Mono-Material Engineering Talent:Tube converters struggle to recruit polymer scientists capable of reformulating barrier layers without incompatible adhesive interlayers.
- Extrusion Line Retrofit Costs:Transitioning from multi-layer to single-layer extrusion requires substantial capital redeployment for coextrusion die replacement and cooling system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Tubes Market |
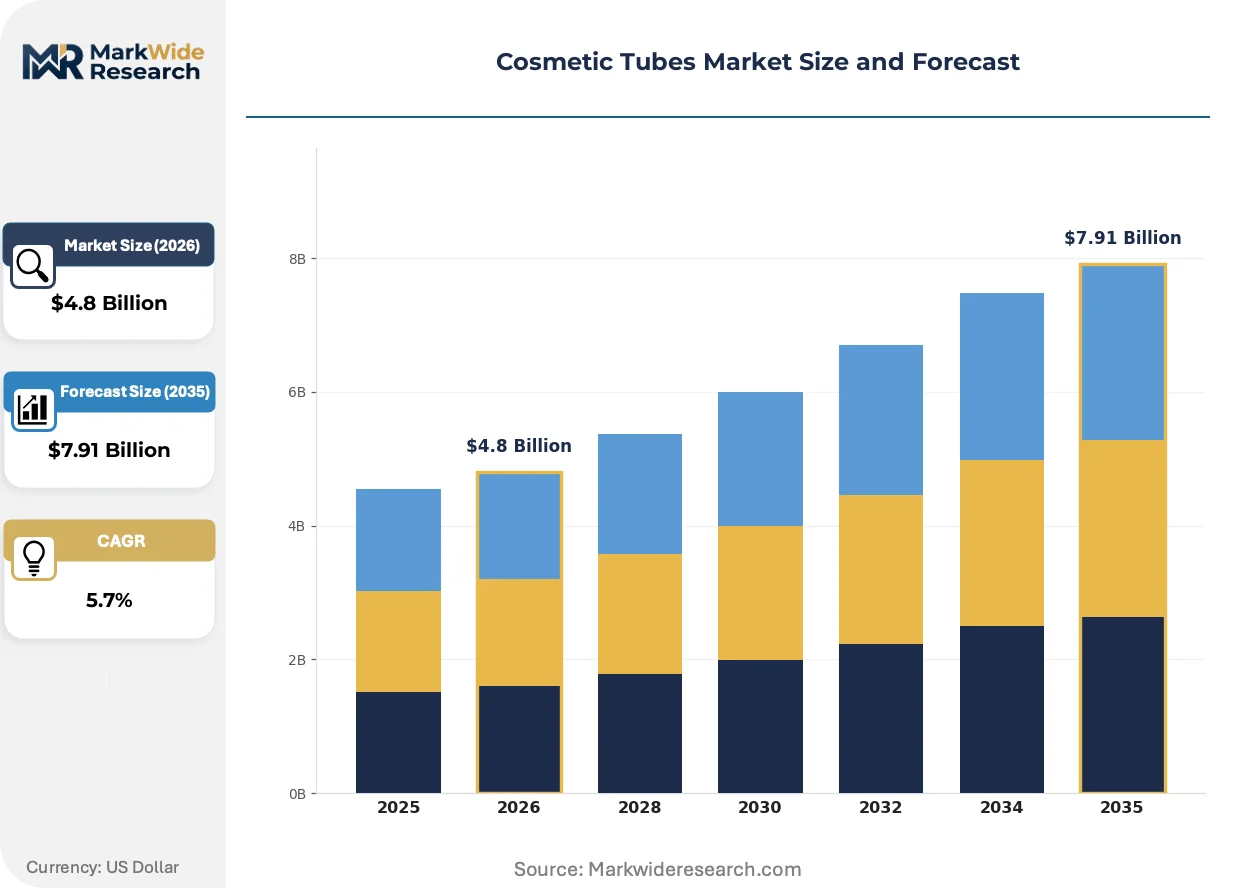
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Aluminum, Glass, Biodegradable Closure Type: Flip Top, Screw Cap, Spout, Pump Capacity: 10ml, 30ml, 50ml, 100ml Application: Skincare, Haircare, Makeup, Oral Care |
| Companies Covered | Berry Global, UDN Packaging Corporation, Albéa, AptarGroup Inc., Hoffmann Neopac, Lisson Packaging, HCP Packaging, Silgan Holdings, Essel Propack (EPL), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Tubes Market Emerging Trajectories
Tube packaging is undergoing material and functional transformation as sustainability mandates collide with performance requirements and brand differentiation pressures.
Airless pump tube systems are electrifying premium skincare packaging by eliminating air contact with sensitive formulations. Luxury cosmetic houses in France and Switzerland are specifying these structures for vitamin C and retinol serums. The technology is compressing conventional screw-cap tube specifications into commodity positioning while elevating pump-equipped formats to prestige tier pricing.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling tube converters to eliminate fluoropolymer barrier coatings from cosmetic packaging. German and French manufacturers are accelerating validation of silicone oxide and aluminum oxide vapor-deposited alternatives. Skincare applications with high active concentrations face the steepest compliance timeline pressure.
Direct-to-consumer subscription models are fragmenting order patterns from bulk seasonal procurement to continuous small-batch replenishment. Tube converters serving indie beauty brands are reconfiguring production scheduling around weekly rather than quarterly demand signals. This pattern is most pronounced in North American digitally native vertical brands bypassing traditional retail distribution.
Cosmetic Tubes Market Segmentation
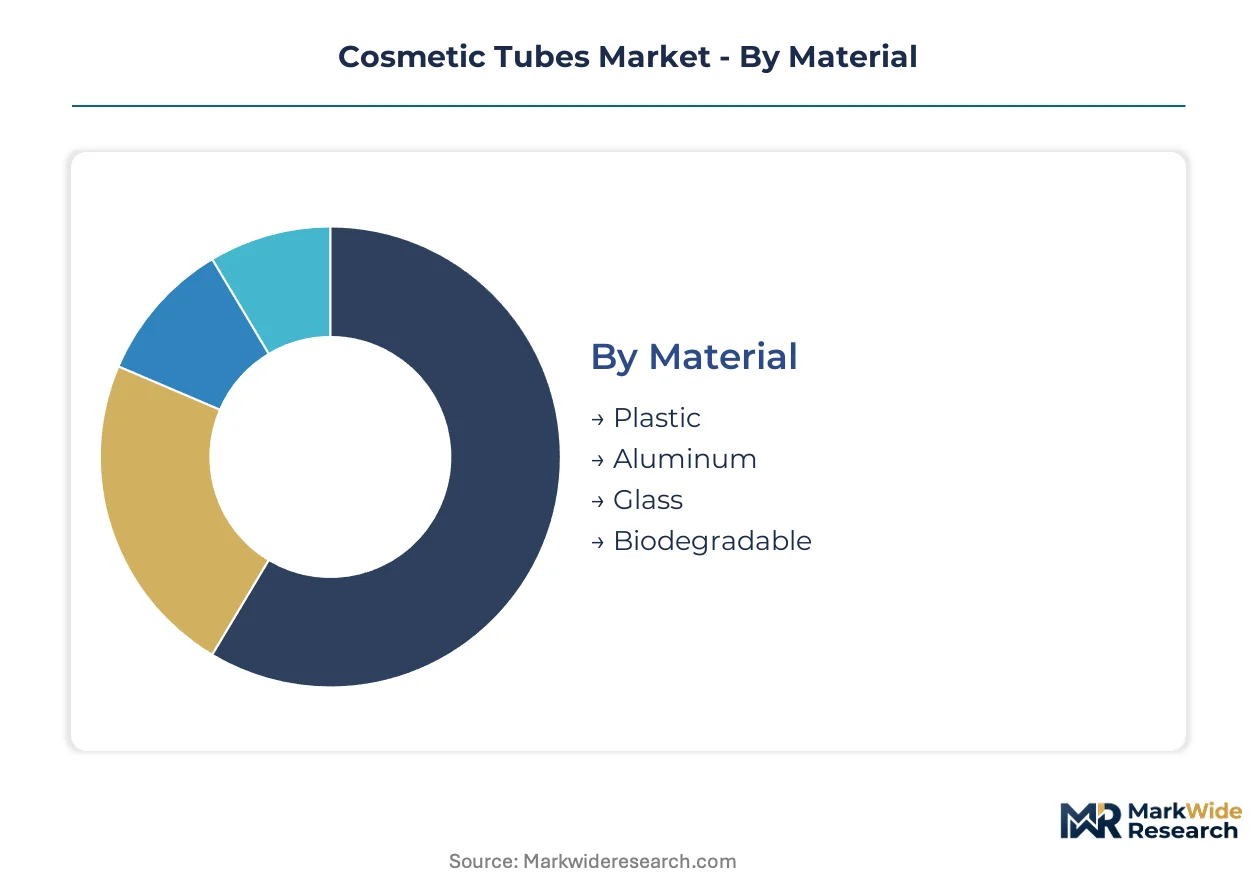
Tube converters calibrate material stacks, closure mechanisms, and capacity configurations against distinct performance thresholds and sustainability mandates. Each segmentation axis reflects divergent procurement priorities across prestige skincare, mass-market haircare, and pharmaceutical-cosmetic crossover applications.
Material:
Upgrade cycles in European tube manufacturing are accelerating as REACH recyclability deadlines force converters to retire multi-layer laminate lines in favor of mono-material extrusion systems.
- Plastic:Polyethylene and polypropylene tubes dominate through coextrusion versatility and decoration compatibility. German cosmetic manufacturers specify mono-material PE formats to satisfy ECHA disclosure requirements while preserving high-definition offset printing surfaces.
- Biodegradable:PLA and PHA polymers target zero-waste retail channels and refill-loop subscription models. French dermocosmetic brands pilot these formats for limited-edition serum releases, though industrial composting infrastructure gaps constrain volume scaling in Southern Europe.
- Aluminum:Collapsible metal tubes serve pharmaceutical-cosmetic crossover applications requiring absolute oxygen barrier performance. London Metal Exchange price volatility compresses margins for converters serving Swiss and Italian skincare houses with aluminum-laminate specifications.
- Glass:Borosilicate and soda-lime tubes occupy ultra-premium fragrance and ampoule segments. Italian luxury cosmetic houses specify these for single-dose active concentrates where material prestige outweighs fragility and weight penalties.
Volume placements concentrate in Plastic; the faster expansion belongs to Biodegradable.
Closure Type:
Closure specification directly determines shelf-stability performance and consumer convenience positioning across retail and direct-to-consumer channels.
- Pump:Airless pump systems eliminate air contact with oxidation-sensitive actives like vitamin C and retinol. Swiss prestige skincare brands specify these for serum formulations, commanding premium placement in pharmacy and department store channels.
- Flip Top:Hinged polypropylene closures enable single-handed dispensing for haircare and body care applications. German mass-market brands favor these for shower gel and shampoo tubes where in-use convenience drives repeat purchase.
- Screw Cap:Threaded closures remain standard for toothpaste and pharmaceutical-cosmetic tubes. Italian oral care manufacturers specify tamper-evident screw cap variants to satisfy national pharmacy retail requirements.
- Spout:Precision-dispensing nozzles target hair color and treatment applications requiring controlled flow rates. French professional salon brands specify these for developer and mask products.
Flip Top configurations sustain the highest shipment volumes; Pump closures are climbing the fastest as prestige skincare specifications harden.
Capacity:
Tube sizing reflects travel retail regulations, subscription model logistics, and formulation concentration economics.
- 100ml:Standard capacity for shampoo, conditioner, and body lotion applications. German drugstore chains specify this format for family-size haircare tubes, optimizing shelf productivity against smaller alternatives.
- 30ml:Serum and treatment concentrate standard matching TSA liquid restrictions for travel retail. French airport duty-free operators concentrate procurement on this capacity for skincare gift sets.
- 50ml:Mid-size format for daily-use moisturizers and SPF formulations. Italian cosmetic manufacturers favor this capacity for pharmacy-channel face care lines balancing portability with value perception.
- 10ml:Single-dose and sample formats for subscription box inclusion and clinical trial distribution. Swiss dermocosmetic brands specify these for physician sampling programs.
100ml placements dominate mass-market shipments; 30ml formats are gaining share fastest through travel retail recovery and premium miniaturization trends.
Application:
End-use category dictates barrier performance requirements, decoration investment levels, and regulatory compliance intensity.
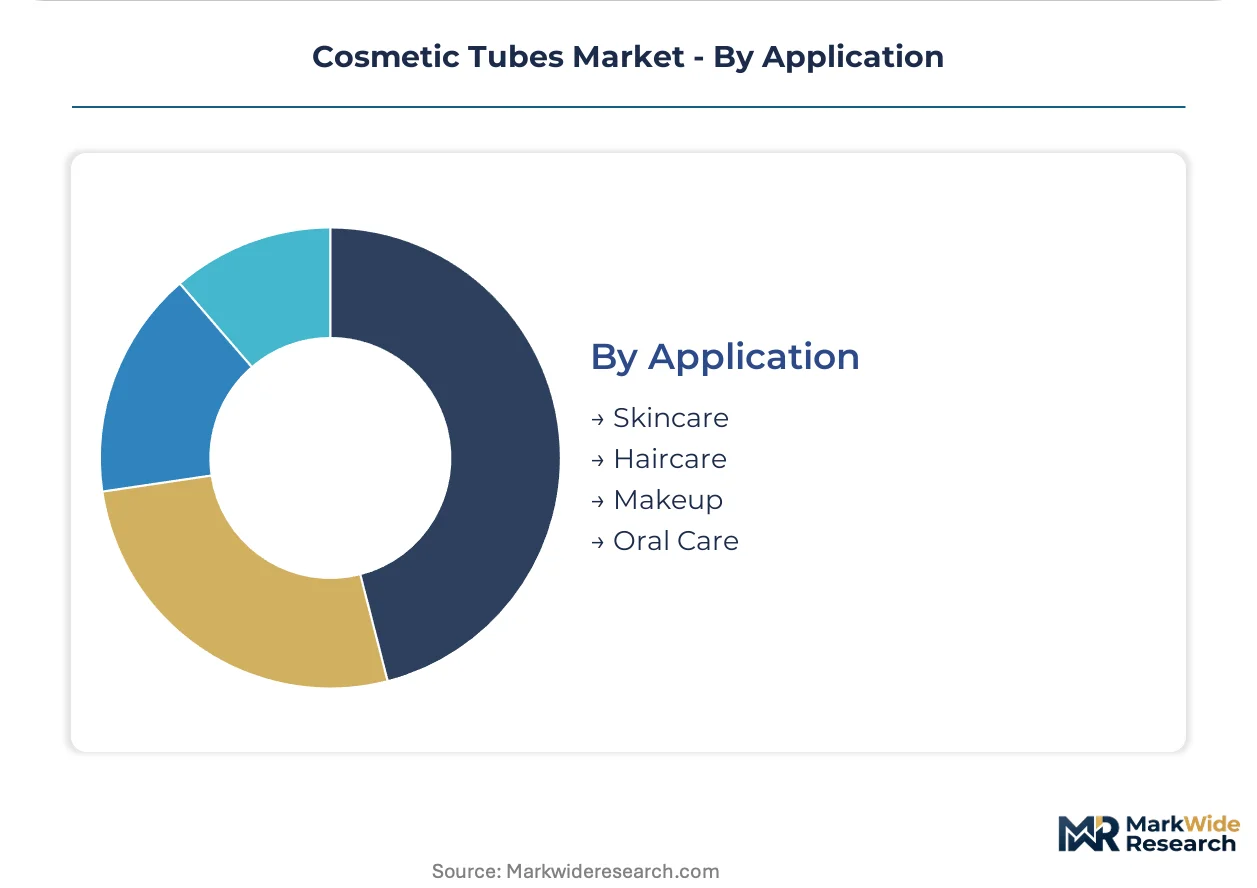
- Skincare:Face creams, serums, and SPF formulations demand the highest tube complexity. French and Swiss prestige houses specify multi-layer or airless pump structures for active-rich formulations, driving margin concentration in this segment.
- Oral Care:Toothpaste tubes represent mature, high-volume, lower-margin procurement. German and Italian manufacturers dominate this category through established laminate tube supply relationships with multinational consumer goods groups.
- Haircare:Shampoo, conditioner, and treatment tubes prioritize cost efficiency and decoration versatility. British and French salon brands specify large-format flip-top tubes for professional back-bar applications.
- Makeup:Foundation, primer, and concealer tubes require precise viscosity compatibility and premium decoration. Italian color cosmetic specialists specify these for fashion-brand licensed collections.
Oral Care sustains the highest unit volumes; Skincare generates the steepest expansion trajectory through premiumization and active formulation proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates tube converter capacity for European cosmetic brands, while the United States and China absorb the highest absolute consumption volumes through domestic manufacturing and import dependence respectively.
Germany
REACH Annex XVII deadlines and ECHA disclosure mandates are retrofitting procurement specifications for Hamburg and Frankfurt cosmetic manufacturers. The EU Green Deal accelerates mono-material polyethylene validation programs at regional converter facilities. North Rhine-Westphalia hosts the densest cluster of tube extrusion lines serving dermocosmetic brands.
United States
FDA cosmetic labeling requirements and tamper-evident closure standards govern tube imports for prestige skincare houses in New York and Los Angeles. The IRA's domestic manufacturing incentives indirectly support packaging supplier co-location near formulation plants. New Jersey and California concentrate procurement offices for multinational beauty groups.
China
SAMR GB standards for cosmetic packaging safety and migration limits filter foreign tube supplier access to Shanghai and Guangzhou brand headquarters. Dual carbon goals compress timelines for biodegradable polymer adoption in domestic tube production. The Yangtze River Delta anchors laminated tube capacity for Asian export markets.
France
ANSM oversight of cosmetic product safety intersects with CNIL data requirements for connected packaging pilots in Paris luxury houses. The country's pharmaceutical-cosmetic convergence demands pharmaceutical-grade tube cleanliness standards. Île-de-France clusters formulation R&D facilities specifying airless pump tube structures.
Switzerland
Swissmedic pharmaceutical regulations extend to dermocosmetic tube specifications for Geneva and Basel skincare laboratories. The country's precision manufacturing heritage elevates barrier performance expectations for active-rich serum packaging. Zurich-area converters specialize in small-batch premium tube production.
Cosmetic Tubes Market Vendor Landscape
Top-tier vendors anchor high-volume laminated tube supply, while mid-scale specialists occupy premium niches requiring customization velocity. The vendor base stratifies across three tiers: multinational converters with continental extrusion footprints, regional specialists in mono-material engineering, and boutique decorators serving limited-edition campaigns. Two dominant competitive moves are reshaping positioning: backward integration into polymer compounding for recyclability compliance, and strategic partnerships with airless pump mechanism suppliers.
Among European-based packaging groups, Albéa and Hoffmann Neopac exemplify divergent specialization archetypes. Albéa occupies a position aligned with sustainable tube production scale for luxury cosmetic houses. Hoffmann Neopac sits within the pharmaceutical-cosmetic crossover tier, representing precision small-diameter fabrication capabilities.
| Leading Market Players |
|---|
| Berry Global |
| UDN Packaging Corporation |
| Albéa |
| AptarGroup Inc. |
| Hoffmann Neopac |
| Lisson Packaging |
| HCP Packaging |
| Silgan Holdings |
| Essel Propack (EPL) |
| Others |
Supply Flow & Price Mechanics
Prestige skincare brand procurement offices in Paris and New York anchor contract-based long-term offtake pricing for airless pump tubes, while mass-market oral care buyers transact on commodity spot terms for laminated formats. This buyer-tier concentration creates divergent margin profiles across converter tiers.
Pricing Analysis
Margin tightening in mono-material polyethylene formats reflects extrusion line retrofit capital requirements and polymer scientist recruitment costs. Three-tier pricing structure across premium, standard, and economy levels separates airless pump specifications from flip-top laminate tubes from commodity screw-cap formats. Cost compression in aluminum-laminate segments intensifies because London Metal Exchange price volatility transfers directly to converter cost bases. Mass-market oral care manufacturers exhibit highest price sensitivity; Swiss dermocosmetic laboratories show least sensitivity given pharmaceutical-grade cleanliness requirements.
Supply Chain Analysis
Polyethylene resin supply rests on petrochemical complexes in Germany, Belgium, and the Netherlands serving European tube extruders. Aluminum coil feedstock draws from rolling mills in Germany and Switzerland; pump mechanism components hinge on precision manufacturers in Germany and France. Single-source vulnerability concentrates in fluoropolymer barrier coating alternatives as REACH Annex XVII deadlines eliminate legacy suppliers. Distribution runs through converter direct sales to cosmetic brand procurement offices, with regional logistics hubs in North Rhine-Westphalia and Île-de-France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tube converter consolidation accelerates as REACH recyclability mandates force smaller multi-layer laminate specialists into distressed exits. Regulatory compliance capital requirements separate scalable mono-material producers from stranded asset operators.
For Market Incumbents: Hedge aluminum price exposure through long-term metal supply agreements indexed to London Metal Exchange futures. Secure backward integration into polymer compounding for recyclability-compliant resin formulations. Defend against emerging mono-material engineering specialists by acquiring talent clusters in North Rhine-Westphalia. For New Entrants and Emerging Players: Indie beauty brand procurement offices represent underserved buyer archetypes seeking short-run digital printing personalization without plate-changeover constraints. Pharmaceutical-cosmetic crossover specifications offer penetrable white-space given few converters combine pharmaceutical-grade cleanliness with cosmetic decoration versatility. Pursue direct-to-consumer subscription model partnerships enabling weekly replenishment scheduling. For Investors and Strategic Acquirers: Distressed-cycle entries favor mono-material engineering specialists with validated ECHA disclosure compliance in Germany. Long-term viability centers on converters with installed airless pump tube capacity serving prestige skincare houses. Watch aluminum-laminate margin compression as inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Retrofit | REACH Annex XVII compliance secures access to ECHA-mandated procurement specifications. |
| Airless Pump Mechanism Partnership | Swiss prestige skincare brands specify these structures for oxidation-sensitive serum formulations. |
| Digital Printing Personalization Capability | North American digitally native vertical brands demand short-run variable decoration campaigns. |
| Biodegradable Polymer Scale-Up | PLA and PHA formats target zero-waste retail channels and refill-loop subscription models. |
| Pharmaceutical-Grade Cleanliness Certification | French ANSM oversight extends to dermocosmetic tube specifications requiring validated standards. |
Methodological Framework
Independent corroboration across tube converter operations managers, cosmetic brand procurement directors, and polymer R&D specialists underwrites the qualitative findings. Secondary validation draws from ECHA disclosure databases, EU Green Deal implementation trackers, and customs trade data for polyethylene and aluminum coil movements. Bottom-up capacity assessments at German and French extrusion facilities triangulate against top-down demand estimates from skincare and oral care brand production schedules.
Comparable-period anchoring connects historical multi-layer laminate shipment patterns to projected mono-material polyethylene adoption curves across the analysis window. Segmentation dimensions span material stack, closure mechanism, capacity configuration, and application category. CAGRs derive from regression analysis against cosmetic manufacturing output indices and sustainability mandate implementation timelines. Industry-specific inputs include aluminum price volatility indices and REACH Annex XVII compliance deadline schedules.
Revisions become necessary when ECHA accelerates disclosure timelines or aluminum price volatility exceeds historical bands. Forecasts reflect assumptions around recycling infrastructure deployment rates in Southern and Eastern Europe. A small set of named triggers warrants ongoing watch: fluoropolymer barrier coating substitution validation failures, extrusion line retrofit capital cost inflation, and German cosmetic manufacturing cluster relocation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market