
 Cosmetic Pump Bottle Market | 2026-2036
Cosmetic Pump Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Pump Bottle Market Insights
Aftermarket refill and replacement pump revenue is fragmenting across specialty component suppliers and original equipment converters. AptarGroup, Inc. leverages its airless dispensing patents to sustain premium positioning in skincare applications. Albéa Group anchors European supply through integrated aluminum and plastic pump production in France and Poland. Silgan Holdings Inc. competes via high-volume manufacturing scale across North American personal care contracts.
A cosmetic pump bottle is a mechanically actuated dispensing closure that uses a piston or pre-compression chamber to meter viscous or semi-viscous formulations through an exit orifice, typically manufactured via injection molding of polypropylene or polyethylene components with silicone or thermoplastic elastomer sealing elements. Its primary commercial purpose is to protect oxygen-sensitive or preservative-free formulations from contamination while enabling controlled, repeatable dosing for consumer use. Lotion pumps occupy the largest volume share due to universal compatibility with mainstream body care and hair care viscosities, whereas treatment pumps command higher unit margins through precision dosing mechanisms for serum and eye-care applications. Biodegradable material development represents the fastest-growing structural segment as brand sustainability commitments force converters away from virgin petroleum-based resins.
The FDA regulates cosmetic packaging under the Federal Food, Drug, and Cosmetic Act for material safety and labeling accuracy, while the EPA governs volatile organic compound emissions from aerosol and spray pump formulations. REACH compliance in Europe restricts phthalate and heavy-metal content in pump components, compelling Asian exporters to reformulate colorants and stabilizers. Stakeholders must monitor how extended producer responsibility frameworks in multiple jurisdictions will redistribute end-of-life collection costs between packaging converters and finished goods brands.
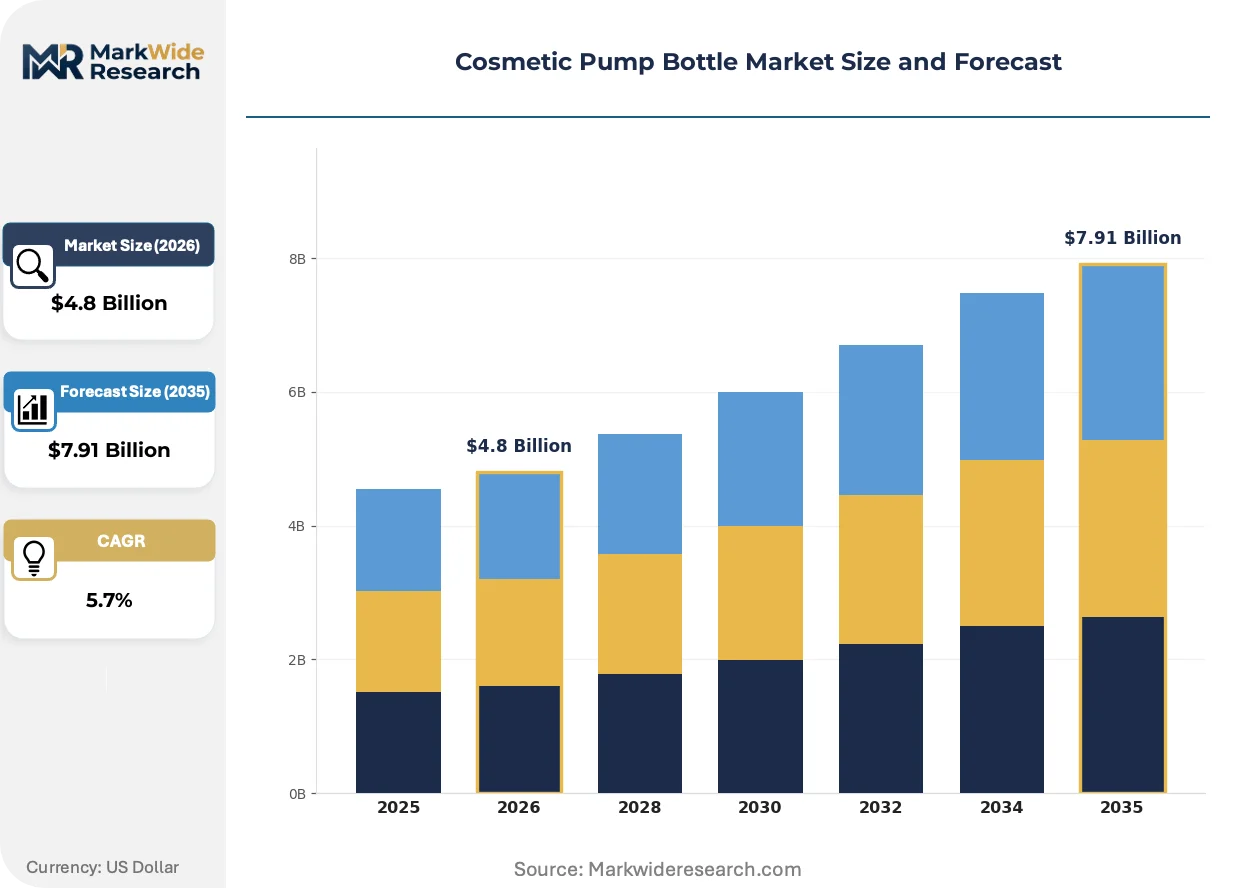
Market Dynamics
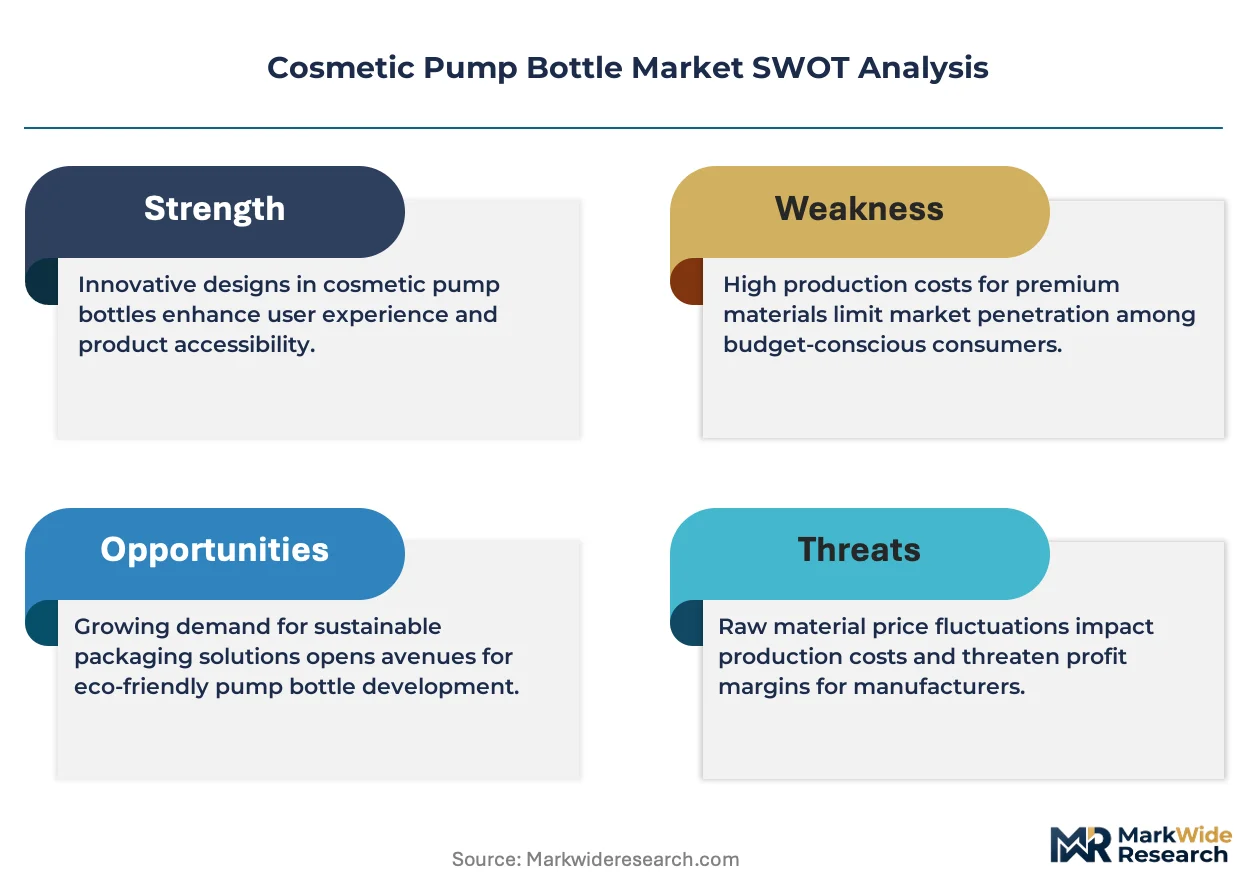
Airless pump technology is concentrating manufacturing investment in China's coastal clusters while EU material compliance rules force converters toward bio-based resin formulations.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates accelerate brand demand for recyclable mono-material pump assemblies.
- Preservative-free skincare:Oxygen-sensitive serum formulations require airless barrier protection, expanding precision treatment pump adoption.
- Biodegradable polymer R&D:PLA and PHA compound development enables converters to meet corporate sustainability commitments without performance degradation.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, compressing converter margins on fixed-price contracts.
- Asian supply concentration:Zhejiang and Guangdong provinces dominate precision mold manufacturing, creating single-source risk for North American and European brands.
- Mechanical complexity limits:Treatment pump dosing precision requires tight-tolerance piston machining that resists full automation.
Strategic Opportunities
- Indian personal care expansion:Domestic skincare brands in Maharashtra and Karnataka seek localized pump supply to reduce import duty exposure.
- Refill system integration:Modular pump heads designed for reusable glass bottles capture premium positioning in direct-to-consumer channels.
- REACH-compliant colorant substitution:Heavy-metal-free pigment development opens EU market access for Southeast Asian component suppliers previously excluded.
Industry Challenges
- Multi-material separation:Pumps combining polypropylene, stainless steel, and silicone elastomer resist automated recycling stream sorting.
- Validation timeline compression:Brand sustainability deadlines outpace ISO 17025 laboratory certification cycles for novel biodegradable formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Pump Bottle Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foaming Pumps, Spray Pumps, Lotion Pumps, Treatment Pumps Material: Plastic, Glass, Metal, Biodegradable End User: Manufacturers, Retailers, Brands, Distributors Distribution Channel: Online Sales, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Silgan Holdings Inc., AptarGroup, Inc., Albéa Group, Rieke Corporation, Berry Global Group, Inc., Frapak Packaging, Quadpack, SGB Packaging Group, APackaging Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Pump Bottle Market Trends and Innovations
Material science breakthroughs and regulatory stringency are reconfiguring competitive advantage around circular design capabilities rather than unit cost alone.
Monomaterial pump construction is migrating from niche premium applications toward mass-market personal care. European luxury skincare houses pioneered all-polypropylene assemblies to satisfy EPR reporting requirements. Major North American body care brands now specify mono-material pumps for 2025 packaging refresh cycles, compressing demand for traditional multi-component designs that complicate mechanical recycling.
REACH Annex XVII restrictions on phthalate plasticizers and heavy-metal stabilizers are forcing reformulation of pump spring and gasket compounds. Asian compounders serving EU export markets must validate replacement chemistries through ECHA-registered laboratories. Treatment pump segments face the steepest compliance costs due to precision elastomer performance requirements that resist simple material substitution.
Direct-to-consumer sampling programs are fragmenting bulk procurement into smaller, more frequent orders. Indie beauty brands bypass traditional distributor networks for factory-direct relationships with Zhejiang and Guangdong molders. California and New York-based skincare startups now specify 10,000-unit minimums rather than legacy 100,000-unit stock-keeping arrangements, forcing converters to reconfigure production scheduling and inventory management systems.
Cosmetic Pump Bottle Market Segmentation
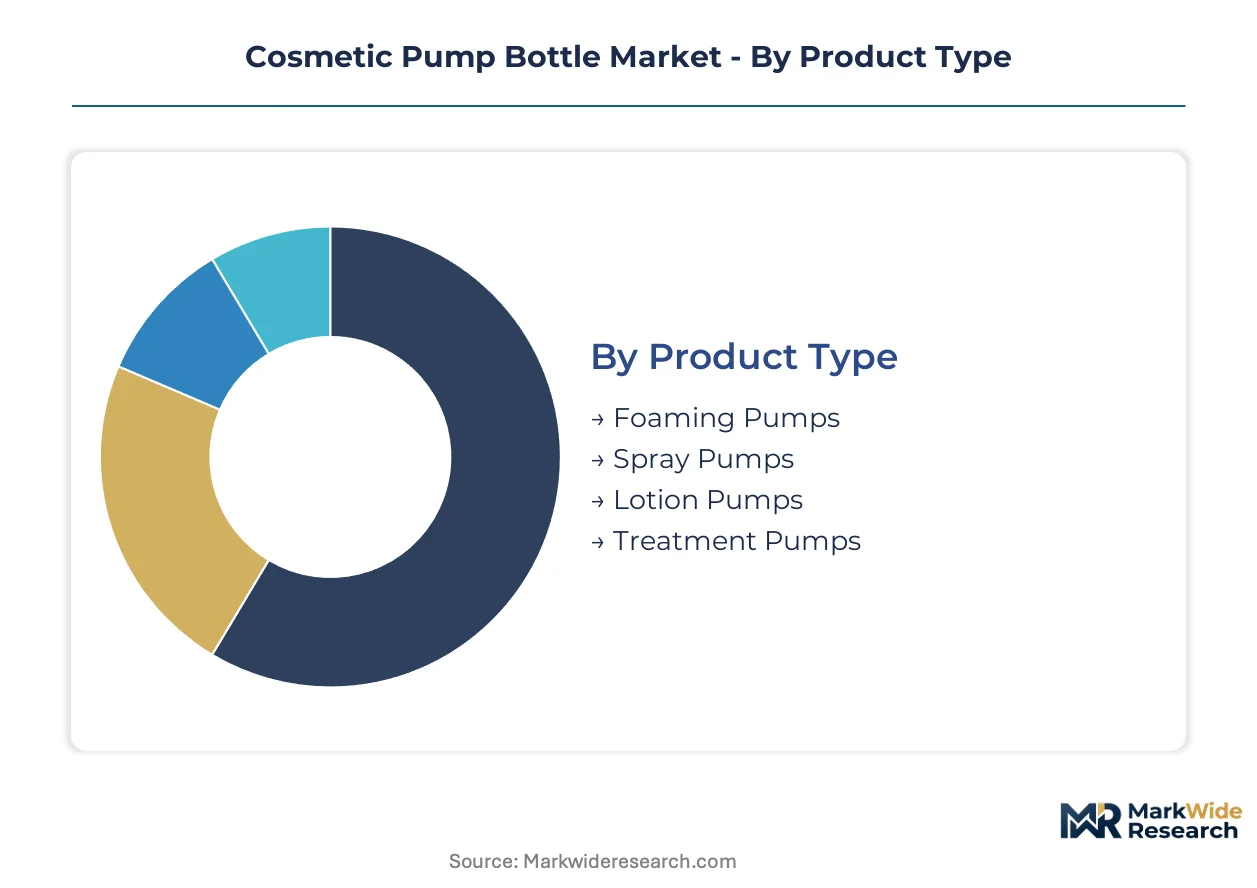
Pump specification varies sharply across cosmetic applications, with replacement frequency and technical service requirements driving fundamentally different margin structures. Refill compatibility and dosing precision separate segments where aftermarket revenue potential diverges significantly.
Product Type:
After-sales service intensity peaks with precision mechanisms that require recalibration or seal replacement during product lifecycle.
- Lotion Pumps:Standard piston-actuated dispensers with 24mm or 28mm neck finishes handle viscosities from 1,000 to 50,000 centipoise. Mass-market body care brands in the United States and Germany specify these for 200ml to 500ml family sizes where unit cost compression dominates procurement negotiations.
- Treatment Pumps:Micro-dosing systems with pre-compression chambers deliver 0.15ml to 0.30ml per actuation for serum and eye-care applications. Premium skincare houses in France and South Korea specify these for oxygen-sensitive formulations requiring airless barrier protection, generating the highest service revenue per unit through precision component replacement programs.
- Foaming Pumps:Mesh-screen aeration mechanisms convert liquid formulations to foam through mechanical agitation without propellants.
- Spray Pumps:Fine-mist actuators with mechanical breakup tips for fragrance and toner applications.
Lotion pumps hold the largest share; momentum sits with treatment pumps as preservative-free formulations proliferate.
Material:
Cost tier positioning separates commodity resin applications from certified sustainable alternatives commanding procurement premiums.
- Plastic:Polypropylene and polyethylene homopolymer constructions dominate through injection-molded pump bodies, collars, and actuators. Chinese coastal manufacturers achieve 0.03-second cycle times on 128-cavity molds, supplying North American mass-market brands at sub-cent per-component economics.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate compounds from NatureWorks and Danimer Scientific enable compostable pump assemblies. EU-based premium brands specify these to satisfy extended producer responsibility reporting, though heat deflection temperatures limit hot-fill applications.
- Glass:Borosilicate or soda-lime pump bottles for luxury fragrance and serum presentations.
- Metal:Aluminum collars and actuators for premium positioning and mechanical durability.
Plastic holds the largest share; momentum sits with biodegradable alternatives as REACH-compliant resin availability expands.
End User:
Volume concentration and specification authority determine which stakeholder controls pump design decisions.
- Brands:Finished goods companies with direct consumer relationships specify pump performance parameters, material certifications, and sustainability credentials. L'Oréal and Estée Lauder maintain captive packaging engineering teams that issue 200-page technical specifications dictating seal compatibility, actuation force curves, and shelf-life validation protocols.
- Manufacturers:Contract fillers and toll manufacturers in China's Guangdong province procure pumps against brand-provided specifications, absorbing inventory risk on 90-day payment terms.
- Retailers:Private-label skincare programs at Sephora and Ulta Beauty specify exclusive pump designs for house-brand differentiation.
- Distributors:Regional beauty supply wholesalers serving salon and spa channels.
Brands hold the largest share; momentum sits with manufacturers as direct-to-consumer order fragmentation increases.
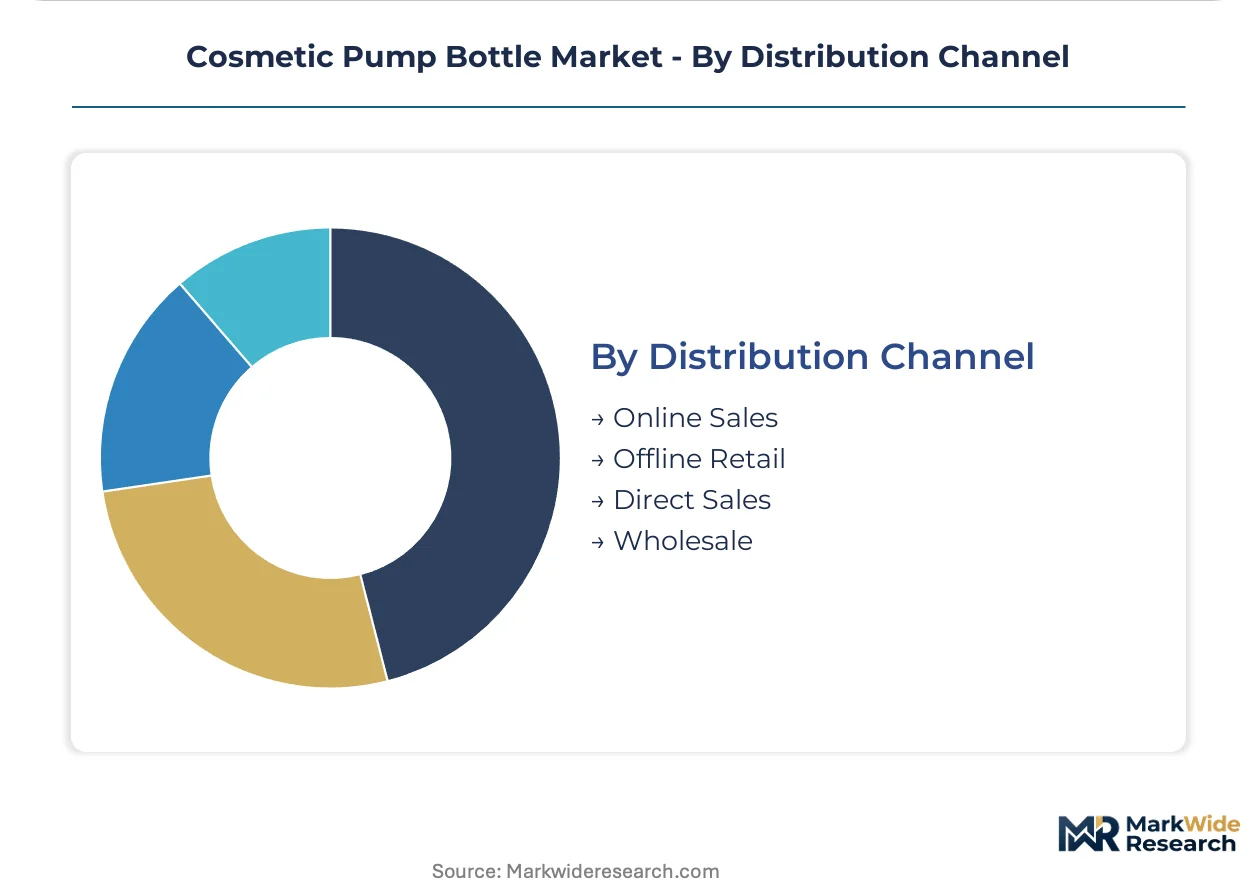
Distribution Channel:
Customer type and order frequency reshape logistics requirements and working capital intensity.
- Direct Sales:Factory-direct relationships between Zhejiang molders and California-based indie beauty brands enable 10,000-unit minimums with 21-day lead times. This channel captures the fastest expansion as direct-to-consumer sampling programs bypass traditional distributor markups.
- Wholesale:Regional packaging distributors in New Jersey and Rotterdam maintain 500-SKU inventories for mid-tier brands requiring 48-hour fulfillment.
- Online Sales:Alibaba and GlobalTrade platforms for spot procurement of standard pump specifications.
- Offline Retail:Physical trade show transactions and distributor showroom purchasing.
Wholesale holds the largest share; momentum sits with direct sales as order fragmentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. North American brands prioritize airless precision for preservative-free formulations. European procurement mandates recyclable mono-material construction. Asian manufacturing clusters supply global volume through coastal export infrastructure.
United States
Premium skincare houses in California and New York drive specification authority for treatment pump precision. FDA material safety requirements under the Federal Food, Drug, and Cosmetic Act govern polypropylene contact surfaces. New Jersey-based wholesale distributors maintain 500-SKU pump inventories for 48-hour fulfillment to mid-tier brands.
Germany
Mass-market body care brands specify lotion pumps for 200ml to 500ml family formats where unit cost dominates negotiations. REACH Annex XVII restricts phthalate plasticizers in spring and gasket compounds, forcing compound reformulation. North Rhine-Westphalia contract fillers absorb inventory risk on 90-day payment terms against brand specifications.
China
Zhejiang and Guangdong molders achieve 0.03-second cycle times on 128-cavity molds for sub-cent component economics. MEE enforcement of dual carbon goals pressures converters toward bio-based resin trials. Guangdong province dominates precision mold manufacturing for North American and European brand supply.
France
Luxury skincare houses pioneered all-polypropylene pump assemblies to satisfy extended producer responsibility reporting. ECHA-registered laboratories validate replacement chemistries for heavy-metal-free pigment development. Albéa Group anchors European supply through integrated aluminum and plastic pump production facilities.
South Korea
Domestic skincare brands specify treatment pumps for oxygen-sensitive serum formulations requiring airless barrier protection. MFDS cosmetic packaging regulations align with international material safety standards. Seoul-based premium houses generate highest service revenue per unit through precision component replacement programs.
Cosmetic Pump Bottle Market Competitive Landscape
Capability concentration sits with precision treatment pump specialists; scale advantage sits with high-volume lotion pump fabricators. The vendor base organizes around three strategic archetypes: integrated multinational converters with captive resin compounding, regional molders serving factory-direct indie beauty relationships, and component specialists focused on precision elastomer and spring assemblies. Dominant competitive moves include backward integration into resin compounding to secure bio-based material supply, and geographic expansion into Maharashtra and Karnataka to capture Indian personal care brand localization.
Among North American diversified packaging conglomerates, Silgan Holdings Inc. occupies a position exemplifying scale-driven manufacturing across personal care contract portfolios. European integrated converters are represented by Albéa Group, which anchors regional supply through multi-material production capabilities. Precision dispensing specialists include AptarGroup, Inc., sitting within the premium-tier vector through airless technology positioning for skincare applications.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| AptarGroup, Inc. |
| Albéa Group |
| Rieke Corporation |
| Berry Global Group, Inc. |
| Frapak Packaging |
| Quadpack |
| SGB Packaging Group |
| APackaging Group |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Ningbo port freight corridors transmit polypropylene resin cost volatility directly to Zhejiang molders, compressing margins on fixed-price contracts while enabling premium pricing for REACH-compliant mono-material assemblies serving EU brands.
Pricing Analysis
Long-term offtake agreements dominate procurement between North American mass-market brands and Guangdong converters, though spot purchasing gains share among California indie beauty startups ordering 10,000-unit minimums. Three-tier pricing structure across premium, standard, and economy levels separates airless treatment pumps with precision elastomer certification from commodity lotion pumps with generic polypropylene construction. Price differentiation hinges on ISO 17025 laboratory validation and after-sales component replacement bundling. Cost compression in standard lotion pumps is intensifying because Chinese coastal manufacturers compete on 0.03-second mold cycle times. Mass-market body care brands in Germany exhibit highest price sensitivity; premium skincare houses in France and South Korea accept procurement premiums for oxygen-sensitive barrier protection.
Supply Chain Analysis
Polypropylene homopolymer feedstock draws from petrochemical complexes in China, Saudi Arabia, and South Korea, with resin pricing tethered to crude oil benchmarks. Precision mold manufacturing rests on German and Japanese CNC equipment installed in Zhejiang and Guangdong facilities. Silicone elastomer and stainless steel spring components rely on single-source suppliers in Japan and Germany. Tariff exposure threatens North American brands dependent on Chinese coastal export infrastructure. Distribution runs through New Jersey and Rotterdam wholesale distributors maintaining 500-SKU inventories for 48-hour fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision component replacement programs for treatment pumps generate recurring revenue expanding faster than hardware sales, converting transactional pump supply into service-attach relationships with premium skincare houses.
For Market Incumbents: Harden airless technology patent portfolios against emerging Chinese precision molders offering factory-direct pricing to indie beauty brands. Secure captive bio-based resin supply through backward integration into PLA and PHA compounding partnerships. Expand ISO 17025 laboratory certification capacity to compress validation timelines for novel biodegradable formulations.
For New Entrants and Emerging Players: Build out modular pump head designs for reusable glass bottle systems targeting direct-to-consumer channels in California and New York. Maharashtra and Karnataka domestic skincare brands offer the most penetrable geography, seeking localized supply to reduce import duty exposure. Pursue factory-direct relationships with 10,000-unit minimums and 21-day lead times as the primary go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core personal care pump divisions. The five-to-ten year viability window favors precision treatment pump specialists with captive elastomer compounding capabilities. Packaging engineering teams issuing 200-page technical specifications signal durable customer captivity. Watch EPR framework implementation timelines across multiple jurisdictions as the inflection indicator for mono-material pump demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Resin Compounding | Secures PLA and PHA supply for EU extended producer responsibility compliance. |
| Precision Component Replacement Program Launch | Captures recurring service revenue from airless treatment pump installed base. |
| Direct-to-Consumer Channel Expansion | Bypasses New Jersey and Rotterdam distributor markups for California indie brands. |
| REACH-Compliant Colorant Substitution Investment | Opens EU market access for Southeast Asian suppliers previously excluded. |
| Indian Manufacturing Footprint Establishment | Serves Maharashtra and Karnataka brands seeking import duty reduction. |
Research Methodology
A standing panel of packaging engineering directors, contract filler procurement leads, brand sustainability officers, and wholesale distributor inventory managers provided ongoing calibration across primary interviews. Secondary validation drew from FDA Federal Food, Drug, and Cosmetic Act filings, ECHA REACH Annex XVII substance restrictions, EU Packaging and Packaging Waste Regulation drafts, and Chinese customs export data. Bottom-up pump unit shipment aggregation and top-down personal care packaging spend analysis enabled triangulation.
Scenario-bracketing framed projections across the analysis window through sensitivity testing of petrochemical input volatility and regulatory compliance timeline acceleration. Segmentation dimensions modeled include pump mechanism type, material certification tier, end-user specification authority, and distribution channel order frequency. CAGRs derived from compound annual growth rate curve-fitting against historical shipment trajectories. Forecast inputs incorporated dual carbon goal enforcement intensity from China's MEE and EPR framework adoption pace across European member states.
Practitioners should monitor crude oil benchmark movements and REACH Annex XVII amendment cycles for early signals requiring forecast revision. Cross-checking against personal care packaging spend data from Nielsen and Circana retail audits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Cream Jars Market