
 Europe Cosmetic and Perfumery Glass Bottle Packaging Market | 2026-2036
Europe Cosmetic and Perfumery Glass Bottle Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cosmetic and Perfumery Glass Bottle Packaging Market Foresight
Post-consumer recycled glass is restructuring cost and quality benchmarks across cosmetic packaging supply chains. Gerresheimer AG leverages its pharmaceutical-grade glass expertise to serve prestige fragrance clients with exacting clarity standards. Groupe Pochet anchors its competitiveness through integrated crystal manufacturing in Normandy, controlling raw material sourcing and decorative finishing under one roof. Verescence differentiates via flame-polishing technology that eliminates secondary surface treatments for high-end perfume bottles.
Europe cosmetic and perfumery glass bottle packaging encompasses soda-lime and borosilicate vessels formed through blow-and-blow or press-and-blow processes, typically featuring wall thicknesses of 2–5 millimeters and compatibility with crimped spray pumps and threaded metal closures. These containers protect volatile fragrance compounds from UV degradation and oxidation while conveying brand equity through tactile weight and optical clarity. Pump bottles lead volume demand across mass-market skincare and body care lines, whereas dropper bottles represent the fastest-expanding segment as serum and facial oil formulations multiply across indie and established beauty labels. Closure type selection increasingly determines margin pools, with metal caps commanding premium positioning in classic design styles for heritage fragrance houses.
EMA cosmetic ingredient oversight, REACH chemical compliance, and EU Green Deal carbon-border adjustments collectively tighten material traceability and energy disclosure requirements for glass converters serving beauty brands. CE marking obligations for packaging machinery further shape capital investment patterns among mid-sized bottle decorators. Stakeholders must monitor evolving Extended Producer Responsibility schemes and recycled content mandates that will reshape supplier qualification criteria and furnace technology roadmaps.
Market Dynamics
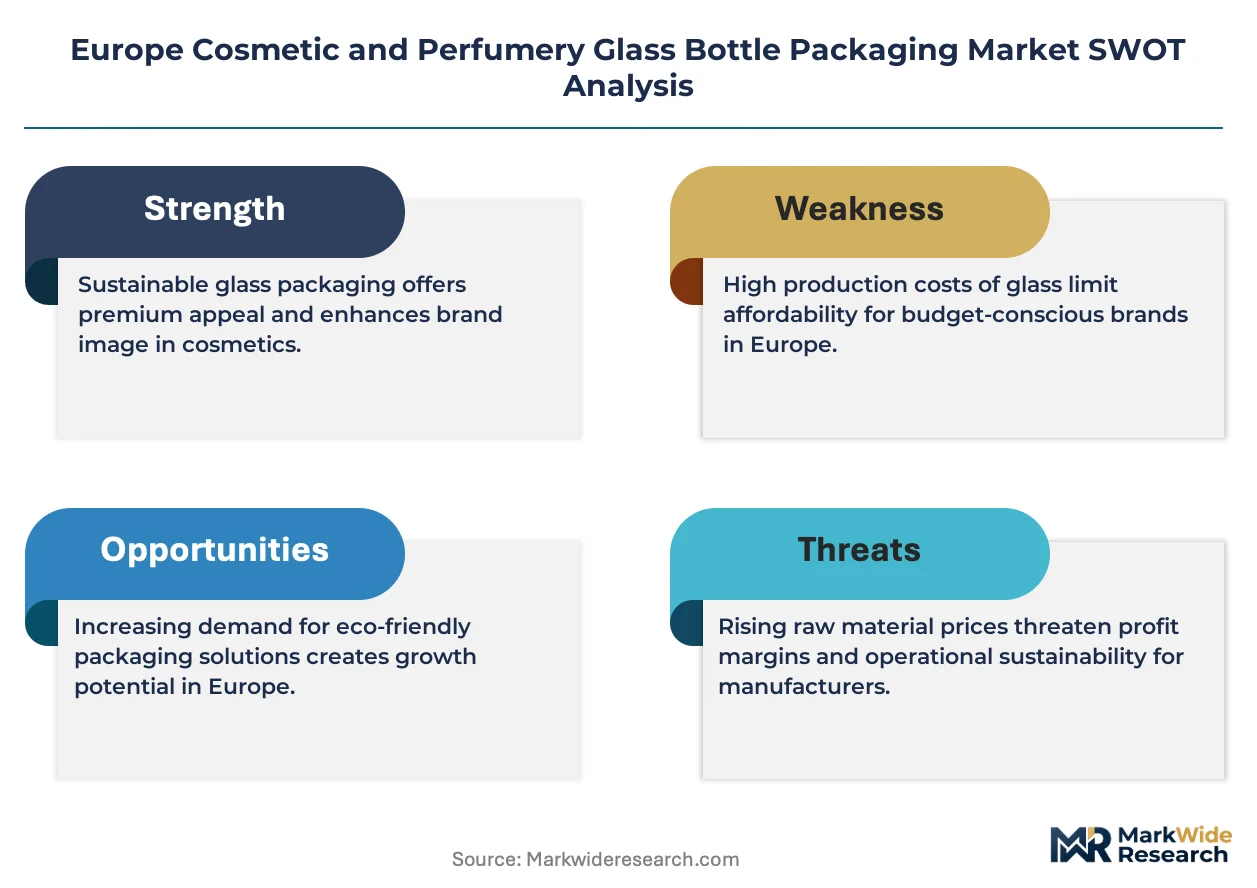
The EU Green Deal and F-Gas Regulation are forcing a furnace technology transition across European glass converters, with electric melting and post-consumer recycled cullet integration now determining competitive viability in cosmetic and perfumery packaging supply chains.
Growth Catalysts
- REACH chemical compliance mandates:Beauty brands require full material traceability from glass converters, creating qualification barriers that favor established suppliers with documented supply chains.
- Emilia-Romagna glassmaking cluster concentration:Italy's artisanal and industrial producers co-located in this region enable rapid prototyping and short-run flexibility for limited-edition fragrance launches.
- Electric furnace retrofits:The EU Green Deal's carbon-border adjustments accelerate capital deployment toward low-emission melting technologies that reduce scope emissions for beauty brand clients.
Market Restraints
- Natural gas price volatility:Conventional fossil-fuel furnaces expose converters to input cost swings that compress margin pools during energy price spikes.
- Post-consumer recycled cullet quality inconsistency:Cosmetic-grade glass demands exacting clarity standards that mechanically sorted recycled feedstock struggles to meet without optical sorting upgrades.
- Aluminum and polymer closure substitution:Lightweight dispensing solutions threaten glass volume in mass-market body care and hair care applications where tactile weight matters less.
Strategic Opportunities
- Portuguese converter expansion:Underdeveloped premium glass capacity in Portugal offers greenfield sites for solar-powered furnace installations serving Iberian beauty brands.
- Refillable fragrance systems:Permanent bottle programs with replaceable inner cartridges extend customer lifetime value while reducing per-use material intensity.
- CE marking harmonization:Standardized machinery safety certifications reduce cross-border equipment deployment friction for decorators serving multinational beauty houses.
Industry Challenges
- Flame-polishing technician scarcity:Specialized surface-finishing expertise required for high-clarity perfume bottles faces generational attrition without structured apprenticeship pipelines.
- Extended Producer Responsibility scheme complexity:Divergent national implementations across France, Germany, and Italy create compliance fragmentation for pan-European brand portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cosmetic and Perfumery Glass Bottle Packaging Market |
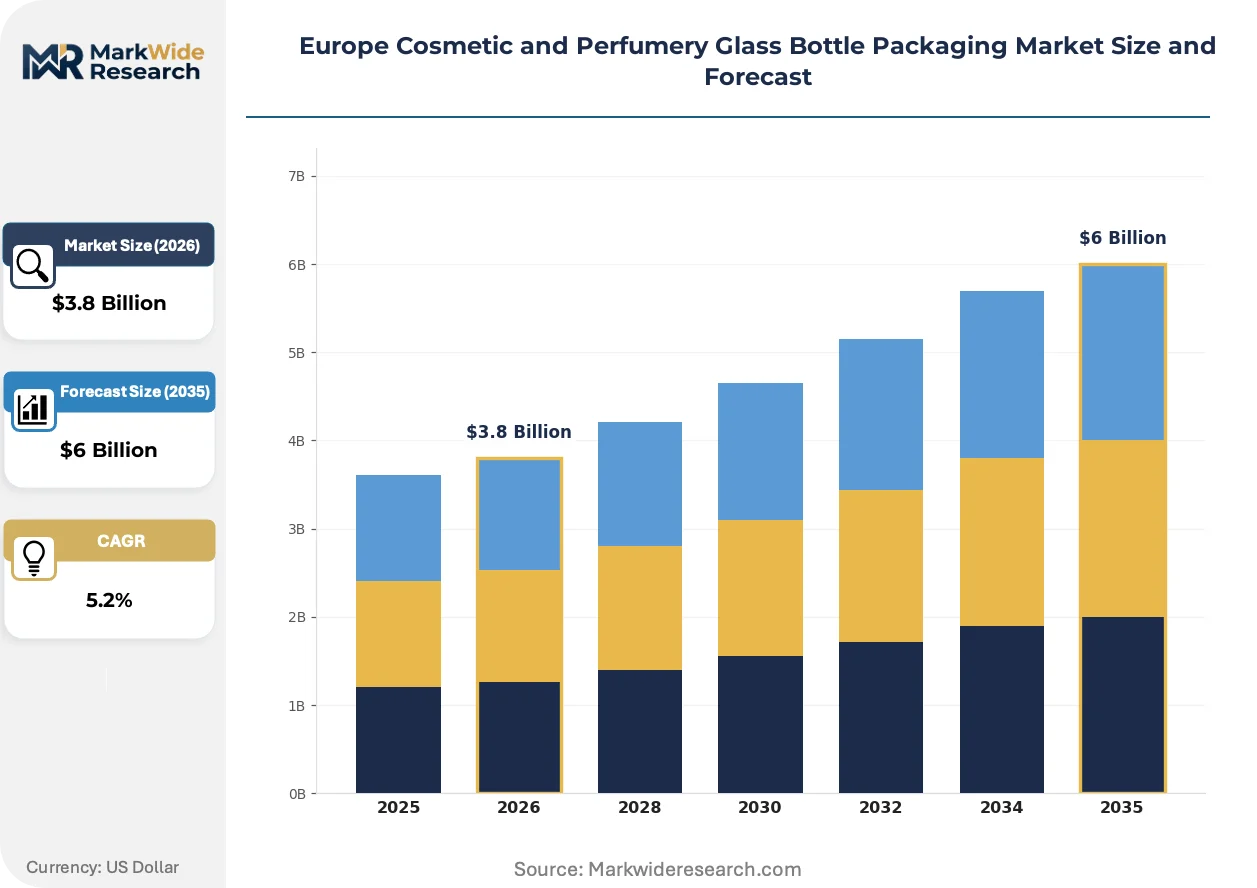
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-On Bottles, Pump Bottles, Dropper Bottles, Jars Closure Type: Metal Caps, Plastic Caps, Wooden Caps, Spray Pumps Capacity: 30ml, 50ml, 100ml, 200ml Design Style: Classic, Modern, Vintage, Minimalist |
| Companies Covered | Bormioli Luigi, Groupe Pochet, Gerresheimer AG, Quadpack, Aptar, Verallia, Zignago Vetro, HCP Global Cosmetics Packaging, Verescence, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cosmetic and Perfumery Glass Bottle Packaging Market Shifts & Advancements
European cosmetic glass packaging is experiencing a technology and compliance pivot where furnace decarbonization, regulatory traceability, and brand-led circularity programs are simultaneously reshaping converter investment priorities and buyer qualification criteria.
Flame-polishing automation is consolidating quality consistency in premium perfume bottle production. Heritage fragrance houses in France and Italy are adopting robotic surface-finishing cells to reduce manual labor dependency while maintaining optical clarity standards. This technology compression is enabling mid-volume converters to compete for prestige brand contracts previously reserved at larger suppliers.
The EU Green Deal's carbon-border adjustment mechanism is tightening emissions disclosure requirements for imported packaging materials. Glass converters must now document scope emissions across melting, forming, and decoration processes to maintain qualification with multinational beauty brands. Small and mid-sized decorators in Germany and Spain face the steepest compliance adaptation costs.
Beauty brand procurement teams are consolidating supplier panels around circularity credentials. Indie skincare labels and established fragrance houses alike now mandate post-consumer recycled content minimums and take-back program participation in glass packaging tenders. This qualification compression is most visible in France, where Sephora and Marionnaud distribution networks amplify brand sustainability signaling to end consumers.
Europe Cosmetic and Perfumery Glass Bottle Packaging Market Segmentation
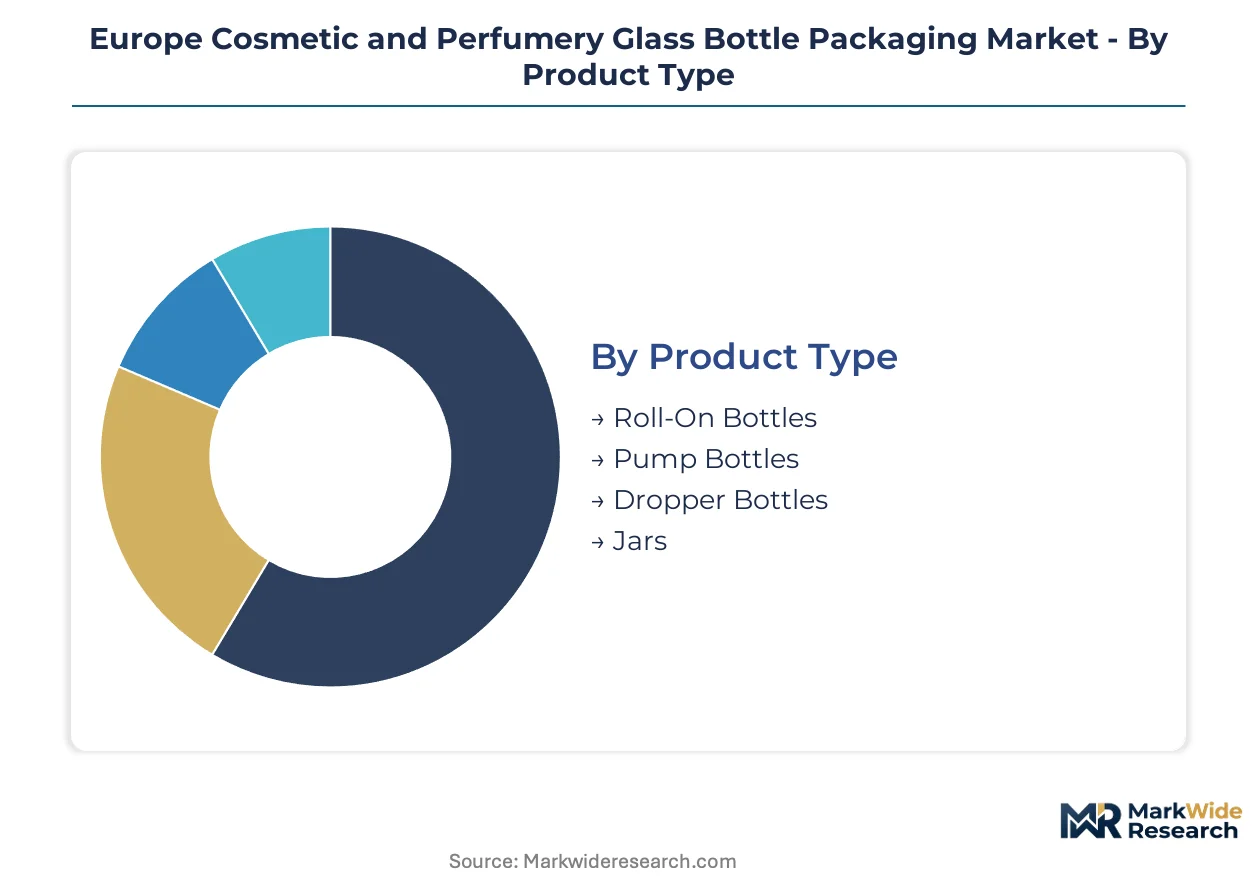
Glass packaging specifications in European cosmetics and perfumery diverge sharply across application requirements, dispensing mechanisms, and brand positioning tiers. Understanding these segment boundaries clarifies where converter capabilities must align with formulation chemistry, retail channel expectations, and sustainability mandates.
Product Type:
Forming technology and wall thickness specifications determine which product types command premium positioning versus mass-market volume.
- Pump Bottles:Blow-and-blow formed vessels with 2–3 millimeter walls dominate mass-market skincare and body care lines across German drugstore chains. Compatibility with crimped spray pumps and threaded metal closures drives procurement consolidation among converters serving Coty and L'Oréal fragrance portfolios.
- Dropper Bottles:Press-and-blow precision forming enables the narrow neck geometries required for pipette dispensing. Serum and facial oil formulations from indie beauty labels in France and the United Kingdom are expanding most quickly, with Emilia-Romagna converters capturing short-run flexibility for limited-edition launches.
- Roll-On Bottles:Spherical internal cavities formed through specialized mold designs accommodate ball-bearing applicators for eye serums and targeted treatments.
- Jars:Wide-mouth press-and-blow containers serve thick cream formulations with wall thicknesses reaching 5 millimeters for tactile weight in premium positioning.
Mature deployment sits with pump bottles across established fragrance houses. Newer deployment is concentrated in dropper bottles as clean beauty serum formulations multiply.
Closure Type:
Margin pools concentrate disproportionately in closure selection, with material and mechanism choices signaling brand tier to end consumers.
- Metal Caps:Zamak alloy and aluminum stampings deliver the cold-touch sensation and acoustic closure that heritage fragrance houses in France require for classic design codes. REACH compliance documentation for surface coatings creates qualification barriers favoring established Italian and German suppliers with documented supply chains.
- Spray Pumps:Crimped aluminum actuator assemblies with dip tubes demand precise neck finish tolerances from glass converters. Mass-market adoption across Spanish and Portuguese beauty brands prioritizes cost efficiency over tactile premiumization.
- Plastic Caps:Injection-molded polypropylene and ABS alternatives reduce unit costs for body care lines where glass weight matters less than shelf price positioning.
- Wooden Caps:Turned hardwood closures from sustainable forestry certification programs serve niche organic cosmetic brands in Scandinavia and German-speaking markets.
Metal caps anchor prestige fragrance positioning. Plastic caps dominate volume across mass-market personal care.
Capacity:
Volume specifications correlate directly with retail channel economics and consumer usage occasion segmentation.
- 50ml:The standard reference size for eau de parfum and eau de toilette launches across Sephora and Marionnaud distribution networks. German converters optimize furnace campaigns around this capacity to minimize changeover downtime.
- 100ml:Gift set and duty-free channel concentration drives demand for heavier wall constructions that signal value through tactile weight. French luxury houses specify this capacity for flagship fragrance introductions.
- 30ml:Travel retail and discovery set formats favor this compact dimension for skincare serums and niche perfume sampling programs.
- 200ml:Body lotion and hair care applications in family-size formats where glass competes against polymer substitution pressure.
50ml capacity commands the deepest converter tooling investment. 30ml formats are gaining share fastest through travel retail expansion.
Design Style:
Aesthetic coding determines decoration technology requirements and the geographic concentration of specialized finishing capabilities.
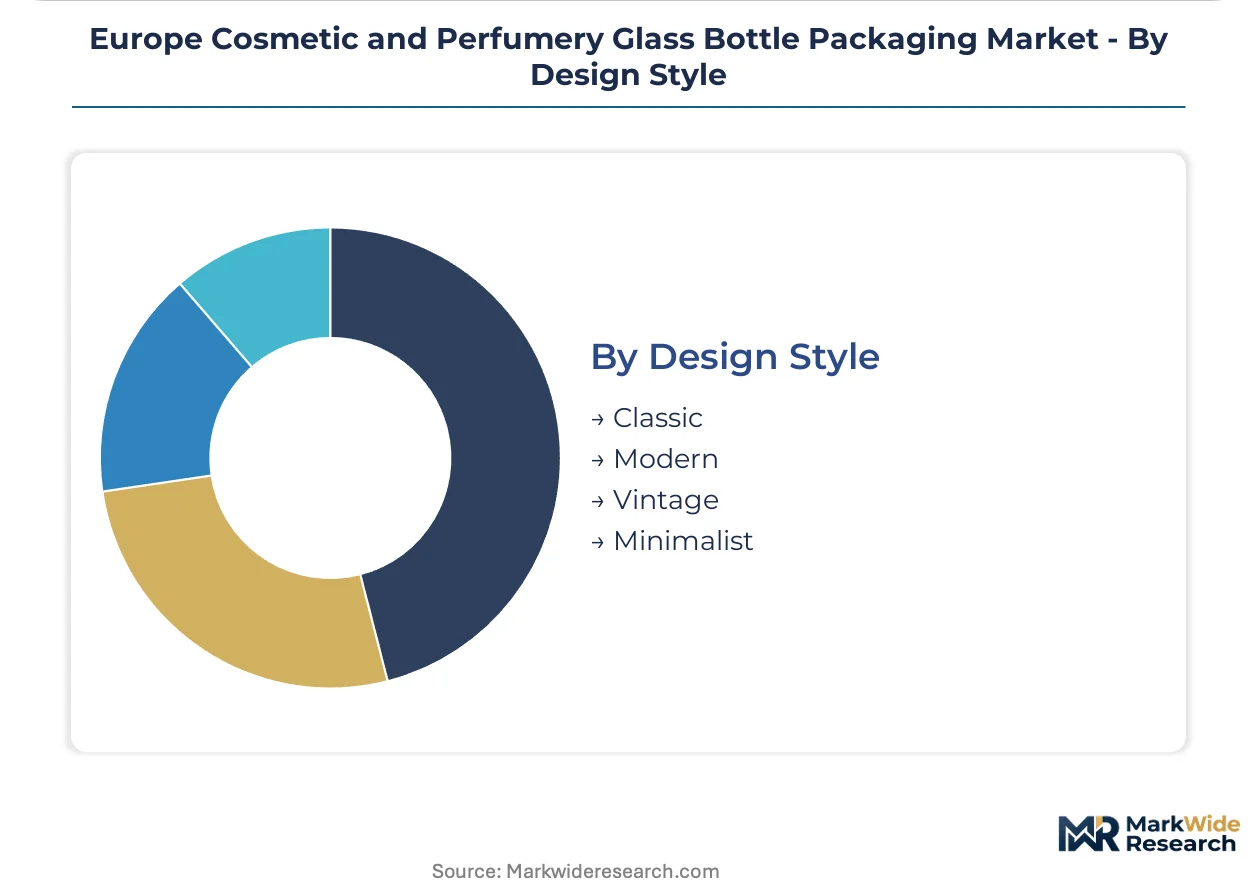
- Classic:Faceted crystal geometries and heavy bases reference nineteenth-century perfume architecture. Normandy manufacturing clusters retain flame-polishing expertise for optical clarity without secondary coatings.
- Minimalist:Cylindrical or rectangular profiles with reduced surface decoration align with Scandinavian and Dutch beauty brand codes. This style is expanding most quickly as clean beauty positioning prioritizes sustainability signaling over ornamentation.
- Modern:Asymmetric silhouettes and gradient coloration through internal coating technologies serve contemporary fragrance launches targeting younger demographics.
- Vintage:Reproduction mold designs and applied ceramic labeling evoke heritage apothecary references for niche perfume houses in Italy and France.
Classic styling retains the deepest heritage converter relationships. Minimalist codes are capturing procurement priority as sustainability disclosure requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates the deepest demand for premium perfumery glass, with heritage fragrance houses driving procurement consolidation around Normandy and Paris Basin manufacturing clusters. This demand-side weight shapes converter investment priorities across neighboring supply basins.
France
Heritage fragrance houses in Grasse and Paris anchor procurement volumes for limited-edition crystal bottles. ANSM cosmetic oversight and REACH chemical compliance tighten material documentation requirements for glass converters serving LVMH and Kering beauty portfolios. Normandy manufacturing clusters retain flame-polishing expertise for optical clarity without secondary surface coatings.
Italy
Emilia-Romagna glassmakers capture short-run flexibility for indie skincare labels launching serum and facial oil formulations. ECHA enforcement of SVHC candidate list substances pushes decorators toward documented supply chain transparency. The Piacenza-Parma corridor concentrates both artisanal crystal producers and industrial converters serving Scandinavian clean beauty brands.
Germany
Drugstore chains DM and Rossmann drive mass-market pump bottle volumes for body care and hair care applications. KBA industrial safety standards and CE marking obligations shape capital investment patterns among mid-sized decorators in North Rhine-Westphalia. The Cologne-Düsseldorf corridor hosts furnace retrofit specialists serving pan-European beauty brand networks.
Spain
Barcelona-based cosmetic brands expand glass procurement for Mediterranean-inspired fragrance launches targeting travel retail channels. The country's national pharmaceutical regulator aligns cosmetic packaging standards with EU MDR technical documentation requirements. Catalan glass converters invest in electric melting pilot lines to meet Iberian sustainability procurement mandates.
United Kingdom
Indie beauty labels in London and the Southeast multiply dropper bottle demand for clean beauty serum formulations. The Health and Safety Executive enforces workplace exposure limits for decorative coating processes in packaging facilities. The Midlands manufacturing belt hosts decorators specializing in minimalist cylindrical profiles for Scandinavian brand codes.
Europe Cosmetic and Perfumery Glass Bottle Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage fragrance houses favoring captive supply relationships while mass-market brands consolidate around multi-category packaging platforms. The vendor base organizes into three tiers: integrated crystal manufacturers controlling raw material sourcing, mid-scale decorators with flexible furnace campaigns, and regional specialists serving geographic brand clusters. Two dominant competitive moves are reshaping positioning: electric furnace retrofits to meet EU Green Deal carbon-border requirements, and backward integration into decorative finishing to capture margin pools in metal closure assembly.
Among France-based fabricators, Groupe Pochet and Verescence exemplify integrated manufacturing archetypes with captive control over Normandy crystal production and surface finishing capabilities. Germany's Gerresheimer AG occupies a position bridging pharmaceutical-grade glass expertise and prestige fragrance client requirements. Italian specialists including Bormioli Luigi and Zignago Vetro represent the flexible-campaign tier, with Emilia-Romagna proximity enabling rapid prototyping for limited-edition launches.
| Leading Market Players |
|---|
| Bormioli Luigi |
| Groupe Pochet |
| Gerresheimer AG |
| Quadpack |
| Aptar |
| Verallia |
| Zignago Vetro |
| HCP Global Cosmetics Packaging |
| Verescence |
| Others |
Supply & Pricing Matrix
Electric furnace retrofits across Normandy and Emilia-Romagna are simultaneously inflating capital depreciation schedules and concentrating procurement leverage among converters with balance-sheet capacity for decarbonization investments. This technology transition fragments the supplier base into capital-rich integrated manufacturers and margin-pressured regional decorators.
Pricing Analysis
Volume-mass pump bottles for German drugstore chains trade on thin conversion margins, while crystal perfume vessels for French heritage houses capture substantial brand-premium markups. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in wall-thickness specifications, optical clarity grades, and decorative finishing intensity. Cost compression in mass-market tiers is intensifying because aluminum closure substitution threatens glass volume in body care applications. Drugstore chain procurement teams exhibit highest price sensitivity, whereas LVMH and Kering beauty portfolios prioritize supply security and sustainability credentials over unit cost.
Supply Chain Analysis
Flame-polishing technician scarcity in Normandy and the Piacenza-Parma corridor is constraining output expansion for premium perfume bottle orders. Supply concentrates in France, Italy, and Germany, with raw material sourcing drawing from Belgian soda ash deposits, Spanish silica sand, and German dolomite processors. Single-source vulnerability sits with specialized crystal cullet suppliers serving optical-clarity grades. Distribution runs through converter-direct relationships with heritage fragrance houses, supplemented by packaging distributors serving mid-market indie beauty labels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as EU Green Deal carbon-border adjustments disqualify smaller decorators lacking emissions documentation infrastructure. Furnace technology transitions are forcing weaker capitalized players toward exit or acquisition.
For Market Incumbents: Anchor competitiveness through backward integration into decorative metal closure assembly, capturing margin pools currently leaking to Zamak alloy stampers in Italy and Germany. Prioritize electric furnace commissioning in Portugal to preempt Iberian sustainability procurement mandates from Barcelona-based beauty brands. Aluminum and polymer substitution threats in mass-market body care demand defensive positioning through premiumization of pump bottle tactile specifications. For New Entrants and Emerging Players: Robotic flame-polishing cells offer a technology-first wedge into mid-volume prestige fragrance contracts previously reserved for heritage Normandy suppliers. Target Portuguese greenfield solar-powered furnace installations serving underserved Iberian clean beauty labels. Indie skincare serum formulations in London and the Southeast present the most penetrable demand segment, with go-to-market execution through Emilia-Romagna prototyping partnerships enabling rapid limited-edition turnaround. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale Italian decorators possessing flexible furnace campaigns and documented REACH supply chains, given ECHA enforcement tightening qualification barriers. Long-term viability favors converters with captive crystal production and integrated surface-finishing capabilities across a five-to-ten-year decarbonization window. Monitor electric furnace retrofit completion rates as the inflection signal distinguishing acquisition targets from stranded-asset risks.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Retrofit | EU Green Deal carbon-border compliance secures qualification with multinational beauty brand procurement panels. |
| Backward Integration into Metal Closure Assembly | Captures margin pools in Zamak alloy and aluminum stamping currently outsourced to specialized suppliers. |
| Portuguese Greenfield Expansion | Solar-powered melting capacity addresses Iberian sustainability mandates from Barcelona-based fragrance houses. |
| Robotic Flame-Polishing Deployment | Reduces manual labor dependency while maintaining optical clarity standards for heritage perfume bottle orders. |
| Refillable Fragrance System Development | Permanent bottle programs with replaceable cartridges extend customer lifetime value for clean beauty positioning. |
Research Methodology
Multi-period observation of furnace technology adoption rates, recycled cullet integration levels, and carbon-border compliance documentation anchored the trend analysis, supplemented by interviews with glass converter operations directors, beauty brand procurement managers, decorative finishing technicians, and ECHA regulatory affairs specialists. Secondary validation drew from EU ETS emissions disclosure databases, REACH SVHC candidate list updates, CE marking machinery safety directives, and customs trade flows for cosmetic glass packaging. Bottom-up segment sizing triangulated against top-down macro demand indicators from fragrance house production schedules.
Segment-weighting approaches modeled product type splits across pump bottles, dropper bottles, and jars, crossed with closure type tiers and capacity specifications. CAGRs were derived from regression analysis of historical volume trends projected across the analysis window, incorporating electric furnace deployment timelines and Extended Producer Responsibility scheme implementation schedules. Industry-specific forecast inputs included beauty brand sustainability procurement mandate acceleration and indie skincare label formation rates in France and the United Kingdom.
Several conditions sit outside the modeled scope, including abrupt natural gas price spikes affecting conventional furnace economics, breakthrough polymer substitution technologies displacing glass in mass-market applications, and divergent national Extended Producer Responsibility implementations fragmenting pan-European compliance. Forecasts reflect documented assumptions regarding EU Green Deal enforcement continuity and recycled cullet quality improvement trajectories. Material deviation in carbon-border adjustment timelines or flame-polishing automation adoption rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Mason Jars Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Turkey Container Glass Market