
 Lip Care Packaging Market | 2026-2036
Lip Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Care Packaging Market Outlook
Aftermarket refill and reuse program revenue is rewriting margin capture across the lip care packaging value chain. HCP Packaging leverages its Asian manufacturing footprint to supply premium stick containers for global cosmetic houses. Albéa Group anchors European demand through its specialized tube and jar production lines with integrated post-consumer recycled content capabilities. AptarGroup differentiates via precision dispensing closure systems that extend brand owner control over product dosing consistency.
Lip care packaging encompasses primary and secondary containment systems engineered from polypropylene, polyethylene, glass, or aluminum substrates, typically ranging from 3 milliliters to 15 milliliters in fill volume, designed to protect balm, gloss, or treatment formulations from oxidation, contamination, and mechanical damage while enabling controlled consumer application. Stick containers command the largest volume share due to their compatibility with wax-based formulations and ergonomic single-hand use, though tubes are gaining fastest among liquid and semi-liquid product extensions where flexible dispensing matters. Plastic dominates material selection for its cost efficiency and decoration versatility, yet composite structures incorporating bio-based layers are emerging as the margin pool for sustainability-positioned brands seeking differentiation at shelf.
The FDA regulates cosmetic packaging under the Federal Food, Drug, and Cosmetic Act with specific attention to color additive safety and labeling accuracy, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability targets that reshape material specifications across export-bound production. ISO 9001 and ISO 15378 certification requirements for primary packaging materials further constrain supplier qualification timelines and capital deployment decisions. Stakeholders must monitor evolving state-level plastic bans in California and New York alongside pending EU harmonization of recycled content mandates to align capacity investments with compliance-bound demand corridors.
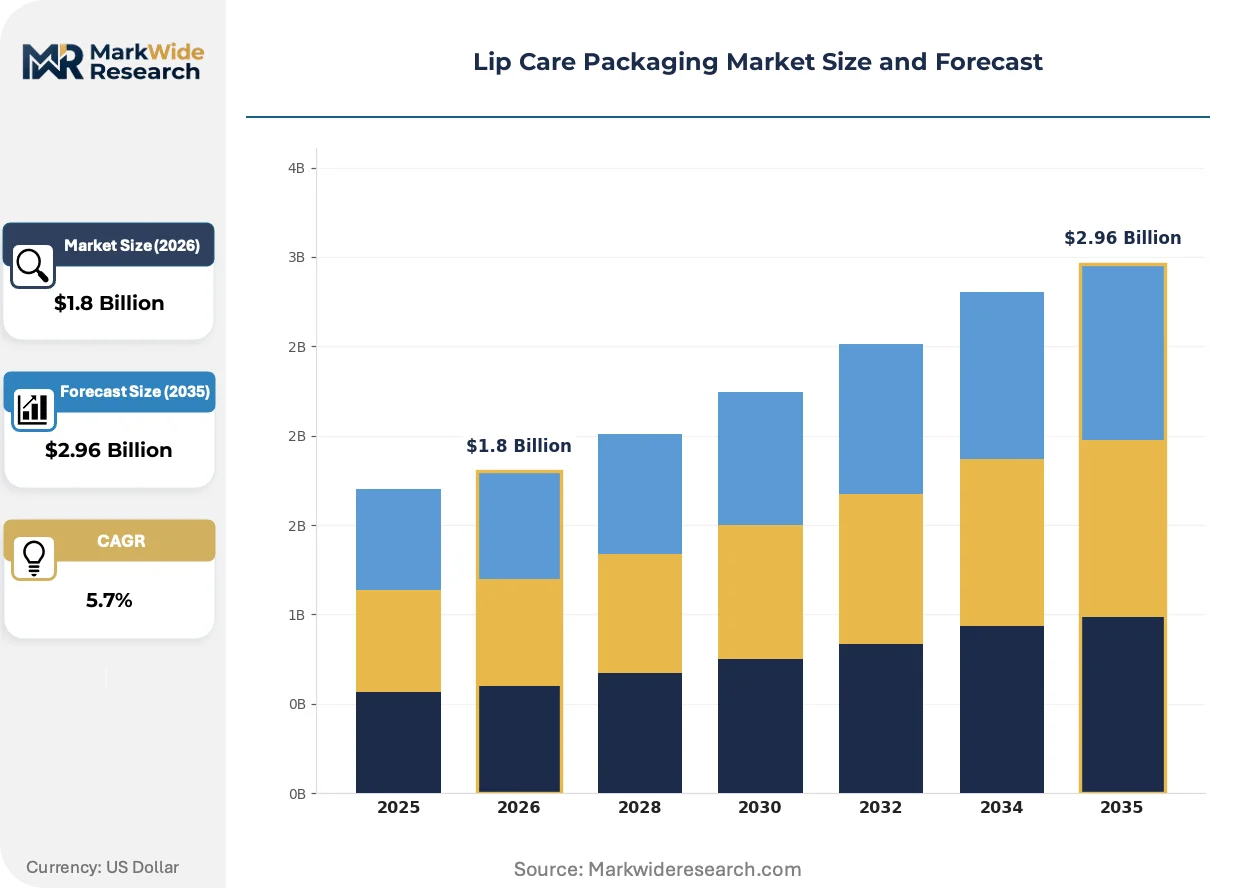
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material specifications across export-bound production, forcing converters to requalify substrates and accelerate mono-material recyclable formats ahead of enforcement timelines.
Growth Catalysts
- Refillable format mandates:The EU Packaging and Packaging Waste Regulation creates binding demand for reusable primary packaging systems, pulling investment into stick container redesigns across German and French cosmetic supply chains.
- Post-consumer recycled content specifications:Brand owners in the United States are specifying minimum PCR thresholds for polyethylene tubes, converting formerly virgin-dependent supply chains to circular feedstock sourcing.
- Direct-to-consumer channel expansion:US-based beauty brands prioritize portable, shelf-differentiated formats that compress order minimums and accelerate sampling program deployment.
Market Restraints
- Polypropylene price volatility:Feedstock cost swings for homopolymer resins compress converter margins and destabilize annual contract pricing with cosmetic houses.
- Asian manufacturing concentration:Premium stick container supply clusters in Chinese and South Korean production zones, exposing lead time risk from port congestion and tariff uncertainty.
- Multi-layer barrier incompatibility:Existing composite tubes with EVOH oxygen barriers face mechanical recycling exclusion, stranding capital in legacy extrusion assets.
Strategic Opportunities
- Italian converter specialization:Northern Italy's packaging machinery cluster offers acquisition targets for brands seeking European nearshoring of tube production.
- Bio-based polymer qualification:Drop-in polyethylene from sugarcane feedstock is hybridizing with conventional resin streams, opening premium positioning for sustainability-certified lines.
- Pharmaceutical channel crossover:Medicated lip treatment formats are penetrating pharmacy retail in Germany, requiring ISO 15378-compliant primary packaging that commands price premiums over cosmetic-grade equivalents.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical-grade quality management system implementation stretches 14-18 months, delaying supplier qualification for medicated lip care launches.
- Legacy decoration asset stranding:Hot stamping and silk screening equipment lacks compatibility with thinner-walled recyclable substrates, forcing premature capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Care Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tubes, Jars, Stick Containers, Pots Material: Plastic, Glass, Metal, Composite Closure Type: Screw Cap, Flip Top, Roll-On, Snap Fit End User: Retail Consumers, Salons, Online Users, Wholesalers |
| Companies Covered | HCP Packaging, AptarGroup, Albéa Group, Berry Global, Quadpack, Berlin Packaging, IntraPac International, Arminak & Associates, Park Tech A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Care Packaging Market Strategic Shifts
Material science convergence with regulatory compliance is compressing development cycles and forcing parallel qualification of sustainable substrates alongside performance validation.
Mono-material polypropylene tubes are hybridizing with integrated precision dispensing closures, eliminating multi-component assembly. Premium cosmetic brands in France and Germany are specifying these formats for liquid lip treatment extensions. The technology is hybridizing supply chain structures by collapsing former separation between tube body and closure suppliers into single-source relationships.
REACH substance restriction updates are tightening scrutiny on color additives and plasticizers in lip-contact applications. The European Chemicals Agency's candidate list expansion is forcing reformulation of decorative coatings previously standard in mass-market sticks. German brand owners are responding by accelerating migration to mineral-based pigment systems ahead of sunset dates.
Aftermarket refill program architecture is restructuring brand-owner converter relationships toward long-term service contracts. Direct-to-consumer beauty brands in the United States are unbundling primary container ownership from product purchase, converting one-time packaging sales into recurring revenue streams. This shift concentrates most visibly in California and New York markets where sustainability messaging drives subscription adoption rates.
Lip Care Packaging Market Segmentation
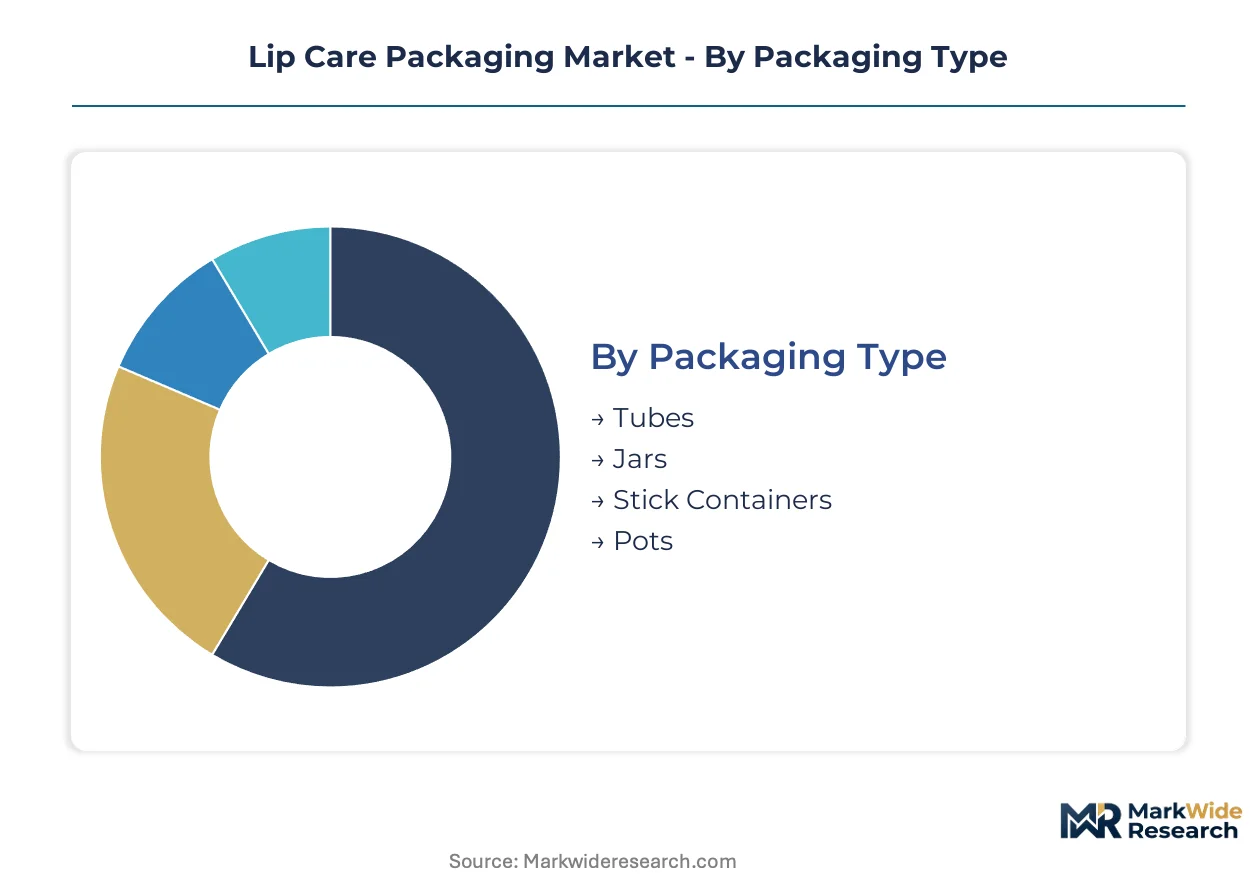
Segmentation in lip care packaging reveals how formulation chemistry, retail channel requirements, and regulatory compliance reshape procurement decisions across the value chain. Each dimension captures distinct technical and commercial trade-offs that determine supplier qualification and margin capture.
Packaging Type:
Mature stick formats dominate current throughput, while emerging tube innovations are displacing legacy containers in liquid and semi-liquid extensions.
- Tubes:Flexible polyethylene or polypropylene extrusions with precision dispensing closures enable controlled dosage for liquid lip treatments. Demand concentrates in direct-to-consumer beauty brands across the United States where portable formats accelerate sampling program deployment and shelf differentiation drives repeat purchase.
- Stick Containers:Rigid polypropylene or polyethylene tubes with smooth-twist mechanisms protect wax-based balm formulations from oxidation and contamination. German and French cosmetic houses specify these formats for premium balm lines where ergonomic single-hand use and decoration versatility support brand positioning at retail.
- Jars:Wide-mouth containers in glass or thick-walled plastic accommodate pot-style balms requiring finger application.
- Pots:Compact circular formats with snap-fit or screw closures target travel-size and gift-set configurations.
Stick containers handle the majority of throughput; tubes are climbing the fastest on share as liquid treatment extensions proliferate.
Material:
Cost tier stratification separates commodity resin streams from certified sustainable alternatives commanding procurement premiums.
- Plastic:Polypropylene and polyethylene homopolymers and copolymers deliver cost efficiency, decoration versatility, and compatibility with high-speed filling lines. Brand owners in the United States are specifying minimum post-consumer recycled content thresholds for polyethylene tubes, converting formerly virgin-dependent supply chains to circular feedstock sourcing under emerging state-level mandates in California and New York.
- Glass:Borosilicate or soda-lime containers provide inert barrier properties for premium treatment formulations sensitive to oxygen permeation. Italian and French luxury cosmetic houses specify these formats for pharmacy-positioned medicated treatments where perceived quality and recyclability support price positioning.
- Metal:Aluminum tins and tubes offer collapsible formats with complete light and oxygen barrier protection.
- Composite:Multi-layer structures incorporating EVOH oxygen barriers face mechanical recycling exclusion under EU Packaging and Packaging Waste Regulation, stranding capital in legacy extrusion assets.
Plastic commands absolute volume; glass is expanding most quickly in premium positioning.
Closure Type:
Application mechanics determine consumer experience quality and dosing precision across formulation viscosities.
- Screw Cap:Threaded polypropylene closures with torque specifications ensure secure sealing for jar and pot formats. German pharmacy retailers specify ISO 15378-compliant screw cap systems for medicated lip treatments where child-resistance and tamper-evidence satisfy regulatory requirements.
- Flip Top:Hinged polypropylene closures enable single-hand operation for tube formats in portable use contexts. Direct-to-consumer brands in the United States prioritize flip-top tubes for on-the-go application scenarios where convenience drives subscription retention.
- Roll-On:Stainless steel or glass roller ball applicators deliver cooling sensation for liquid treatment serums.
- Snap Fit:Friction-lock closures reduce component count and assembly complexity for cost-optimized mass-market sticks.
Screw caps and flip tops together dominate current procurement; roll-on formats are gaining share fastest in treatment serum extensions.
End User:
Customer type segmentation maps volume scale against margin structure and service intensity requirements.
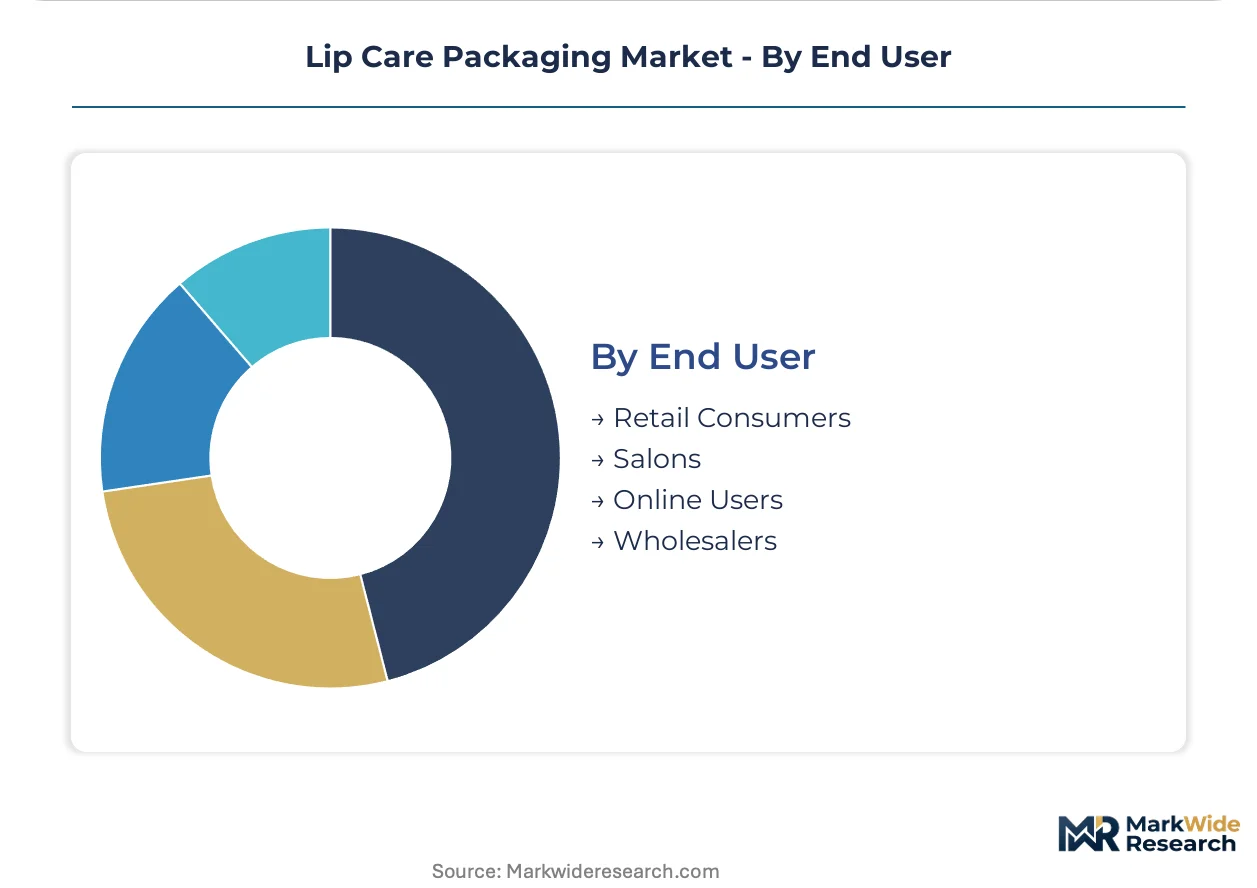
- Retail Consumers:Individual purchasers through mass-market, specialty beauty, and pharmacy channels drive format standardization and decoration investment. EU refillable format mandates are pulling investment into stick container redesigns across German and French supply chains serving this segment.
- Salons:Professional service providers require bulk-format jars and tubes with hygienic dispensing for back-bar treatment application.
- Online Users:Direct-to-consumer subscription purchasers prioritize portable, shelf-differentiated formats that compress order minimums and enable sampling program deployment.
- Wholesalers:Distributors serving fragmented retail networks demand standardized formats with inventory flexibility and rapid replenishment cycles.
Retail consumers generate the dominant revenue pool; online users are expanding most quickly as subscription models restructure purchase frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European markets prioritize regulatory-compliant refillable formats, while US buyers favor portable direct-to-consumer designs, and Asian manufacturing hubs concentrate export-oriented premium production capacity.
United States
Direct-to-consumer beauty brands drive demand for portable tubes and stick containers that enable sampling program deployment and shelf differentiation. The FDA regulates cosmetic packaging under the Federal Food, Drug, and Cosmetic Act with attention to color additive safety and labeling accuracy. California and New York state-level plastic bans are accelerating minimum post-consumer recycled content specifications for polyethylene tubes.
Germany
Pharmacy-positioned medicated lip treatments are penetrating retail channels, requiring ISO 15378-compliant primary packaging that commands price premiums. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability targets that reshape material specifications. Northern Italy's packaging machinery cluster supplies German converters with specialized tube production equipment.
France
Premium cosmetic houses specify mono-material polypropylene tubes with integrated precision dispensing closures for liquid lip treatment extensions. REACH substance restriction updates through the European Chemicals Agency are tightening scrutiny on color additives and plasticizers in lip-contact applications. Paris-based brand owners are accelerating migration to mineral-based pigment systems ahead of regulatory sunset dates.
China
Manufacturing concentration for premium stick containers serves global cosmetic houses through export-oriented production zones. The country's national packaging standards align with international ISO certifications for primary materials. Zhejiang and Jiangsu province-based converters supply HCP Packaging's Asian manufacturing footprint with specialized injection molding capacity.
Italy
Luxury cosmetic houses specify glass containers for pharmacy-positioned treatments where perceived quality supports price positioning. The EU Green Deal implementation is accelerating demand for mono-material recyclable solutions across Italian export-bound production. Lombardy-based converters specialize in tube and jar production lines with integrated post-consumer recycled content capabilities.
Lip Care Packaging Market Competitive Environment
Capability concentration sits with specialized converters holding pharmaceutical-grade certifications; scale advantage sits with diversified packaging conglomerates serving multi-category beauty portfolios. The market structures around three tiers: premium specialists with ISO 15378 compliance, mid-scale regional fabricators with decoration expertise, and volume-driven commodity suppliers. Dominant competitive moves include backward integration into resin compounding to secure circular feedstock supply and strategic partnerships with direct-to-consumer brands for refill program architecture.
Within the premium specialist tier, HCP Packaging and Albéa Group exemplify geographic anchoring strategies that align production capacity with regional regulatory requirements. AptarGroup occupies a position emphasizing precision dispensing closure systems. These three names represent distinct archetypes: Asian manufacturing footprint leverage, European nearshoring with recycled content integration, and dosing technology differentiation respectively.
| Leading Market Players |
|---|
| HCP Packaging |
| AptarGroup |
| Albéa Group |
| Berry Global |
| Quadpack |
| Berlin Packaging |
| IntraPac International |
| Arminak & Associates |
| Park Tech A/S |
| Others |
Value Chain & Pricing Dynamics
Chinese and South Korean injection molding clusters for premium stick containers concentrate upstream capacity, anchoring margin capture downstream with brand owners and direct-to-consumer retailers who command pricing power through refill program architectures and subscription bundling.
Pricing Analysis
Long-term offtake agreements dominate procurement between German cosmetic houses and Albéa Group's European tube lines, while spot purchasing persists for commodity polyethylene resin streams. Three-tier pricing structure across premium ISO 15378-certified pharmaceutical-grade, standard cosmetic-grade, and economy mass-market tiers separates margin pools. Cost compression in virgin polypropylene feedstocks is intensifying because of naphtha price volatility linked to energy market swings. Direct-to-consumer beauty brands exhibit lowest price sensitivity due to subscription revenue visibility, whereas mass-market retailers face acute pressure from private-label substitution.
Supply Chain Analysis
Contract manufacturing concentrates with HCP Packaging's Zhejiang and Jiangsu province facilities, Albéa Group's Lombardy tube lines, and AptarGroup's precision closure foundries across France and Germany. Raw material flows draw from Saudi and Qatari polyethylene feedstock, South Korean polypropylene resin streams, and Italian glass furnace capacity. Single-source vulnerability runs through Chinese port congestion exposure for premium stick container exports. Distribution runs through direct-to-consumer fulfillment centers in California and New York, pharmacy wholesale networks in Germany, and luxury retail consolidators in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lip care packaging market sits in early-cycle expansion as EU refillable format mandates pull investment into redesigned primary container systems ahead of enforcement timelines.
For Market Incumbents: Insulate margin pools by accelerating backward integration into post-consumer recycled resin compounding to secure circular feedstock supply against virgin price volatility. Deepen ISO 15378 certification coverage across Italian and German production lines to capture pharmacy-channel price premiums before competitor qualification timelines compress. Priority rests on controlling closure mechanism technology as precision dispensing becomes the differentiation layer. For New Entrants and Emerging Players: Pursue white-space opportunity in bio-based polymer tube formats for sustainability-positioned direct-to-consumer brands in California and New York where PCR mandates create procurement urgency. Target Northern Italian packaging machinery specialists for acquisition or partnership to establish European nearshoring credibility with German cosmetic houses. Lead with refill program architecture as a service offering rather than transactional container sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade primary packaging as ISO 15378 compliance stretches supplier qualification timelines and equipment replacement cycles. The 5-10 year viability window favors converters holding dual cosmetic-pharmaceutical certifications with integrated PCR capabilities. Acquisition targets should profile as mid-scale Italian or German tube specialists with underutilized capacity and established brand-owner relationships. Monitor EU Packaging and Packaging Waste Regulation enforcement acceleration as the inflection signal for refillable format demand pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Refill Program Architecture Development | Converts one-time packaging sales into recurring revenue streams for direct-to-consumer brands. |
| Post-Consumer Recycled Content Integration | Aligns converter capacity with California and New York state-level plastic ban compliance timelines. |
| ISO 15378 Certification Investment | Unlocks pharmacy-channel price premiums for medicated lip treatment formats in Germany. |
| Mono-Material Tube Redesign | Eliminates mechanical recycling exclusion risk under EU Packaging and Packaging Waste Regulation. |
| Precision Dispensing Closure Partnership | Collapses former separation between tube body and closure suppliers into single-source relationships. |
Study Parameters
Operator-level perspectives from packaging procurement managers at cosmetic houses, converter plant directors in Zhejiang and Lombardy, pharmacy retail category buyers in Germany, and direct-to-consumer brand supply chain heads anchored the qualitative base. Primary interview data triangulated against secondary sources including FDA cosmetic labeling guidance, EU Packaging and Packaging Waste Regulation impact assessments, and customs trade data for polyethylene and polypropylene resin flows. Bottom-up capacity modeling across stick container, tube, and jar production lines converged with top-down demand estimation from retail audit data and subscription platform disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning packaging type, material substrate, closure mechanism, and end-user channel. Pharmaceutical-grade versus cosmetic-grade certification tiers, refillable versus single-use format adoption curves, and regional regulatory cluster variations shaped the analytical framework. CAGRs derived from elasticity-adjusted demand curves incorporating substitution effects between stick and tube formats, with specific inputs from post-consumer recycled content mandate implementation schedules and ISO 15378 qualification timeline benchmarks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian contract manufacturers into European nearshoring capacity or accelerated EU enforcement timelines would shift outcomes. Cross-checking against ECHA substance restriction sunset date announcements and California Department of Resources Recycling and Recovery rulemaking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market