
 Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market | 2026-2036
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market Analysis
India is rewriting regional supply dynamics for authentication packaging as domestic capacity for holographic labels and RFID-integrated blister packs expands rapidly. CCL Industries leverages vertical integration across substrate production and conversion to sustain margin control in pharmaceutical-grade labels. SICPA Holding SA anchors security ink supply for tax stamp and brand protection programs across emerging markets. Avery Dennison Corporation differentiates through RFID inlay manufacturing scale, occupying a critical node in pharmaceutical cold-chain authentication.
Anti-counterfeit pharmaceuticals and cosmetics packaging encompasses multi-layered security systems—incorporating optically variable devices, serialized two-dimensional barcodes, and substrate-level taggants—engineered to verify product authenticity, prevent diversion, and enable supply-chain traceability from manufacture to point of dispensation. The primary commercial purpose centers on protecting brand equity, ensuring patient safety, and satisfying regulatory compliance for unit-level serialization. Holograms and RFID Tags command premium positioning due to their dual function as consumer-facing authentication tools and backend track-and-trace enablers, though QR Codes and digital watermarking gain traction among cosmetic brands seeking smartphone-accessible verification without hardware infrastructure investment. Flexible Packaging and Blister Packs concentrate volume demand as pharmaceutical companies prioritize patient-compliant dosing formats with integrated tamper evidence.
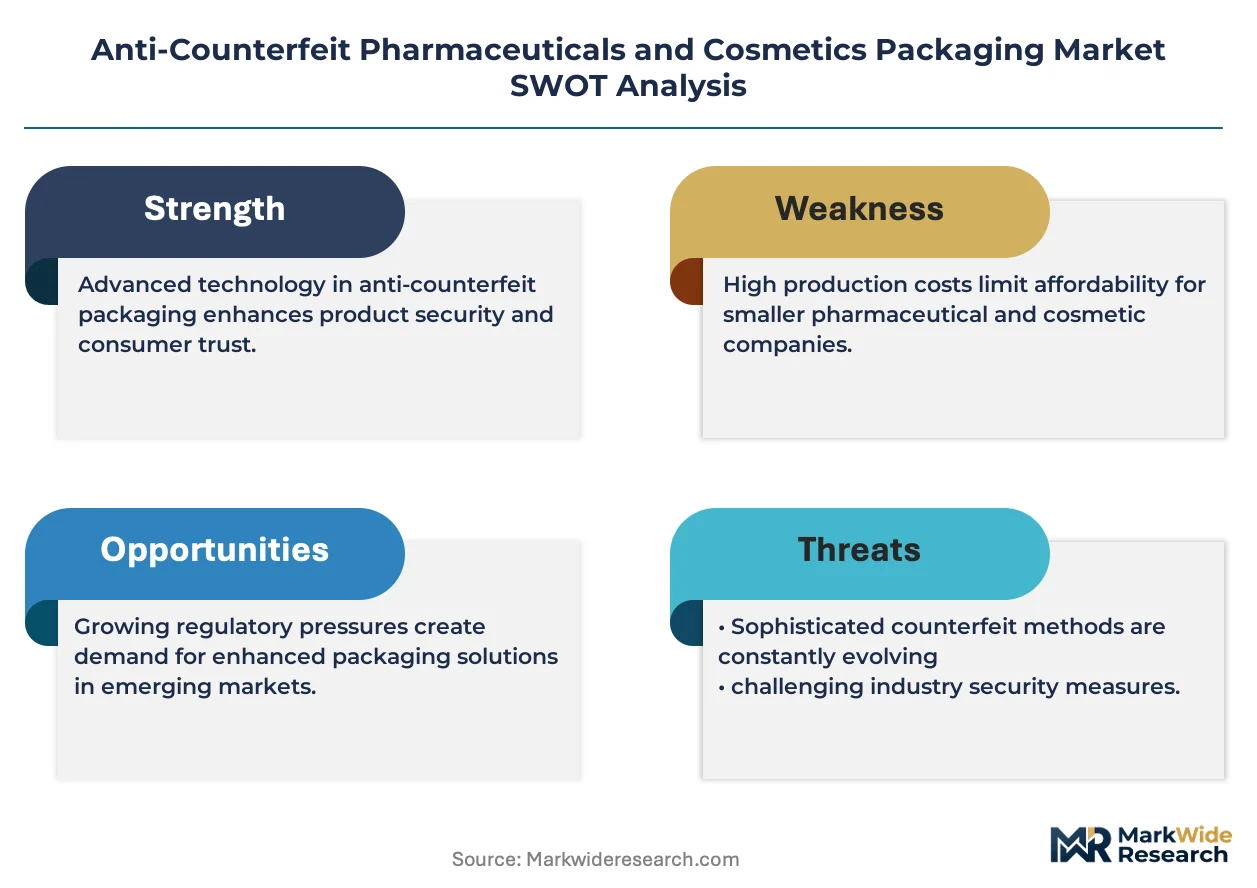
FDA's Drug Supply Chain Security Act and EMA's Falsified Medicines Directive collectively mandate unit-level serialization and verification architecture, forcing packaging converters to embed traceability layers at the primary package level. India's CDSCO export authentication rules and China's NMPA vaccine tracking requirements extend regulatory pressure into contract manufacturing networks, compelling wholesalers and contract manufacturers to upgrade packaging specifications. Stakeholders must monitor divergence between regional serialization standards and assess whether technology platforms can bridge incompatible national verification databases without redundant capital deployment.
Market Dynamics
Serialization mandates from FDA and EMA are compressing packaging procurement timelines, forcing pharmaceutical converters to embed track-and-trace layers at the primary package level rather than applying authentication retroactively.
Growth Catalysts
- EMA Falsified Medicines Directive:European wholesalers must verify serialized medicines at dispensing points, creating pull for tamper-evident blister packs and authentication labels across EU member states.
- Holographic substrate demand:Cosmetic brands in premium fragrance and skincare segments are specifying optically variable devices to combat gray-market diversion and protect brand equity at retail.
- India CDSCO export rules:Track-and-trace requirements for medicines shipped abroad are redirecting supplier investment toward South Asian contract manufacturing hubs with integrated authentication capabilities.
Market Restraints
- Security ink supply concentration:Specialty pigment and taggant production clusters in Switzerland and limited alternative sources create input vulnerability for tax stamp and pharmaceutical authentication programs.
- RFID inlay cost structure:Chip shortages and noble metal conductor pricing volatility compress margins for cold-chain pharmaceutical labels requiring temperature-logging functionality.
- Serialization standard fragmentation:Incompatible national verification databases between US, EU, and China force redundant capital deployment without interoperability guarantees.
Strategic Opportunities
- Smartphone-accessible verification:QR codes and digital watermarking penetration in cosmetics remains underdeveloped relative to hardware-dependent alternatives, opening white space for app-integrated authentication.
- China NMPA vaccine tracking:Expanded biologics traceability requirements create procurement pull for RFID-integrated vial labels and temperature indicators in domestic cold-chain networks.
- Blockchain-physical convergence:Serialized barcodes paired with distributed ledger verification enable patient-facing provenance confirmation without proprietary hardware infrastructure.
Industry Challenges
- Track-and-trace integration complexity:Legacy enterprise resource planning systems at mid-sized pharmaceutical contract manufacturers require costly middleware development to interface with national verification databases.
- Authentication chemist skill scarcity:Formulation expertise for covert taggants and substrate-level security features concentrates among aging specialists without sufficient training pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market |
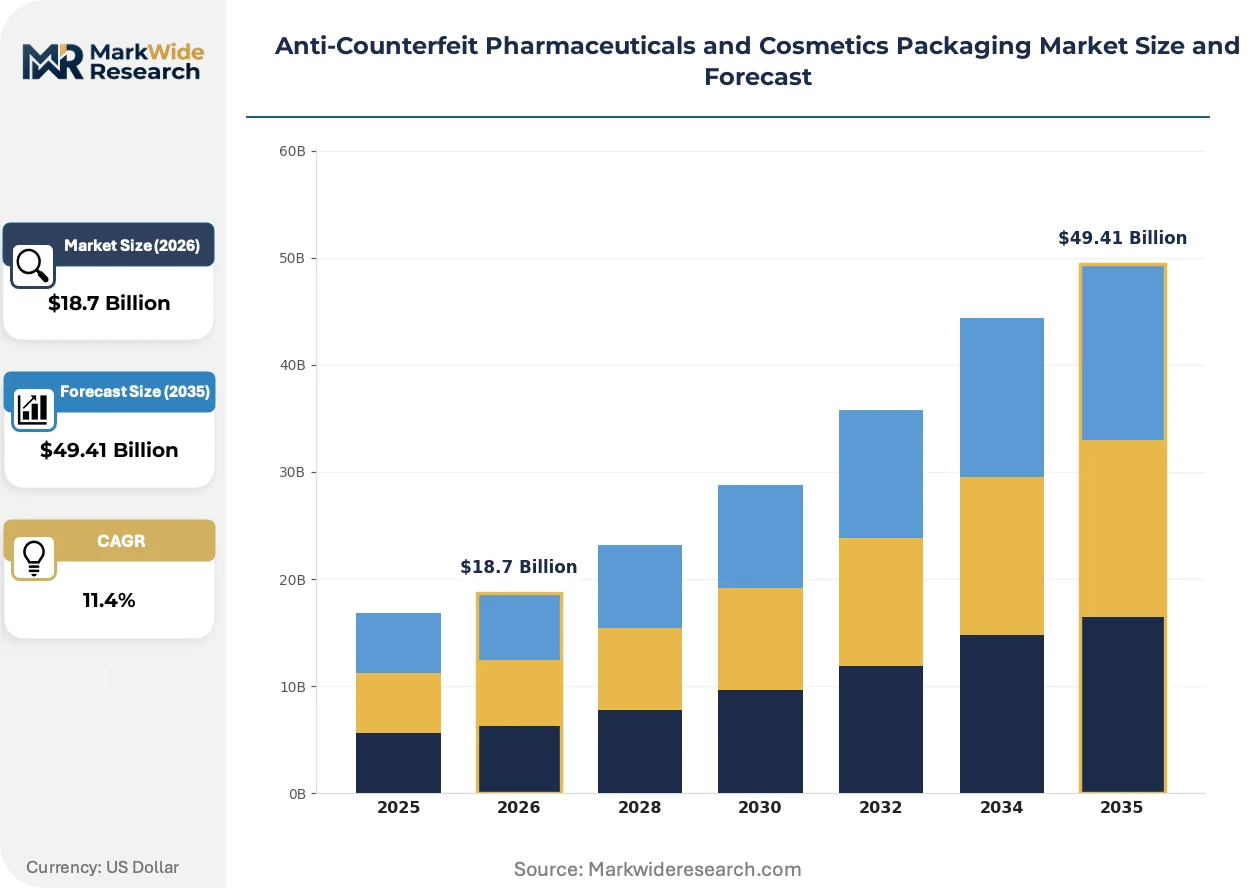
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Tamper-Proof Caps, Holograms, RFID Tags Technology: Barcodes, QR Codes, Digital Watermarking, Nano-Technology End User: Pharmaceutical Companies, Cosmetic Brands, Contract Manufacturers, Wholesalers Packaging Type: Flexible Packaging, Rigid Containers, Blister Packs, Bottles |
| Companies Covered | CCL Industries Inc., SICPA Holding SA, Avery Dennison Corporation, 3M Company, Zebra Technologies Corp., AlpVision SA, SML Group, Authentix, Impinj Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market Emerging Trajectories
Authentication packaging is pivoting from overt consumer-facing features toward invisible, machine-readable layers that integrate with supply-chain software architectures and patient verification apps.
Blockchain-anchored serialization is digitizing provenance verification for high-value biologics and oncology medicines. Pharmaceutical manufacturers in North American and European markets are piloting distributed ledger integration with existing barcode infrastructure. This convergence is digitizing trust architecture between manufacturers, wholesalers, and dispensing pharmacies without requiring hardware replacement cycles.
REACH substance restrictions are forcing reformulation of solvent-based security inks and adhesive systems used in pharmaceutical labels. European converters are accelerating migration to UV-curable and water-based alternatives to maintain compliance. Flexible packaging and blister pack segments face the steepest adaptation timelines given laminate compatibility requirements.
Direct-to-pharmacy procurement models are compressing distributor intermediation in authentication packaging supply. Large retail pharmacy chains in the United States and Germany are specifying pack-level serialization requirements directly with contract manufacturers. This disintermediation is most visible in generic medicine segments where margin pressure drives volume consolidation toward vertically integrated packaging suppliers.
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market Segmentation
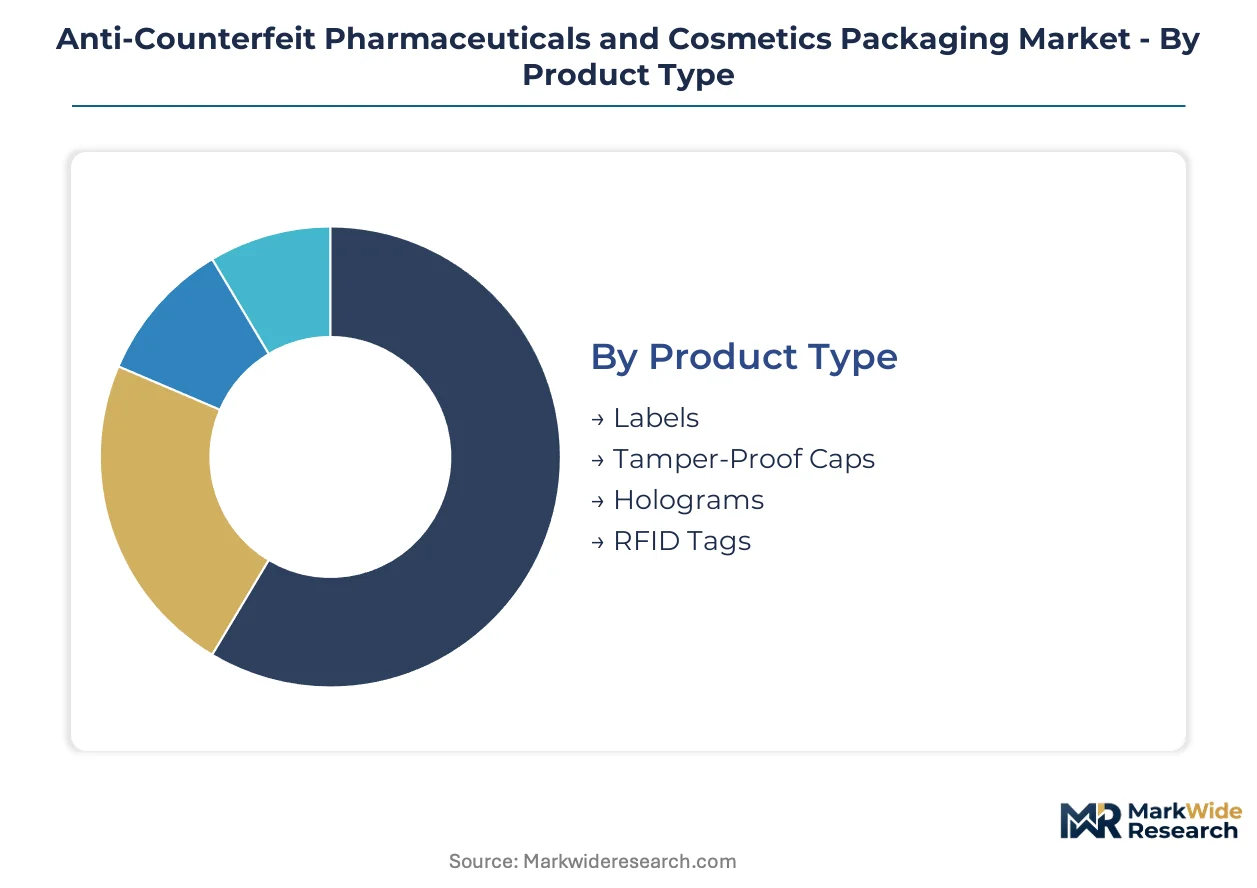
Segmentation in anti-counterfeit packaging reveals how authentication requirements diverge across regulatory environments, product formats, and supply-chain positions. Each dimension carries distinct technical specifications and procurement patterns that shape supplier strategy.
Product Type:
Pharmaceutical and cosmetic brands deploy authentication features across a spectrum from passive visual verification to active electronic tracking, with selection driven by unit economics and regulatory stringency.
- Labels:Pressure-sensitive constructions integrate serialized barcodes, holographic overlays, and covert taggants for primary package authentication. Demand concentrates among generic pharmaceutical manufacturers in India and Eastern Europe where CDSCO and EMA serialization mandates force line-speed integration at converting facilities.
- RFID Tags:Inlay-based designs embed UHF or NFC chips for automated inventory verification and cold-chain temperature logging. Hospital and retail pharmacy chains in Germany and the United States specify these for high-value biologics where automated dispensing accuracy outweighs per-unit cost premiums.
- Holograms:Optically variable devices combat gray-market diversion in premium cosmetics through consumer-facing visual authentication.
- Tamper-Proof Caps:Break-ring and induction-seal designs provide first-open evidence for over-the-counter medicines and personal care products.
The dominant share belongs to Labels, while RFID Tags are closing the gap fastest as automated dispensing networks expand.
Technology:
Verification methods span hardware-dependent infrastructure and smartphone-accessible platforms, with cost structure and interoperability determining adoption trajectories.
- QR Codes:Two-dimensional matrix patterns enable patient-facing authentication through standard smartphone cameras without dedicated hardware. Cosmetic brands in France and South Korea favor these for direct-to-consumer verification apps that bypass distributor authentication infrastructure.
- Barcodes:Linear and DataMatrix formats anchor pharmaceutical serialization under FDA DSCSA and EMA FMD mandates, requiring line-level printing integration at contract manufacturing sites. Legacy infrastructure and regulatory specificity sustain volume despite limited consumer engagement.
- Digital Watermarking:Invisible embedded patterns resist replication while enabling smartphone detection, gaining traction in luxury cosmetics where aesthetic package design precludes overt security features.
- Nano-Technology:Substrate-level taggants and molecular markers provide forensic-level verification for high-risk product categories.
Barcodes command installed-base dominance, though QR Codes are climbing the fastest as cosmetic brands prioritize consumer-accessible verification.
End User:
Procurement authority varies across the value chain, with regulatory liability shaping whether authentication specifications originate at brand, manufacturer, or distributor level.
- Pharmaceutical Companies:Originators and generic manufacturers specify pack-level serialization for regulatory compliance and brand protection, embedding authentication at primary package design stage. Large-volume producers in Switzerland and the United States negotiate direct supply agreements with substrate converters to secure capacity and customize security feature portfolios.
- Contract Manufacturers:Packaging service providers absorb capital burden for serialization infrastructure to serve multiple brand clients, with equipment utilization rates determining competitive positioning. CDSCO export requirements have redirected investment toward Indian contract manufacturing hubs with integrated track-and-trace capabilities.
- Cosmetic Brands:Premium fragrance and skincare marketers specify holographic and digital watermarking features to combat parallel import and protect retail price integrity.
- Wholesalers:Distribution intermediaries under EMA FMD verification obligations drive demand for scan-capable authentication at secondary packaging level.
Pharmaceutical Companies retain specification authority, yet Contract Manufacturers are gaining share fastest as outsourcing consolidates authentication investment.
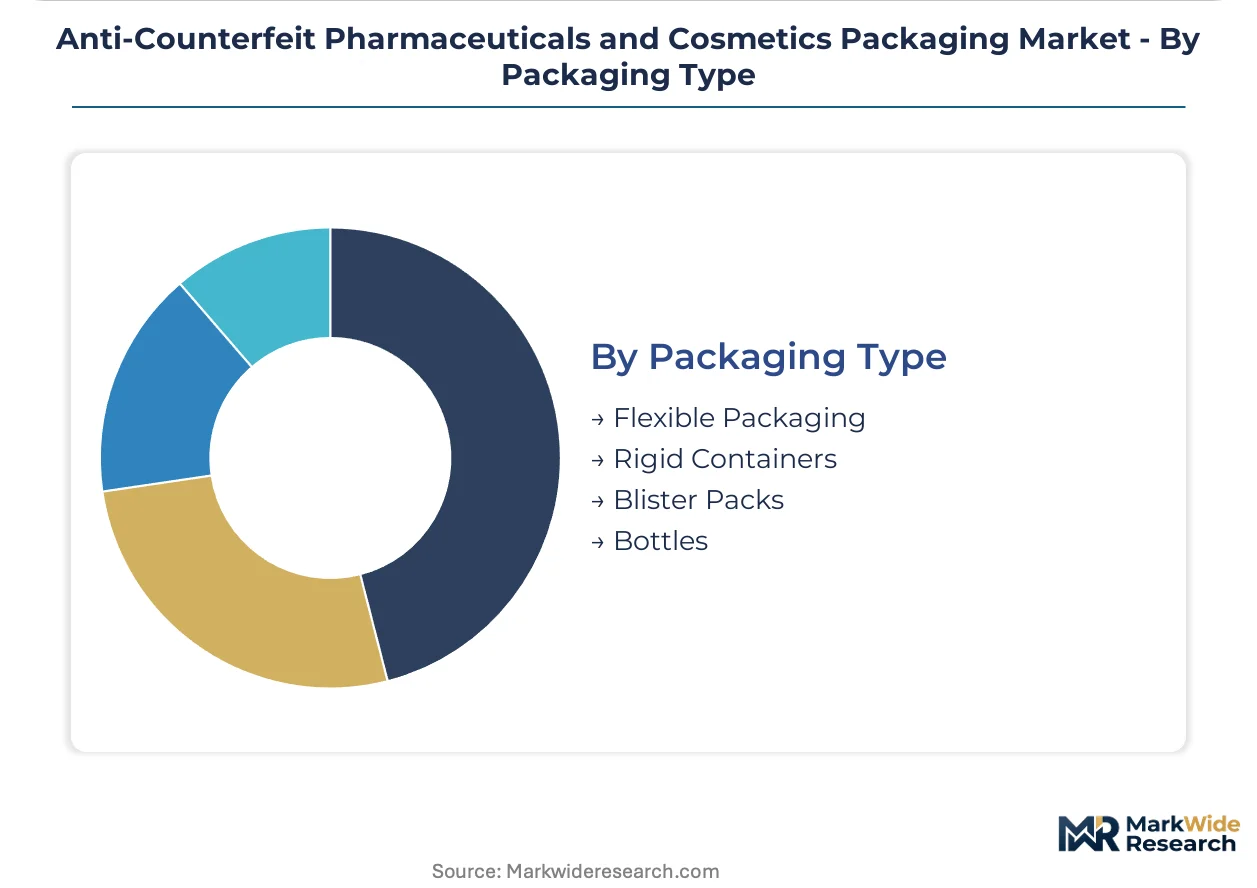
Packaging Type:
Format selection determines where authentication layers integrate—at substrate, conversion, or filling stage—and influences tamper-evidence mechanisms.
- Blister Packs:Thermoformed cavity designs with lidding foil integrate serialization at sealing station, enabling unit-dose verification for solid oral dosage forms. European generic manufacturers specify tamper-evident lidding with holographic or serialized features to satisfy FMD wholesale verification requirements.
- Flexible Packaging:Pouch and sachet formats for single-use cosmetics and OTC liquids embed authentication through printed laminate layers or applied labels. High-speed form-fill-seal operations in China and India favor cost-optimized QR code integration over hardware-intensive alternatives.
- Bottles:Rigid containers for liquid pharmaceuticals and cosmetics combine closure-based tamper evidence with label or shrink-sleeve authentication.
- Rigid Containers:Jar and canister formats for premium skincare accommodate multi-layer security through in-mold labels and direct decoration.
Blister Packs hold the largest position, while Flexible Packaging is expanding most quickly as single-use format demand accelerates in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates anchor procurement patterns in the United States, while EMA verification requirements reshape European wholesale networks. India's CDSCO export rules and China's NMPA vaccine tracking extend regulatory pressure into contract manufacturing hubs across Asia.
United States
Pharmaceutical manufacturers accelerate track-and-trace infrastructure deployment ahead of DSCSA enforcement deadlines. FDA verification architecture requires unit-level serialization at primary package level. New Jersey and Pennsylvania pharmaceutical corridors concentrate label converting capacity for cold-chain biologics authentication.
Germany
Hospital pharmacy chains specify RFID-integrated vial labels for automated dispensing accuracy in high-value oncology medicines. EMA Falsified Medicines Directive verification obligations compel wholesale distributors to upgrade scan-capable secondary packaging. Baden-Württemberg precision manufacturing clusters supply serialization equipment to domestic and export markets.
India
Contract manufacturers absorb capital burden for integrated authentication capabilities to serve export markets under tightened CDSCO track-and-trace requirements. DGFT export documentation rules redirect supplier investment toward Gujarat and Maharashtra pharmaceutical hubs. Hyderabad and Mumbai corridors expand holographic label and RFID blister pack production for regulated markets.
Switzerland
Originator pharmaceutical manufacturers negotiate direct substrate supply agreements to secure security ink capacity for tax stamp and brand protection programs. Swissmedic serialization requirements align with EMA standards while preserving distinct national verification database architecture. Basel pharmaceutical cluster anchors security feature formulation expertise for forensic-level taggants.
China
Domestic vaccine manufacturers procure RFID-integrated labels and temperature indicators under expanded NMPA biologics traceability requirements. MIIT industrial standards push serialization integration at form-fill-seal operations for single-use cosmetic pouches. Yangtze River Delta flexible packaging converters optimize QR code printing for cost-sensitive OTC export segments.
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market Vendor Landscape
Capability concentration sits with security ink and substrate specialists; scale advantage sits with diversified packaging converters with pharmaceutical-grade certification. The supplier base stratifies across three tiers: integrated multinational converters controlling substrate-to-label production, security technology licensors specializing in authentication chemistry, and regional contract manufacturers absorbing serialization capital burden for multiple brand clients. Competitive positioning hardens through backward integration into holographic film extrusion and strategic partnerships with national verification database operators.
Within the integrated converter tier, CCL Industries Inc. exemplifies margin control through captive substrate production and pharmaceutical label conversion. SICPA Holding SA anchors security ink supply for tax stamp and pharmaceutical authentication programs across emerging markets. Avery Dennison Corporation occupies a critical position in RFID inlay manufacturing scale for cold-chain pharmaceutical networks. These three entities represent distinct archetypes: vertical integration, security chemistry specialization, and electronic tracking infrastructure scale.
| Leading Market Players |
|---|
| CCL Industries Inc. |
| SICPA Holding SA |
| Avery Dennison Corporation |
| 3M Company |
| Zebra Technologies Corp. |
| AlpVision SA |
| SML Group |
| Authentix |
| Impinj Inc. |
| Others |
Supply Flow & Price Mechanics
Swiss security ink production concentration anchors margin capture for authentication chemistry suppliers serving pharmaceutical tax stamp and brand protection programs worldwide. Specialty pigment and taggant formulation expertise clusters around Basel-based chemical specialists, creating pricing power divergence between substrate-integrated security features and commodity label converting.
Pricing Analysis
Geographic price spreads widen between European-origin holographic substrates and Asian-manufactured QR-integrated flexible packaging. Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled cold-chain labels from serialized barcode constructions and basic tamper-evident closures. Cost compression in standard-tier barcode labels intensifies as Indian and Chinese converters add serialization capacity for CDSCO and NMPA compliance. Generic pharmaceutical manufacturers exhibit highest price sensitivity, while originator biologics producers absorb premium for temperature-logging authentication.
Supply Chain Analysis
Export control regimes on semiconductor-grade RFID chips limit inlay availability for pharmaceutical cold-chain applications, forcing allocation decisions among converter tiers. Supply concentration centers on Switzerland for security chemistry, China for flexible packaging substrates, and India for serialized label converting. Noble metal conductor pricing volatility and specialty adhesive feedstock scarcity create input vulnerability. Distribution runs through direct-to-pharmacy procurement channels that disintermediate traditional wholesale packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat sustained by regulatory entrenchment—serialization mandates create switching costs that lock pharmaceutical manufacturers into verified supplier relationships through compliance continuity requirements.
For Market Incumbents: Harden backward integration into holographic film extrusion to secure substrate supply against emerging Asian converters. Expand RFID inlay manufacturing scale in Germany and the United States to capture hospital pharmacy automation procurement. Certification investment for FDA and EMA pharmaceutical-grade production lines reinforces barrier against unqualified entrants.
For New Entrants and Emerging Players: Build out smartphone-accessible verification platforms targeting cosmetic brands in France and South Korea where digital watermarking penetration remains underdeveloped. Smartphone-accessible QR authentication in premium skincare segments offers the most penetrable white space. Partner with national verification database operators to bypass hardware infrastructure requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward security chemistry specialists with captive taggant formulation expertise and established pharmaceutical customer relationships. Long-term viability over the coming decade rests on regulatory compliance continuity rather than cyclical demand. Watch for CDSCO enforcement intensity in Indian export markets as inflection signal for contract manufacturing hub consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | CCL Industries controls holographic film supply through captive extrusion capacity in North American pharmaceutical corridors. |
| RFID Inlay Manufacturing Scale-Up | Avery Dennison anchors cold-chain authentication through UHF chip integration at pharmaceutical-grade production facilities. |
| Security Ink Formulation Partnership | SICPA Holding SA secures tax stamp programs through Swiss-based specialty pigment chemistry and government contract relationships. |
| Blockchain-Physical Convergence Platform | Serialized barcode integration with distributed ledger verification enables patient-facing provenance without proprietary hardware replacement. |
| Direct-to-Pharmacy Procurement Channel | Large retail chains in Germany and the United States specify pack-level serialization directly with contract manufacturers, bypassing distributor intermediation. |
Methodological Framework
Cross-validation between primary interviews with packaging converters and secondary regulatory filing analysis anchors the qualitative findings. Conversations with pharmaceutical serialization directors, contract manufacturing operations heads, cosmetic brand protection managers, and security ink formulation chemists informed demand-side validation. FDA DSCSA guidance documents, EMA FMD implementation reports, CDSCO export circulars, and NMPA biologics tracking standards provided regulatory trajectory inputs. Bottom-up volume modeling triangulated against top-down pharmaceutical production forecasts.
Calibration against historical serialization infrastructure deployment rates validated growth trajectory assumptions across the analysis window. Segmentation modeling incorporated technology type, packaging format, end-user procurement authority, and regional regulatory cluster dimensions. CAGRs derived from line-speed integration timelines at contract manufacturing sites and authentication feature penetration curves in cosmetic segments. Cold-chain expansion in biologics and vaccine distribution networks supplied demand-side forecast inputs.
Stress conditions across RFID chip availability, security ink feedstock pricing, and serialization mandate enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance continuity and technology substitution thresholds. Material shifts in FDA verification architecture or EMA database interoperability standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
North America Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Bottles Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Hair Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Glass Cosmetic Bottle Market