
 PP Container Liner Market | 2026-2036
PP Container Liner Market Size, Share, and Industry Trends Forecast 2026-2036
PP Container Liner Market Outlook
A capital-intensity divergence between integrated resin producers and converted liner specialists is unwinding competitive stability in the PP container liner sector. Berry Global Inc. leverages captive polypropylene supply chains across North American manufacturing corridors. Thrace Group anchors southeastern European production with dedicated extrusion and weaving assets. Eceplast competes through specialized hazardous-material certification programs that command premium positioning.
PP container liners are woven polypropylene fabric enclosures engineered to line standard shipping containers, typically constructed from coated or uncoated PP tape with basis weights ranging from 140 to 250 gsm to prevent cargo contamination and enable bulk discharge. Their primary industrial purpose centers on transforming general-purpose ISO containers into single-commodity transport vessels for powders, granules, and flowable solids. Bulk liners within the product-type dimension dominate volume throughput in chemical transport applications where contamination control commands structural priority. FIBCs represent the fastest-expanding category as food manufacturers adopt one-ton flexible intermediate bulk containers for sugar, flour, and grain handling. Flexible containers occupy a mature margin pool concentrated among logistics providers with long-term vessel-charter agreements.
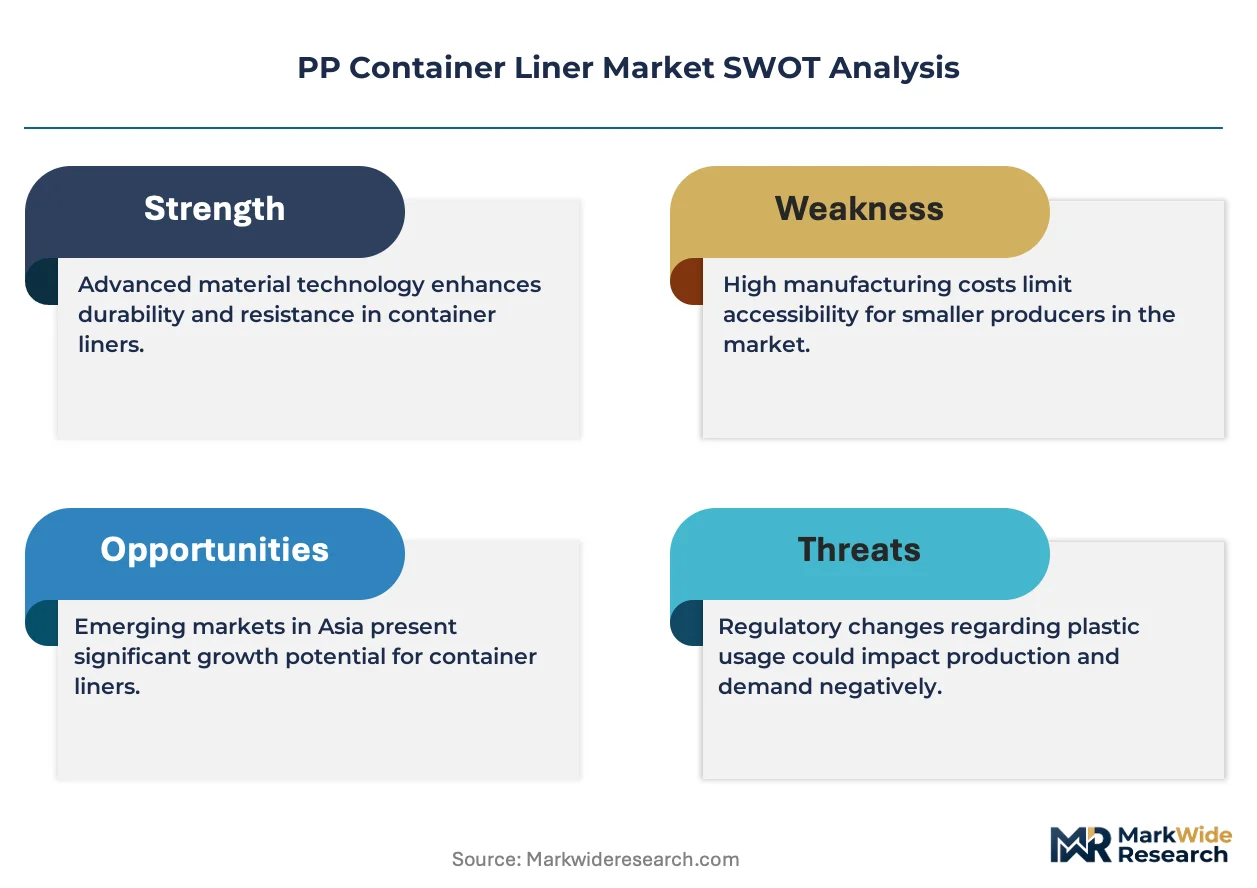
REACH in Europe mandates migration testing and substance registration for liners contacting food and chemical cargoes, while FDA compliance requirements in the United States govern direct-contact food applications with specific extractable limits. China's GB standards and SAMR oversight enforce dimensional tolerances and load-rating certifications for domestic and export-bound liner production. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in the European Union and corresponding state-level packaging regulations in California and New York that will reshape material-recovery obligations and liner-design specifications.
Market Dynamics
REACH migration testing mandates and FDA direct-contact rules are compressing supplier qualification timelines while resin supply concentration in Middle Eastern and Chinese petrochemical corridors creates procurement bottlenecks for converter specialists lacking backward integration.
Growth Catalysts
- REACH compliance expansion:German and Dutch chemical handlers now require certified bulk liners for hazardous powder transport, forcing specification upgrades across European supply chains.
- FIBC food adoption:Sugar millers and grain processors in China's coastal manufacturing clusters are replacing rigid IBCs with one-ton flexible containers to reduce cleaning costs and cross-contamination risk.
- Resin supply chain proximity:Polypropylene production concentration in Ningbo and Shanghai enables just-in-time liner fabrication for export-bound chemical shipments.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and PDH unit economics in Middle Eastern supply basins transmit directly to PP tape pricing.
- Weaving equipment concentration:Circular loom manufacturing clusters in Turkey and India create single-source dependencies for European converter specialists.
- Woven fabric substitution limits:PE-based alternatives lack the tensile strength for abrasive mineral loads, locking liners into PP resin exposure.
Strategic Opportunities
- Extended Producer Responsibility tailwinds:EU packaging waste directives will mandate recycled content thresholds, rewarding converters with post-industrial scrap collection networks.
- Hazardous material certification premiums:UN-certified liners for lithium carbonate and battery precursor powders command price multiples over standard agricultural grades.
- Coastal manufacturing integration:Liner production co-location with FIBC sewing operations in Vietnam and Indonesia reduces logistics cost for Australian mineral exporters.
Industry Challenges
- Multistandard compliance complexity:Simultaneous FDA extractable limits, REACH substance registration, and GB dimensional tolerances extend product development cycles.
- Extrusion line capex intensity:Tape stretching and coating equipment requires seven-figure capital commitments that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PP Container Liner Market |
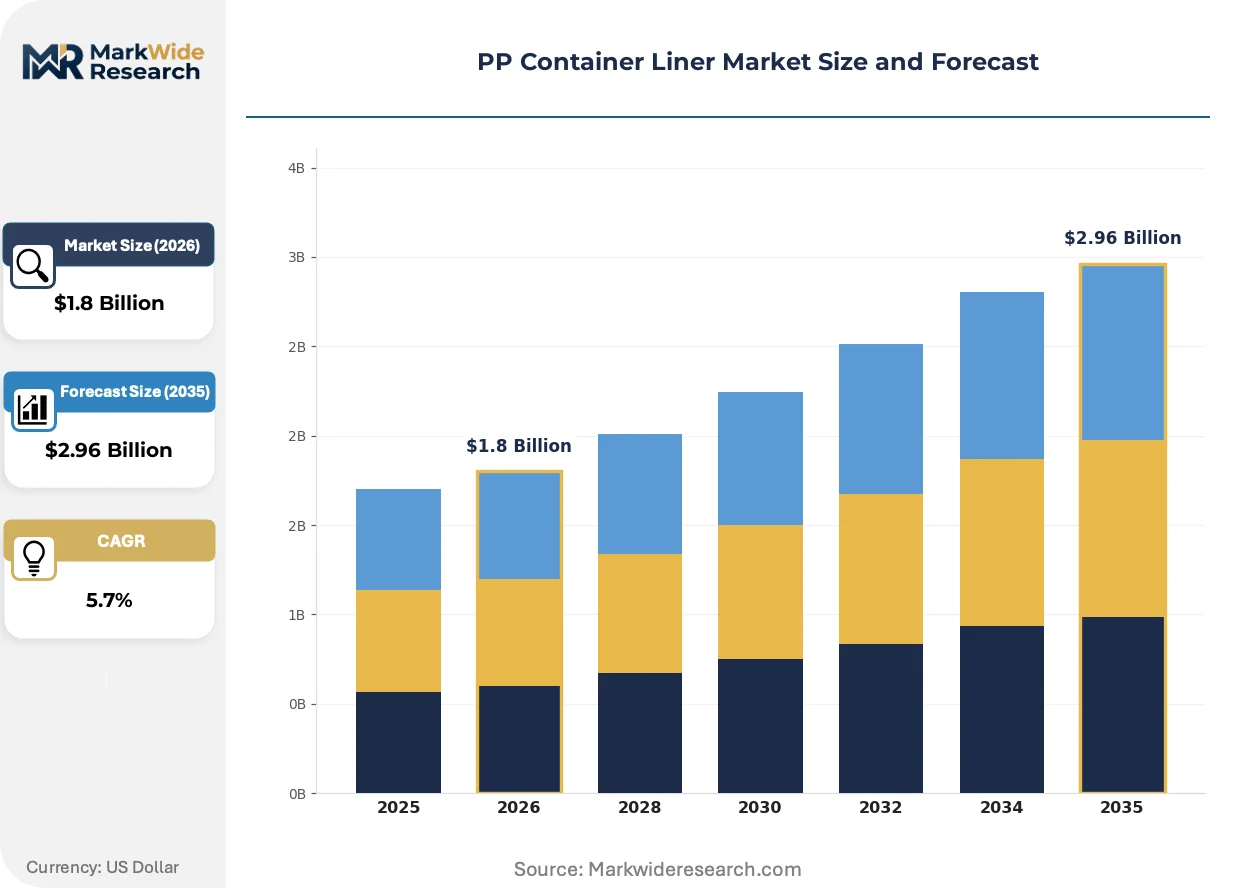
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Liners, FIBCs, Silo Bags, Flexible Containers Application: Food Packaging, Chemical Transport, Agricultural Products, Hazardous Materials End User: Logistics Providers, Food Manufacturers, Chemical Companies, Agricultural Firms Distribution Channel: Online Sales, Direct Sales, Retail Outlets, Industrial Supply Stores |
| Companies Covered | LC Packaging, Berry Global Inc., Taihua Group, Sinopack, Caretex, Greif Flexible Products & Services, Thrace Group, Eceplast, Linertech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PP Container Liner Market Strategic Shifts
Active barrier coatings and digital tracking integration are redefining liner performance specifications while regulatory pressure on recyclability accelerates material formulation changes.
Multilayer coextruded barrier films with ethylene vinyl alcohol cores are fragmenting the traditional coated-PP tape segment. Pharmaceutical ingredient shippers in Switzerland and Singapore are specifying oxygen transmission rates below 0.5 cc/m²/day for probiotic and enzyme powders. This performance tier is compressing margins for commodity weavers lacking lamination capabilities.
REACH Annex XVII restrictions on perfluorinated compounds are banning legacy grease-resistant treatments used in food-contact liners. ECHA substance evaluation is forcing reformulation toward silicone-based alternatives with comparable moisture barrier properties. German and French packaging converters are accelerating qualification timelines to maintain EU market access.
Buyers are consolidating liner procurement with container leasing operators rather than maintaining separate vendor relationships. Chemical distributors in the Port of Rotterdam and Singapore's Jurong Island are bundling liner supply with tank and box container rentals. This channel compression is displacing direct sales relationships between weavers and end-users.
PP Container Liner Market Segmentation
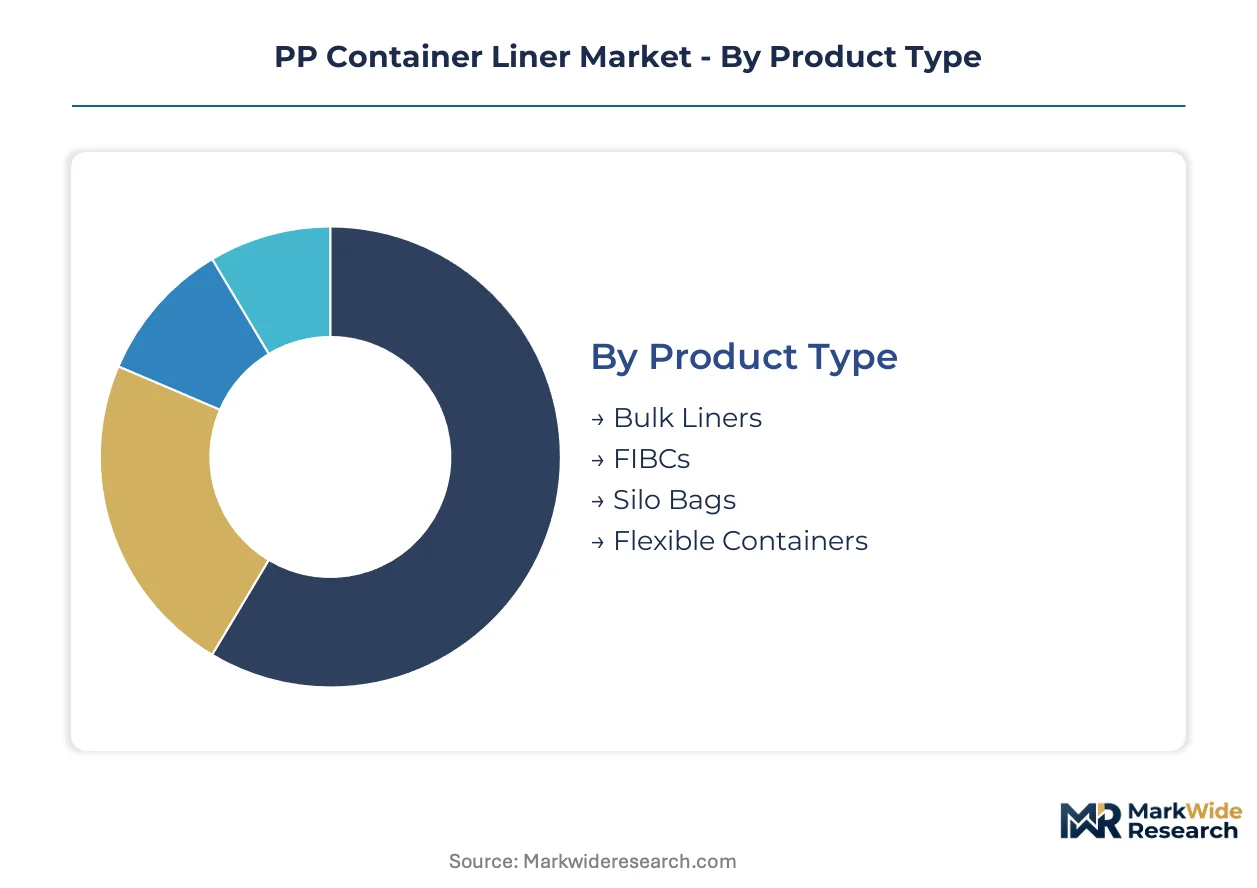
Segmentation in the PP container liner market exposes critical fault lines between commodity-grade supply and certified specialty production. Product-type distinctions determine resin specification and barrier performance, while application-driven requirements separate hazardous-material compliance from standard food-contact tiers.
Product Type:
Substitution pressure from multilayer PE films and rigid IBC systems concentrates most intensely on commodity woven segments lacking barrier certification.
- Bulk Liners:Woven polypropylene enclosures with 140-250 gsm basis weights line ISO containers for powder and granule transport. Chemical handlers in Germany and the Netherlands specify these for REACH-compliant hazardous material movements under tightened migration testing mandates.
- FIBCs:One-ton flexible intermediate bulk containers with four-loop or tubular construction replace rigid totes in sugar milling and grain processing. China's coastal manufacturing clusters drive adoption as food manufacturers prioritize cleaning cost reduction and cross-contamination prevention.
- Silo Bags:Large-diameter woven tubes store grain and forage crops at harvest points. Agricultural cooperatives in Argentina and Ukraine deploy these for temporary field-side storage where permanent silo infrastructure is uneconomical.
- Flexible Containers:Reusable liner systems with integrated discharge spouts serve logistics providers holding long-term vessel charter agreements. Port operators in Singapore and Rotterdam bundle these with container leasing contracts.
Bulk liners retain volume leadership; FIBCs hold the steepest expansion curve.
Application:
Cost tier stratification separates premium-certified grades from standard agricultural specifications across end-use categories.
- Food Packaging:FDA-extractable-compliant and EU food-contact-certified liners handle flour, sugar, and grain shipments. Swiss and Singaporean pharmaceutical ingredient shippers now specify oxygen transmission rates below 0.5 cc/m²/day for probiotic powders.
- Chemical Transport:REACH-registered liners with substance migration documentation serve German and Dutch chemical distributors. UN-certified variants for lithium carbonate and battery precursor powders command substantial price premiums over standard grades.
- Agricultural Products:Uncoated woven liners with basic contamination protection move grain, seed, and fertilizer through seasonal harvest cycles. Ukrainian and Brazilian farm cooperatives dominate procurement volume.
- Hazardous Materials:ECHA Annex XVII-compliant liners exclude perfluorinated compounds in favor of silicone-based grease resistance. German and French converters accelerate qualification timelines to maintain EU market access.
Chemical transport commands the highest certification burden; food packaging is gaining share fastest.
End User:
Customer-type concentration determines channel strategy, with integrated logistics operators consolidating procurement away from direct weaver relationships.
- Logistics Providers:Container leasing operators in Rotterdam and Singapore's Jurong Island bundle liner supply with tank and box rentals. This channel compression displaces direct sales between weavers and end-users.
- Food Manufacturers:Sugar millers and grain processors in China's coastal clusters replace rigid IBCs with FIBCs. Ningbo and Shanghai resin proximity enables just-in-time fabrication for export-bound shipments.
- Chemical Companies:German and Dutch handlers require certified bulk liners for hazardous powder transport under expanded REACH compliance. Specification upgrades cascade through European supply chains.
- Agricultural Firms:Seasonal demand patterns from harvest cycles in Argentina and Ukraine drive silo bag procurement. Price sensitivity limits adoption of coated or barrier-enhanced variants.
Logistics providers control the consolidating procurement channel; food manufacturers are expanding specification fastest.
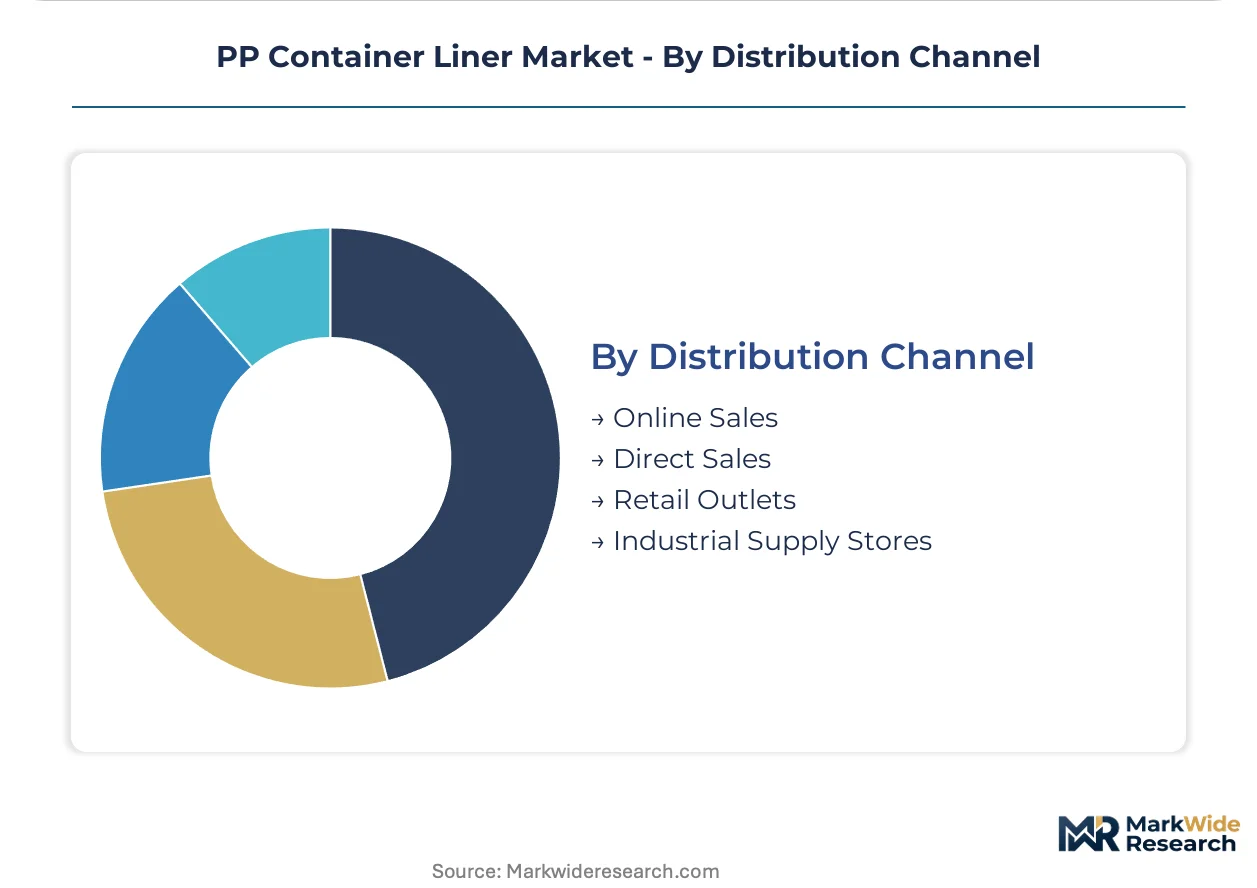
Distribution Channel:
Supply concentration in weaving equipment manufacturing shapes channel economics and regional access patterns.
- Online Sales:Digital procurement platforms serve small-volume agricultural buyers and replacement-part purchasers. Standard specification liners without certification requirements dominate transaction volume.
- Direct Sales:Converter-direct relationships persist for hazardous-material and pharmaceutical-grade liners requiring technical qualification. Berry Global and Thrace Group maintain dedicated sales engineering for certified applications.
- Retail Outlets:Agricultural supply cooperatives stock standard silo bags and basic FIBCs for seasonal farm demand. Limited barrier certification inventory reflects price-sensitive customer bases.
- Industrial Supply Stores:Regional distributors serve mid-tier chemical and food processors with partially certified liner inventories. REACH and FDA documentation availability varies by store location.
Direct sales retain margin leadership for certified grades; online channels are expanding access fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German chemical corridors while Chinese manufacturing clusters compete on resin proximity and fabrication scale. This asymmetry shapes procurement patterns across end-use segments.
Germany
REACH migration testing mandates and ECHA Annex XVII compliance requirements drive specification premiums for hazardous-material liners. German chemical handlers in the Port of Rotterdam corridor now require certified bulk enclosures for lithium carbonate transport. The Rhine-Ruhr industrial zone anchors converter qualification programs for battery precursor powders.
China
Coastal manufacturing clusters in Ningbo and Shanghai integrate polypropylene resin supply with just-in-time liner fabrication. SAMR dimensional tolerances and GB load-rating certifications govern export-bound production. Yangtze River Delta FIBC sewing operations serve Australian mineral exporters through Vietnam and Indonesia co-location strategies.
United States
FDA extractable limits govern direct-contact food applications for sugar and flour handling. Berry Global leverages captive North American resin supply chains across manufacturing corridors. Midwest agricultural distribution channels serve seasonal grain processor demand through industrial supply networks.
Netherlands
Rotterdam port operators bundle liner procurement with container leasing contracts, compressing direct weaver relationships. REACH substance registration requirements cascade through European chemical supply chains. Dutch chemical distributors specify UN-certified variants for cross-border hazardous powder movements.
Switzerland
Swissmedic-aligned pharmaceutical ingredient shippers specify oxygen transmission rates below 0.5 cc/m²/day for probiotic and enzyme powders. Multilayer coextruded barrier specifications fragment traditional coated-PP tape segments. Basel-area logistics providers integrate active barrier coatings into high-value cargo handling protocols.
PP Container Liner Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated resin producers command supply security advantages while specialized converters compete on certification depth and barrier performance. Three archetypes dominate: backward-integrated polymer giants, regional weaving specialists with hazardous-material credentials, and logistics-integrated bundlers. M&A activity concentrates among container leasing operators acquiring liner supply capabilities, while capacity expansion clusters in Southeast Asian sewing corridors.
Among European-based specialists, Thrace Group and Eceplast exemplify the certification-premium archetype, with the former anchoring southeastern European production and the latter occupying positions in hazardous-material compliance tiers. Berry Global Inc. represents the integrated-resin model with North American supply chain control. Taihua Group and Sinopack sit within the scale-driven Asian fabrication tier serving export-bound chemical and agricultural demand.
| Leading Market Players |
|---|
| LC Packaging |
| Berry Global Inc. |
| Taihua Group |
| Sinopack |
| Caretex |
| Greif Flexible Products & Services |
| Thrace Group |
| Eceplast |
| Linertech |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day resin inventory buffers at Ningbo and Shanghai extrusion plants translate directly into pricing leverage for backward-integrated converters serving REACH-certified chemical transport tiers. This lead-time compression at the polypropylene source separates premium-quoting specialists from spot-market-dependent weavers.
Pricing Analysis
The configured-to-order premium spread separates UN-certified hazardous-material liners from standard agricultural grades by multiples reflecting migration-testing documentation and silicone-based barrier validation. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with FDA-extractable-compliant food-contact variants commanding intermediate positioning. Price differentiation stems from REACH substance registration burden and ECHA Annex XVII reformulation costs. Cost compression in commodity woven segments is intensifying because Turkish and Indian loom equipment concentration limits supplier switching. Agricultural cooperatives in Argentina and Ukraine exhibit highest price sensitivity; pharmaceutical ingredient shippers in Switzerland demonstrate lowest.
Supply Chain Analysis
Inventory positioning at Middle Eastern PDH units and Chinese naphtha crackers anchors raw material availability for tape extrusion corridors. Polypropylene supply concentrates in Saudi Arabia, China, and South Korea. Converter operations draw from circular loom manufacturing in Turkey and India, with coating and lamination equipment concentrated in Germany and Italy. Single-source vulnerability pervades weaving equipment procurement. Distribution runs through Rotterdam and Singapore port operators bundling liner supply with container leasing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified barrier-lamination capacity sits scarcer than extrusion scale, creating durable rent extraction for converters holding pharmaceutical-grade oxygen transmission certification.
For Market Incumbents: Shield margin position by accelerating silicone-based grease-resistant qualification ahead of ECHA Annex XVII enforcement deadlines. Deepen upstream control over post-industrial scrap collection networks to capture Extended Producer Responsibility compliance premiums. Berry Global and Thrace Group demonstrate this path through captive resin and dedicated extrusion assets. For New Entrants and Emerging Players: Anchor in Vietnamese and Indonesian sewing corridors serving Australian mineral exporters through coastal manufacturing integration. White-space targets concentrate in lithium carbonate UN-certified liners and probiotic powder active-barrier segments. Go-to-market through logistics-integrated bundlers rather than direct weaver competition. For Investors and Strategic Acquirers: Carve-out targets emerge from container leasing operators seeking backward integration into liner fabrication capabilities. Long-term viability favors converters with hazardous-material certification depth over commodity weavers exposed to resin volatility. Watch ECHA substance evaluation timelines as inflection indicator for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polypropylene supply secures margin stability against Middle Eastern feedstock volatility. |
| Hazardous-Material Certification | UN-certified liner programs command price multiples in lithium carbonate transport. |
| Post-Industrial Scrap Networks | Collection infrastructure captures EU packaging waste directive recycled content thresholds. |
| Active Barrier Coating Investment | Multilayer EVOH lamination meets Swissmedic-aligned pharmaceutical oxygen transmission specifications. |
| Coastal Manufacturing Co-Location | Vietnam and Indonesia sewing integration reduces logistics cost for Australian mineral exporters. |
Study Parameters
Initial hypotheses were tested against primary input from liner procurement managers at Rotterdam and Singapore port operators, extrusion plant engineers at Ningbo and Shanghai manufacturing clusters, REACH compliance officers at German and Dutch chemical distributors, and agricultural cooperative buyers in Argentina and Ukraine. These perspectives were refined against secondary validation from customs trade data, ECHA substance registration databases, SEC filings of integrated resin producers, and FIBC industry association shipment reports. Bottom-up capacity estimates and top-down demand segmentation were triangulated to cross-validate volume conclusions.
Variance decomposition across the projection horizon isolates drivers by product-type, application tier, end-user concentration, and regional regulatory cluster. Segmentation dimensions modeled include barrier performance level, certification grade, resin integration status, and channel structure. CAGRs were derived from recursive substitution analysis linking end-use demand to liner consumption intensity. Forecast inputs incorporated REACH migration testing mandate expansion rates and FIBC adoption curves in Chinese coastal food manufacturing.
Material uncertainties — propylene feedstock margin collapse, circular loom equipment supply disruption, and ECHA perfluorinated compound restriction acceleration — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Wide Mouth Jars Market
Containers
ISO Container Market
Containers
Flexible Water Tanks Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Oblong Jar Market
Containers
Half Height Containers Market
Containers
Wire Containers Market
Containers
Bulk Container Packaging Market
Containers
Twist Up Stick Container Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Jerry Cans Market
Containers
Corrugated Bin Boxes Market
Containers
Child-Resistant Containers Market
Containers
Sample Containers Market
Containers
Compartment Take-Out Container Market
Containers
Global Food Containers Market