
 Corrugated Fish Box Market | 2026-2036
Corrugated Fish Box Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Fish Box Market Analytics
A capital-intensity divergence between integrated paperboard producers and regional converters is reorganizing competitive tiers in corrugated fish box supply. Smurfit Kappa leverages its European recycled fiber network to anchor large-format insulated box output for North Sea processors. WestRock competes through controlled access to virgin kraft linerboard, sustaining moisture-resistance specifications that distributors in the Gulf of Mexico demand. Georgia-Pacific differentiates via in-house pulp-to-box integration, dominating volume contracts with Pacific Northwest salmon processors.
Corrugated fish boxes are fiber-based containers engineered with wax-impregnated or polymer-coated linerboard to resist moisture degradation during iced seafood transit, typically constructed in single-wall to triple-wall flute configurations with burst strengths exceeding 200 psi for stacking load tolerance. Their primary commercial purpose is to maintain product temperature integrity, prevent leakage, and enable efficient palletization from harvest point through retail distribution. Recycled paperboard material dominates volume production due to cost structures, though virgin fiber commands premium positioning where extended cold-chain duration exceeds 72 hours. Insulated box types represent the fastest-expanding segment as processors replace expanded polystyrene with fiber-based thermal barriers to meet retailer sustainability protocols.
FDA food-contact substance regulations and the EU Packaging and Packaging Waste Regulation jointly shape material compliance requirements, with the former governing migration limits for coatings in US seafood commerce and the latter mandating recyclability thresholds that exclude certain polyethylene barriers from European circulation. The EPA's emphasis on marine debris reduction amplifies pressure against non-recyclable alternatives in domestic coastal markets. Stakeholders must monitor evolving coating chemistries and regional recyclability certification schemes to determine capital allocation between barrier-laminated and bare fiberboard production lines.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing acceptable coating chemistries for fiber-based seafood containers, forcing converters to requalify barrier formulations while Nordic processors accelerate air-freight volume to Asian retail chains.
Growth Catalysts
- Insulated fiber substitution:Retailer sustainability protocols in Norway and Scotland are mandating replacement of expanded polystyrene with corrugated thermal barriers for Atlantic salmon exports.
- REACH compliance evolution:ECHA's advancing restrictions on per- and polyfluoroalkyl substances are redirecting coating R&D toward bio-based wax alternatives for moisture resistance.
- Asian air-freight corridors:Tokyo and Seoul importers are specifying stackable triple-wall configurations with burst tolerances exceeding 250 psi for direct-to-retail distribution.
Market Restraints
- Recycled fiber price volatility:Old corrugated container feedstock costs fluctuate with municipal collection rates, compressing converter margins in Baltic states.
- Virgin kraft supply concentration:Controlled access to Scandinavian pulp mills limits moisture-resistant linerboard availability for Gulf of Mexico shrimp processors.
- Polyethylene barrier exclusion:EU recyclability thresholds under PPWR are disqualifying laminated structures from circulation in German and French retail channels.
Strategic Opportunities
- Underpenetrated Vietnamese processing:Mekong Delta aquaculture exporters lack domestic insulated box capacity, creating white space for European converters with PPWR-certified formats.
- Dual carbon alignment:China's MEE emission reduction mandates are incentivizing fiber-based cold-chain adoption over petroleum-derived alternatives in Qingdao port operations.
- Channel consolidation:Direct procurement relationships between Scottish salmon farmers and Asian e-commerce platforms are bypassing traditional distributor networks.
Industry Challenges
- Coating formulation expertise:Shortage of polymer chemists familiar with FDA food-contact migration limits is delaying new product qualification timelines.
- Recyclability certification complexity:Divergent testing protocols between EU harmonized standards and US EPA marine debris guidelines require dual-track validation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Fish Box Market |
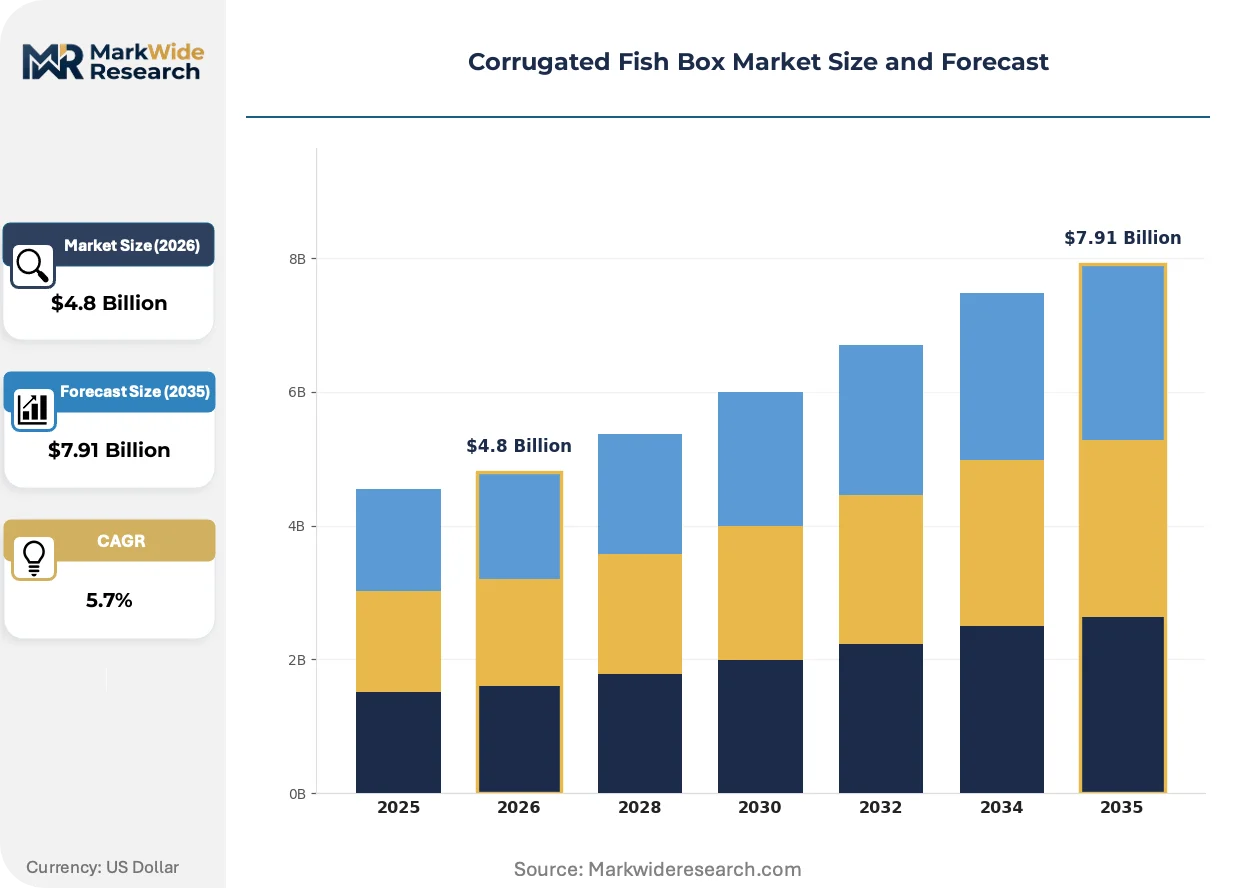
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Box Type: Standard Boxes, Insulated Boxes, Custom Design, Stackable Boxes Material: Recycled Paperboard, Virgin Fiber, Double-Wall, Single-Wall End User: Fish Processors, Distributors, Retailers, Restaurants Size: Small, Medium, Large, Extra Large |
| Companies Covered | Smurfit Kappa, Snyder Industries, Sekisui Plastics, Styropack, Tri-Core Plastics Containers, PPS, International Paper, WestRock, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Fish Box Market Evolving Landscape
Barrier technology, regulatory chemistry restrictions, and procurement centralization are converging to reshape how corrugated fish boxes are specified, manufactured, and distributed across cold-chain corridors.
Plant-derived wax coatings with tuned hydrophobicity are decomposing the historical reliance on synthetic polymer barriers in premium seafood packaging. Scottish and Norwegian salmon exporters are qualifying these formulations for 72-hour air-freight durations to Tokyo and Singapore. The shift is compressing demand for polyethylene-laminated linerboard while expanding recycled fiber acceptance rates in EU circular-economy audits.
REACH substance restrictions on fluorinated chemistries are eliminating legacy moisture-barrier options from European circulation. Converter investments in bio-based alternatives now dominate capital allocation discussions in Nordic paperboard clusters. German retail compliance teams are accelerating supplier audits to verify coating chemistry documentation ahead of 2025 enforcement milestones.
Consolidated procurement by Asian e-commerce seafood platforms is compressing supplier diversity among Baltic and North Sea converters. Direct volume contracts with centralized buying desks are displacing fragmented distributor relationships that historically characterized the trade. This concentration is most visible in Qingdao and Busan, where platform-controlled logistics now dictate box specification standards.
Corrugated Fish Box Market Segmentation
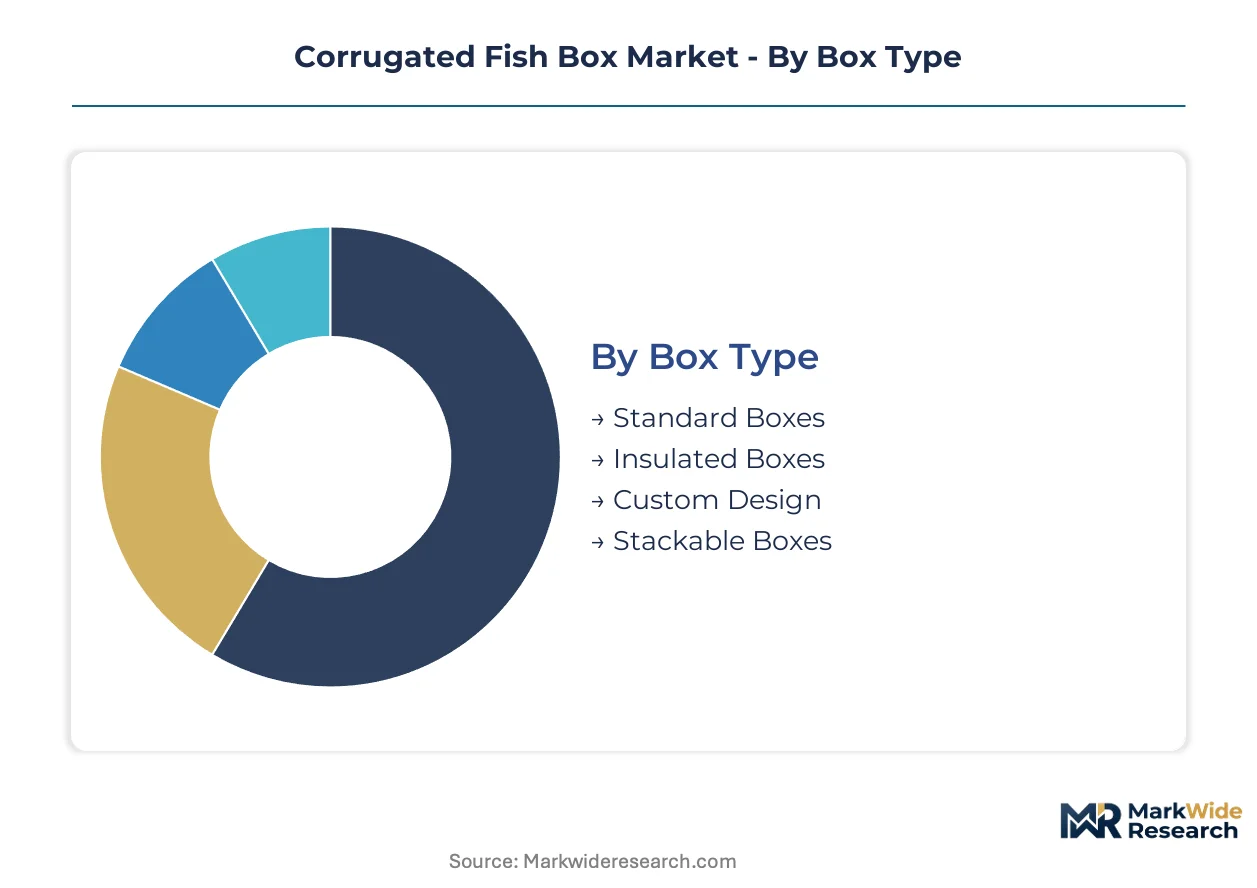
Corrugated fish box specification diverges sharply across cold-chain duration, regulatory jurisdiction, and palletization requirements. Processors select configurations based on moisture-exposure hours, stacking load tolerances, and destination market recyclability mandates.
Box Type:
Regulatory chemistry restrictions in the EU and Japan are forcing converters to requalify barrier formulations by box architecture, with insulated formats facing the tightest compliance timelines.
- Standard Boxes:Single-wall to double-wall constructions with wax-impregnated linerboard dominate short-haul Nordic distribution. Norwegian Atlantic salmon exporters deploy these for truck-based delivery to European processing hubs where transit stays under 24 hours.
- Insulated Boxes:Triple-wall configurations incorporating plant-derived thermal barriers replace expanded polystyrene in air-freight corridors. Scottish processors qualify these for 72-hour durations to Tokyo and Singapore under retailer sustainability protocols.
- Custom Design:Specified by Vietnamese Mekong Delta exporters lacking domestic insulated capacity.
- Stackable Boxes:Burst-tolerance specifications exceeding 250 psi serve Qingdao and Busan platform-controlled logistics.
Standard boxes handle the majority of throughput; insulated boxes are gaining share fastest on sustainability-driven specification changes.
Material:
Cost tier separation between feedstock types determines converter margin structures and export market access.
- Recycled Paperboard:Old corrugated container feedstock dominates Baltic and North Sea volume production. German retail compliance teams audit coating chemistry documentation for EU circular-economy acceptance rates.
- Virgin Fiber:Scandinavian pulp mill output sustains moisture-resistance specifications for Gulf of Mexico shrimp processors requiring extended cold-chain integrity.
- Double-Wall:Balances burst strength against material cost for medium-haul distribution.
- Single-Wall:Serves same-day harvest-to-retail operations in coastal Norwegian clusters.
Recycled paperboard moves the highest volume; virgin fiber commands the steepest expansion trajectory in premium export channels.
End User:
Procurement centralization is compressing supplier diversity across buyer categories.
- Fish Processors:Direct volume contracts with Asian e-commerce platforms now displace fragmented distributor relationships. Scottish salmon farmers bypass traditional networks to secure stackable triple-wall supply.
- Distributors:Consolidated buying desks in Qingdao and Busan dictate box specification standards for cross-border cold-chain corridors.
- Retailers:Mandate PPWR-certified formats and bio-based wax alternatives.
- Restaurants:Smaller lot sizes favor standard box procurement through regional converters.
Fish processors account for the dominant procurement volume; distributor consolidation is expanding most quickly.
Size:
Palletization efficiency and aircraft cargo constraints shape dimensional demand.
- Small:Direct-to-restaurant portions in Norwegian coastal markets.
- Medium:Retail-ready configurations for Seoul and Tokyo importers.
- Large:Industrial processors in Scotland and Norway specify these for consolidated air-freight palletization.
- Extra Large:Limited adoption due to manual handling constraints in Mekong Delta operations.
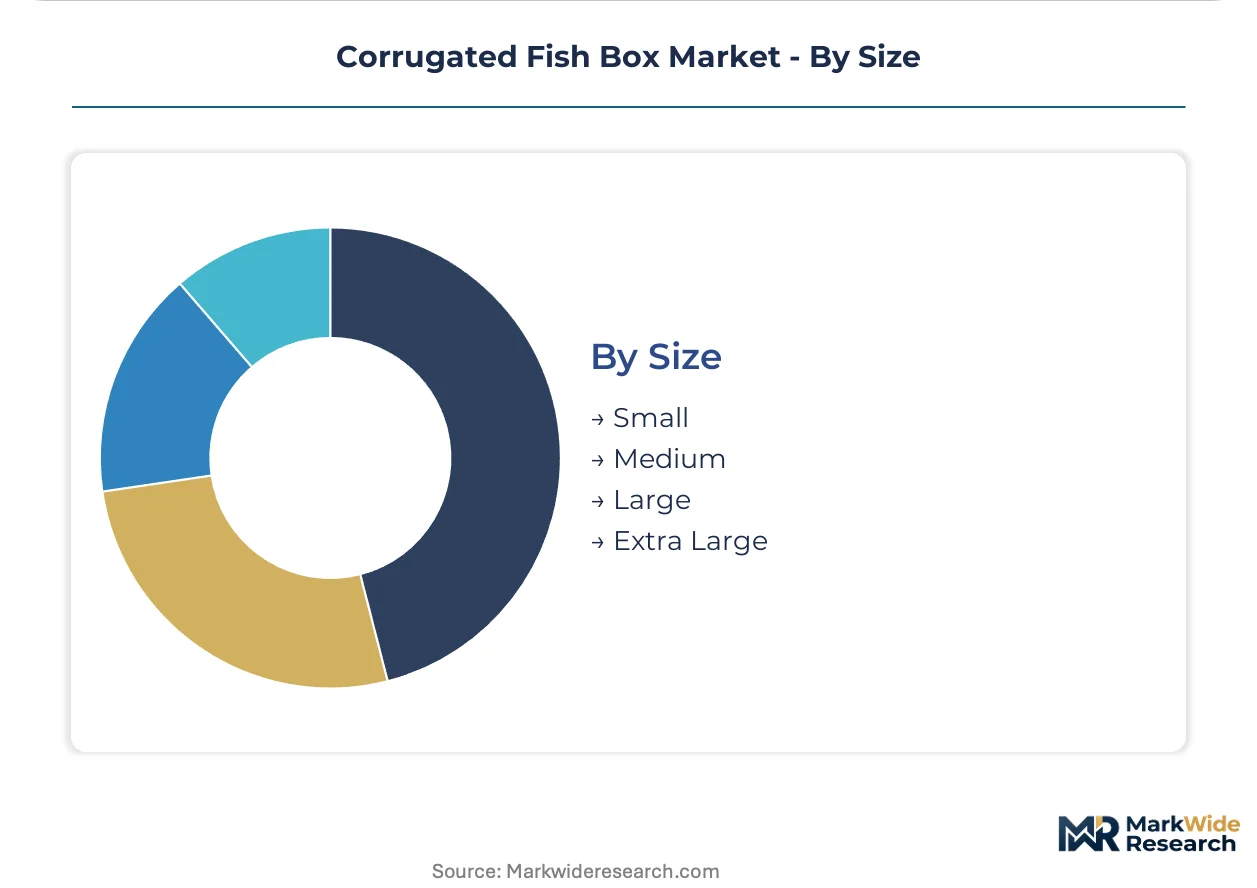
Large sizes carry the bulk of export volume; medium sizes are climbing fastest on e-commerce platform specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian processors command premium pricing for Atlantic salmon exports to Asian markets, while Vietnamese Mekong Delta exporters face compressed margins due to limited domestic insulated box manufacturing capacity.
Norway
Atlantic salmon air-freight volumes to Tokyo and Singapore drive demand for triple-wall insulated configurations with plant-derived wax barriers. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that Norwegian exporters must meet for German and French retail channels. Bergen and Stavanger processing clusters are qualifying bio-based thermal barriers for 72-hour cold-chain durations.
United States
Gulf of Mexico shrimp processors require moisture-resistant linerboard specifications for extended distribution networks. FDA food-contact substance regulations govern migration limits for coatings used in domestic seafood commerce. Seattle and Portland facilities in the Pacific Northwest dominate volume contracts with salmon processors seeking in-house pulp-to-box integration.
Germany
Retail compliance teams audit coating chemistry documentation ahead of PPWR enforcement milestones, accelerating supplier qualification timelines. ECHA REACH restrictions on fluorinated chemistries eliminate legacy moisture-barrier options from circulation. Hamburg and Bremerhaven logistics hubs concentrate procurement standard-setting for Baltic and North Sea cold-chain corridors.
Vietnam
Mekong Delta aquaculture exporters lack domestic insulated box capacity, creating procurement dependence on European converters with certified formats. China's MEE emission reduction mandates incentivize fiber-based cold-chain adoption in adjacent Qingdao port operations. Ho Chi Minh City processing clusters are negotiating direct volume contracts with Asian e-commerce platforms.
Scotland
Retailer sustainability protocols mandate replacement of expanded polystyrene with corrugated thermal barriers for Atlantic salmon exports. Direct procurement relationships with Asian e-commerce platforms are bypassing traditional distributor networks. Aberdeen and Peterhead fishing ports specify stackable configurations with burst tolerances exceeding 250 psi for palletized air freight.
Corrugated Fish Box Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the corrugated fish box supply base. Integrated paperboard producers with captive pulp supply anchor premium moisture-resistant segments, while regional converters compete on recycled fiber cost structures and rapid turnaround. Three archetypes dominate: multinational integrated producers with European recycled fiber networks, North American virgin kraft specialists, and Asia-Pacific converters serving underpenetrated export markets. Competitive moves concentrate on barrier formulation requalification and direct procurement relationships with centralized e-commerce buying desks.
Among European integrated producers, Smurfit Kappa exemplifies the recycled fiber network archetype, while WestRock and Georgia-Pacific occupy positions on the North American virgin kraft specialization vector. These three entities represent distinct strategic postures: European circular-economy alignment, moisture-resistance specification leadership, and pulp-to-box vertical control respectively.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Snyder Industries |
| Sekisui Plastics |
| Styropack |
| Tri-Core Plastics Containers |
| PPS |
| International Paper |
| WestRock |
| Georgia-Pacific |
| Others |
Value Network & Pricing Analysis
Sixty-day virgin kraft linerboard lead times from Scandinavian pulp mills compress converter margins while anchoring premium pricing power for moisture-resistant specifications serving Gulf of Mexico shrimp processors. This inventory-to-pricing nexus forces Baltic converters toward recycled fiber cost structures that trade barrier performance for circular-economy compliance.
Pricing Analysis
Configured-to-order insulated box pricing commands spreads exceeding standard wax-impregnated configurations by certification grade and cold-chain duration. Three-tier pricing structure across PPWR-certified premium, REACH-compliant standard, and economy recycled tiers stratifies buyer access. Cost compression in Baltic converter margins intensifies because old corrugated container feedstock volatility erodes contract stability. Fish processors direct-procuring through Asian e-commerce platforms exhibit lowest price sensitivity; regional restaurant distributors face acute margin pressure.
Supply Chain Analysis
Scandinavian pulp mill concentration around the Baltic Sea underwrites virgin kraft availability for extended-duration export specifications. Norway, Germany, and Vietnam anchor supply geography, drawing from old corrugated container collections, plant-derived wax coating inputs, and thermal barrier substrates. Single-source vulnerability runs through ECHA REACH-compliant coating chemistries that disqualify legacy fluorinated alternatives. Distribution runs through platform-controlled logistics hubs in Qingdao and Busan that dictate specification standardization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: PPWR compliance timelines and REACH substance restrictions create switching costs that lock processors into qualified supplier relationships.
For Market Incumbents: Fortify barrier formulation expertise through captive polymer chemistry capabilities that emerging Asian converters cannot replicate. Secure capacity addition in Vietnamese Mekong Delta corridors before local insulated box manufacturing matures. PPWR certification investments represent the critical lever against margin pressure from recycled fiber volatility. For New Entrants and Emerging Players: Differentiate on bio-based wax coating chemistry that satisfies ECHA REACH fluorinated substance restrictions ahead of enforcement milestones. Vietnamese aquaculture exporters lacking domestic insulated capacity present the most penetrable white space. Direct volume contracts with Asian e-commerce platform buying desks offer the essential go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from European paperboard parents with stranded polyethylene-laminated production lines facing PPWR disqualification. Long-term viability across the analysis window hinges on coating chemistry transition completion. Watch ECHA enforcement milestone adherence as the inflection indicator for stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Formulation Requalification | ECHA REACH fluorinated restrictions force coating chemistry transition investments. |
| Backward Integration into Pulp Supply | Scandinavian virgin kraft access secures moisture-resistance specification leadership. |
| Direct Platform Procurement Relationships | Qingdao and Busan e-commerce logistics hubs displace fragmented distributor networks. |
| PPWR Certification Investment | German retail compliance audits mandate recyclability threshold documentation. |
| Vietnamese Capacity Expansion | Mekong Delta aquaculture export growth outpaces domestic insulated box supply. |
Research Methodology
The analysis maps insulated box architectures, recycled and virgin fiber material tiers, and end-user procurement channels, each validated through converter operations directors, seafood processor procurement leads, retail compliance auditors, and cold-chain logistics coordinators. Primary interview intelligence triangulates against secondary sources including EU PPWR regulatory filings, ECHA REACH substance restriction updates, FDA food-contact substance guidance, and customs trade data for corrugated container movements. Bottom-up volume estimates from named processing clusters reconcile with top-down market sizing across the projection horizon.
Model outputs undergo consistency checks against external benchmarks including paperboard production statistics and seafood export volume correlations. Segmentation dimensions span box type, material grade, end-user category, and geographic cold-chain corridor throughout the forecast period. CAGRs derive from trend extrapolation of air-freight volume growth, sustainability protocol adoption curves, and regulatory compliance timeline impacts. Industry-specific inputs incorporate Nordic salmon export trajectories and Asian e-commerce platform procurement centralization patterns.
Material uncertainties — regulatory enforcement delays, coating chemistry qualification failures, pulp mill supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about PPWR implementation adherence and REACH substance restriction timelines. Practitioners should keep alternative scenarios live as ECHA enforcement milestones and virgin kraft supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market