
 Corrugated Handle Box Market | 2026-2036
Corrugated Handle Box Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Handle Box Market Analysis
The capital-intensity divergence between automated corrugators and manual assembly operations is rotating competitive advantage toward integrated manufacturers. DS Smith leverages its European recycled fiber network to control input costs across multiple plant locations. GWP Group specializes in bespoke die-cut handle configurations for premium retail clients. Guangzhou Bosing Paper Printing and Packaging Co., Ltd. anchors its position through integrated printing and converting capabilities in South China.
A corrugated handle box consists of fluted paperboard laminated between flat linerboards, typically constructed from kraft or recycled fibers with integrated die-cut hand holes or reinforced strap handles, manufactured through single-face corrugation, slotting, and folding-gluing processes designed for portable product protection and brand presentation. Custom Boxes command premium positioning through variable-depth designs and high-resolution lithographic printing that supports unboxing-driven marketing campaigns. Standard Boxes occupy high-volume, price-sensitive segments in grocery and household goods distribution where material efficiency outweighs aesthetic differentiation. Recycled Paper substrates face tightening specification requirements as post-consumer content thresholds rise under extended producer responsibility frameworks.
The EPA's recycled fiber content guidelines for paperboard packaging, combined with EU REACH restrictions on coatings and adhesives, are reshaping material sourcing strategies for North American and European converters. FDA food-contact substance regulations govern linerboard formulations destined for direct food packaging applications in the United States. ISO 9001 and FSC chain-of-custody certifications increasingly function as market-access prerequisites for multinational brand procurement teams. Stakeholders must monitor evolving state-level extended producer responsibility legislation and calibrate capital allocation between recycled-content compliance and virgin-fiber performance specifications.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing virgin-fiber demand while recycled-content thresholds climb, forcing converters to reengineer linerboard formulations and secure post-consumer waste streams ahead of compliance deadlines.
Growth Catalysts
- E-commerce fulfillment infrastructure:Last-mile delivery networks are expanding procurement of custom-printed handle boxes to support unboxing-driven brand experiences and reduce damage rates in direct-to-consumer shipments.
- REACH coating restrictions:EU chemical regulations are accelerating water-based adhesive and barrier coating adoption, creating first-mover advantages for converters with certified compliant production lines.
- Extended producer responsibility frameworks:Germany's Verpackungsgesetz and France's AGEC law are mandating recycled content minimums that lock in demand for post-consumer fiber sourcing contracts.
Market Restraints
- Old corrugated container supply concentration:Post-consumer fiber availability clusters in German and Benelux industrial corridors, exposing southern European converters to input cost volatility and logistics premiums.
- Flute calibration limitations:Micro-flute and nano-flute configurations below E-flute thickness face structural integrity failures in humid climates, restricting deployment in Southeast Asian export markets.
- Kraft linerboard price spreads:Virgin kraft pulp contracts indexed to NBSK futures transmit commodity volatility directly to premium custom box margins, compressing converter profitability during pulp price spikes.
Strategic Opportunities
- India's organized retail expansion:Reliance Retail and D-Mart store rollouts are creating demand for standardized handle boxes in FMCG distribution where unbranded corrugated currently dominates.
- Digital print-convergence:Single-pass inkjet integration with rotary die-cutting is enabling batch-size-one production economics for premium cosmetics and electronics unboxing campaigns.
- EU Green Deal procurement incentives:Public sector tendering rules awarding 15-30% weighting to circularity criteria are opening institutional channels for FSC-certified, high-recycled-content handle box suppliers.
Industry Challenges
- Prepress-to-die-cut workflow integration:Legacy CAD table operations require skilled tooling technicians whose training pipelines collapsed during 2020-2022 restructuring, creating hiring bottlenecks for high-mix production.
- Food-contact migration testing timelines:FDA and EFSA substance notifications for novel barrier coatings extend 18-24 months, delaying product launches for direct-food handle box applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Handle Box Market |
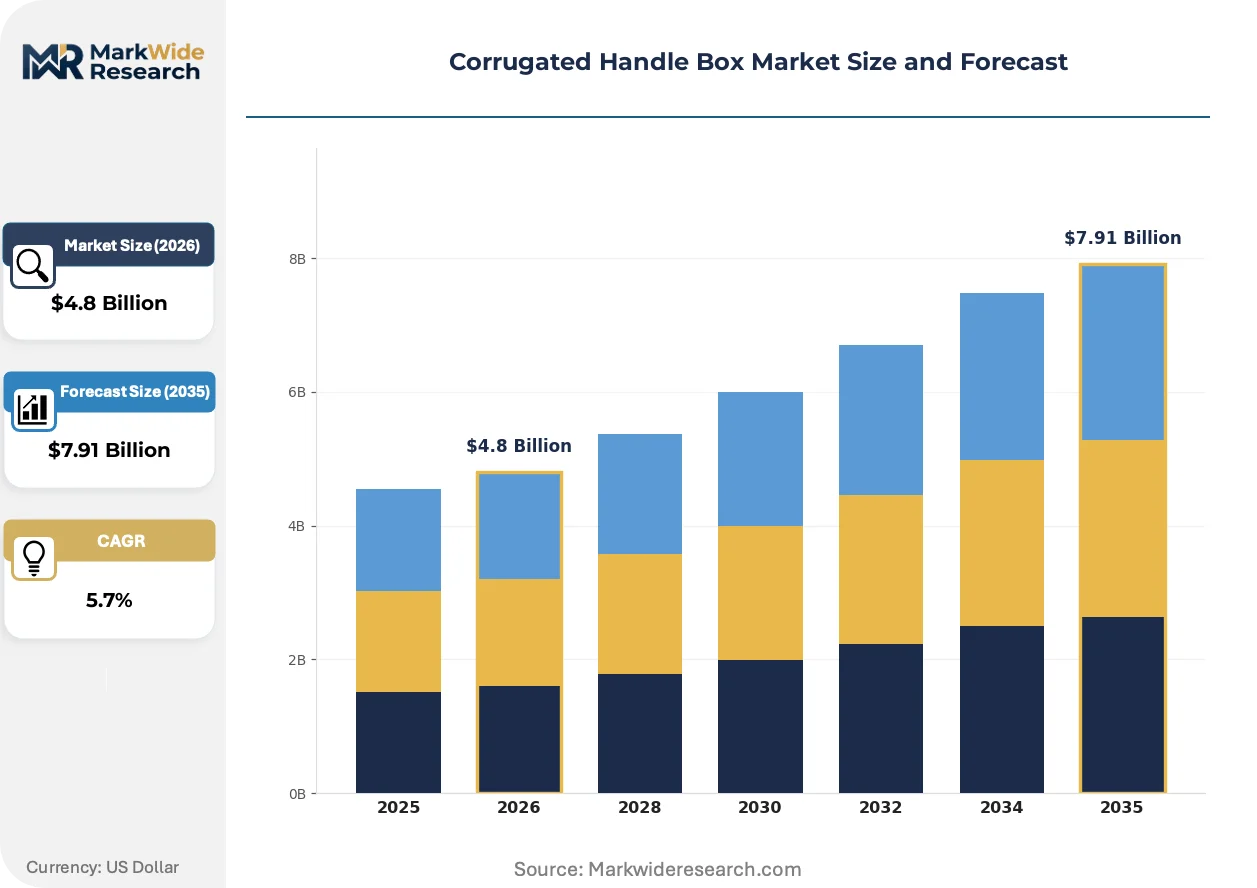
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Boxes, Custom Boxes, Insulated Boxes, Retail Boxes Material: Recycled Paper, Virgin Fiber, Coated Paper, Kraft End User: Food & Beverage, Cosmetics, Electronics, Household Goods Distribution Channel: Online Retail, Wholesale, Direct Sales, Third-party Retail |
| Companies Covered | REID PACKAGING, Allen Field Company Inc., STÜRMER MASCHINEN, GWP Group, Guangzhou Bosing Paper Printing and Packaging Co., Ltd., WH Skinner, CBS Packaging Group, Riverside Paper Co. Inc., DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Handle Box Market Emerging Trajectories
Digital production workflows and fiber chemistry advances are fragmenting the traditional volume-mass-customization tradeoff, enabling economically viable short-run premium packaging that was previously confined to folding carton substitutes.
Water-based flexo ink systems with extended color gamut capabilities are decomposing the lithographic lamination requirement for photographic-quality retail graphics. Beauty and electronics brands in Germany and France are adopting these systems for runs below 10,000 units. The technology is decomposing minimum order quantity thresholds that previously locked mid-tier brands into standard box formats.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances in food-contact materials are compelling linerboard suppliers to certify fluorine-free grease barriers. German converters face reformulation costs and substrate qualification delays. The regulation is reshaping supplier qualification protocols for quick-service restaurant chains sourcing direct-food handle boxes.
Unboxing video content creation is compressing brand packaging refresh cycles from annual to quarterly rhythms. Influencer marketing teams in Los Angeles and London now specify handle box prototypes for single campaign deployments. This pattern concentrates demand volatility in premium custom segments while standard grocery distribution maintains stable procurement schedules.
Corrugated Handle Box Market Segmentation
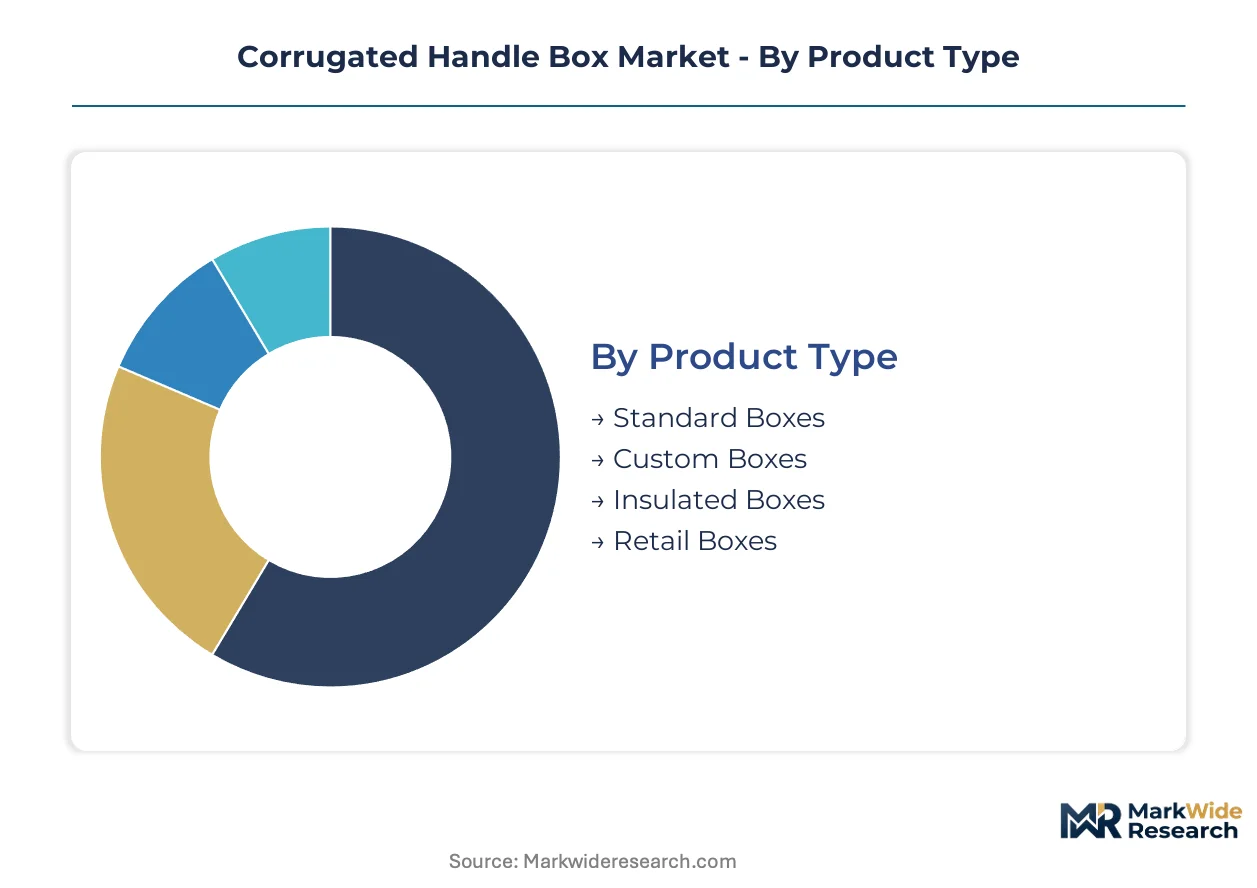
Corrugated handle box demand fragments across four distinct dimensions. Product configuration determines capital intensity and margin structure. Material sourcing constrains geographic compliance. End-use concentration drives specification divergence. Channel selection locks in volume predictability versus customization premiums.
Product Type:
Domestic consumption clusters in standard and retail formats, while custom and insulated variants serve export-led premium segments.
- Standard Boxes:Single-wall C-flute or B-flute construction dominates grocery and household goods distribution. German discounters and French supermarket chains specify these for private-label detergent and dry-goods consolidation. Demand concentrates in high-volume, price-sensitive procurement where material efficiency outweighs aesthetic differentiation.
- Custom Boxes:Variable-depth die-cut configurations with lithographic or flexographic printing support unboxing-driven marketing campaigns. Los Angeles-based influencer marketing teams and London cosmetics brands now specify prototypes for single campaign deployments, compressing refresh cycles from annual to quarterly rhythms.
- Insulated Boxes:Expanded polystyrene or cellulose pad liners bonded to corrugated shells protect temperature-sensitive pharmaceuticals and meal-kit deliveries.
- Retail Boxes:Shelf-ready designs with tear-away perforations and stacking headers serve mass merchandiser floor displays.
Standard Boxes command the established base. The steepest expansion runs through Custom Boxes.
Material:
Cost tiers separate virgin-fiber performance specifications from recycled-content compliance mandates.
- Recycled Paper:Post-consumer corrugated containers processed through repulping and de-inking stages face tightening EU Packaging and Packaging Waste Regulation thresholds. German converters secure long-term supply contracts with municipal waste collectors to lock in fiber streams ahead of compliance deadlines.
- Virgin Fiber:Unbleached softwood kraft pulp delivers superior burst strength and printability for premium cosmetics and electronics applications. NBSK futures-indexed contracts transmit commodity volatility directly to converter margins.
- Coated Paper:Clay or calcium carbonate surface treatments enable high-resolution graphic reproduction for beauty brand campaigns.
- Kraft:Natural brown linerboard signals sustainability positioning in organic food and artisanal goods packaging.
Virgin Fiber retains the premium tier. Recycled Paper is gaining share fastest under extended producer responsibility frameworks.
End User:
Application-specific requirements fragment specification standards across regulatory jurisdictions.
- Food & Beverage:Direct-contact linerboard must satisfy FDA food-contact substance notifications and EFSA migration testing timelines extending 18-24 months. Quick-service restaurant chains sourcing handle boxes for fried food delivery face EU REACH Annex XVII fluorine-free grease barrier mandates.
- Cosmetics:Premium unboxing experiences demand soft-touch coatings, foil stamping, and magnetic closures that drive per-unit value multiples.
- Electronics:Anti-static coatings and foam-in-place cushioning specifications protect high-value devices through last-mile distribution.
- Household Goods:Detergent and cleaning product packaging prioritizes stack strength and moisture resistance over graphic sophistication.
Household Goods anchors volume throughput. Cosmetics delivers the steepest margin expansion trajectory.
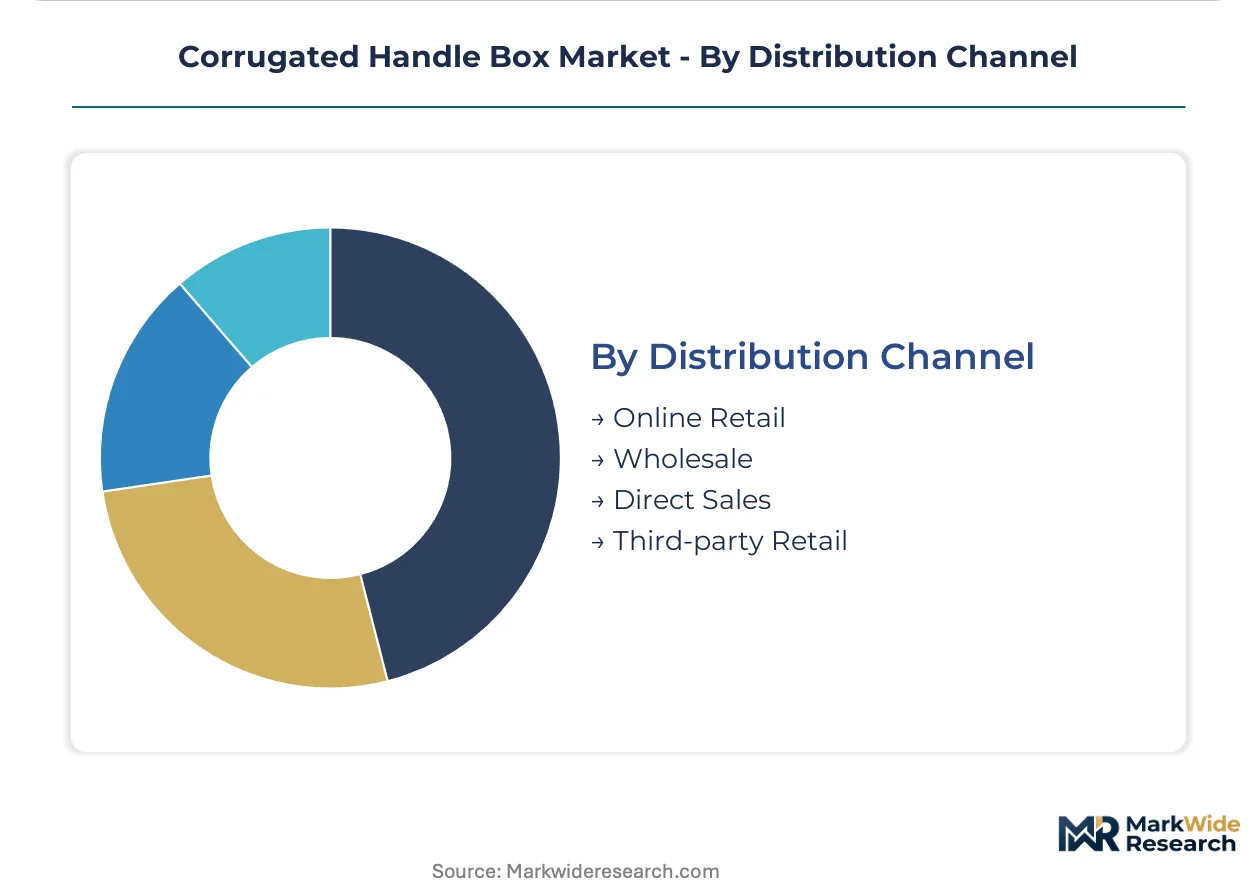
Distribution Channel:
Customer type determines order predictability and production planning horizons.
- Online Retail:E-commerce fulfillment centers procure custom-printed handle boxes for direct-to-consumer shipments where damage reduction and brand presentation drive specification. Batch-size-one digital print-convergence enables campaign-specific production.
- Wholesale:Distributor intermediaries aggregate fragmented demand from regional retailers, requiring standardized SKU portfolios and extended payment terms.
- Direct Sales:Converter-to-brand relationships eliminate margin capture by intermediaries but demand dedicated account management infrastructure.
- Third-party Retail:Mass merchandiser compliance programs impose vendor qualification barriers including ISO 9001 and FSC chain-of-custody certification.
Wholesale maintains the volume base. Online Retail is climbing the fastest as unboxing content creation reshapes procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial packaging corridor while southern European converters absorb logistics premiums for post-consumer fiber sourcing. This asymmetry is reshaping capital allocation across the continent.
Germany
Verpackungsgesetz mandates are locking converters into long-term municipal waste contracts ahead of recycled-content deadlines. ECHA REACH restrictions on fluorine-based grease barriers are forcing linerboard reformulation for quick-service restaurant supply. The North Rhine-Westphalia cluster hosts integrated corrugators serving FMCG distribution across the Benelux corridor.
United States
FDA food-contact substance notifications are extending 18-24 month qualification timelines for direct-food packaging applications. EPA recycled fiber content guidelines are reshaping material sourcing strategies for North American converters. Los Angeles-based influencer marketing teams are compressing custom box refresh cycles through campaign-specific unboxing specifications.
China
Guangdong Province's integrated printing and converting capabilities anchor export-oriented production for premium retail clients. MEE environmental inspections are tightening wastewater discharge standards for de-inking operations. The Pearl River Delta concentration enables rapid prototyping for batch-size-one digital print runs.
India
Reliance Retail and D-Mart store rollouts are displacing unbranded corrugated with standardized handle specifications in FMCG distribution. BIS packaging standards are formalizing quality thresholds for organized retail procurement. Maharashtra's industrial corridor is attracting corrugator investments targeting western India's consumption growth.
France
AGEC law recycled-content minimums are accelerating post-consumer fiber contract negotiations ahead of compliance deadlines. ANSM oversight of food-contact materials is extending barrier coating qualification timelines for meal-kit delivery applications. The Île-de-France region concentrates cosmetics brand procurement demanding premium unboxing configurations.
Corrugated Handle Box Market Vendor Landscape
Concentration sits with integrated European manufacturers controlling recycled fiber networks across multiple plant locations. The vendor base fragments between automated corrugators and manual assembly operations, rotating advantage toward capital-intensive integrated producers. Three archetypes dominate: fiber-integrated multinationals, bespoke die-cut specialists, and integrated printing-converting operators in South China. Competitive moves center on backward integration into post-consumer waste streams and single-pass inkjet adoption for batch-size-one production economics.
Among European fiber-integrated operators, DS Smith exemplifies the multinational archetype leveraging continental recycled fiber networks. GWP Group occupies a position within the bespoke die-cut specialist tier serving premium retail configurations. Guangzhou Bosing Paper Printing and Packaging Co., Ltd. anchors the integrated printing-converting model in South China's export manufacturing base.
| Leading Market Players |
|---|
| REID PACKAGING |
| Allen Field Company Inc. |
| STÜRMER MASCHINEN |
| GWP Group |
| Guangzhou Bosing Paper Printing and Packaging Co., Ltd. |
| WH Skinner |
| CBS Packaging Group |
| Riverside Paper Co. Inc. |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at automated corrugators in Germany's North Rhine-Westphalia cluster shapes both supply concentration and price floors across European markets. German integrated manufacturers leverage scale economies to compress unit costs while southern European converters absorb logistics premiums for post-consumer fiber sourcing.
Pricing Analysis
The customization-premium spread separates configured-to-order custom boxes from standard grocery formats. Three-tier pricing structure across premium, standard, and economy levels captures value from lithographic unboxing campaigns down to material-efficient dry-goods distribution. Price differentiation hinges on certification grade and volume scale, with FSC-certified custom configurations commanding premiums while standard C-flute grocery boxes face cost compression from virgin kraft pulp volatility. Brand managers and influencer marketing teams show lowest price sensitivity for campaign-specific prototypes, whereas German discounters and French supermarket chains prioritize material efficiency over aesthetic investment.
Supply Chain Analysis
Inventory lead times for post-consumer fiber contracts extend 12-18 months ahead of EU Packaging and Packaging Waste Regulation compliance deadlines. Supply concentrates in Germany, Benelux, and China's Guangdong Province, with German converters drawing from municipal waste streams and South Chinese operators feeding from integrated printing-converting hubs. Raw material dependencies center on old corrugated containers, unbleached softwood kraft pulp, and water-based barrier coatings. Single-source vulnerability clusters in German industrial corridors for recycled fiber, while distribution runs through converter-to-brand direct relationships and wholesale distributor networks aggregating fragmented retail demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment locks incumbents into long-term municipal waste contracts that new entrants cannot replicate.
For Market Incumbents: Secure backward integration into post-consumer fiber streams ahead of recycled-content threshold escalations under extended producer responsibility frameworks. Expand single-pass inkjet capacity for batch-size-one production economics, defending margin position against digital-native competitors targeting premium cosmetics unboxing segments. For New Entrants and Emerging Players: Differentiate on fluorine-free grease barrier certification for quick-service restaurant chains facing EU REACH Annex XVII mandates. Target India's organized retail expansion where Reliance Retail and D-Mart procurement standards displace unbranded corrugated, leveraging BIS packaging standard formalization as a market entry mechanism. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with certified compliant production lines and digital print-convergence capabilities. Acquisition targets should demonstrate locked-in municipal waste contracts and FSC chain-of-custody certification. The signal to watch is qualification timeline compression for novel barrier coatings under FDA and EFSA substance notification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Fiber | Locks in supply security ahead of EU recycled-content mandates affecting German and French converters. |
| Single-Pass Inkjet Adoption | Enables batch-size-one economics for Los Angeles and London influencer marketing campaign specifications. |
| Fluorine-Free Barrier Certification | Opens quick-service restaurant supply channels under EU REACH Annex XVII food-contact restrictions. |
| Digital Print-Convergence Investment | Compresses minimum order quantities for premium cosmetics and electronics unboxing deployments. |
| India Organized Retail Expansion | Captures standardized handle box demand from Reliance Retail and D-Mart store rollouts displacing unbranded corrugated. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory notifications. Conversations with corrugator plant managers, FMCG procurement leads, municipal waste contract officers, and brand packaging directors informed demand-side calibration. Secondary validation drew from EPA recycled fiber guidelines, EU Packaging and Packaging Waste Regulation impact assessments, and SEC filings by publicly traded packaging converters. Bottom-up volume estimates triangulated against top-down spending projections across the analysis window.
Segmentation dimensions modeled include product configuration, material sourcing tier, end-use application, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking regulatory compliance timelines. Industry-specific forecast inputs incorporated ECHA REACH restriction implementation schedules and FDA food-contact substance notification approval velocities.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce fulfillment infrastructure expansion or abrupt pulp commodity volatility would require recalibration. Forecasts reflect assumptions about regulatory enforcement consistency and fiber recycling technology maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market