
 Electric Vehicle Rapid Charger Market | 2026-2036
Electric Vehicle Rapid Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Rapid Charger Market Insights
Power electronics engineering talent is bifurcating the competitive landscape, with specialists commanding premium wages in Silicon Valley and Shenzhen simultaneously. ABB leverages its Swiss-Swedish industrial heritage to sustain integrated manufacturing of high-voltage rectifiers. Tesla anchors North American deployment through proprietary connector architecture and captive site development. TELD New Energy dominates China's state-tendered highway charging network, controlling grid interconnection standards across provincial utility territories.
An electric vehicle rapid charger converts alternating current from the grid into direct current at power levels exceeding 50 kW, enabling battery replenishment in 20–40 minutes through liquid-cooled cable assemblies and silicon carbide power modules. DC Fast Charger installations command the largest capital allocation among product types, while Wireless Charging remains nascent due to coil alignment tolerances and efficiency losses. Fleet Operators represent the fastest-growing end user category as logistics electrification mandates tighten, whereas Public Charging Stations still absorb the majority of networked systems deployment.
FAA guidelines for airport ground support electrification, NHTSA corridor-designation rules under the National Electric Vehicle Infrastructure program, and China's GB/T charging standards collectively shape product certification requirements and site approval timelines. The EU AI Act and CSRD disclosure rules are beginning to filter into charger-network procurement specifications, particularly for smart charging algorithms and embodied carbon reporting. Stakeholders must monitor which connector standard gains regulatory default status in India and Southeast Asia, as this will determine manufacturing volume allocation across CCS and CHAdeMO supply chains.
Market Dynamics
Silicon carbide power modules are compressing thermal management costs while simultaneously elevating power density thresholds, forcing incumbent rectifier architectures into obsolescence and redrawing supplier hierarchies across the charging stack.
Growth Catalysts
- Fleet electrification mandates:Logistics operators in California and Germany face binding zero-emission vehicle quotas that necessitate depot-scale DC fast charger deployment.
- US Inflation Reduction Act:Section 30C tax credits cover up to thirty percent of charging hardware and installation costs, redirecting institutional capital toward high-power corridor sites.
- GB/T standardization:China's state grid utilities are underwriting interprovincial highway charging corridors through unified connector and communication protocols.
Market Restraints
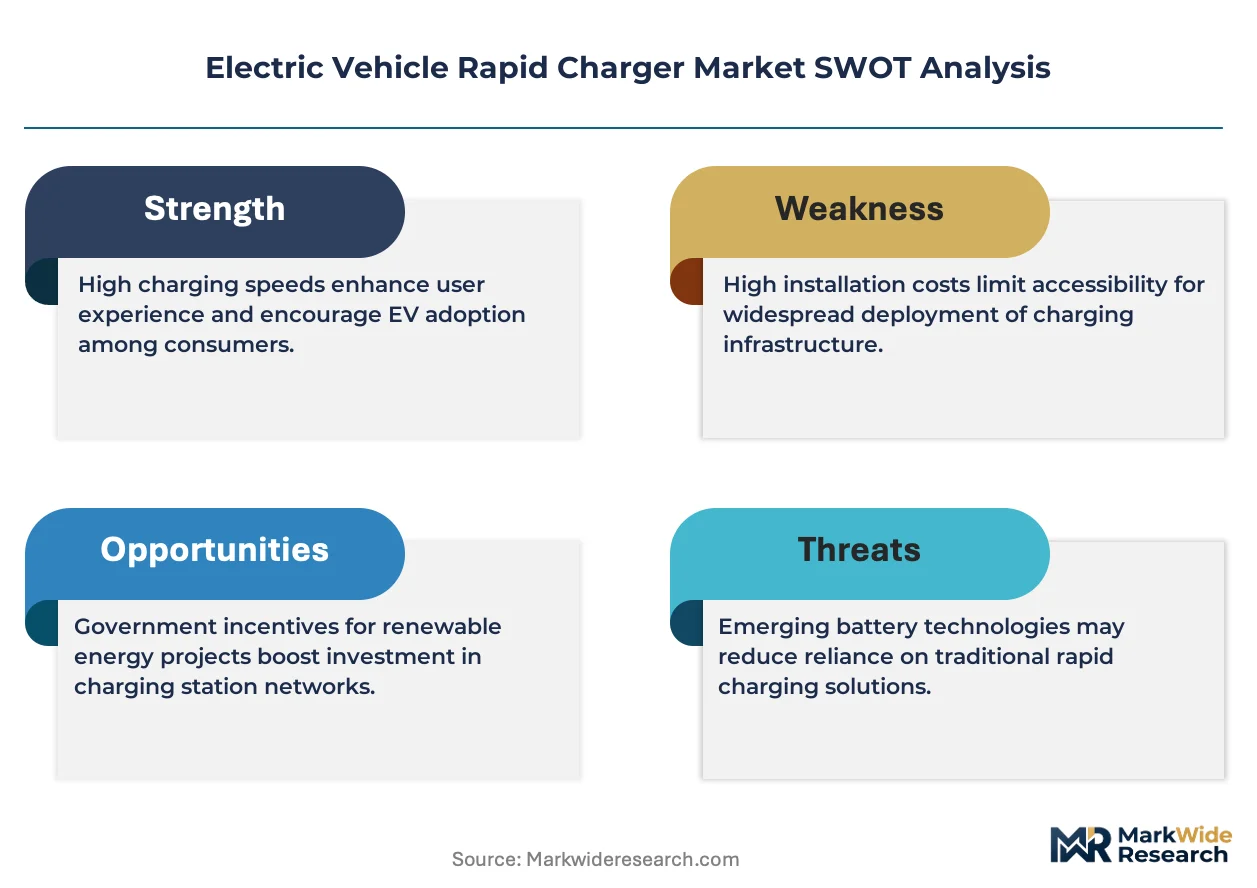
- Copper and rare earth price volatility:Liquid-cooled cable assemblies and permanent magnet components in power modules expose manufacturers to commodity input swings.
- Taiwan semiconductor concentration:Foundry capacity for silicon carbide wafers and gate driver ICs remains concentrated in a single geography, creating supply vulnerability.
- Grid interconnection queues:Utility approval timelines for multi-megawatt substations stretch eighteen to thirty-six months in jurisdictions with constrained transmission infrastructure.
Strategic Opportunities
- India connector standard arbitration:The Bureau of Indian Standards has yet to designate a default DC fast charging protocol, creating a window for CCS and GB/T lobbying.
- Wireless charging convergence:Dynamic inductive systems for bus rapid transit and automated guided vehicles in warehouse logistics are approaching commercial viability.
- EU CSRD carbon disclosure:Embodied emissions reporting requirements are filtering into charger network procurement specifications, favoring manufacturers with verified supply chain data.
Industry Challenges
- Power electronics engineering scarcity:Specialists in wide-bandgap semiconductor design command premium wages in Silicon Valley and Shenzhen simultaneously, constraining R&D scaling.
- Multi-protocol certification complexity:Hardware must simultaneously satisfy UL 2202, IEC 61851, and GB/T 27930 standards, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Rapid Charger Market |
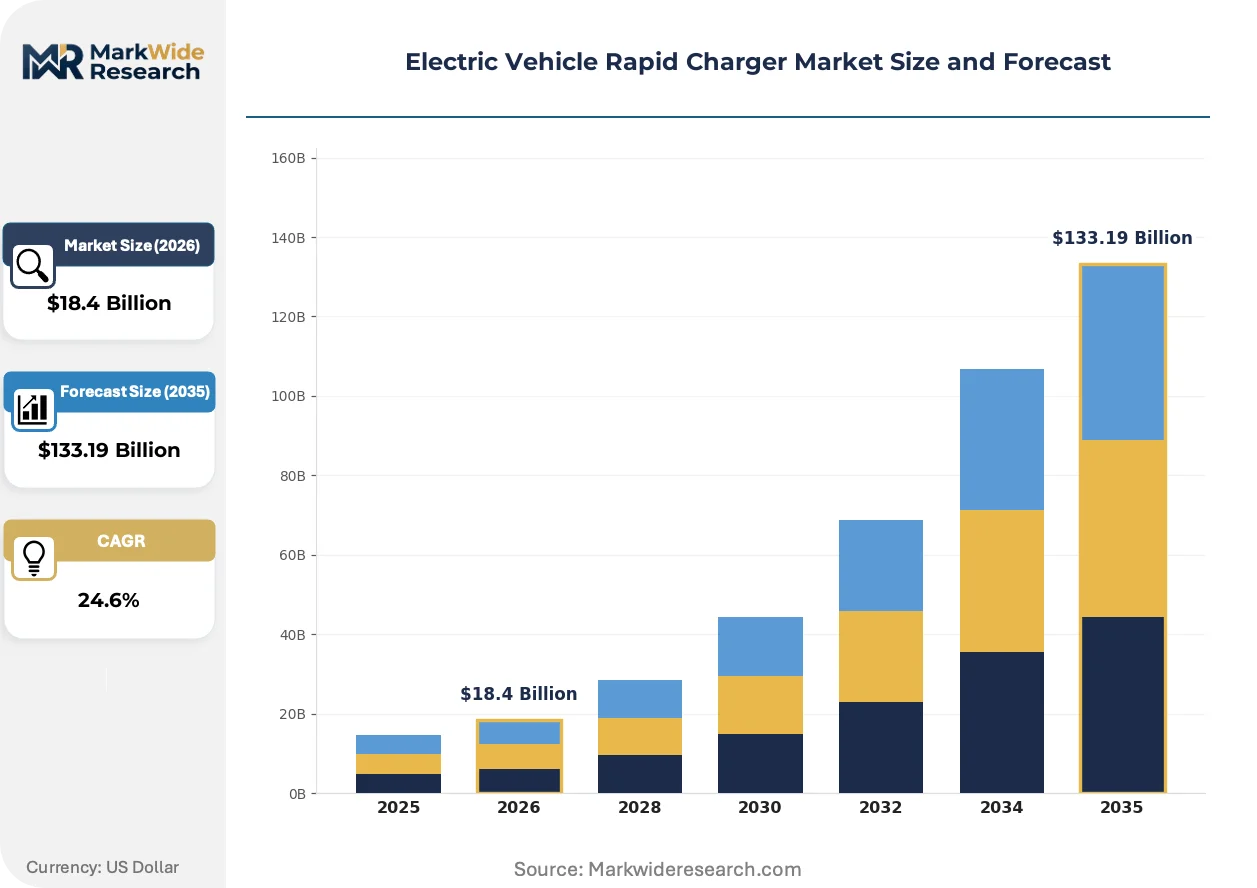
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $133.19 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Fast Charger, AC Charger, Portable Charger, Wall-mounted Charger End User: Public Charging Stations, Fleet Operators, Commercial Establishments, Residential Users Installation Type: Standalone Units, Networked Systems, Integrated Solutions, Smart Chargers Technology: CHAdeMO, CCS, Tesla Supercharger, Wireless Charging |
| Companies Covered | ChargePoint, ABB, Tesla, EVBox, EVgo, Electrify America, Delta Electronics, Tritium, TELD New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Rapid Charger Market Trends and Innovations
Modular power conversion architectures are fragmenting the traditional integrated rectifier market, enabling tiered performance configurations and compressing time-to-market for regional variants.
Silicon carbide MOSFETs enable switching frequencies above one hundred kilohertz, shrinking magnetic component volume by sixty percent versus silicon IGBT equivalents. Fleet operators in the Netherlands and Norway are specifying SiC-based chargers for new depot installations. The technology is decomposing the historical cost barrier between fifty-kilowatt and three-hundred-fifty-kilowatt product tiers.
NHTSA corridor-designation rules under the National Electric Vehicle Infrastructure program are mandating CCS connector compatibility and minimum power levels for federally funded highway sites. Equipment vendors must recertify existing product lines or risk exclusion from state procurement pools. California and Texas transportation authorities are prioritizing sites that demonstrate interoperability across multiple network operators.
Hardware-as-a-service contracting is displacing capital purchase models among municipal transit agencies and mid-size logistics operators. Leasing structures bundle installation, maintenance, and energy management software into per-kilowatt-hour or per-port monthly fees. This shift is most pronounced in Germany and the United Kingdom, where public sector budget constraints favor operational expenditure treatment.
Electric Vehicle Rapid Charger Market Segmentation
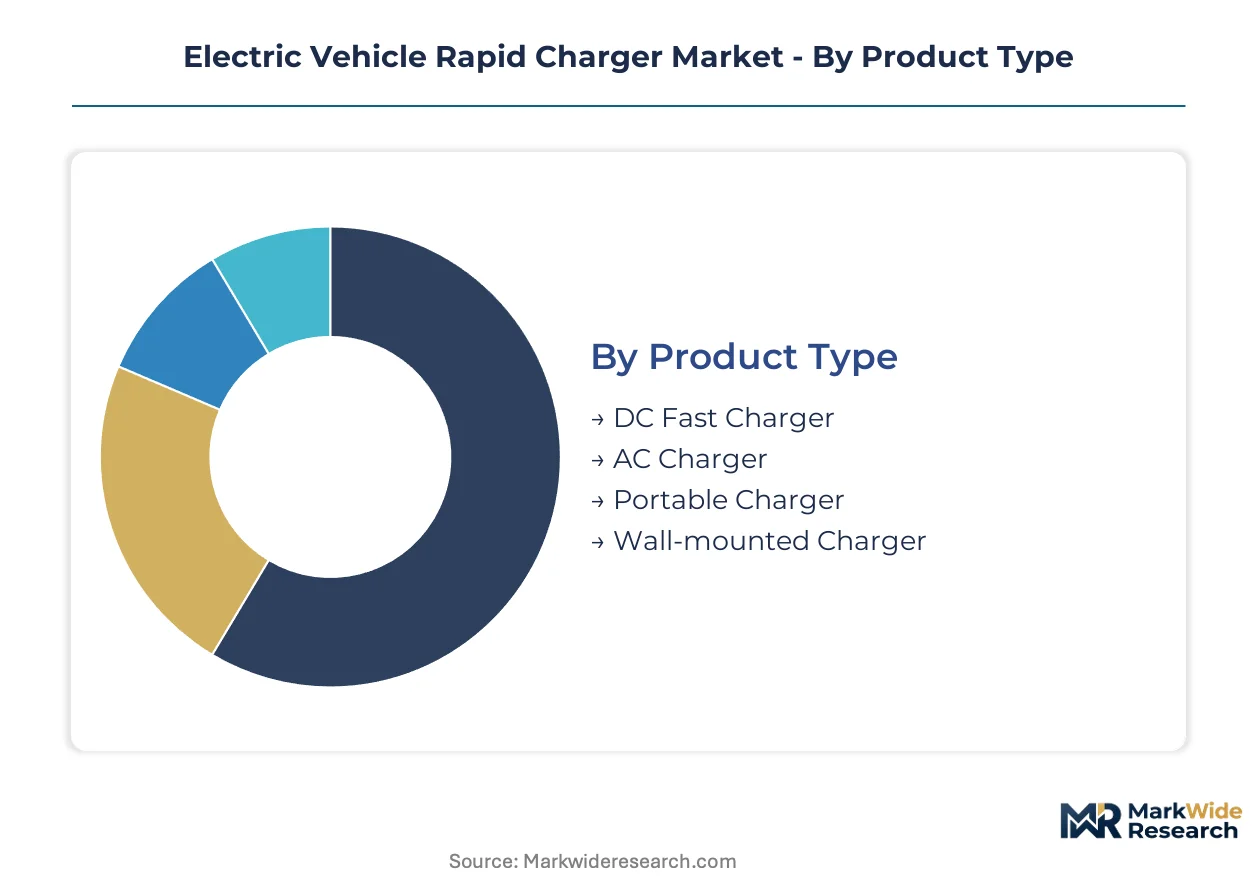
Segmentation in the electric vehicle rapid charger market reveals how power electronics architectures, connector protocols, and ownership models create distinct competitive arenas with diverging margin profiles and capital requirements.
Product Type:
DC Fast Chargers face acute substitution pressure from emerging wireless systems in fleet depot applications, while portable alternatives erode residential AC charger demand.
- DC Fast Charger:Converts grid AC to high-voltage DC exceeding 50 kW through silicon carbide rectifiers and liquid-cooled cable assemblies. Demand concentrates in California and Germany where fleet electrification mandates enforce depot-scale installations, though copper commodity volatility compresses hardware margins.
- AC Charger:Delivers alternating current directly to onboard vehicle converters at 7–22 kW, requiring simpler power electronics and lower installation costs. Residential uptake in China's eastern provinces dominates volume, constrained by GB/T standardization delays for bidirectional charging functionality.
- Portable Charger:Mobile emergency units with 3–7 kW output through standard household outlets.
- Wall-mounted Charger:Fixed residential and workplace installations with integrated cable management.
DC Fast Charger retains volume leadership; Portable Charger holds the steepest expansion curve.
End User:
Cost tier differentiation separates capital-intensive networked deployments from operational-expenditure fleet contracts reshaping procurement patterns.
- Fleet Operators:Logistics electrification mandates in California and Germany drive depot-scale DC fast charger rollouts with hardware-as-a-service contracting displacing capital purchases. Tightening zero-emission vehicle quotas compress installation timelines to eighteen-month utility interconnection windows.
- Public Charging Stations:Federally funded highway corridor sites under NHTSA rules mandate CCS compatibility and minimum power thresholds, excluding non-compliant vendors from state procurement pools. Interoperability demonstrations across multiple network operators now determine site prioritization in Texas and California.
- Commercial Establishments:Retail and hospitality locations seeking customer dwell-time extension through amenity charging.
- Residential Users:Single-family homeowners with overnight Level 2 charging needs.
Fleet Operators capture the fastest share gains; Public Charging Stations maintain installed base dominance.
Installation Type:
Supply concentration in power module manufacturing favors integrated solution providers with captive silicon carbide sourcing.
- Smart Chargers:Bidirectional units with vehicle-to-grid capability and dynamic load management algorithms. EU CSRD disclosure rules filter into procurement specifications for embodied carbon reporting, advantaging manufacturers with verified supply chain data.
- Networked Systems:Multi-port installations with centralized payment processing and remote diagnostics. China's state grid utilities underwrite interprovincial highway corridors through unified communication protocols, consolidating tender awards to domestic equipment vendors.
- Standalone Units:Single-point installations without backend connectivity requirements.
- Integrated Solutions:Turnkey packages combining hardware, installation, and energy management software.
Networked Systems anchor current deployment value; Smart Chargers climb the fastest on grid services revenue potential.
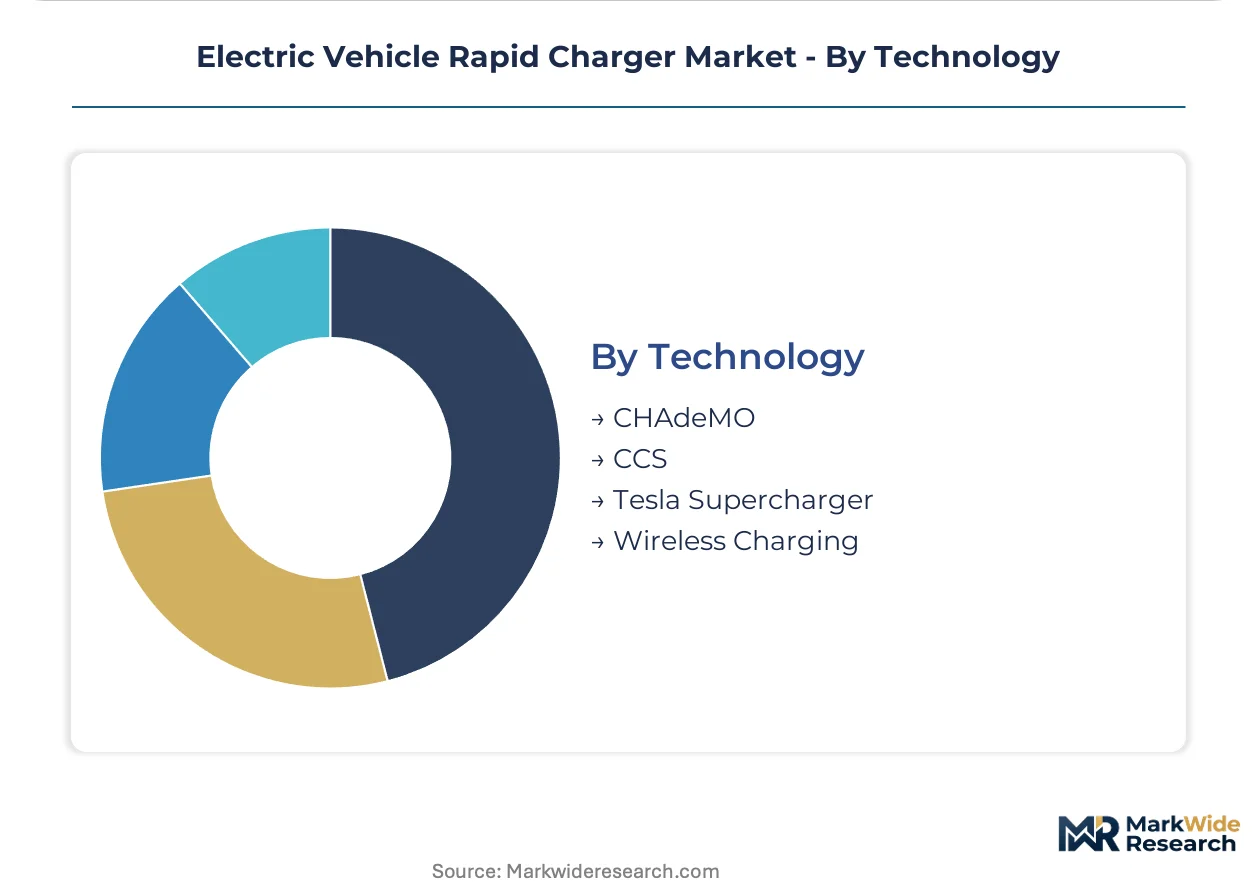
Technology:
Maturity gaps between field-proven conductive standards and inductive alternatives fragment R&D allocation across engineering teams.
- CCS:Combined Charging System with alternating current and DC pins in a single connector housing. NHTSA corridor-designation rules mandate CCS compatibility for federally funded highway sites, forcing recertification of existing product lines to maintain state procurement eligibility.
- Wireless Charging:Inductive power transfer through aligned transmitter and receiver coils. Dynamic systems for bus rapid transit in the Netherlands approach commercial viability, constrained by coil alignment tolerances and fifteen-percent efficiency losses versus conductive alternatives.
- CHAdeMO:Japanese-origin standard with bidirectional charging native to the protocol specification.
- Tesla Supercharger:Proprietary connector architecture with captive North American site development.
CCS retains connector volume leadership; Wireless Charging holds the steepest expansion curve contingent on efficiency improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB/T standardization mandates that compress deployment timelines across state-tendered highway corridors. The country's dual carbon goals accelerate provincial utility underwriting of urban fast-charging infrastructure.
United States
Fleet operators in California and Texas scale depot electrification ahead of binding zero-emission vehicle quotas. NHTSA corridor-designation rules under the National Electric Vehicle Infrastructure program mandate CCS compatibility and minimum power thresholds for federally funded highway sites. Silicon Valley power electronics specialists command premium wages as ABB and Tesla anchor North American deployment through integrated manufacturing and proprietary connector architectures.
Germany
Logistics operators face tightening EU Green Deal mandates that necessitate hardware-as-a-service contracting for depot-scale DC fast charger rollouts. The EU CSRD disclosure rules filter embodied carbon reporting into charger network procurement specifications. Bavaria and North Rhine-Westphalia concentrate manufacturing of silicon carbide power modules as automotive OEMs vertically integrate charging stack production.
China
State grid utilities underwrite interprovincial highway charging corridors through unified GB/T connector and communication protocols. The country's national standardization regulator consolidates tender awards to domestic equipment vendors controlling grid interconnection standards. Yangtze River Delta provinces concentrate demand as urban fast-charging corridors saturate Shanghai, Jiangsu, and Zhejiang metropolitan clusters.
India
The Bureau of Indian Standards has yet to designate a default DC fast charging protocol, creating competitive lobbying windows for CCS and GB/T proponents. The country's national automotive regulator evaluates connector interoperability alongside state-level electric vehicle policies in Maharashtra and Gujarat. Tamil Nadu and Karnataka industrial corridors attract power module assembly investments as original equipment manufacturers establish captive sourcing for domestic charger production.
Netherlands
Fleet operators specify SiC-based chargers for new depot installations as hardware-as-a-service contracting displaces capital purchase models among municipal transit agencies. The EU AI Act filters into smart charging algorithm procurement specifications for bidirectional vehicle-to-grid systems. Randstad logistics hubs concentrate dynamic inductive charging pilots for bus rapid transit approaching commercial viability.
Electric Vehicle Rapid Charger Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with power electronics engineering capability determining competitive position. The market structures around three archetypes: captive site developers with proprietary connector architectures, integrated industrial manufacturers with in-house silicon carbide sourcing, and state-tendered domestic champions controlling grid interconnection standards. Consolidation pressure intensifies as silicon carbide power modules compress thermal management costs and redraw supplier hierarchies. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers seek captive wafer supply and utility interconnection expertise.
Among North American charging network operators, ChargePoint and EVgo occupy positions within the networked systems tier, while Tesla exemplifies the captive site developer archetype through proprietary connector architecture and vertical control over deployment. ABB anchors the integrated industrial manufacturer tier, leveraging Swiss-Swedish heritage to sustain high-voltage rectifier production.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Tesla |
| EVBox |
| EVgo |
| Electrify America |
| Delta Electronics |
| Tritium |
| TELD New Energy |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer fabrication scale in Taiwan and South Korea compresses power module costs and redraws price floors across charger tiers, concentrating margin leverage among manufacturers with captive foundry relationships or long-term offtake agreements.
Pricing Analysis
Geographic price spreads separate North American CCS-certified hardware from Chinese GB/T-compliant equivalents, with California and Germany commanding fifteen to twenty percent premiums for UL 2202 and IEC 61851 dual-certification. Hardware-as-a-service contracting displaces capital purchase models among municipal transit agencies, compressing upfront revenue recognition while extending lifetime value capture. Fleet operators in the Netherlands exhibit highest price sensitivity due to standardized procurement pools, whereas integrated solution providers with captive site development face least pressure. Cost compression in liquid-cooled cable assemblies intensifies as copper commodity volatility feeds through bill-of-materials.
Supply Chain Analysis
Taiwan and South Korea anchor silicon carbide wafer fabrication and gate driver IC production, while China concentrates power module assembly and permanent magnet component manufacturing. The supply chain draws from copper rod, rare earth elements, and liquid-cooled cable assemblies as critical inputs. Single-source vulnerability in Taiwan semiconductor foundry capacity exposes manufacturers to geographic concentration risk. Distribution runs through state-tendered utility procurement channels in China, integrated solution providers in Germany, and networked system operators in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat arena where regulatory entrenchment through multi-protocol certification creates switching costs that protect incumbent positions against modular hardware commoditization.
For Market Incumbents: Shield installed base value by deepening backward integration into silicon carbide wafer supply and accelerating recertification timelines for NHTSA corridor eligibility. Wireless charging substitution in fleet depot applications threatens hardware incumbency. Certification investment in India's pending BIS standard arbitration secures future tender access. For New Entrants and Emerging Players: Anchor in hardware-as-a-service contracting for mid-size logistics operators in Germany and the United Kingdom where public sector budget constraints favor operational expenditure treatment. India's unresolved connector standard creates the most penetrable geography. Target interoperability demonstration capabilities as the primary go-to-market angle for state procurement pools in Texas and California. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among networked system operators with hardware-as-a-service contracting and energy management software bundling. Long-term viability centers on manufacturers with verified supply chain data for EU CSRD disclosure compliance. Acquisition target archetype: integrated solution providers with captive silicon carbide sourcing and utility interconnection expertise. Monitor India's BIS standard designation as the inflection indicator for manufacturing volume allocation across CCS and GB/T supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Shrinks thermal management costs and elevates power density thresholds above IGBT equivalents. |
| Hardware-as-a-Service Contracting | Captures municipal transit and logistics operators shifting from capital purchase to operational expenditure models. |
| Multi-Protocol Certification Investment | Secures NHTSA corridor eligibility and state procurement pool access under federally funded highway rules. |
| Backward Integration into Wafer Supply | Reduces exposure to Taiwan foundry concentration and locks in cost advantages across charger tiers. |
| India Connector Standard Lobbying | Determines manufacturing volume allocation and tender eligibility across CCS and GB/T supply chains. |
Research Methodology
Cross-validation between primary interviews with power electronics engineering directors, fleet procurement managers, and utility interconnection planners and secondary validation through SEC equipment vendor filings, NHTSA corridor designation records, and GB/T standardization bulletins anchors the qualitative findings. Bottom-up triangulation aggregates charger deployment data by state and provincial jurisdiction, while top-down reconciliation cross-checks against national electric vehicle adoption targets and infrastructure investment disclosures.
Sensitivity analysis around silicon carbide adoption curves, copper commodity price bands, and utility interconnection queue durations tests forecast robustness across the projection horizon. Segmentation dimensions span product type, connector protocol, end-user category, and installation model alongside regional regulatory cluster differentiation. CAGRs derive from fitted growth curves against historical deployment trajectories, with forecast inputs including fleet electrification mandate timelines and IRA Section 30C credit utilization rates.
Material uncertainties — commodity price volatility, Taiwan semiconductor supply disruption, and India BIS standard designation delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory continuity and technology substitution thresholds. Recalibration cycles align with material shifts in federal infrastructure funding allocations and provincial utility tender awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market