
 Electric Vehicle (EV) Charging Station Infrastructure Market | 2026-2036
Electric Vehicle (EV) Charging Station Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Charging Station Infrastructure Market Analysis
China's coastal manufacturing corridors is fragmenting as local governments compete for charging equipment factories and battery supply chain nodes. Tesla leverages its Supercharger network design to sustain proprietary connector dominance in North American highway corridors. ABB anchors European grid-integration projects with high-power charging systems that bridge utility-scale power management. ChargePoint competes across multiple installation types with open-network software that accommodates heterogeneous hardware.
Electric Vehicle Charging Station Infrastructure comprises power conversion systems, grid connection hardware, and communication protocols that deliver electrical energy from distribution networks to battery electric vehicles, typically operating at power levels from 3.7 kW residential AC to 350 kW DC fast charging with liquid-cooled cables. The primary commercial purpose centers on enabling vehicle electrification by reducing range anxiety and supporting fleet operational continuity. DC Fast Charging commands premium hardware margins due to semiconductor-intensive power electronics and thermal management requirements, while Home Charging sustains volume leadership through lower per-unit costs and simpler installation logistics. Fleet Operators represent the fastest-growing end user segment as logistics companies electrify delivery routes and require depot-based high-power clusters.
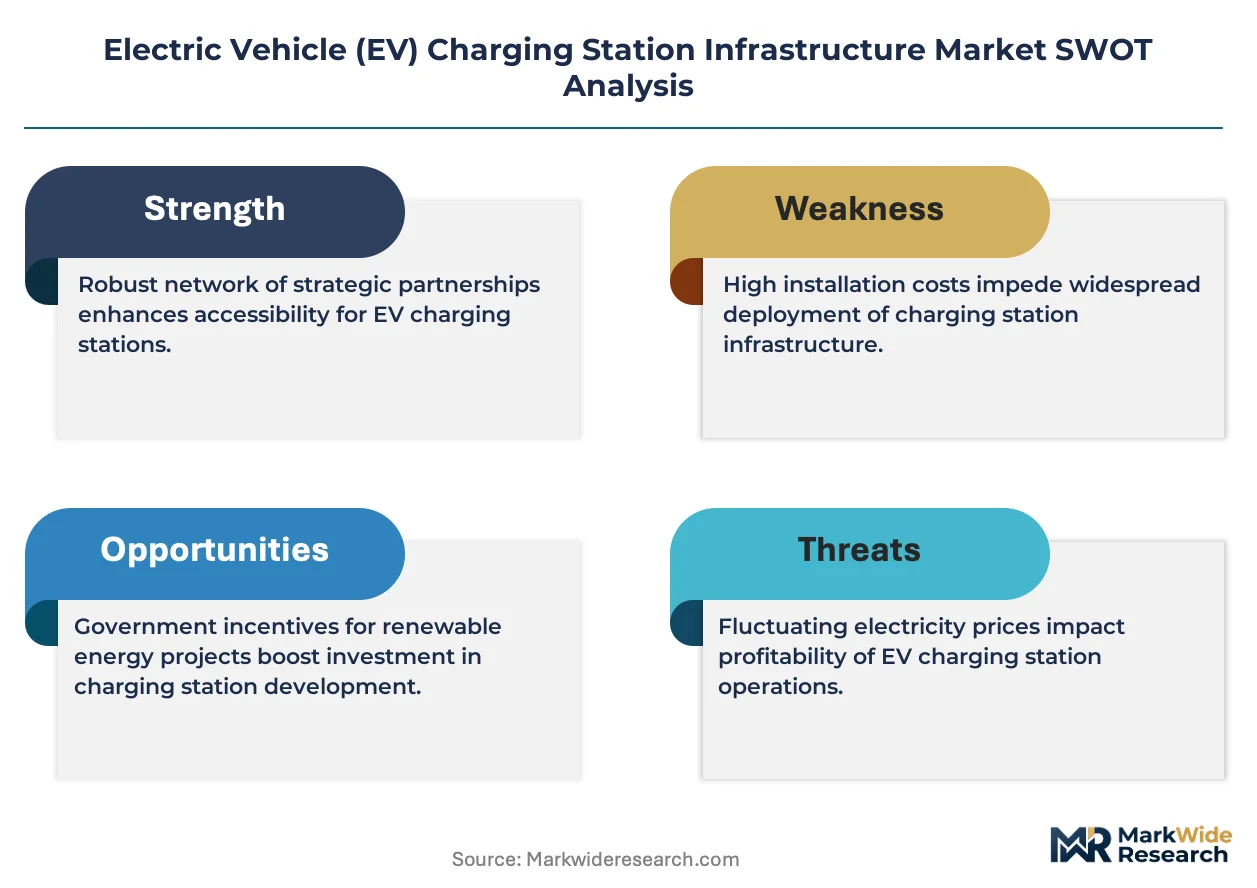
NHTSA guidelines shape US interoperability mandates, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices in charging station thermal systems. China's GB standards and MIIT directives enforce domestic connector protocols and grid-code compliance for imported equipment. Stakeholders must monitor evolving power grid capacity constraints and dynamic electricity pricing structures as determinants of charging network profitability.
Market Dynamics
Fleet electrification timelines are compressing installation windows for depot charging clusters, forcing hardware suppliers to synchronize manufacturing capacity with utility interconnection queues that now stretch 18-24 months in major metropolitan corridors.
Growth Catalysts
- California ZEV Mandates:The state's Advanced Clean Trucks regulation compels medium- and heavy-duty fleet operators to electrify, generating concentrated demand for high-power depot charging systems with 150 kW+ output capacity.
- Battery Chemistry Advancement:Lithium iron phosphate cells with 4C charging capability enable 10-80% recharge cycles under 20 minutes, validating business models for public fast-charging networks serving long-haul corridors.
- Grid-Interactive Standards:IEEE 1547-2018 compliance requirements for distributed energy resources are accelerating bidirectional charging hardware deployment, allowing vehicle-to-grid revenue streams for fleet asset owners.
Market Restraints
- Semiconductor Supply Concentration:Silicon carbide MOSFET fabrication capacity concentrates in Taiwan and South Korea, creating 26-32 week lead times for 350 kW DC fast-charging power modules.
- Copper and Aluminum Volatility:Liquid-cooled cable assemblies and busbar systems face input cost swings of 15-40% annually, compressing hardware margins for charging station OEMs.
- Permitting Fragmentation:Municipal electrical code variations across US counties create compliance friction, extending site approval timelines and deterring standardized network rollouts.
Strategic Opportunities
- India PLI Scheme:The country's production-linked incentive scheme for advanced chemistry cell manufacturing is attracting charging equipment suppliers to establish localized assembly for two- and three-wheeler fleet electrification.
- ISO 15118-20 V2X Protocol:Plug-and-charge authentication combined with automated demand response creates white space for software-integrated charging network operators to capture grid services revenue.
- High-Rise Residential Retrofit:Parking structure electrical upgrades in legacy buildings represent underpenetrated demand for load-managed AC charging systems with dynamic power allocation across multiple parking bays.
Industry Challenges
- Power Electronics Talent Scarcity:Design engineers with combined expertise in wide-bandgap semiconductors and thermal management command 40-60% salary premiums, constraining R&D velocity for mid-tier charging hardware manufacturers.
- UL 2594 Certification Backlogs:Third-party safety testing for residential EV supply equipment faces 14-18 month queues, delaying product launches and freezing working capital in pre-certified inventory.
- Legacy Grid Integration:Distribution transformers installed before 1990 lack capacity headroom for clustered fast-charging loads, forcing costly utility-side upgrades that fragment site economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Charging Station Infrastructure Market |
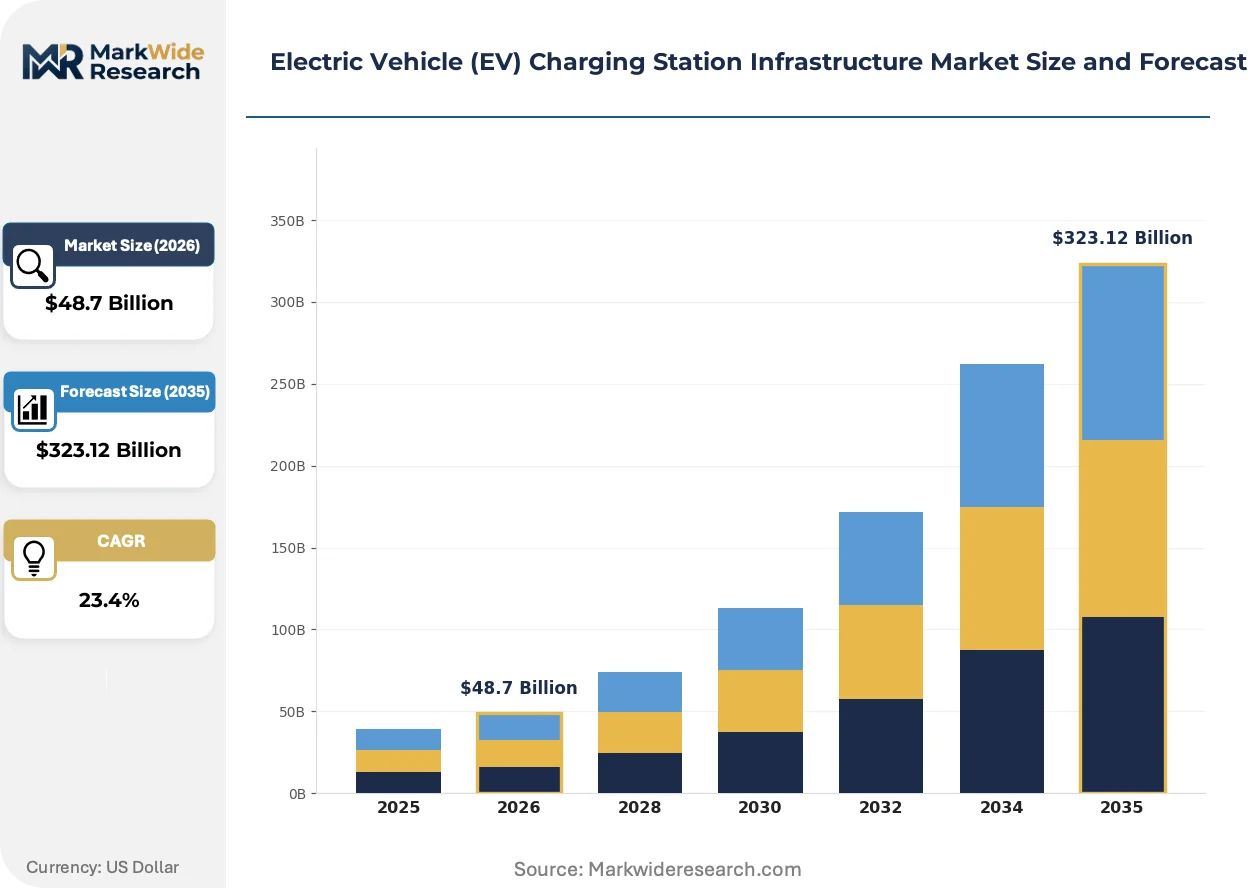
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $323.12 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: AC Charging, DC Fast Charging, Wireless Charging, Level 2 Charging End User: Consumers, Fleet Operators, Commercial Facilities, Government Agencies Installation Type: Public Charging, Home Charging, Workplace Charging, Destination Charging Power Output: Low Power, Medium Power, High Power, Ultra Fast |
| Companies Covered | Tesla, ChargePoint, ABB, EVBox, BYD, Shell, EVgo, Electrify America, bp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Charging Station Infrastructure Market Emerging Trajectories
Hardware commoditization pressures are redirecting competitive investment toward software-defined charging management and energy orchestration platforms that monetize grid flexibility rather than equipment margins alone.
Silicon carbide power conversion is collapsing thermal management system complexity in 350 kW DC fast chargers, reducing liquid cooling loop volume by 60% compared to silicon IGBT architectures. Fleet operators with 500+ vehicle deployments in Texas and Florida are specifying SiC-based systems exclusively for new depot installations. This compression is enabling modular, containerized charging stations that slash civil engineering costs for temporary or mobile deployment scenarios.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in charging station cooling systems, compelling manufacturers to adopt CO2 transcritical heat pumps or dielectric fluid immersion cooling. Equipment suppliers with European certification pipelines are redesigning thermal architectures to maintain power density under stricter greenhouse gas emission quotas. This regulatory pressure is most acute for German and Dutch highway corridor networks where 2027 compliance deadlines approach.
Charging network access is unbundling from vehicle purchase decisions as fleet procurement teams negotiate roaming agreements independent of OEM relationships. Commercial vehicle lessors in California and New York are contracting with multi-network software platforms rather than single-brand hardware providers. This behavioral shift is most visible in last-mile delivery segments where route flexibility demands interoperability across competing charging networks.
Electric Vehicle (EV) Charging Station Infrastructure Market Segmentation
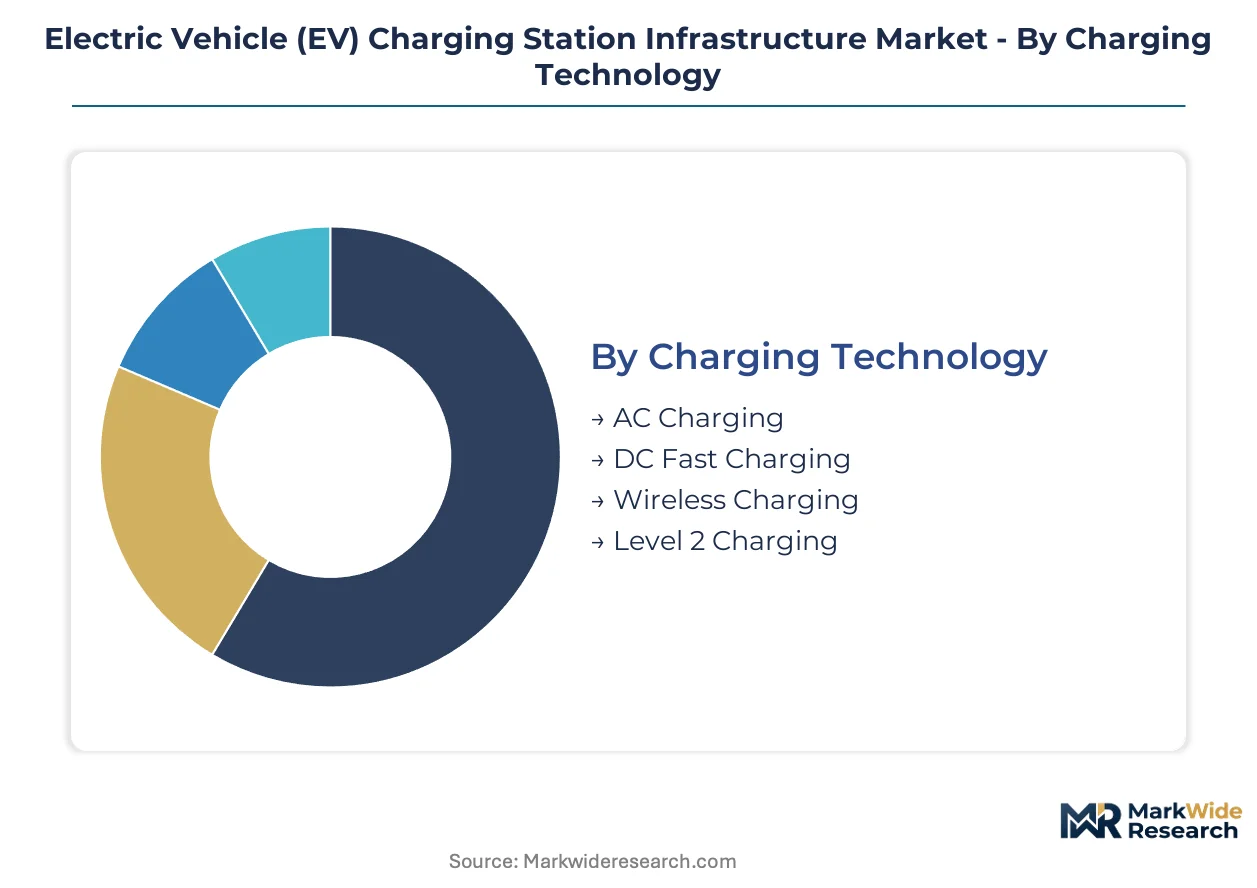
Segmentation in EV charging infrastructure reveals how hardware specifications, user requirements, and deployment contexts fragment purchasing decisions. Service intensity varies dramatically across segments—fleet depots demand 24/7 uptime guarantees while residential installations prioritize low-touch remote diagnostics.
Charging Technology:
After-sales service intensity peaks in high-power DC systems where thermal management failures require on-site technician dispatch within four hours.
- DC Fast Charging:Power electronics operate at 350 kW with liquid-cooled silicon carbide MOSFETs and active thermal monitoring. Demand concentrates along Texas and Florida highway corridors where fleet operators specify four-hour service response SLAs for 500+ vehicle deployments. Semiconductor supply constraints from Taiwan and South Korea extend replacement part lead times to 26-32 weeks.
- AC Charging:Residential and workplace units deliver 3.7-22 kW through onboard vehicle rectifiers with passive cooling architectures. California's Title 24 building codes mandate EV-ready circuitry in new construction, driving volume demand for Level 2 wallbox installations with minimal maintenance requirements.
- Wireless Charging:Inductive pad systems transfer power across 150-300mm air gaps at 11 kW with alignment tolerance compensation. Commercial pilots in Michigan and Sweden target autonomous vehicle fleets where connector wear elimination justifies 40% hardware cost premiums.
- Level 2 Charging:Mid-power AC systems bridge residential and light commercial applications with 240V split-phase connections. Workplace installations in Germany and the Netherlands dominate procurement volumes under EU corporate fleet electrification mandates.
AC Charging holds the largest share; momentum sits with DC Fast Charging.
End User:
Procurement authority separates consumer discretionary spending from fleet capital allocation cycles with multi-year electrification roadmaps.
- Fleet Operators:Logistics and delivery companies electrify medium-duty routes under California's Advanced Clean Trucks regulation, requiring depot clusters with 150 kW+ output and vehicle-to-grid bidirectional capability. Texas and Florida deployments specify exclusive silicon carbide architectures for new installations.
- Consumers:Residential buyers prioritize plug-and-play installation with smartphone scheduling and utility rate integration. Single-family homeowners in suburban US markets drive volume through retail channel purchases with self-installation options.
- Commercial Facilities:Retail and hospitality venues deploy destination charging to extend customer dwell time. Shopping centers in China's coastal manufacturing corridors anchor supply chain proximity for equipment procurement.
- Government Agencies:Municipal and federal procurement emphasizes domestic content requirements and Buy America compliance. NHTSA infrastructure guidelines reshape interoperability mandates for publicly funded installations.
Consumers represent the largest installed base; Fleet Operators are expanding most quickly.
Installation Type:
Site control and electrical access determine hardware specification flexibility and revenue model viability.
- Public Charging:Highway corridor and urban street-side installations require ruggedized enclosures with payment authentication and network roaming. China's GB standards enforce domestic connector protocols for imported equipment in coastal manufacturing zones.
- Home Charging:Garage and driveway deployments dominate unit volumes through lower per-unit costs and simplified permitting. Legacy electrical panels in pre-1990 US housing stock constrain 48-amp circuit upgrades without service entrance replacements.
- Workplace Charging:Employer-sponsored installations balance employee benefit costs with sustainability reporting metrics. Load-managed systems with dynamic power allocation across multiple parking bays address high-rise retrofit constraints.
- Destination Charging:Hotels, restaurants, and entertainment venues integrate charging as amenity infrastructure. Extended dwell times accommodate slower AC charging without high-power hardware premiums.
Home Charging holds the largest share; momentum sits with Public Charging.
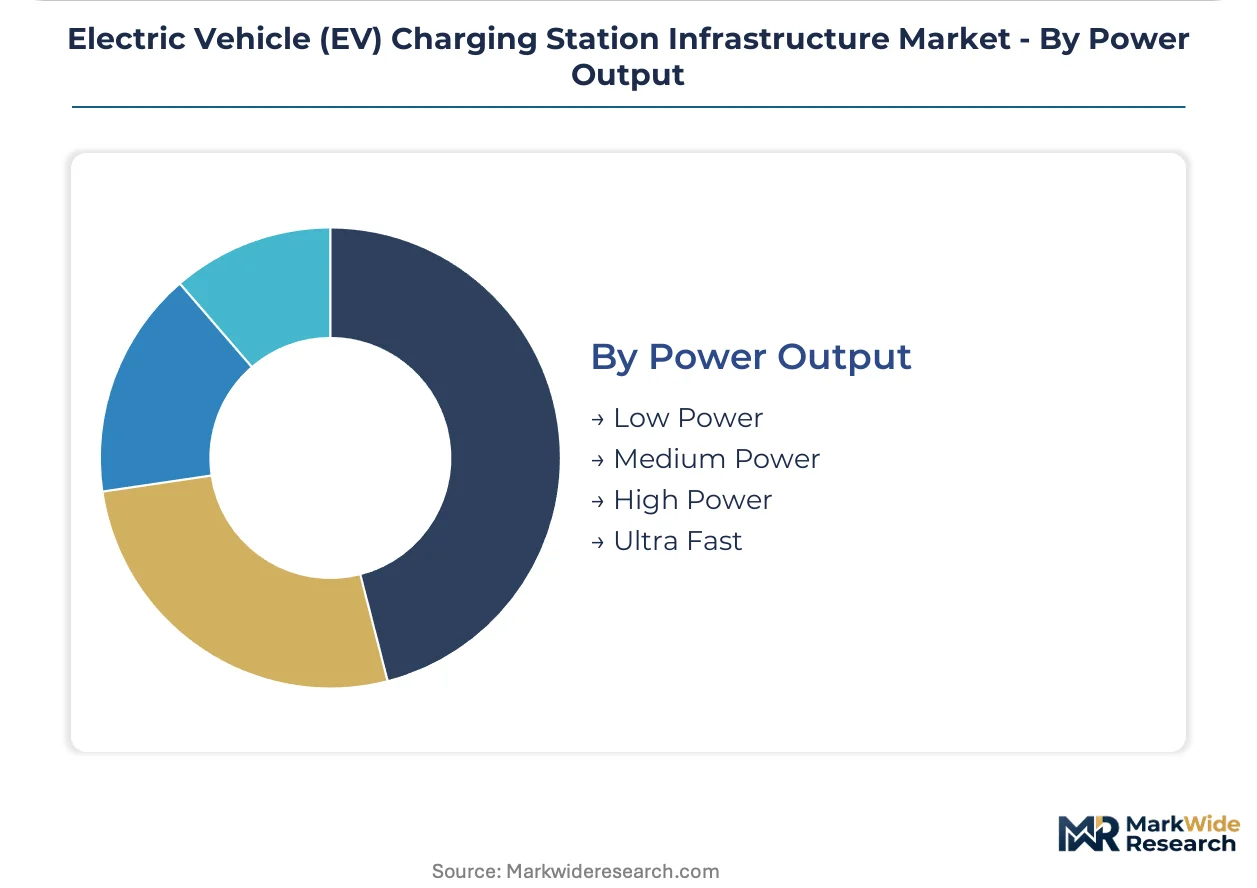
Power Output:
Thermal management complexity and semiconductor content scale non-linearly with power density requirements.
- High Power:150-350 kW systems enable 10-80% recharge cycles under 20 minutes for long-haul commercial routes. ABB anchors European grid-integration projects with utility-scale power management bridging distribution network constraints.
- Ultra Fast:350+ kW liquid-cooled architectures with 500A+ continuous current capability target premium passenger segments. Battery chemistry advancement in lithium iron phosphate cells with 4C charging validates business models for corridor networks.
- Medium Power:50-150 kW systems serve mixed-use applications with balanced hardware cost and recharge speed. Workplace and destination installations specify this tier for 2-4 hour dwell scenarios.
- Low Power:Under 50 kW residential and light commercial units prioritize volume manufacturing efficiency. Simpler installation logistics and minimal grid interconnection requirements sustain margin compression resilience.
Low Power holds the largest share; Ultra Fast is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes highway corridor DC fast charging for long-haul fleet electrification, while China concentrates manufacturing-scale deployment in coastal industrial zones, and Europe emphasizes grid-integrated bidirectional systems under stringent climate regulations.
United States
California's Advanced Clean Trucks regulation compels medium- and heavy-duty fleet operators to electrify, generating concentrated demand for 150 kW+ depot charging systems. NHTSA infrastructure guidelines reshape interoperability mandates for publicly funded installations. Texas and Florida anchor highway corridor deployment where fleet operators specify exclusive silicon carbide architectures for new installations.
China
Coastal manufacturing corridors in Guangdong and Jiangsu provinces fragment as local governments compete for charging equipment factories and battery supply chain nodes. MIIT directives enforce domestic GB connector protocols and grid-code compliance for imported equipment. BYD and CATL anchor supply chains in Shenzhen and Ningbo, driving equipment procurement volumes for export-oriented production.
Germany
Corporate fleet electrification mandates under EU Green Deal targets accelerate workplace and depot charging procurement. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in charging station cooling systems, compelling thermal architecture redesigns. ABB anchors European grid-integration projects with high-power charging systems bridging utility-scale power management in Bavaria and Baden-Württemberg.
India
Two- and three-wheeler fleet electrification creates localized demand for compact charging equipment. The country's production-linked incentive scheme for advanced chemistry cell manufacturing attracts charging equipment suppliers to establish assembly operations. Maharashtra and Gujarat host emerging industrial clusters where domestic fabricators scale production for last-mile delivery segments.
Netherlands
Corporate sustainability reporting requirements drive workplace charging installations with load-managed dynamic power allocation. EU corporate fleet electrification mandates dominate procurement volumes in the Randstad conurbation. Eindhoven Region hosts grid-interactive pilot programs testing ISO 15118-20 V2X protocol implementations for automated demand response revenue capture.
Electric Vehicle (EV) Charging Station Infrastructure Market Vendor Landscape
Capability concentration sits with power electronics specialists commanding wide-bandgap semiconductor expertise; scale advantage sits with integrated automotive-energy conglomerates deploying capital across manufacturing and network operations. The market structures around three tiers: vertically integrated vehicle OEMs with captive charging networks, pure-play charging equipment manufacturers with open-network software platforms, and energy majors leveraging retail fuel station real estate for electrification pivots. Dominant competitive moves include strategic partnerships between hardware suppliers and utility operators for grid interconnection queue management, plus geographic expansion through modular containerized station architectures that reduce civil engineering costs.
Within the integrated automotive tier, Tesla represents the proprietary network archetype with Supercharger infrastructure designed to sustain connector ecosystem dominance. Among open-network specialists, ChargePoint exemplifies software-defined platform strategies accommodating heterogeneous hardware across multiple installation types. In the energy-major pivot category, Shell and bp occupy positions bridging hydrocarbon retail legacy with electrification infrastructure deployment, leveraging existing real estate and customer payment relationships for charging network access.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVBox |
| BYD |
| Shell |
| EVgo |
| Electrify America |
| bp |
| Others |
Supply Flow & Price Mechanics
Shenzhen and Ningbo anchor silicon carbide MOSFET and power module fabrication, concentrating upstream capacity and translating semiconductor scarcity into hardware margin compression for DC fast-charging OEMs. Copper and aluminum price volatility in liquid-cooled cable assemblies feeds directly into tiered equipment pricing, with fleet procurement teams negotiating multi-year contracts to lock input costs.
Pricing Analysis
North American highway corridor deployments command 25-40% premiums over European workplace installations due to utility interconnection queue delays and ruggedized enclosure requirements. Three-tier pricing structure across premium SiC-based systems, standard silicon IGBT architectures, and economy AC wallbox units differentiates by thermal management complexity and certification tier. Cost compression in mid-power DC segments is intensifying because contract manufacturers in Taiwan and South Korea throttle capacity allocation to highest-margin automotive customers. Fleet operators with 500+ vehicle deployments exhibit lowest price sensitivity, prioritizing four-hour service response SLAs over per-unit hardware costs.
Supply Chain Analysis
Delta Electronics and Foxconn hold dominant contract manufacturing capacity for power conversion modules, with Hon Hai Precision anchoring high-volume AC charger assembly in Shenzhen and Taoyuan. Taiwan, South Korea, and China concentrate silicon carbide wafer and MOSFET fabrication, while Chile and Australia feed copper and lithium raw material streams. Single-source vulnerability concentrates in 350 kW liquid-cooled cable assemblies where two German suppliers control dielectric fluid formulation IP. Distribution runs through direct OEM-fleet relationships for depot installations and electrical distributor networks for residential and workplace segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV charging infrastructure is approaching a platform-economics inflection where ISO 15118-20 plug-and-charge protocols unbundle network access from hardware ownership, reshaping competitive moats around software orchestration rather than proprietary connector ecosystems.
For Market Incumbents: Pre-empt margin erosion in DC fast-charging hardware by securing captive silicon carbide wafer supply through equity partnerships with Taiwanese foundries. Consolidate service infrastructure across Texas and Florida corridor networks to defend against modular containerized entrants offering temporary deployment alternatives. Reinforce software platform stickiness through V2X protocol certification investment ahead of IEEE 1547-2018 compliance deadlines. For New Entrants and Emerging Players: Establish a beachhead in high-rise residential retrofit segments where legacy parking structure electrical constraints create demand for load-managed AC systems with dynamic power allocation. Target municipal procurement in US counties with fragmented permitting codes where standardized network rollouts face compliance friction. Pursue white-label manufacturing partnerships with established power electronics specialists to bypass UL 2594 certification backlogs. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive OEM captive charging divisions seeking to monetize non-core infrastructure assets as platform unbundling accelerates. Prioritize acquisition of software-defined charging management platforms with ISO 15118-20 certification pipelines and utility interconnection queue management capabilities. Watch for inflection signals in bidirectional charging hardware deployment volumes under FERC Order 2222 implementation.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Supply Agreement | Secures wide-bandgap semiconductor allocation from TSMC or GlobalFoundries for 350 kW module production. |
| Utility Partnership | Accelerates grid interconnection queue positioning through co-development with FERC-jurisdictional distribution operators. |
| V2X Protocol Certification | Enables vehicle-to-grid revenue capture under IEEE 1547-2018 compliance for fleet asset owners. |
| Containerized Deployment | Reduces civil engineering costs for temporary highway corridor installations in Texas and Florida markets. |
| Software Platform Integration | Captures roaming agreement value as fleet procurement unbundles network access from OEM relationships. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of NHTSA infrastructure guidance documents, FERC interconnection queue databases, and EU Green Deal regulatory filings. The study combined structured interviews with fleet electrification directors, utility distribution planning officers, charging equipment procurement managers, and power electronics R&D leads with validation through SEC 10-K disclosures, EIA electricity demand projections, and customs trade data. Bottom-up equipment shipment tallies and top-down grid capacity modeling were triangulated against MIIT production statistics and EPA vehicle registration databases.
Forecast inputs span charging technology segmentation, power output tiering, installation type economics, and end-user procurement cycles across the projection horizon. The analytical framework modeled penetration trajectories for DC fast charging, AC systems, and wireless architectures alongside fleet operator, consumer, and commercial facility demand archetypes. CAGRs were derived from installed base growth rates, replacement cycle assumptions, and grid interconnection capacity expansion schedules. Semiconductor supply constraints, copper price volatility, and permitting timeline variations were stress-tested as sensitivity inputs.
Stress conditions across utility interconnection queue durations, silicon carbide wafer allocation priorities, and F-Gas Regulation compliance deadlines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding battery chemistry advancement timelines and fleet electrification mandate enforcement intensity. Cross-checking against IEA Global EV Outlook infrastructure deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market