
 EV Charging Station Market | 2026-2036
EV Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Station Market Analysis
The gap between premium smart-grid-integrated hardware and commodity AC units is expanding as fleet operators demand load-balancing software while residential buyers prioritize cost minimization. ABB leverages its power-electronics heritage to dominate high-reliability DC fast charger deployments across European highway corridors. Tesla sustains proprietary connector ecosystems and captive charging networks that lock in brand loyalty. Shell competes through forecourt conversion, repositioning retail fuel sites into multi-fuel mobility hubs with ultra-fast charging bays.
EV charging stations are electromechanical systems that convert grid alternating current to direct current matched to battery chemistry, with DC fast chargers delivering 50 kW to 350 kW through liquid-cooled cables and CCS or NACS connectors to replenish electric vehicle packs in 15–45 minutes. Their primary commercial purpose is to extend vehicle range utility by enabling energy transfer at destinations where vehicles dwell or along corridors where drivers travel. DC fast chargers command the steepest capital outlays but capture the strongest utilization rates and per-session revenue at highway and fleet locations. Smart grid integrated technology is gaining share as utilities mandate demand-response compatibility to qualify for interconnection incentives. Residential charging remains the largest volume segment though per-unit economics trail commercial applications.
The US NHTSA and EPA coordinate fuel-economy credit rules that effectively require OEMs to subsidize charging infrastructure buildout, while the EU F-Gas Regulation and CE marking framework constrain coolant selection and electrical safety certification for equipment sold across member states. China's GB standards and MIIT edicts mandate domestic connector protocols and grid-interoperability testing that foreign manufacturers must satisfy for market access. Stakeholders must track which connector standard achieves jurisdictional dominance in North America as the NACS-CCS transition determines hardware obsolescence risk and retrofit liability.
Market Dynamics
Fleet electrification mandates and proprietary connector standard battles are compressing deployment timelines while fragmenting hardware procurement strategies across highway, depot, and residential use cases.
Growth Catalysts
- EU Green Deal ICE phase-out mandates:Germany, France, and the Netherlands have codified charger deployment obligations that accelerate public infrastructure buildout along transit corridors and urban centers.
- State grid upgrades in China's eastern coastal provinces:Municipal procurement timelines compress installation cycles as SOEs coordinate transmission reinforcement with charging station commissioning.
- Load-balancing software integration:Fleet operators now require demand-response compatibility to qualify for utility interconnection incentives, pulling smart-grid-enabled hardware into depot deployments.
Market Restraints
- Copper and silicon carbide cost volatility:Power electronics components face input price swings that squeeze DC fast charger manufacturing margins and delay project financing.
- Connector standard fragmentation:The unresolved NACS-CCS transition in North America creates hardware obsolescence risk and retrofit liability for capital-intensive charging assets.
- Grid interconnection queue congestion:Utility approval timelines for high-capacity DC installations extend 18-36 months in transmission-constrained regions, throttling deployment velocity.
Strategic Opportunities
- Multi-fuel mobility hub conversion:Forecourt operators are repositioning retail fuel sites with ultra-fast charging bays alongside hydrogen and biofuel dispensers to capture stranded real estate value.
- Vehicle-to-grid (V2G) bidirectional charging:Convergence of battery storage protocols and grid management software enables fleet operators to monetize parked vehicle capacity as distributed energy resources.
- Residential solar-charger bundling:Home energy management platforms are integrating Level 2 units with rooftop PV and home battery systems, opening new channel partnerships between automotive OEMs and solar installers.
Industry Challenges
- Power electronics engineering talent scarcity:Liquid-cooled cable design and high-frequency converter optimization require specialized expertise that outpaces vocational training pipeline output.
- CE marking and F-Gas compliance complexity:Coolant selection constraints and electrical safety certification timelines delay European product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Station Market |
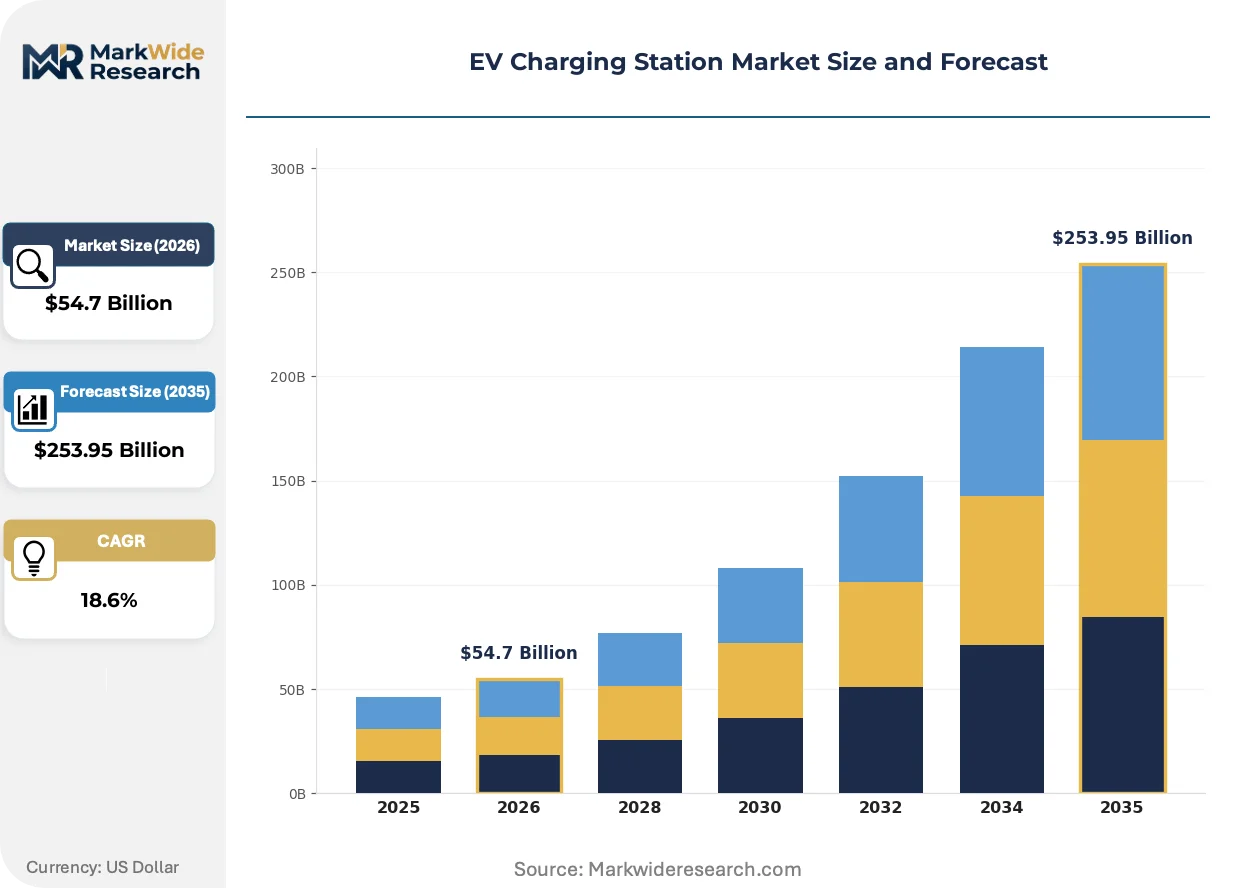
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $253.95 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Battery Swapping Stations Technology: Plug-In, Inductive Charging, Conductive Charging, Solar-Powered, Smart Grid Integrated, Ultra-Fast Charging Application: Public Charging, Fleet Charging, Workplace Charging, Residential Charging, Highway Charging End User: Commercial Operators, Municipal Corporations, Fleet Operators, Real Estate Developers, Hospitality Providers |
| Companies Covered | ChargePoint, ABB, Tesla, EVBox, Shell, BYD, EVgo, BP, Wallbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Station Market Emerging Trajectories
Hardware-software decoupling is accelerating as charger OEMs unbundle power electronics from network management platforms, enabling third-party software overlays and subscription revenue models.
Silicon carbide (SiC) power semiconductors are rewriting thermal management requirements for 350 kW+ DC fast chargers by enabling higher switching frequencies with reduced cooling overhead. European highway corridor operators are adopting SiC-based units to minimize footprint and maintenance intervals. This technology compression is collapsing the physical size differential between 150 kW and 350 kW hardware, rewriting site design economics for constrained urban locations.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in liquid-cooled charging cables, forcing manufacturers to qualify CO2 or hydrocarbon alternatives. Equipment suppliers must retest thermal performance under revised safety protocols before CE marking renewal. This regulatory friction most affects 350 kW+ highway deployments where coolant reliability directly determines session throughput and warranty exposure.
Fleet procurement teams are consolidating charging infrastructure decisions under centralized sustainability officers who negotiate network-wide service contracts rather than site-by-site hardware purchases. This buyer concentration is displacing fragmented municipal procurement and pushing OEMs toward energy-as-a-service offerings with guaranteed uptime clauses. The shift is most visible in North American last-mile delivery electrification programs where Amazon, FedEx, and UPS units coordinate charging strategy at the holding company level.
EV Charging Station Market Segmentation
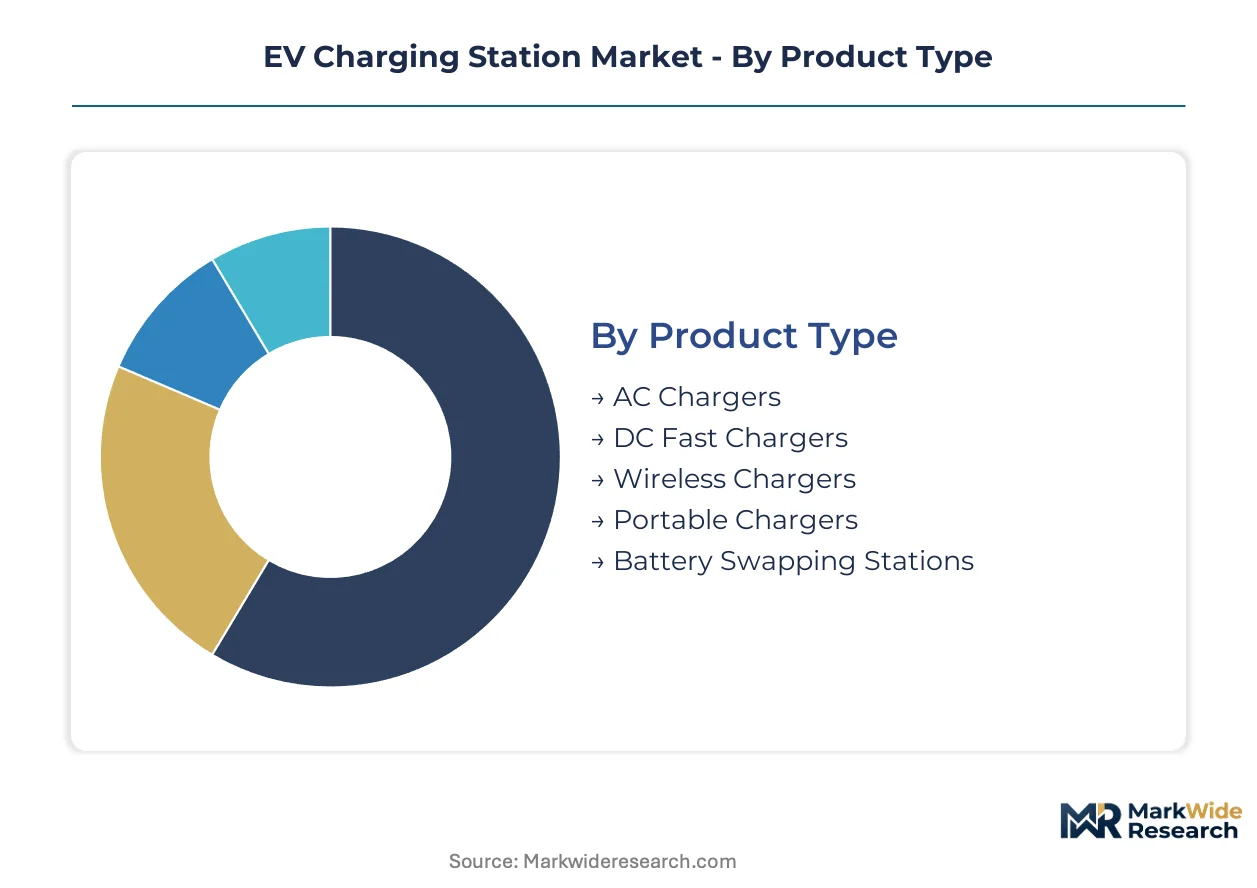
Segmentation in the EV charging station market reveals divergent hardware requirements across power levels, connectivity protocols, and duty cycles. Procurement patterns fragment sharply between fleet operators optimizing for depot utilization and residential buyers minimizing upfront capital outlay.
Product Type:
Capital intensity and session throughput drive buyer selection between AC and DC hardware tiers.
- AC Chargers:Level 1 and Level 2 units deliver 3.3 kW to 19.2 kW through onboard vehicle rectifiers, requiring minimal site electrical upgrades. Residential installations in Germany and the Netherlands concentrate here due to overnight dwell-time abundance and subsidy eligibility constraints.
- DC Fast Chargers:Off-board power electronics convert grid AC to DC at 50 kW to 350 kW, enabling 15–45 minute replenishment cycles. Highway corridor deployments across France and California prioritize these units for intercity range extension, though silicon carbide cost volatility squeezes manufacturing margins.
- Wireless Chargers:Inductive pad systems eliminate connector wear but suffer efficiency losses and higher capital costs per kilowatt.
- Portable Chargers:Emergency backup units with 120V/240V flexibility target apartment dwellers lacking fixed parking infrastructure.
- Battery Swapping Stations:Automated exchange systems serve electric taxi and delivery fleets in China's eastern coastal provinces where state grid upgrades support high-turnover depot designs.
AC chargers lead on scale; DC fast chargers lead on momentum.
Technology:
Interoperability mandates and utility incentive structures determine which power transfer and grid communication protocols achieve procurement preference.
- Plug-In:Conductive cable-and-connector systems dominate with CCS, NACS, and GB/T standards competing for jurisdictional dominance. The unresolved NACS-CCS transition in North America creates hardware obsolescence risk for capital-intensive assets.
- Inductive Charging:Magnetic resonance systems enable automated alignment for autonomous vehicle fleets and premium residential installations.
- Conductive Charging:Pantograph and overhead catenary systems serve electric bus depots in France and Germany with high-utilization duty cycles.
- Solar-Powered:Off-grid DC coupling with rooftop PV reduces interconnection queue dependency for remote highway locations.
- Smart Grid Integrated:Demand-response compatibility qualifies operators for utility interconnection incentives and time-of-use rate arbitrage.
- Ultra-Fast Charging:350 kW+ liquid-cooled cable systems with silicon carbide power semiconductors minimize footprint for constrained urban sites.
Plug-in systems anchor installed base; smart grid integrated configurations are climbing the fastest.
Application:
Dwell-time economics and utilization rate expectations segment deployment locations by revenue model and ownership structure.
- Public Charging:Curbside and parking garage installations serve sporadic demand with lower utilization but higher per-session pricing power.
- Fleet Charging:Depot-based systems for electric bus and delivery truck operators achieve 70%+ utilization through scheduled overnight and opportunity charging windows.
- Workplace Charging:Employer-subsidized Level 2 units capture daytime dwell periods with loyalty-program integration.
- Residential Charging:Single-family home installations represent the largest volume segment though per-unit economics trail commercial applications.
- Highway Charging:Corridor fast-charging networks require redundant power electronics and liquid-cooled cables to minimize driver dwell time.
Residential charging dominates volume; fleet charging commands margin expansion.
End User:
Procurement centralization and service contracting sophistication vary sharply across public, private, and institutional buyers.
- Commercial Operators:Retail fuel forecourt conversions and parking network expansions reposition stranded real estate into multi-fuel mobility hubs with ultra-fast charging bays.
- Municipal Corporations:Transit authority electrification programs in Germany, France, and the Netherlands codify charger deployment obligations along urban corridors.
- Fleet Operators:Amazon, FedEx, and UPS units coordinate charging strategy at holding company level, consolidating infrastructure decisions under centralized sustainability officers.
- Real Estate Developers:Pre-wiring mandates in California and New York drive Level 2 installation in new multi-family construction.
- Hospitality Providers:Hotels and resorts leverage charging amenities to capture premium guest segments with extended dwell times.
Fleet operators lead on contract scale; commercial operators show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys charging infrastructure at triple the velocity of Germany despite comparable fleet electrification targets, while the United States struggles with interconnection queue delays that European markets have largely resolved through streamlined permitting.
China
State Grid Corporation coordinates transmission upgrades with municipal procurement timelines across eastern coastal provinces, compressing installation cycles for depot-based fleet operators. MIIT edicts mandate GB/T connector protocols and grid-interoperability testing that foreign manufacturers must satisfy for market access. Shenzhen and Shanghai clusters concentrate battery swapping infrastructure for electric taxi and delivery fleets.
Germany
The KBA enforces ICE phase-out mandates that codify charger deployment obligations along Autobahn corridors and urban transit routes. Federal network agency regulations streamline grid interconnection approvals for high-capacity DC installations compared to transmission-constrained neighboring markets. Bavaria and North Rhine-Westphalia host the densest concentrations of ultra-fast charging hubs at converted retail fuel forecourts.
United States
NHTSA and EPA coordinate fuel-economy credit rules that effectively require OEMs to subsidize charging infrastructure buildout across highway corridors. FERC jurisdiction over interstate transmission creates procedural friction that extends utility approval timelines 18-36 months in constrained regions. California and Texas lead state-level deployment through preemptive building codes and utility rate reform.
France
The EU Green Deal translates into national legislation that accelerates public infrastructure buildout through concession agreements with highway operators. ANSM and environmental regulators enforce F-Gas Regulation constraints on coolant selection for liquid-cooled charging cables. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate electric bus depot electrification programs under transit authority procurement.
Netherlands
Municipal corporations leverage holding company structures to consolidate charging infrastructure decisions under centralized sustainability officers. CE marking frameworks and electrical safety certification timelines remain predictable relative to southern European markets. The Randstad metropolitan cluster exhibits the highest per-capita AC charger density through aggressive residential subsidy programs.
EV Charging Station Market Vendor Landscape
Top-tier vendors anchor highway corridor and fleet depot deployments, while mid-tier specialists compete for residential and workplace installation contracts. The vendor base stratifies across power electronics heritage firms, captive automotive networks, and energy retailer conversions. Strategic archetypes include utility-aligned hardware OEMs, forecourt repositioning fuel retailers, and integrated automotive charging network operators. Competitive intensity concentrates on silicon carbide supply chain security and software platform unbundling.
Within the integrated automotive tier, Tesla exemplifies proprietary connector ecosystem lock-in through captive network control. Among European power electronics specialists, ABB occupies a position representing high-reliability DC fast charger heritage across continental highway infrastructure. Shell anchors the energy retailer conversion archetype, repositioning stranded retail fuel real estate into multi-fuel mobility hubs with ultra-fast charging bays.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Tesla |
| EVBox |
| Shell |
| BYD |
| EVgo |
| BP |
| Wallbox |
| Others |
Supply Flow & Price Mechanics
The premium-commodity hardware divergence between smart-grid-integrated DC fast chargers and basic AC residential units manifests in parallel supply chain configurations that source silicon carbide power modules from distinct tier-one semiconductor foundries while commodity units draw from standardized component distributors.
Pricing Analysis
Capacity additions in China's eastern coastal provinces are reshaping price floors for DC fast charger power electronics as domestic silicon carbide wafer output expands. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled 350 kW highway units with CE marking and F-Gas compliance from uncertified depot hardware and basic Level 2 residential installations. Price erosion runs through the AC residential segment as municipal subsidy programs in the Netherlands and Germany cap reimbursement ceilings. Fleet operators show least price sensitivity due to energy-as-a-service contracting, while independent commercial operators face acute margin pressure from interconnection queue delays.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon, FedEx, and UPS fleet electrification programs, while distributor networks serve fragmented municipal procurement. Manufacturing concentrates in China, Germany, and South Korea for power electronics assembly, with silicon carbide substrates sourcing from Japan and the United States. Copper busbar and liquid-cooled cable assemblies draw from specialized automotive tier suppliers in Mexico and Eastern Europe. Single-source vulnerability sits with silicon carbide MOSFET supply where qualification timelines for alternative vendors extend 18-24 months.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV charging station market compounds steadily as fleet electrification mandates hardwire infrastructure demand into regulatory compliance timelines across Germany, France, and California.
For Market Incumbents: Anticipate connector standard consolidation by securing dual-protocol hardware architectures that bridge NACS and CCS ecosystems without full retrofit liability. Deepen backward integration into silicon carbide supply through long-term offtake agreements with Japanese substrate manufacturers to defend margin position against commodity power module entrants. For New Entrants and Emerging Players: Bidirectional V2G software platforms offer a technology-first wedge into fleet depot deployments where incumbent hardware OEMs lack grid-interoperability expertise. Target underpenetrated workplace charging in multi-tenant commercial real estate where pre-wiring mandates in New York and California create installed-base expansion opportunities. Pursue white-label energy management partnerships with solar installers for residential solar-charger bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where regional charging network operators lack scale to absorb interconnection queue costs and software development overhead. The market supports long-term infrastructure holding strategies given regulatory ICE phase-out immutability. Monitor NACS adoption velocity at non-Tesla OEMs as the primary signal for hardware obsolescence risk and stranded asset exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures power semiconductor access from Japanese foundries for 350 kW highway deployments. |
| Dual-Protocol Hardware Certification | Enables NACS-CCS interoperability that future-proofs capital-intensive corridor installations. |
| Fleet Energy-as-a-Service Launch | Captures Amazon and UPS depot demand through guaranteed uptime contracting. |
| Multi-Fuel Forecourt Conversion | Repositions Shell and BP retail sites with hydrogen and ultra-fast charging bays. |
| V2G Grid Integration Partnership | Monetizes parked vehicle capacity through utility demand-response programs in California. |
Methodological Framework
Coverage spans China, Germany, the United States, France, and the Netherlands, with primary inputs from each market's fleet sustainability officers, utility interconnection planners, charging hardware procurement leads, and power electronics engineering directors. Secondary validation draws from NHTSA fuel-economy credit filings, EPA regulatory dockets, EU F-Gas Regulation implementation guidance, State Grid Corporation infrastructure reports, and MIIT GB standard updates. Bottom-up unit deployment estimates triangulate against top-down fleet electrification mandate targets.
Granularity-level modeling disaggregates volume and value across power level tiers, connector protocol types, grid-interoperability certification levels, application use cases, and end-user procurement centralization patterns. CAGRs derive from logistic diffusion curves fitted to fleet penetration thresholds and residential stock turnover rates. Key inputs include silicon carbide cost trajectories, utility rate reform schedules, and municipal procurement pipeline visibility.
The model holds under stable regulatory enforcement of ICE phase-out mandates; deviation in connector standard adoption velocity or grid interconnection approval timelines would shift deployment trajectories. Forecasts embed assumptions regarding silicon carbide supply expansion and F-Gas Regulation compliance cost pass-through. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Electric Car Charging Pile Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market