
 Public EV Charger Market | 2026-2036
Public EV Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Public EV Charger Market Insights
The Inflation Reduction Act is restructuring capital deployment timelines for public charging infrastructure across the United States. ChargePoint leverages its software-integrated network to dominate highway and urban corridor positioning. Tesla sustains proprietary connector advantages through its Supercharger footprint and recent standardization moves. ABB anchors European fast-charging supply with high-power modular systems for fleet and retail applications.
A public EV charger is an electric power dispensing station designed to deliver controlled AC or DC electrical energy to battery electric vehicles, typically operating at outputs from 3.7 kW (Level 2) to 350 kW (ultra-fast DC) with integrated metering, payment, and communication protocols. Its primary purpose is to extend vehicle range beyond home charging by enabling opportunistic or destination-based energy replenishment in publicly accessible locations. DC Fast Chargers command the steepest capital investment but capture the strongest utilization rates at highway corridors and fleet depots where dwell-time minimization drives operator economics. Level 2 Chargers occupy the volume base across municipal facilities and retail centers where longer parking durations align with slower charge cycles. Wireless Chargers remain nascent in public deployment, constrained by infrastructure retrofit costs and alignment tolerances that limit scaling beyond premium pilot sites.
The US Federal Highway Administration, the European Union through its Alternative Fuels Infrastructure Regulation, and China's Ministry of Industry and Information Technology collectively shape product certification, interoperability mandates, and subsidy eligibility that determine market access. The EU's AFIR binding targets for corridor coverage and China's GB/T standard evolution toward ChaoJi high-power compatibility are forcing equipment redesign cycles and testing investments. Stakeholders must monitor which connector standards achieve regulatory default status in major economies, as this choice locks in hardware procurement commitments across decade-long infrastructure amortization schedules.
Market Dynamics
The US Inflation Reduction Act is compressing capital deployment timelines for public charging infrastructure, forcing fleet operators and retail landlords to accelerate site preparation and grid interconnection schedules ahead of subsidy windows closing.
Growth Catalysts
- Alternative Fuels Infrastructure Regulation:The EU's binding corridor coverage targets mandate minimum fast-charging intervals along trans-European transport networks, compelling highway operators to expand DC fast charger installations.
- Fleet electrification commitments:Logistics operators across North America are converting diesel truck depots to electric, creating concentrated demand for high-power charging hubs at distribution centers.
- ChaoJi standard evolution:China's GB/T compatibility migration toward the ChaoJi high-power connector is accelerating equipment refresh cycles and opening procurement windows for next-generation hardware.
Market Restraints
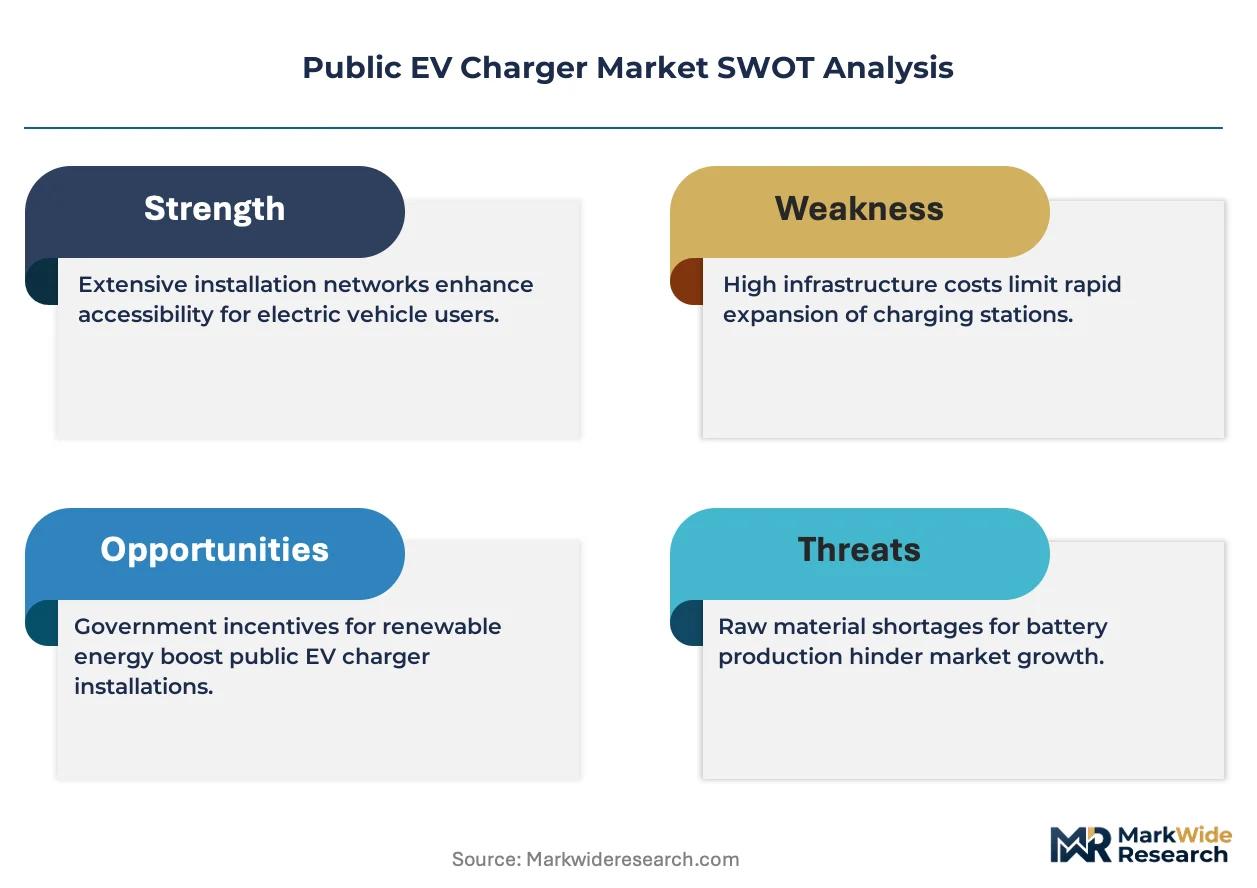
- Copper and silicon carbide cost volatility:Power electronics and cable assemblies constitute 35-40% of DC fast charger bill-of-materials, exposing manufacturers to commodity price swings that compress hardware margins.
- Transformer lead times:Grid interconnection equipment from concentrated North American and European suppliers now extends 18-24 months, delaying site commissioning regardless of charger availability.
- Site access fragmentation:Prime highway and urban corridor real estate is controlled by fragmented retail landlords and municipal authorities, complicating network density strategies for charging operators.
Strategic Opportunities
- India's PLI scheme for auto and auto components:Production-linked incentives for domestic EV manufacturing are creating latent demand for public charging infrastructure in a market with minimal current penetration.
- Vehicle-to-grid integration:Bidirectional charging protocols are converging with stationary battery management systems, enabling charging operators to stack revenue streams through grid services.
- Curbside residential charging:Streetlight-integrated Level 2 units are emerging as a channel innovation for urban dwellers without garage access, unlocking dense metropolitan deployment.
Industry Challenges
- Electrical contractor specialization gaps:High-voltage DC installation and commissioning requires certified technicians that remain scarce relative to deployment targets, constraining field crew scaling.
- OCPP certification timelines:Open Charge Point Protocol interoperability testing with multiple network software providers extends product launch cycles by 4-6 months for hardware manufacturers.
- Legacy payment system integration:Retail site hosts demand compatibility with existing point-of-sale and loyalty platforms, adding software complexity to charger deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public EV Charger Market |
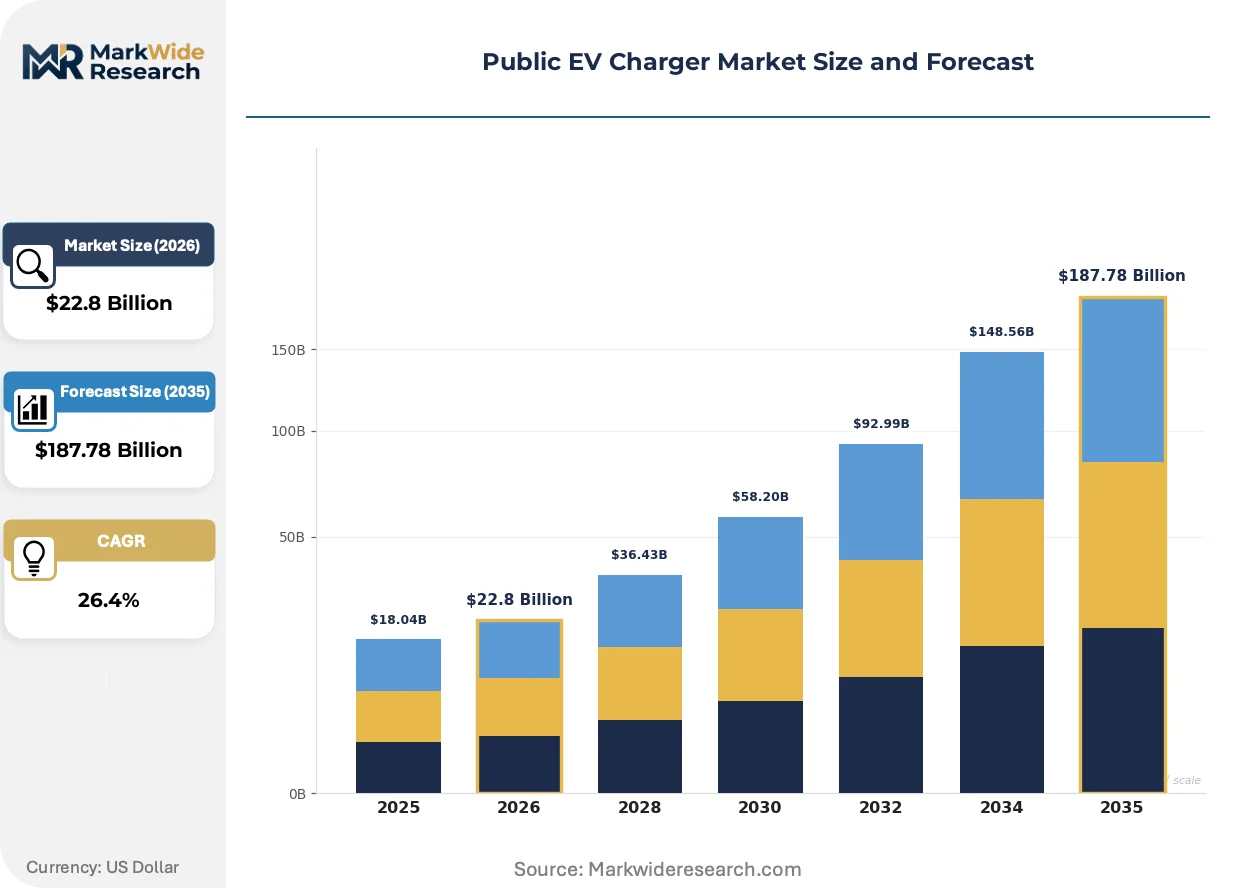
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $187.78 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers, Ultra-Fast Chargers Installation Type: Pole-Mounted, Wall-Mounted, Pedestal, Canopy, Streetlamp Integrated Application: Public Parking Lots, Commercial Complexes, Fleet Parking, Municipal Facilities, Retail Centers End User: Local Governments, Commercial Operators, Transportation Hubs, Hospitality Sector, Charge Point Operators |
| Companies Covered | ChargePoint, Tesla, ABB, EVgo, EVBox, Wallbox, Eaton, TELD New Energy, Star Charge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public EV Charger Market Trends and Innovations
Hardware modularity and software-defined power management are converging to reshape how charging networks scale capacity and optimize utilization across heterogeneous site constraints.
Silicon carbide power electronics are consolidating into the mainstream of DC fast charger designs, replacing traditional silicon IGBTs in 150-350 kW systems. Tier 1 suppliers and captive OEM charging divisions are adopting these modules for new platform releases. This transition is consolidating manufacturing scale around wide-bandgap semiconductor foundries and compressing thermal management system footprints.
The EU's Alternative Fuels Infrastructure Regulation entered force with binding power output targets per corridor and interoperability mandates. Member states must deploy charging pools at 60 km maximum intervals on core networks by 2025. Equipment manufacturers are responding with pre-certified hardware platforms that streamline national approval processes across Germany, France, and the Netherlands.
Subscription-based charging access is displacing per-kWh transactional pricing among fleet operators with predictable route patterns. Logistics providers are negotiating flat-rate network access agreements that bundle energy, maintenance, and software services. This shift is most visible in California and Germany where fleet electrification penetration exceeds retail charging growth rates.
Public EV Charger Market Segmentation
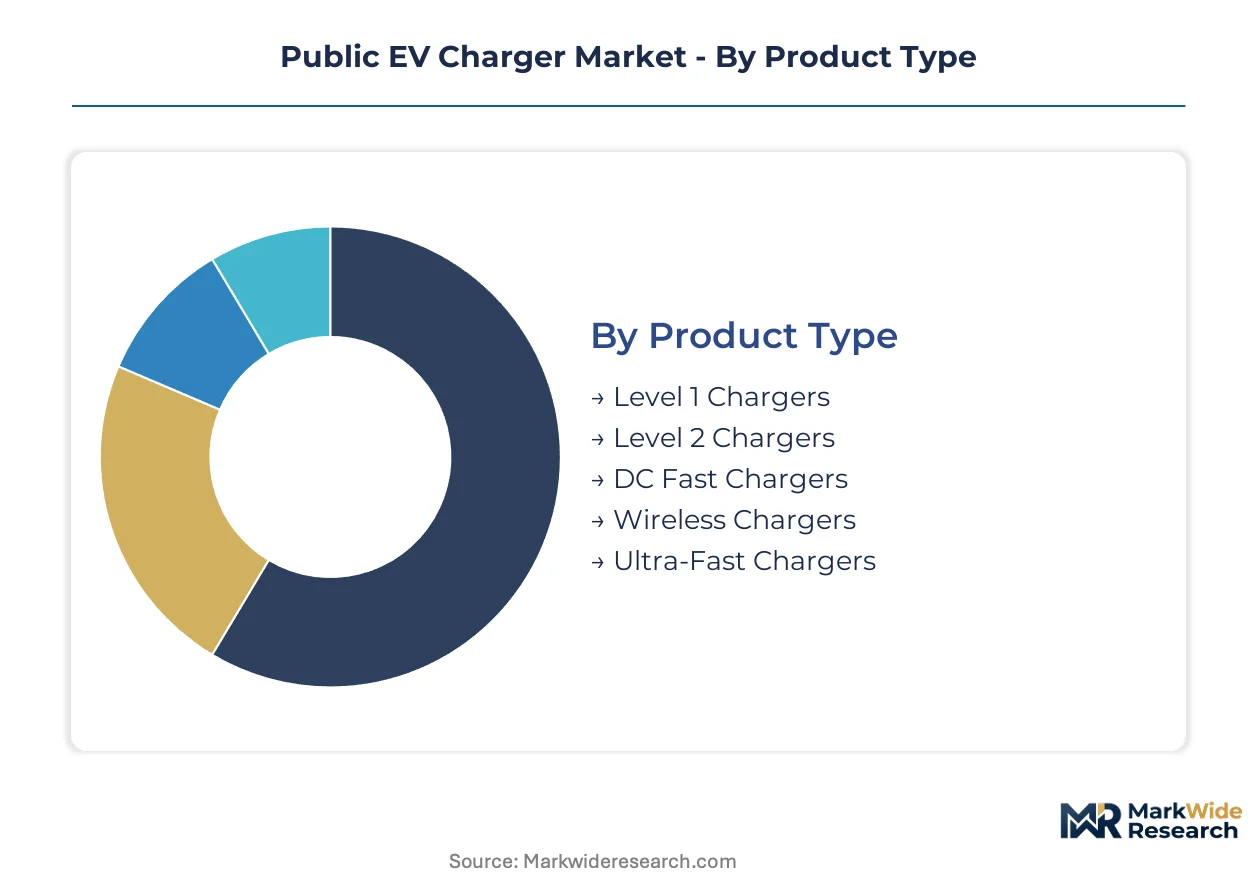
Segmentation in the Public EV Charger Market reveals how capital allocation priorities diverge across power levels, site configurations, and operator business models. Procurement decisions hinge on dwell-time economics, grid capacity constraints, and subsidy eligibility windows that vary by installation type and end-user category.
Product Type:
Power output requirements drive equipment selection, with fleet operators and highway corridor developers prioritizing speed over unit cost while municipal buyers optimize for deployment density.
- DC Fast Chargers:Deliver 50-350 kW through direct current conversion, enabling 10-80% battery replenishment in 20-40 minutes for passenger vehicles. Fleet depots in California and Texas are concentrating procurement here as diesel conversion timelines compress under IRA subsidy deadlines. Transformer lead times of 18-24 months constrain site activation regardless of charger availability.
- Level 2 Chargers:Supply 3.7-22 kW alternating current through onboard vehicle rectifiers, requiring 4-8 hours for full charges. Retail centers and municipal facilities across Germany and the Netherlands dominate volume demand, where longer parking durations align with slower cycles and lower capital intensity per port.
- Level 1 Chargers:Standard 120V residential-grade units repurposed for workplace and long-dwell public sites with minimal infrastructure requirements.
- Wireless Chargers:Inductive pad systems transferring power across air gaps, currently deployed at premium pilot sites in Oslo and Shenzhen due to alignment tolerance constraints.
- Ultra-Fast Chargers:350+ kW liquid-cooled cable systems targeting commercial truck electrification along European TEN-T corridors.
Volume sits with Level 2 Chargers; growth tilts toward DC Fast Chargers.
Installation Type:
Site constraints and right-of-way access determine mounting configurations, with urban density pressures favoring vertical integration into existing street infrastructure over ground-mounted pedestal deployments.
- Pole-Mounted:Attach to utility poles or dedicated columns, minimizing footprint in constrained sidewalk corridors. Berlin and Amsterdam have standardized these units for curbside residential charging where garage access is absent.
- Pedestal:Freestanding ground units housing power electronics and cable management, dominating highway rest stop and retail parking lot configurations across the United States.
- Wall-Mounted:Bracket-fixed units for structured parking garages and building-integrated sites with existing wall infrastructure.
- Canopy:Solar-panel-topped structures combining generation and charging, deployed at corporate campuses in California under net-metering arrangements.
- Streetlamp Integrated:Retrofit adapters converting existing luminaire infrastructure, emerging as a channel innovation for dense metropolitan deployment in London and Paris.
Pedestal units capture the revenue base; pole-mounted configurations are climbing the fastest as cities prioritize sidewalk preservation.
Application:
Dwell-time patterns and vehicle turnover rates segment demand, with applications enabling 4+ hour parking attracting lower-power equipment and highway-adjacent sites commanding premium fast-charging infrastructure.
- Fleet Parking:Dedicated depots for logistics and transit operators with predictable overnight dwell windows. Distribution centers in the US Midwest and Rhine-Ruhr corridor are converting diesel yards to 150-350 kW hub configurations under electrification mandates.
- Public Parking Lots:Mixed-use facilities serving transient vehicles with variable dwell durations, requiring flexible power allocation across Level 2 and DC fast options.
- Commercial Complexes:Office and mixed-use developments where charging amenities support tenant retention and LEED certification targets.
- Retail Centers:Big-box and shopping mall installations where charging duration aligns with average shopping trip intervals of 60-90 minutes.
- Municipal Facilities:Libraries, recreation centers, and government offices where public service mandates override utilization rate optimization.
Revenue concentrates in Fleet Parking; Public Parking Lots are expanding most quickly as subsidy programs democratize access.
End User:
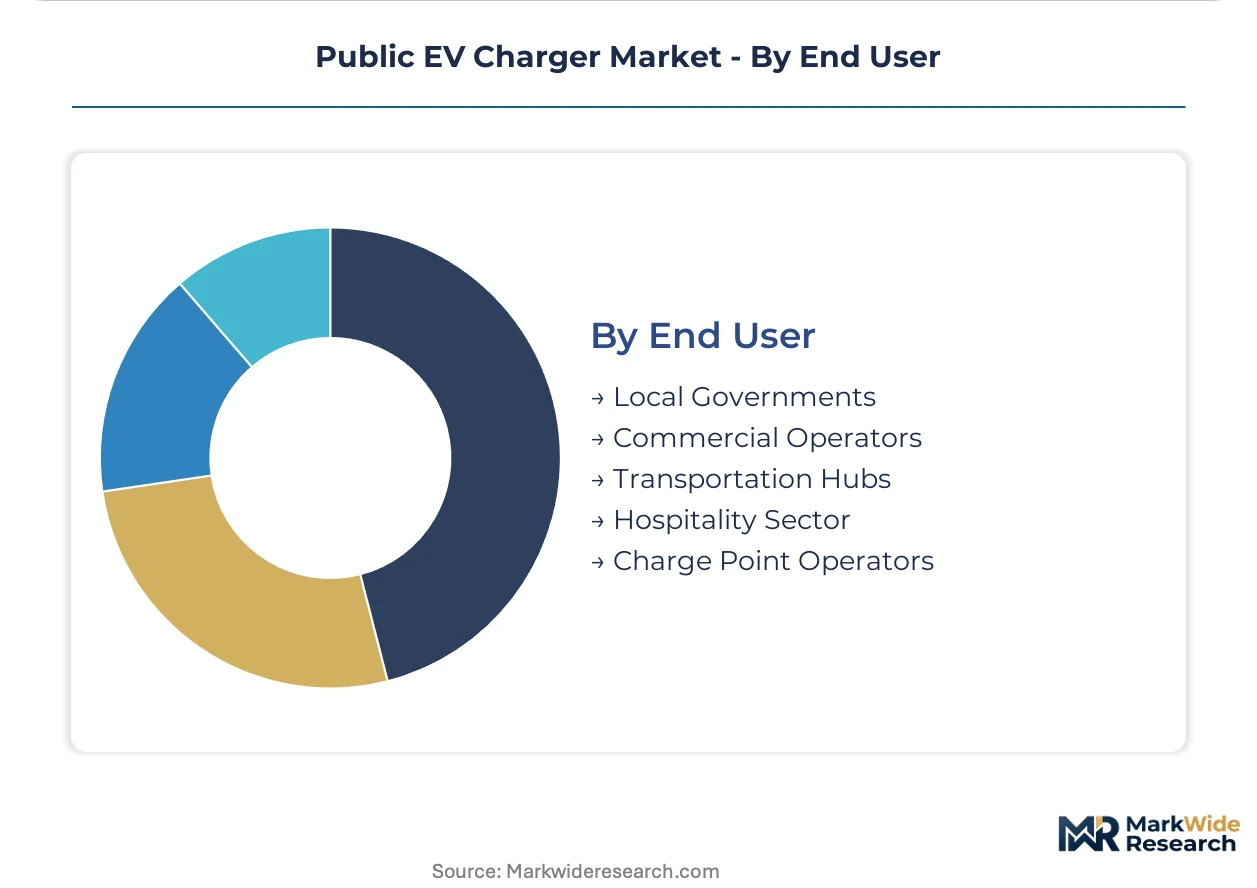
Procurement sophistication and capital access stratify the buyer base, with charge point operators and transportation hubs leveraging scale advantages unavailable to fragmented municipal purchasers.
- Charge Point Operators:Network-scale deployers aggregating sites across multiple geographies, negotiating bulk equipment procurement and software platform licensing. ChargePoint and Ionity exemplify this model across North America and Europe.
- Local Governments:City and county authorities deploying public infrastructure under climate action plans, constrained by procurement cycles and electrical contractor availability.
- Commercial Operators:Retail landlords and property managers adding charging as amenity infrastructure, often through tenant improvement allowances or third-party lease arrangements.
- Transportation Hubs:Airports, ports, and intermodal facilities serving rental fleets and passenger vehicles with high-turnover charging requirements.
- Hospitality Sector:Hotels and resorts targeting destination charging for leisure travelers with overnight dwell patterns.
Charge Point Operators command the installed base; Local Governments are gaining share fastest as federal and state subsidy windows accelerate municipal procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and Germany currently concentrate the heaviest demand for DC fast charging corridors along highway networks, while fleet operators across the United States are expanding charging commitments under federal subsidy programs.
United States
Fleet electrification commitments from logistics operators are converting diesel truck depots to high-power charging hubs. The Inflation Reduction Act subsidizes station deployment, compressing capital deployment timelines for public charging infrastructure. Distribution centers in California and Texas are concentrating procurement of 150-350 kW systems under IRA subsidy deadlines.
Germany
Highway corridor coverage mandates under the EU's Alternative Fuels Infrastructure Regulation are compelling DC fast charger installations at 60 km maximum intervals. The KBA enforces CE marking and interoperability standards for equipment certification. The Rhine-Ruhr corridor is converting diesel yards to electric hub configurations as fleet electrification mandates tighten.
China
GB/T standard evolution toward ChaoJi high-power compatibility is accelerating equipment refresh cycles and opening procurement windows. The Ministry of Industry and Information Technology shapes product certification and subsidy eligibility that determines market access. Shenzhen and Shanghai are deploying next-generation hardware at scale along trans-provincial transport networks.
India
Production-linked incentives for domestic EV manufacturing under the PLI scheme are creating latent demand for public charging infrastructure. The Central Electricity Authority oversees grid interconnection standards for high-voltage installations. Maharashtra and Gujarat are emerging as early deployment clusters for municipal and fleet charging pilots.
Netherlands
Retail centers and municipal facilities dominate volume demand for Level 2 chargers where longer parking durations align with slower cycles. The national regulator enforces AFIR-aligned corridor coverage targets on trans-European networks passing through Dutch territory. Amsterdam has standardized pole-mounted units for curbside residential charging where garage access is absent.
Public EV Charger Market Competitive Landscape
United States producers anchor one tier; European specialists hold equipment supply positions; Chinese manufacturers capture domestic volume deployment. The vendor base spans network-scale operators, captive OEM charging divisions, and industrial electrical equipment conglomerates. Three archetypes dominate: software-integrated network platforms, high-power modular system suppliers, and utility-facing infrastructure providers. Consolidation through M&A and strategic partnerships for corridor access are the dominant competitive moves reshaping positioning.
Within the network-platform tier, ChargePoint and EVgo represent software-integrated deployment models across North American highway and urban corridors. ABB anchors European fast-charging supply with high-power modular systems. Tesla occupies a distinct position through proprietary connector infrastructure and recent standardization moves toward broader network access.
| Leading Market Players |
|---|
| ChargePoint |
| Tesla |
| ABB |
| EVgo |
| EVBox |
| Wallbox |
| Eaton |
| TELD New Energy |
| Star Charge |
| Others |
Pricing and Supply Chain Analysis
Certified high-voltage electrical technicians concentrated in Germany and California command wage premiums that widen pricing spreads between premium-tier DC fast charger deployments and economy-tier Level 2 municipal installations. Labor-cost differentials across installation geographies force equipment manufacturers to tier service bundling, separating turnkey commissioning packages from hardware-only transactions.
Pricing Analysis
Volume concentrates in Level 2 chargers while margins cluster with DC fast systems. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European corridor hardware from UL-certified US fleet depot units and uncertified emerging-market equipment. Price differentiation hinges on silicon carbide power module grades and OCPP certification completeness. Cost compression in standard-tier hardware is intensifying because copper cable assembly volatility feeds directly into bill-of-materials exposure. Fleet operators show least price sensitivity due to IRA subsidy absorption, while municipal purchasers in India and Southeast Asia exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from ChargePoint and ABB now mandate qualified secondary suppliers for silicon carbide MOSFETs and liquid-cooled cable assemblies. Geographic supply concentration centers on China for GB/T connector hardware, Germany for high-voltage transformer components, and South Korea for wide-bandgap semiconductor foundry capacity. Raw material dependencies rest on copper cathodes, silicon carbide substrates, and rare-earth magnetic materials for power conversion. Single-source vulnerability persists at the 350 kW liquid-cooled cable tier where qualified vendors remain limited. Distribution runs through captive OEM service arms for fleet accounts and electrical contractor networks for municipal and retail deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The public EV charger market is accelerating into a vertical-integration race as players pursue captive silicon carbide foundry capacity to secure power electronics supply and compress thermal management costs.
For Market Incumbents: Anticipate transformer lead time bottlenecks by securing grid interconnection equipment commitments 18-24 months ahead of site commissioning schedules. Incumbents should anchor backward integration into wide-bandgap semiconductor supply through joint development agreements with foundry operators, defending against emerging Chinese manufacturers capturing ChaoJi-standard procurement windows. For New Entrants and Emerging Players: Software-defined power management platforms offer the lowest capital barrier for network-scale entry. New entrants should prioritize India's PLI-subsidized manufacturing corridors where domestic content requirements create procurement preferences for local assembly. Curbside residential charging through streetlamp retrofit adapters presents the most penetrable white-space segment in dense European and North American metropolitan cores. For Investors and Strategic Acquirers: Re-rating potential sits with charge point operators achieving software-integrated network density above 10,000 active ports given subscription revenue stabilization and grid services monetization. Acquisition targets should display OCPP 2.0.1 certification completeness and established utility interconnection relationships. The signal to watch as inflection indicator is bidirectional charging protocol adoption rates among fleet operator RFPs.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures power electronics supply for 150-350 kW systems against commodity volatility. |
| OCPP 2.0.1 Certification Investment | Unlocks network interoperability mandates under EU AFIR and US FHWA guidance. |
| Curbside Residential Channel Development | Captures garage-less urban dwellers through streetlamp-integrated Level 2 deployment. |
| Vehicle-to-Grid Protocol Integration | Enables revenue stacking through frequency regulation and peak shaving services. |
| Transformer Pre-Positioning Agreement | Mitigates 18-24 month grid interconnection delays constraining site activation. |
Research Methodology
Document review covered equipment manufacturer technical specifications, national regulatory filings with FHWA and MIIT, and customs trade data for power electronics imports, complemented by interviews with charge point operator procurement directors, electrical contractor field supervisors, utility interconnection planners, and fleet electrification managers. Secondary validation drew from IRA subsidy disbursement records, EU AFIR implementation progress reports, and IEA EV charging infrastructure databases. Bottom-up unit deployment tracking and top-down market sizing triangulated volume estimates.
Installed base projections and revenue forecasts across the modeling period reflect segment-specific adoption curves for DC fast, Level 2, and emerging wireless configurations. The analytical framework modeled power output tiers, installation type constraints, end-user procurement sophistication, and regional subsidy eligibility windows. CAGRs were derived from logistic diffusion curves fitted to fleet electrification commitment timelines and corridor coverage mandate deadlines. Forecast inputs incorporated silicon carbide cost decline trajectories and transformer manufacturing capacity expansion announcements.
The model holds under stable copper pricing and subsidy program continuity; deviation in wide-bandgap semiconductor supply constraints or IRA funding authorization lapses would shift deployment timelines materially. Deviation in GB/T-to-ChaoJi standard migration pace would alter equipment refresh cycle assumptions and procurement window timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
EV DC Chargers Market