
 Global EV Charging Piles Market | 2026-2036
Global EV Charging Piles Market Size, Share, and Industry Trends Forecast 2026-2036
Global EV Charging Piles Market Analysis
Commercial fleet charging is consolidating as the fastest-growing end-use vertical, displacing early residential dominance. ABB leverages its grid integration expertise to anchor large-scale depot projects across European logistics hubs. Tesla sustains technology leadership through proprietary connector ecosystems and supercharger network density. Xuji Group dominates domestic Chinese supply chains with cost-optimized AC pile manufacturing for state-grid tenders.
EV charging piles are electromechanical systems that convert grid electricity to vehicle-compatible DC power, with DC fast charging piles typically delivering 50 kW to 350 kW through liquid-cooled cable assemblies and power conversion modules. Their primary purpose is to replenish battery electric vehicle energy stores at rates calibrated to dwell time constraints and grid capacity. DC charging piles command premium margin pools due to semiconductor content and thermal management complexity, while AC charging piles retain volume leadership in workplace and multi-unit residential deployments where overnight dwell times accommodate slower replenishment cycles. Wireless charging piles remain nascent but attract R&D investment from premium automotive OEMs seeking automated fleet solutions.
The US Department of Transportation, the European Commission through its Alternative Fuels Infrastructure Regulation, and China's National Development and Reform Commission collectively shape deployment mandates, subsidy eligibility, and interoperability standards that determine market access and product certification pathways. These frameworks increasingly tie funding to open-network protocols and domestic content requirements, forcing equipment suppliers to navigate divergent compliance architectures. Stakeholders must monitor evolving grid connection codes and carbon-intensity thresholds that will determine which charging technologies qualify for public procurement and fleet decarbonization contracts.
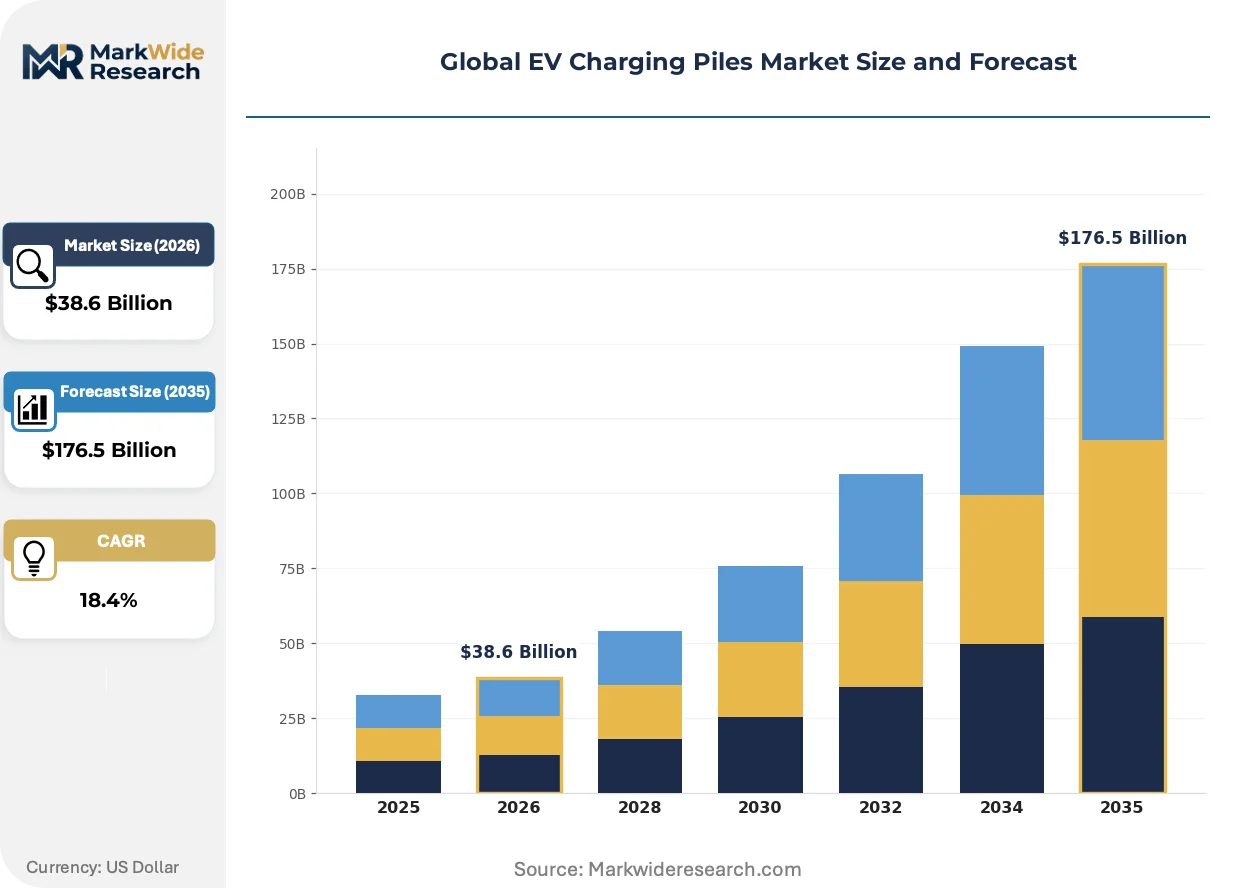
Market Dynamics
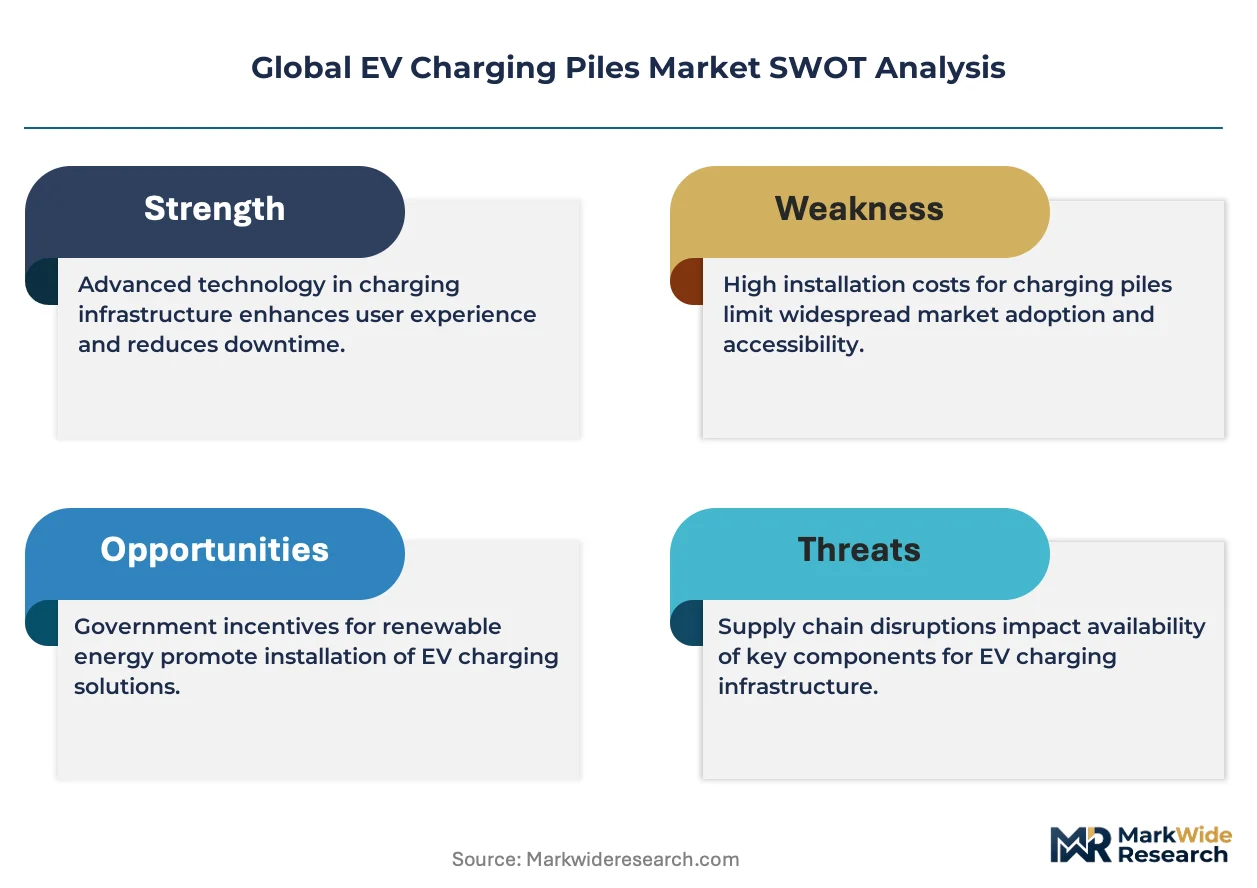
Grid interconnection queues stretching 3-5 years across major economies are forcing fleet operators to co-locate charging infrastructure with on-site generation, fundamentally restructuring deployment economics and site selection criteria for depot-scale projects.
Growth Catalysts
- Alternative Fuels Infrastructure Regulation:The European Commission's binding targets mandate minimum charging capacity per registered vehicle, compelling highway corridor buildouts and urban node densification.
- Commercial fleet electrification:Last-mile delivery operators are consolidating charging demand at logistics hubs, creating concentrated procurement pools that justify high-capacity DC hardware investments.
- Silicon carbide semiconductors:Wider bandgap devices are cutting power conversion losses by 30-50% in 350 kW+ piles, enabling faster charging without proportional thermal management cost increases.
Market Restraints
- Copper and rare-earth magnet costs:Liquid-cooled cable assemblies and permanent-magnet motors in power modules face input price volatility that compresses margin pools for mid-tier manufacturers.
- Transformer lead times:North American utility equipment backlogs extending 18-24 months are delaying commercial depot energization regardless of pile installation readiness.
- Vehicle-to-grid protocol fragmentation:Competing standards (ISO 15118-2, -20, CHAdeMO 3.0) create interoperability dead zones that strand infrastructure investment.
Strategic Opportunities
- India's FAME III subsidy framework:The expanded scheme targets 10,000 charging stations across 100 cities, opening white space for AC pile suppliers with localized manufacturing.
- Wireless inductive charging:Automated taxi and shuttle fleets are piloting 300 kW+ dynamic charging segments, converging road-embedded coils with vehicle-mounted receivers.
- Carbon-intensity-linked procurement:The EU Green Deal's embodied carbon thresholds for public infrastructure contracts favor suppliers with renewable-powered manufacturing and recyclable cable assemblies.
Industry Challenges
- High-voltage electrical technician scarcity:Installation and maintenance of 800V+ DC systems requires certified specialists whose training pipelines lag deployment targets by 2-3 years.
- Multi-protocol certification timelines:Simultaneous UL, CE, and GB standard compliance testing extends product launch cycles 8-14 months beyond hardware readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EV Charging Piles Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $176.5 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Charging Piles, DC Charging Piles, Wireless Charging Piles, Fast Charging Piles, Ultra-Fast Charging Piles Charging Mode: Plug-in Charging, Inductive Charging, Battery Swapping, Solar-Powered Charging, Mobile Charging Units Application: Private Vehicles, Commercial Fleets, Public Transportation, Shared Mobility, Logistics Vehicles End User: Vehicle Fleet Operators, Charging Infrastructure Providers, Workplace Charging, Hospitality Venues, Multi-Unit Residences |
| Companies Covered | Tesla, ABB, ChargePoint, Xuji Group, EVBox, Eaton, Schneider Electric, BYD, TELD New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EV Charging Piles Market Emerging Trajectories
Hardware architectures are fragmenting between integrated turnkey systems and componentized subsystems, enabling new entrant strategies that bypass legacy vertical manufacturing advantages.
Power conversion modules with discrete silicon carbide MOSFET packages are modularizing previously monolithic rectifier designs. Fleet operators in Germany and the Netherlands are adopting these swappable units to extend hardware lifecycles without full pile replacement. This modularity is compressing capital recovery timelines by enabling capacity upgrades through field-replaceable subassemblies rather than wholesale infrastructure renewal.
China's MIIT is tightening GB/T standard compliance for electromagnetic compatibility and grid harmonic limits, disqualifying earlier-generation imports from state-grid tenders. Domestic manufacturers with captive testing facilities are accelerating certification cycles. Export-oriented suppliers are responding with dual-sku strategies that isolate China-specific hardware variants from global product lines.
Energy-as-a-service contracts are displacing capital purchase models for depot operators seeking to offload utilization risk. Third-party financiers are aggregating charging assets into revenue pools, selling guaranteed uptime and per-kWh availability rather than equipment. This shift is most visible in California and the United Kingdom, where fleet decarbonization mandates outstrip operator balance sheet capacity for infrastructure ownership.
Global EV Charging Piles Market Segmentation
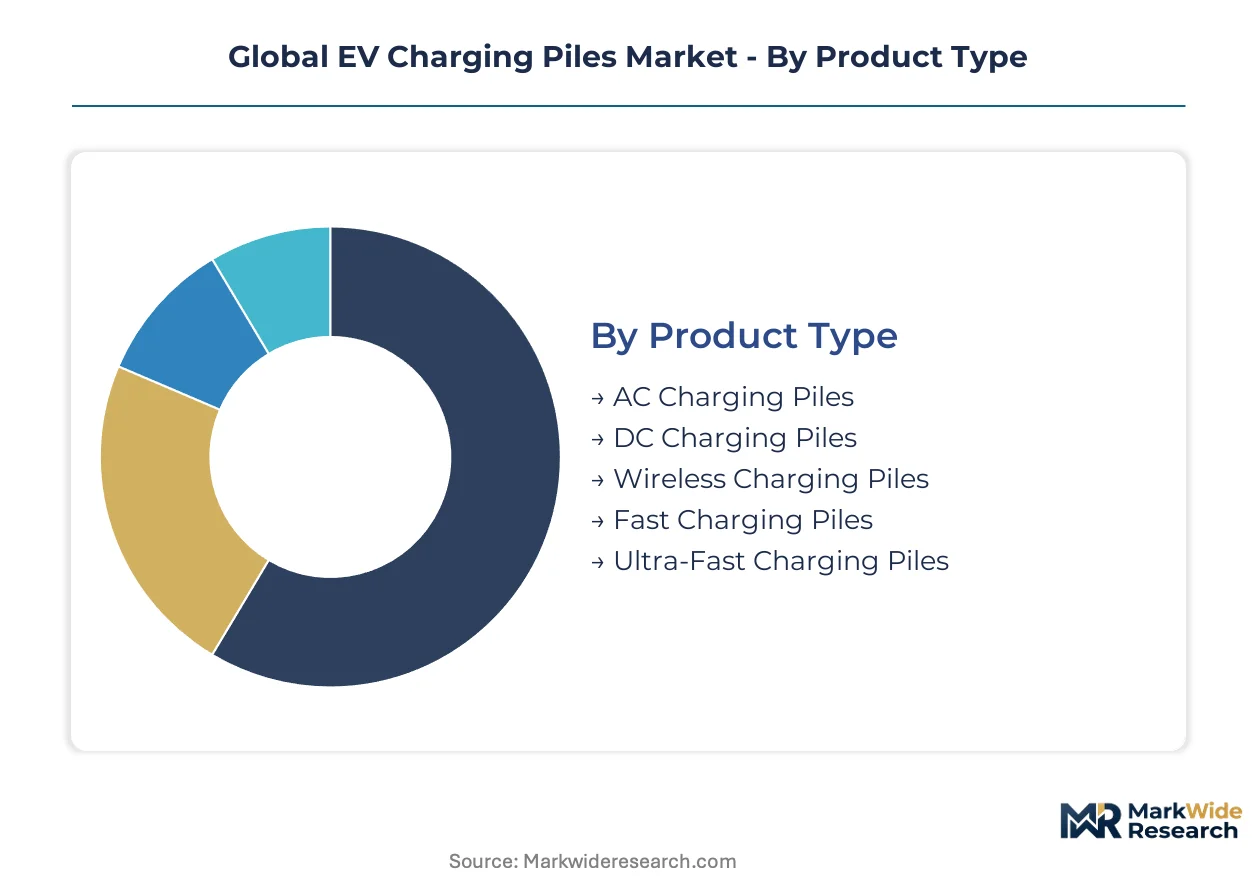
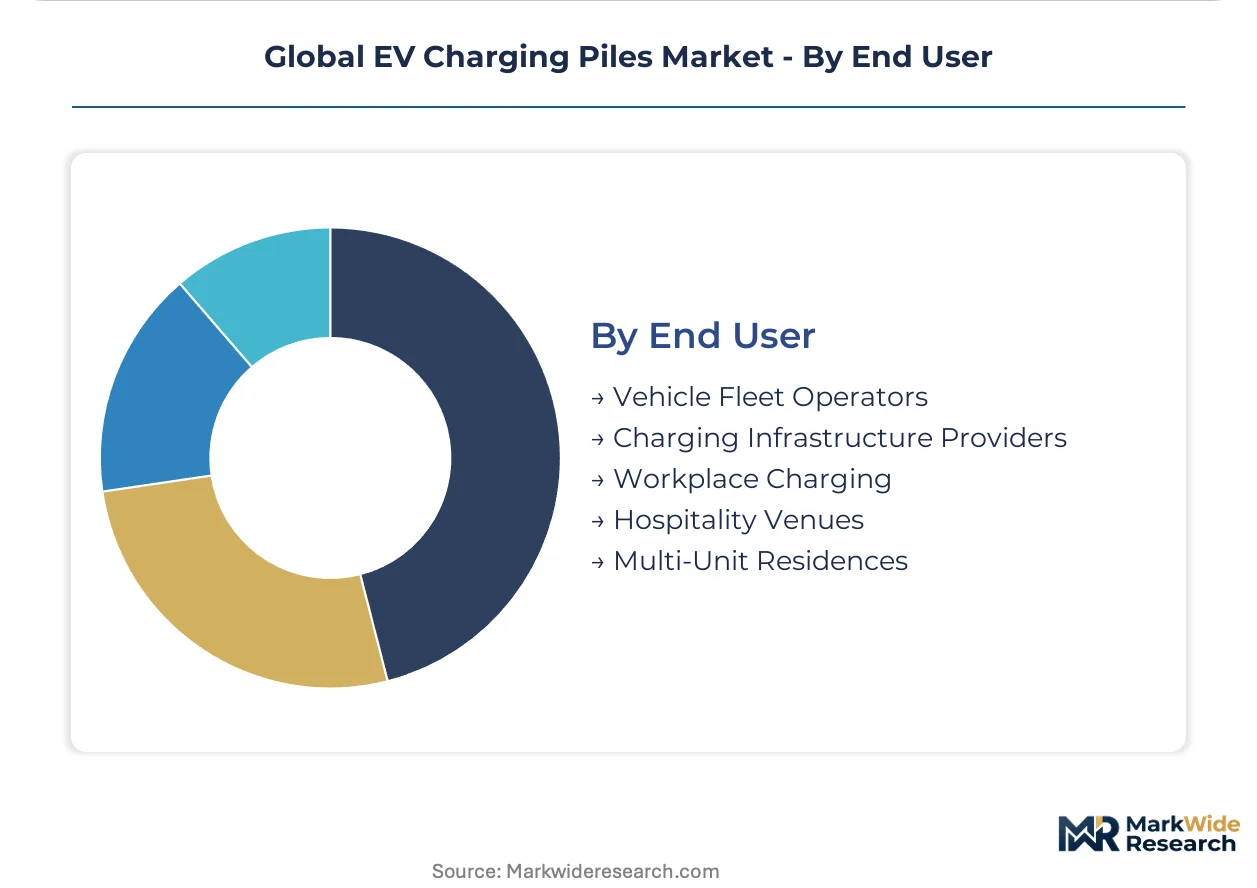
Charging pile procurement diverges sharply across user archetypes, with fleet operators prioritizing throughput density while residential and workplace buyers optimize for capital efficiency. Equipment specifications, power ratings, and service models fragment along these demand fault lines, creating distinct competitive arenas with divergent margin structures.
Product Type:
Buyers in this category separate by dwell time tolerance and power delivery requirements, with commercial operators accepting premium hardware costs for rapid turnaround while residential users absorb slower replenishment cycles.
- DC Charging Piles:These systems convert grid AC to vehicle-direct DC through integrated rectifier modules and liquid-cooled cable assemblies rated 50-350 kW. Fleet depots in Germany and the Netherlands concentrate procurement here, driven by electrification mandates for last-mile logistics vehicles with sub-one-hour turnaround requirements.
- AC Charging Piles:Lower-power units delivering 7-22 kW through onboard vehicle rectification dominate workplace and multi-unit residential installations where overnight dwell times accommodate extended charging windows. China's state-grid tenders favor cost-optimized variants with GB/T connector compatibility.
- Fast Charging Piles:Mid-tier DC systems bridging standard and ultra-fast categories serve highway corridor nodes and urban retail locations.
- Ultra-Fast Charging Piles:350 kW+ installations with silicon carbide power modules target premium passenger segments and heavy-duty commercial routes.
- Wireless Charging Piles:Inductive pad systems with vehicle-mounted receivers remain pilot-scale, attracting automated taxi fleet trials in California and Japan.
AC charging piles lead volumes today; DC charging piles are gaining share fastest.
Charging Mode:
Deployment economics hinge on grid connection availability and capital intensity, with hardwired infrastructure competing against mobile and renewable-coupled alternatives where utility interconnection queues stretch years.
- Plug-in Charging:Conductive cable-and-connector systems dominate installed base, with CCS, CHAdeMO, and GB/T protocols fragmenting connector standards across geographies. North American highway corridors and Chinese urban clusters drive concentrated demand.
- Battery Swapping:Automated exchange systems for standardized battery packs serve commercial taxi and logistics fleets in China, where NIO and state-backed operators have built station networks exceeding 2,000 sites.
- Inductive Charging:Road-embedded coil systems enable dynamic charging for shuttle and bus routes without vehicle stopping.
- Solar-Powered Charging:PV-coupled DC systems with battery buffering address grid-constrained sites in India and rural Australia.
- Mobile Charging Units:Trailer-mounted or van-integrated systems provide emergency and event-based charging where fixed infrastructure is uneconomical.
Plug-in charging dominates installed capacity; battery swapping is climbing the fastest.
Application:
Vehicle utilization patterns determine power throughput requirements, with high-rotation commercial assets justifying premium hardware investments that private owners reject.
- Commercial Fleets:Depot-based charging for delivery vans, trucks, and buses requires 150-350 kW DC systems with load management software to coordinate hundreds of simultaneous charging events. Amazon, DHL, and Deutsche Post procurement pools in Europe and North America concentrate demand here.
- Logistics Vehicles:Heavy-duty freight trucks with megawatt-class charging needs are driving 1 MW+ pilot installations along German autobahn corridors and California freight routes.
- Private Vehicles:Residential and destination charging for passenger cars favors lower-capital AC installations.
- Public Transportation:Bus depots and rail-adjacent nodes require overnight fleet replenishment with managed charging schedules.
- Shared Mobility:Ride-hail and car-share fleets demand rapid turnaround charging in dense urban zones.
Private vehicles anchor current installation volumes; commercial fleets show the steepest expansion trajectory.
End User:
Capital deployment models separate this category, with balance-sheet ownership competing against energy-as-a-service contracts that offload utilization risk to third-party financiers.
- Vehicle Fleet Operators:Logistics companies, transit agencies, and delivery services procure charging as core infrastructure, prioritizing guaranteed uptime and per-kWh availability over hardware ownership. California and United Kingdom fleet decarbonization mandates outstrip operator balance sheet capacity, accelerating third-party financing adoption.
- Charging Infrastructure Providers:Specialized operators like ChargePoint, IONITY, and state-grid affiliates build and monetize public networks through subscription and per-session revenue.
- Workplace Charging:Corporate campus installations serve employee vehicles with tiered pricing structures.
- Multi-Unit Residences:Condominium and apartment building installations require load-sharing systems to manage limited electrical capacity.
- Hospitality Venues:Hotels and retail locations deploy charging as amenity infrastructure to attract EV-owning customers.
Charging infrastructure providers lead deployment scale; vehicle fleet operators are expanding procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with streamlined certification pathways and concentrated subsidy pools, exploiting gaps between the EU's Alternative Fuels Infrastructure Regulation, China's GB/T standard enforcement, and India's FAME III localization requirements. This arbitrage is redrawing supply chain maps faster than demand itself is growing.
China
NEV mandate compliance deadlines and state-grid tender bundling are concentrating procurement in the Yangtze River Delta and Pearl River Delta clusters. MIIT's tightened GB/T electromagnetic compatibility standards are disqualifying earlier-generation imports from state-grid tenders. Xuji Group and domestic manufacturers with captive testing facilities in Shenzhen and Suzhou are accelerating certification cycles.
Germany
Last-mile logistics electrification mandates and autobahn corridor freight charging pilots are driving 150 kW to 1 MW depot installations. The KBA enforces type approval for grid connection codes under the EU Green Deal's embodied carbon thresholds. Industrial concentration in Bavaria and North Rhine-Westphalia hosts ABB's large-scale depot projects for Deutsche Post and DHL procurement pools.
United States
Commercial fleet decarbonization contracts and IRA tax credits are outpacing operator balance sheet capacity for infrastructure ownership. The Department of Transportation shapes deployment mandates and open-network protocol requirements. California's Central Valley and Texas logistics corridors concentrate Tesla supercharger density and third-party energy-as-a-service aggregators.
India
FAME III's expanded subsidy framework targets 10,000 charging stations across 100 cities, opening white space for AC pile suppliers with localized manufacturing. The CEA regulates grid interconnection standards for EV supply equipment. Maharashtra and Gujarat industrial zones are attracting domestic assembly investments to meet domestic content requirements.
Netherlands
Urban node densification requirements and highway corridor buildouts are compelling charging capacity minimums per registered vehicle. The national regulator enforces EU Alternative Fuels Infrastructure Regulation targets through municipal procurement. The Randstad logistics hub concentrates fleet operator demand for modular, swappable power conversion units.
Global EV Charging Piles Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated turnkey suppliers commanding depot-scale projects while componentized subsystem vendors penetrate cost-sensitive AC installations. The market structure tilts toward consolidation at the high-power DC tier and fragmentation in residential and workplace segments. Three archetypes dominate: grid-integration specialists leveraging utility relationships, connector-ecosystem owners capturing proprietary lock-in, and cost-optimized fabricators winning state-grid tenders. Competitive moves center on strategic partnerships with fleet operators and geographic expansion through dual-sku strategies that isolate China-specific variants from global product lines.
Within the premium-tier vector, Tesla and ABB exemplify divergent moats—Tesla through proprietary connector ecosystems and supercharger network density, ABB through grid integration expertise anchoring European logistics hub projects. ChargePoint occupies a position between these poles as a specialized infrastructure provider monetizing public networks through subscription revenue. Xuji Group sits within the cost-optimized tier, representing domestic Chinese supply chain dominance in state-grid AC pile tenders. These three archetypes—ecosystem owner, grid integrator, and tender-optimized fabricator—capture the strategic fault lines reshaping competitive positioning.
| Leading Market Players |
|---|
| Tesla |
| ABB |
| ChargePoint |
| Xuji Group |
| EVBox |
| Eaton |
| Schneider Electric |
| BYD |
| TELD New Energy |
| Others |
Supply Flow & Price Mechanics
Silicon carbide power module adoption is compressing thermal management costs while concentrating procurement leverage among tier-1 semiconductor suppliers in Germany and Japan. This technology transition simultaneously reshapes DC fast-charging economics and redraws component sourcing maps as fleet operators demand higher power density without proportional hardware cost increases.
Pricing Analysis
Distributor margins for DC charging piles compress as direct-to-fleet procurement pools consolidate demand around ABB, Tesla, and state-grid affiliates. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier (UL vs CE vs GB/T), volume scale, and after-sales service bundling. Cost compression in mid-tier AC piles is intensifying because China's MIIT tightened electromagnetic compatibility standards. Workplace charging buyers exhibit highest price sensitivity; commercial fleet operators prioritize guaranteed uptime over per-unit capital cost.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Rotterdam, and Dallas anchor hub-and-spoke patterns for power conversion modules and liquid-cooled cable assemblies. Manufacturing concentrates in China, Germany, and the United States for final assembly, while silicon carbide wafers draw from Japan and the United States. Copper and rare-earth magnet dependencies expose producers to commodity price volatility. Single-source vulnerability for 350 kW+ semiconductor packages threatens capacity expansion timelines. Distribution runs through state-grid tender platforms in China, OEM direct contracts in Europe, and energy-as-a-service aggregators in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Alternative Fuels Infrastructure Regulation compounds demand through binding charging capacity targets per registered vehicle, creating procurement visibility that extends hardware investment cycles.
For Market Incumbents: Cement grid-integration relationships with European logistics hubs before transformer lead times extend further. Defend against modular subsystem entrants by certifying swappable power conversion units under GB/T, UL, and CE simultaneously. Prioritize backward integration into silicon carbide packaging to secure semiconductor allocation. For New Entrants and Emerging Players: Direct-to-fleet SaaS platforms offer a white-space route around established hardware incumbents. Target India's FAME III subsidy window for AC pile tenders requiring localized manufacturing. Pursue componentized subsystem sales to European depot operators seeking field-upgradeable architectures without full pile replacement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier AC pile fabricators lacking DC fast-charging certification. Long-term viability hinges on regulatory compliance breadth across EU, US, and Chinese frameworks. Watch for GB/T standard enforcement tightening as the inflection signal for domestic Chinese supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Integration | Reduces power conversion losses by 30-50% in 350 kW+ piles without proportional thermal cost increases. |
| Dual-SKU Certification Strategy | Isolates China-specific GB/T variants from global product lines to accelerate state-grid tender compliance. |
| Energy-as-a-Service Contracting | Aggregates charging assets into revenue pools selling guaranteed uptime to California and UK fleet operators. |
| On-Site Generation Co-location | Restructures depot deployment economics where grid interconnection queues stretch 3-5 years across major economies. |
| Wireless Inductive Pilot Deployment | Targets automated taxi and shuttle fleets in California and Japan with 300 kW+ dynamic charging segments. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining fleet operator procurement directors, utility interconnection planners, charging infrastructure financiers, and power electronics engineers with secondary validation. Sources include EU Alternative Fuels Infrastructure Regulation filings, US Department of Transportation NEVI program disclosures, China MIIT GB/T standard updates, and IEA Global EV Outlook data. Bottom-up equipment shipment analysis triangulates against top-down fleet electrification mandate trajectories.
Granularity-level modeling disaggregates volume and value across product type (DC, AC, wireless), charging mode (plug-in, battery swapping, inductive), application (commercial fleet, logistics, private vehicle), and end user (fleet operator, infrastructure provider, workplace) throughout the forecast period. CAGRs derive from regression against fleet electrification deadlines and subsidy phase-out schedules. Key inputs include silicon carbide adoption curves and transformer lead time trajectories.
The model assumes a particular technology adoption path; alternative pathways for wireless inductive charging would alter the outlook if dynamic charging segments achieve commercial scale faster than projected. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and grid modernization investment rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market